
 Automotive Transceivers Market | 2026-2036
Automotive Transceivers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Transceivers Market Intelligence
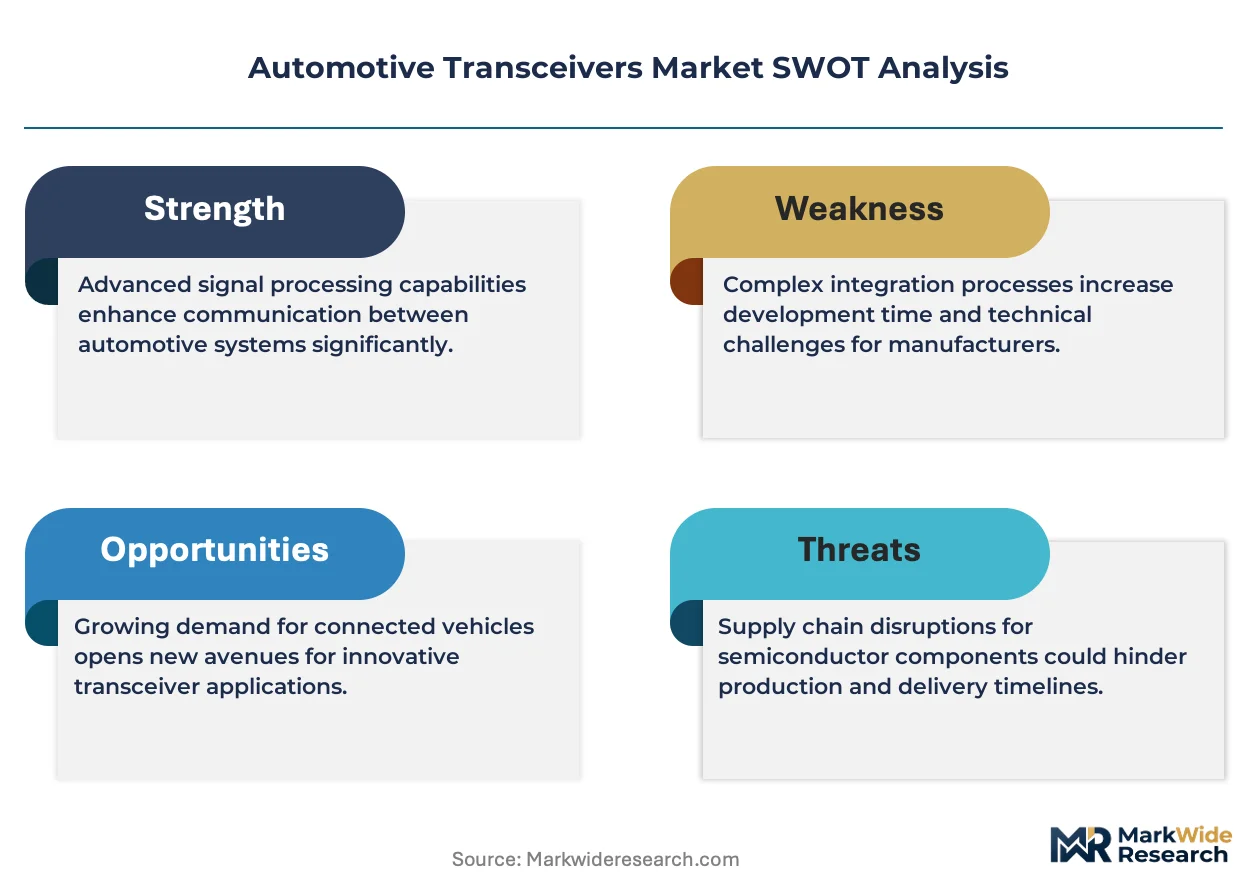
Silicon-on-insulator substrates is decoupling from traditional bulk silicon for high-frequency automotive transceivers, lowering power dissipation and enabling tighter node integration. NXP Semiconductors leverages its S32 automotive platform to dominate gateway applications across European and North American OEM programs. Infineon Technologies anchors its position through backward integration into gallium-nitride R&D for next-generation powertrain interfaces. Texas Instruments competes on manufacturing scale, sustaining cost leadership in LIN and CAN-FD portfolios through 300-millimeter fab utilization.
Automotive transceivers are mixed-signal integrated circuits that translate between protocol-specific physical layers and digital controllers, typically operating at bit rates from kilobits per second in LIN buses to multi-gigabit speeds in automotive Ethernet. Their primary purpose is ensuring reliable, real-time data exchange across distributed electronic control units under electromagnetic interference and temperature extremes. Ethernet transceivers for driver assistance systems represent the fastest-expanding revenue pool as camera and lidar data loads overwhelm legacy CAN bandwidth. CAN transceivers retain volume leadership in powertrain control and body electronics where cost sensitivity and proven fault tolerance still govern procurement decisions. MOST transceivers face structural decline as infotainment systems migrate to Ethernet-based audio-video bridging.
FCC Part 15 emissions rules in the United States constrain wireless transceiver architectures, while EU REACH and RoHS directives restrict hazardous substances in automotive semiconductor packaging. China's GB standards for vehicle networking, enforced by MIIT, mandate domestic protocol certifications that shape product roadmaps for foreign suppliers. ISO 26262 functional safety requirements from the functional safety working group elevate design complexity and qualification costs for safety-critical applications. Stakeholders must monitor how zonal E/E architecture consolidation shifts protocol mix and whether regional content rules fragment supply chain qualification pathways.
Market Dynamics
Zonal E/E architecture consolidation is compressing protocol diversity as automakers collapse distributed ECUs into domain controllers, forcing transceiver suppliers to prioritize multi-protocol integration over single-function optimization.
Growth Catalysts
- EU Green Deal vehicle emissions standards:Centralized computing mandates for powertrain electrification require high-speed data backbone upgrades, pulling Ethernet transceiver demand into production pipelines faster than legacy refresh cycles.
- Silicon-on-insulator substrates:SOI wafers enable sub-1-watt power dissipation at multi-gigabit speeds, unlocking node shrinkage for thermal-constrained engine-bay placements where bulk silicon fails qualification.
- China domestic EV production scaling:MIIT's local semiconductor sourcing policies redirect procurement toward regional foundries, creating captive demand pools for indigenous transceiver suppliers with GB-certified protocol stacks.
Market Restraints
- 300-millimeter fab concentration:Advanced automotive transceiver production concentrates in Taiwan and South Korea foundries, exposing supply continuity to geopolitical friction and water-intensive process vulnerability.
- ISO 26262 functional safety qualification:ASIL-D certification for gateway applications extends development timelines by 18-24 months and locks smaller competitors out of safety-critical revenue pools.
- Gallium-nitride powertrain interfaces:GaN's switching speed advantages threaten incumbent silicon transceiver sockets in high-voltage inverter communications, forcing defensive R&D allocation.
Strategic Opportunities
- Software-defined vehicle platforms:Over-the-air update architectures require persistent high-bandwidth links, expanding Ethernet transceiver attach rates beyond infotainment into chassis and braking domains previously served by CAN-FD.
- India automotive electronics PLI scheme:Production-linked incentives for domestic component manufacturing attract transceiver packaging and testing investments to serve ASEAN export markets with tariff-advantaged sourcing.
- Wireless transceiver integration:UWB and C-V2X modules for digital key and collision avoidance applications converge with baseband processors, opening discrete transceiver displacement risk for incumbents slow to adapt.
Industry Challenges
- EMC validation bottleneck:CISPR 25 radiated emissions testing for multi-gigabit automotive Ethernet requires anechoic chamber capacity that remains scarce relative to product launch cadence, stretching qualification queues.
- Legacy LIN bus coexistence:Door modules and seat controllers retain 19.2 kbps LIN infrastructure, forcing transceiver suppliers to maintain dual-protocol design teams while Ethernet engineering demands concentrate talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Transceivers Market |
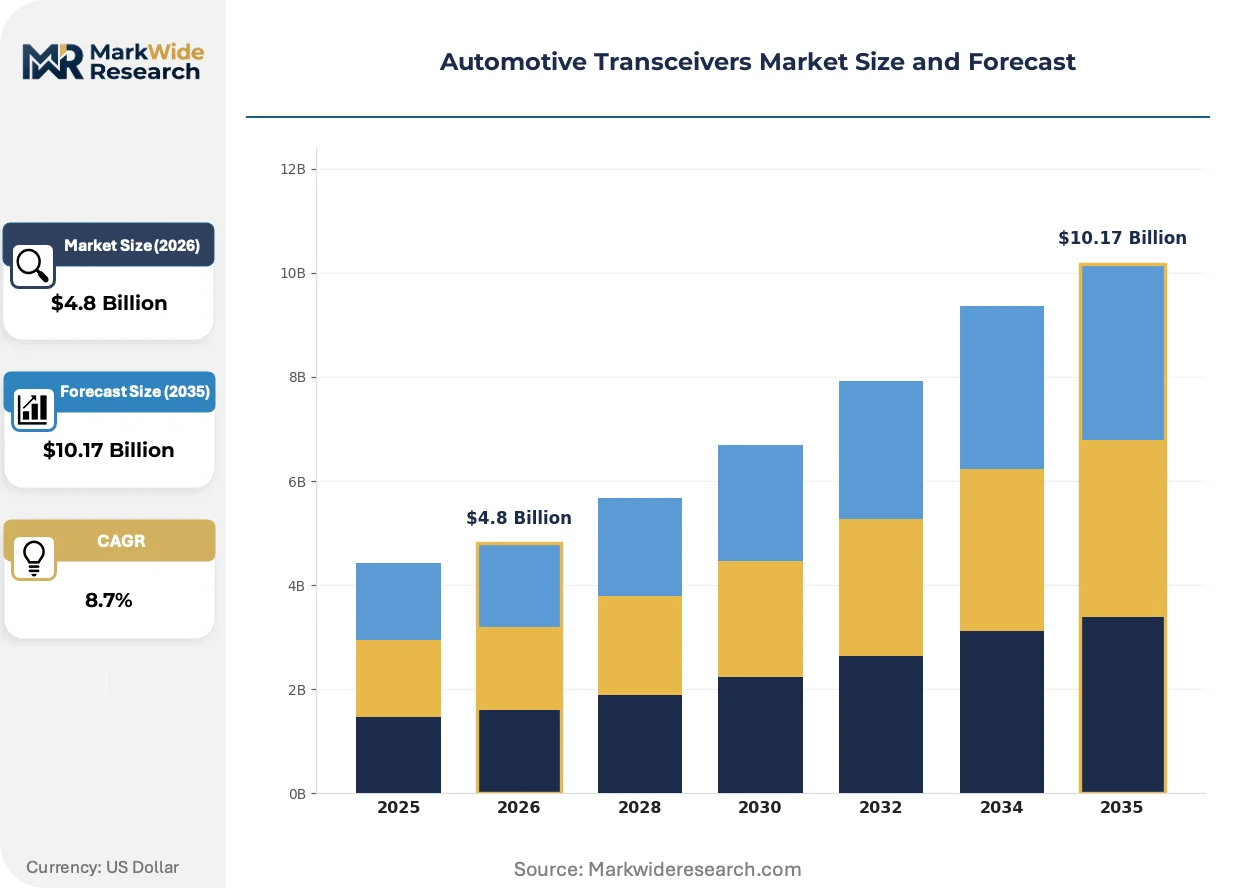
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAN Transceivers, LIN Transceivers, FlexRay Transceivers, MOST Transceivers, Ethernet Transceivers Technology: High-Speed CAN, Single-Wire CAN, BroadR-Reach, Optical, Wireless, Fiber Optic Application: Powertrain Control, Body Control, Infotainment Systems, Safety Systems, Telematics, Driver Assistance End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | STMicroelectronics, Broadcom, NXP Semiconductors, Analog Devices, Toshiba Corporation, Infineon Technologies, Microchip Technology, Renesas Electronics, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Transceivers Market Strategic Shifts & Innovations
Automotive networking is undergoing a protocol stack compression as zonal architectures collapse legacy bus hierarchies into unified Ethernet backbones, reshaping transceiver specifications toward software-configurable physical layers.
Multi-gigabit automotive Ethernet PHYs is converging with Time-Sensitive Networking standards to deliver deterministic latency for lidar fusion pipelines. Tier 1 suppliers are adopting 10BASE-T1S and 100BASE-T1 variants in parallel to cover cost-differentiated vehicle tiers. This convergence is compressing the traditional CAN-to-Ethernet upgrade timeline from two platform generations to one.
China's MIIT GB/T vehicle networking standards now mandate domestic electromagnetic compatibility certification for all imported transceiver modules. The regulation forces foreign suppliers to establish in-country test facilities or partner with local laboratories for pre-shipment validation. Premium EV platforms from domestic OEMs are the first to enforce GB/T compliance as a procurement gate.
Buyer concentration among platform-sharing OEM consortia is consolidating transceiver specification power. Volkswagen's SSP architecture and Hyundai's Integrated Modular Architecture are issuing unified PHY requirements across multiple brands, displacing the previous model where individual nameplates sourced independently. This pattern is most visible in Germany and South Korea where platform engineering centralizes at headquarters level.
Automotive Transceivers Market Segmentation
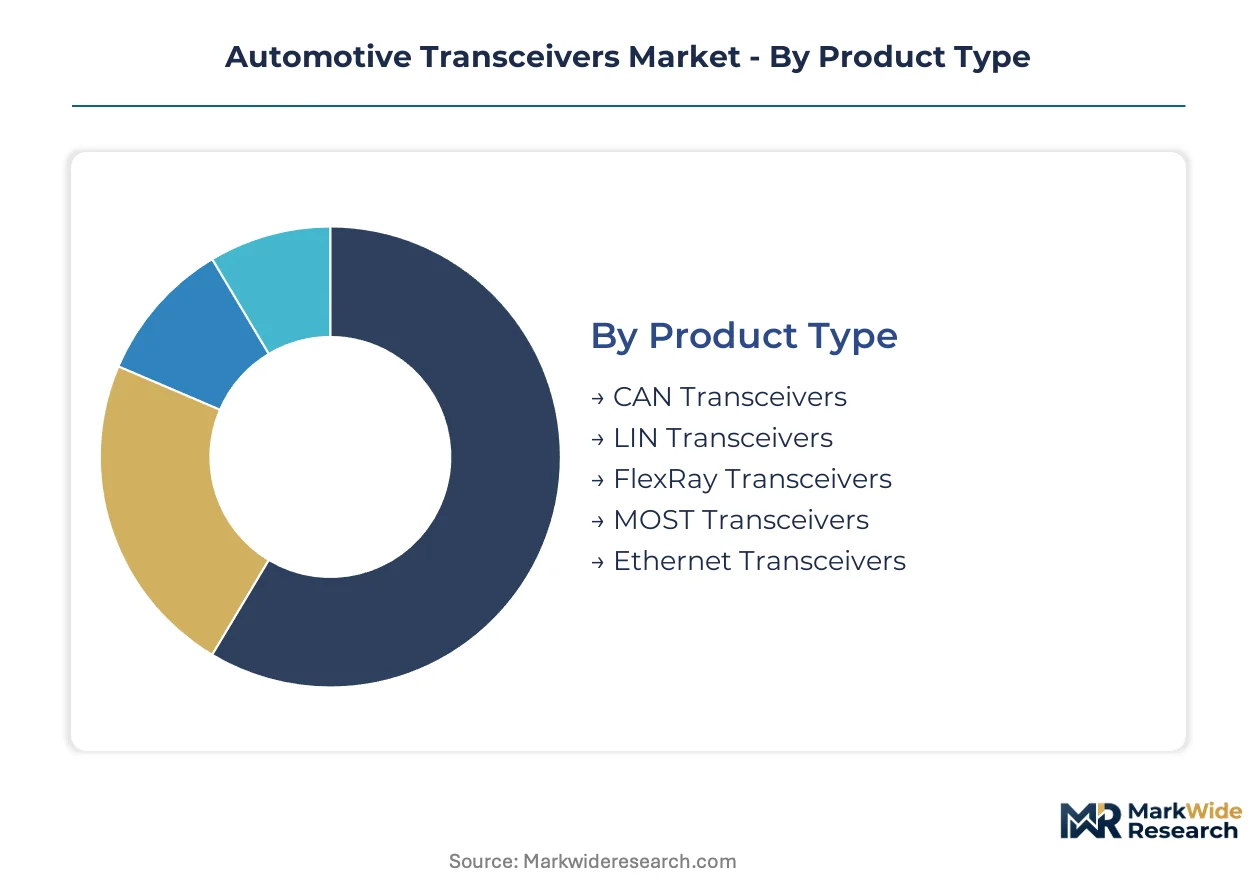
Automotive transceiver segmentation reveals how protocol specialization aligns with vehicle domain requirements. Each axis—product, technology, application, and buyer type—reflects distinct procurement patterns and qualification barriers.
Product Type:
Protocol specifications differentiate transceiver portfolios across bandwidth, fault tolerance, and electromagnetic resilience.
- Ethernet Transceivers:Multi-gigabit PHYs handle camera and lidar data floods in zonal architectures. Demand concentrates in premium EV platforms from Tesla, BYD, and Volkswagen where centralized computing mandates backbone upgrades.
- CAN Transceivers:Controller Area Network PHYs remain the volume workhorse for powertrain and body electronics. Procurement prioritizes cost efficiency and ISO 26262 ASIL-B certification for engine control modules.
- LIN Transceivers:Low-cost single-wire interfaces serve door modules and seat controllers at 19.2 kbps.
- FlexRay Transceivers:Deterministic high-speed buses persist in chassis control where hard real-time constraints outweigh Ethernet migration costs.
- MOST Transceivers:Media Oriented Systems Transport faces displacement as infotainment shifts to audio-video bridging over Ethernet.
Mature deployment sits with CAN Transceivers. Newer deployment is concentrated in Ethernet Transceivers.
Technology:
Physical layer implementations span copper, optical, and wireless media with distinct cost-versus-performance tradeoffs.
- BroadR-Reach:Single-pair Ethernet PHYs deliver 100 Mbps over unshielded twisted pair, slashing cable weight and harness complexity. Adoption clusters in mass-market EVs where wiring cost reduction directly impacts range.
- High-Speed CAN:Differential signaling at 500 kbps to 1 Mbps dominates legacy powertrain networks. Demand remains anchored in internal combustion engine platforms across emerging markets where refresh cycles lag electrification.
- Single-Wire CAN:Reduced-pin-count variants serve cost-constrained body electronics in entry vehicle tiers.
- Optical:Fiber-based transceivers isolate high-voltage powertrain environments from electromagnetic interference.
- Wireless:UWB and C-V2X modules enable digital key and vehicle-to-infrastructure communication.
- Fiber Optic:Glass and polymer fibers support infotainment backbones where galvanic isolation matters.
Volume concentration favors High-Speed CAN. Steepest expansion trajectory belongs to BroadR-Reach.
Application:
Vehicle domains impose divergent latency, bandwidth, and safety integrity requirements on transceiver selection.
- Driver Assistance:Camera fusion and lidar pipelines demand deterministic multi-gigabit links. Procurement concentrates in Level 2+ ADAS platforms where sensor data throughput governs system architecture.
- Powertrain Control:Engine management and battery systems rely on CAN-FD and FlexRay for real-time actuator control. Demand tracks electrification investments in China and Europe.
- Safety Systems:Airbag and braking modules require ASIL-D certified transceivers with fault-tolerant physical layers.
- Body Control:Lighting, climate, and access systems balance cost against LIN and CAN compatibility.
- Infotainment Systems:Display and audio networking migrates from MOST to Ethernet-based AVB.
- Telematics:Cellular and satellite connectivity modules integrate baseband with RF transceiver functions.
Established revenue pools sit with Powertrain Control. Gaining share fastest is Driver Assistance.
End User:
Buyer concentration shapes specification power and contract structures across the supply chain.
- OEMs:Volkswagen, Hyundai, and Tesla centralize platform architecture decisions, issuing unified PHY requirements across multiple brands. Direct procurement of Ethernet transceivers is climbing as zonal designs internalize gateway functions.
- Tier-1 Suppliers:Bosch, Continental, and Denso aggregate transceiver demand across multiple OEM programs. Their integration role preserves volume leverage in CAN and LIN portfolios.
- Vehicle Assemblers:Contract manufacturers and joint venture plants execute build-to-print specifications with limited component autonomy.
- Aftermarket Providers:Diagnostic tool and retrofit module suppliers source legacy protocol transceivers for vehicle parc maintenance.
Procurement authority concentrates with Tier-1 Suppliers in legacy domains. Direct OEM engagement is expanding in Ethernet and safety-critical sockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates demand for automotive transceivers through its domestic EV production scale and MIIT's local semiconductor sourcing mandates. The country's battery-electric vehicle output now exceeds all other markets combined, pulling transceiver procurement toward regional foundries with GB-certified protocol stacks.
China
Domestic OEMs like BYD and NIO drive multi-gigabit Ethernet transceiver demand for zonal computing architectures. MIIT's GB/T vehicle networking standards enforce electromagnetic compatibility certification for all imported modules, compelling foreign suppliers to establish in-country test facilities. Shanghai and Shenzhen host the primary clusters where local foundries scale production for captive demand pools.
Germany
Volkswagen's SSP platform and centralized gateway requirements anchor European transceiver procurement for premium EV segments. The EU Green Deal's vehicle emissions standards mandate powertrain electrification that demands high-speed data backbone upgrades. Stuttgart and Munich concentrate Tier-1 engineering centers where Bosch and Continental aggregate specification power across multiple OEM programs.
United States
Tesla's vertical integration and zonal architecture deployment drive direct Ethernet transceiver procurement at volumes unmatched by traditional OEM sourcing patterns. FCC Part 15 emissions rules constrain wireless transceiver architectures for C-V2X and UWB modules. Austin and Fremont represent the primary production clusters where centralized computing platforms prioritize multi-gigabit PHY integration.
South Korea
Hyundai's Integrated Modular Architecture issues unified PHY requirements across Kia and Genesis brands, consolidating transceiver specification decisions at Seoul headquarters. The country's foundry concentration in advanced nodes supports domestic transceiver production for export markets. Seoul and Busan anchor the semiconductor manufacturing corridor where 300-millimeter fab capacity serves automotive Ethernet scaling.
Japan
Toyota and Honda retain FlexRay and CAN-FD dominance in hybrid powertrain control while cautiously migrating camera fusion pipelines to automotive Ethernet. METI's technology roadmaps prioritize functional safety integration under ISO 26262 frameworks. Nagoya and Tokyo host the embedded systems clusters where Renesas and Toshiba maintain legacy protocol engineering alongside next-generation PHY development.
Automotive Transceivers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated semiconductor houses dominating high-speed Ethernet sockets while discrete suppliers retain LIN and CAN-FD volumes. The market structure tiers around three archetypes: platform-integrated silicon vendors, multi-protocol portfolio aggregators, and regional foundry-aligned specialists. Consolidation pressure concentrates in gateway applications where ASIL-D certification barriers lock out smaller competitors. Dominant competitive moves include backward integration into substrate technologies and strategic partnerships with zonal architecture platform owners.
Among European-integrated semiconductor houses, NXP Semiconductors, Infineon Technologies, and STMicroelectronics exemplify the platform-integrated archetype. These companies occupy positions where automotive-specific silicon platforms anchor long-term OEM program relationships. Texas Instruments represents the scale-driven manufacturing archetype, sustaining cost leadership through 300-millimeter fab utilization. Broadcom and Analog Devices sit within the high-speed connectivity specialist tier, focusing physical layer innovation on multi-gigabit automotive Ethernet variants.
| Leading Market Players |
|---|
| STMicroelectronics |
| Broadcom |
| NXP Semiconductors |
| Analog Devices |
| Toshiba Corporation |
| Infineon Technologies |
| Microchip Technology |
| Renesas Electronics |
| Texas Instruments |
| Others |
Cost & Logistics Intelligence
RF design engineering talent concentration in Taiwan and South Korea generates labor-cost differentials that widen pricing-tier spreads between automotive Ethernet PHYs and legacy CAN transceivers, with high-frequency mixed-signal expertise commanding premium compensation multiples.
Pricing Analysis
Volume concentration in CAN-FD and LIN transceivers compresses margins through commodity-scale competition, while multi-gigabit automotive Ethernet PHYs sustain premium pricing through ASIL-D certification barriers and SOI substrate scarcity. Price differentiation separates ASIL-D certified gateway modules from ASIL-B powertrain controllers and economy-grade body electronics. Pricing pressure stems from 300-millimeter foundry concentration in Taiwan and South Korea, where water-intensive processes face climate vulnerability. Tier-1 suppliers exhibit highest price sensitivity in LIN and CAN portfolios, whereas OEMs accept premium Ethernet pricing for zonal architecture mandates.
Supply Chain Analysis
Dual-sourcing requirements from Volkswagen, Hyundai, and Tesla mandate multi-supplier qualification for gateway transceivers, fragmenting procurement across NXP, Infineon, and Broadcom to mitigate single-source risk. Geographic supply concentration centers on Taiwan, South Korea, and Germany for advanced node fabrication and automotive qualification. Raw material dependencies include SOI wafers, gallium-nitride substrates, and high-purity copper for single-pair Ethernet cabling. Single-source vulnerability in 300-millimeter foundry capacity exposes supply continuity to geopolitical friction. Distribution runs through Tier-1 system integrators for legacy protocols and direct OEM engagement for Ethernet sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive transceivers occupy a technology-transition phase where multi-gigabit Ethernet PHYs displace legacy CAN hierarchies in zonal architectures, compressing the traditional two-generation upgrade timeline.
For Market Incumbents: Deploy ASIL-D certification investment as the defensive lever to lock gateway revenue pools against emerging GaN-based powertrain interface suppliers. Deepen backward integration into SOI wafer sourcing to secure substrate allocation for thermal-constrained engine-bay placements. Consolidate specification influence through platform-standardization partnerships with Volkswagen's SSP and Hyundai's Integrated Modular Architecture.
For New Entrants and Emerging Players: Tier-2 foundry partnerships in India offer the most penetrable channel for tariff-advantaged ASEAN export sourcing under the PLI scheme. Target aftermarket diagnostic tool suppliers for legacy LIN and CAN-FD transceivers where qualification barriers remain lowest. White-space exists in UWB and C-V2X wireless transceiver modules where baseband-processor convergence displaces discrete incumbents slow to adapt.
For Investors and Strategic Acquirers: Re-rating potential sits with SOI-substrate specialists given EU Green Deal electrification mandates accelerating high-speed backbone demand. Long-term viability favors suppliers with captive foundry relationships and GB/T certification infrastructure for China market access. Watch MIIT domestic sourcing policy enforcement as the inflection signal for regional procurement capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen's SSP architecture consolidates PHY requirements across Audi, Porsche, and Skoda brands. |
| Backward Integration into Substrates | SOI wafer captive supply secures allocation priority from Taiwan foundries during capacity crunches. |
| Software-Defined Vehicle Investment | Persistent high-bandwidth links for over-the-air updates expand Ethernet attach rates into chassis domains. |
| Geographic Manufacturing Footprint | India PLI scheme attracts packaging and test investments for ASEAN tariff-advantaged sourcing. |
| Charging Infrastructure Partnership | High-voltage inverter communication sockets create GaN transceiver displacement opportunities. |
Research Approach
Multi-period observation of vehicle production databases, semiconductor foundry utilization rates, and OEM platform architecture disclosures anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and foundry account managers. Secondary validation drew from MIIT GB/T certification registries, EU Green Deal implementation tracking, FCC Part 15 filings, and SEC 10-K semiconductor segment disclosures. Bottom-up protocol-specific demand modeling triangulated against top-down vehicle production forecasts.
Input-output matrices mapped transceiver content per vehicle across propulsion architectures, vehicle classes, and regional production clusters to generate segment-level projections over the analysis window. CAGRs derived from protocol migration curves, zonal architecture adoption rates, and foundry capacity expansion schedules. Modeled inputs included ISO 26262 certification timelines, SOI substrate supply elasticity, and MIIT local sourcing enforcement intensity.
Caveats apply where foundry concentration risk, geopolitical friction, or GB/T certification delays could materially shift the outlook. Forecasts assume continued zonal architecture consolidation and Ethernet backbone migration without disruptive protocol alternatives. Deviation in Taiwan semiconductor policy or EU emissions standard enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Bluetooth Low Energy Market