
 VR Device Chips Market | 2026-2036
VR Device Chips Market Size, Share, and Industry Trends Forecast 2026-2036
VR Device Chips Market Insights
The OEM-direct procurement channel is rewriting how VR chip vendors reach headset manufacturers. Qualcomm Incorporated leverages its Snapdragon XR platform to anchor premium standalone devices across multiple brands. NVIDIA Corporation competes on graphics processing leadership for tethered enterprise systems. Samsung Electronics Co Ltd controls captive supply chains by integrating in-house Exynos variants into its own Gear and Odyssey product lines.
VR device chips are semiconductor components purpose-built to render stereoscopic displays, track spatial positioning, and manage sub-20ms motion-to-photon latency through dedicated co-processors. SoC architectures dominate volume shipments by integrating CPU, GPU, and AI accelerators onto single die configurations. Gaming applications generate the largest revenue pool, while healthcare and training segments expand fastest as FDA and EMA pathways clarify software-as-medical-device classifications. Graphics processing technology leads R&D allocation, though sensor fusion capabilities differentiate premium tiers through inside-out tracking precision.
FCC electromagnetic emissions standards and EU CE marking requirements shape radio-frequency design constraints for wireless VR chipsets. China's MIIT mandates domestic cybersecurity review for biometric data processing hardware, affecting NMPA-registered medical VR systems. Stakeholders must monitor how ISO/IEC 27001 extensions into immersive environments reshape procurement criteria for enterprise buyers.
Market Dynamics
Foundry capacity allocation for advanced nodes is the central structural force compressing VR chip availability. Taiwan Semiconductor Manufacturing Company and Samsung Foundry prioritize AI accelerator wafer starts over XR SoC orders, extending lead times for headset manufacturers.
Growth Catalysts
- EU AI Act transparency mandates:Biometric VR systems require algorithmic audit trails, driving demand for dedicated neural processing units with embedded logging capabilities.
- Healthcare training simulation:FDA and EMA software-as-medical-device pathways legitimize surgical rehearsal platforms, expanding chip requirements for haptic feedback integration.
- Domestic foundry scaling in China:Semiconductor Manufacturing International Corporation advances 7nm production for local headset OEMs, reducing import dependency for NMPA-registered devices.
Market Restraints
- Advanced packaging substrate shortage:Ajinomoto Build-up Film and glass core substrate supply bottlenecks constrain high-bandwidth memory integration for premium VR SoCs.
- Radio-frequency design complexity:FCC Part 15 emissions testing and EU CE marking for 60GHz WiGig modules add 8-14 weeks to certification cycles.
- Silicon carbide power component costs:Efficient thermal management for standalone headsets depends on SiC regulators with 3x pricing premium over silicon alternatives.
Strategic Opportunities
- India PLI scheme for electronics:Modified incentive structures for semiconductor assembly attract VR module packaging investments near Noida and Chennai clusters.
- Enterprise maintenance training:Aviation and energy sectors deploy mixed-reality procedural guidance, creating chip demand for pass-through camera processing.
- Eye-tracking foveated rendering:Convergence of infrared sensor arrays and machine learning inference engines halves GPU load while preserving perceived resolution.
Industry Challenges
- Photonics integration expertise gap:Laser scanning display architectures require rare optoelectronics talent concentrated in Eindhoven and San Francisco Bay Area corridors.
- ISO/IEC 27001 immersive extensions:Enterprise procurement teams demand security certifications that few chip vendors have completed for biometric data pathways.
- Legacy CAD software compatibility:Industrial VR training systems must bridge proprietary geometry kernels from Dassault Systèmes and Siemens PLM, complicating driver development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Device Chips Market |
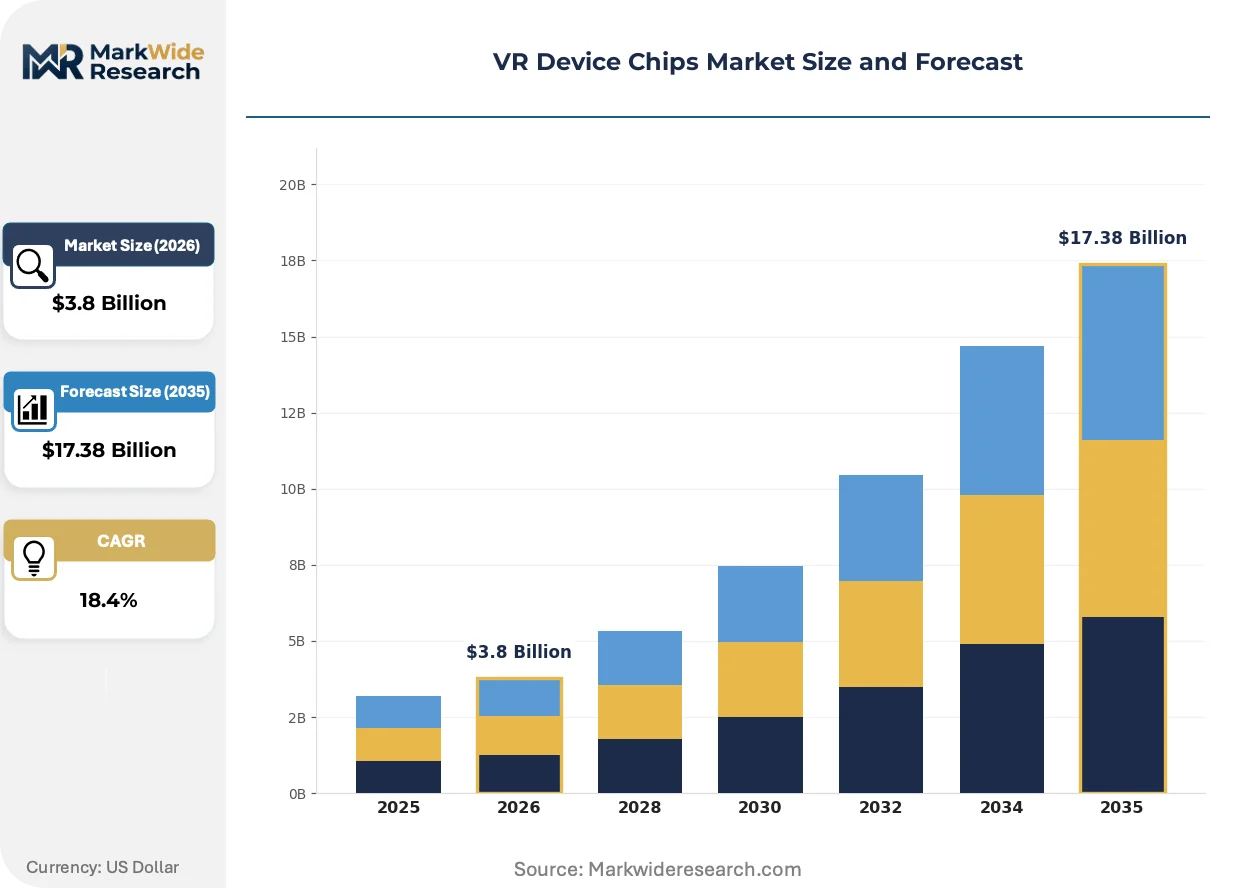
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chip Type: SoC, ASIC, FPGA, DSP Technology: Embedded Systems, Wireless Communication, Sensor Fusion, Graphics Processing Application: Gaming, Education, Healthcare, Training End User: Developers, Enterprises, Educational Institutions, Consumers |
| Companies Covered | Qualcomm Incorporated, NVIDIA Corporation, Advanced Micro Devices Inc, Intel Corporation, MediaTek Inc, Broadcom Inc, Samsung Electronics Co Ltd, Spectra7 Microsystems, Imagination Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Device Chips Market Trends and Innovations
Monolithic integration of previously discrete functions is compressing bill-of-materials complexity while elevating thermal design requirements. This architectural consolidation redefines competitive differentiation away from raw transistor counts toward system-level power efficiency.
Chiplet-based heterogeneous integration is rendering obsolete traditional monolithic SoC strategies for high-end VR devices. Enterprise headset manufacturers at Boeing and Siemens Energy pilot multi-die packages combining logic, memory, and I/O on organic substrates. This approach is rendering obsolete the single-die cost-performance tradeoffs that constrained standalone device battery life.
China's MIIT cybersecurity review for biometric hardware is mandating localized data processing architectures. NMPA-registered medical VR systems must embed encryption engines with domestically certified algorithms, fragmenting previously unified global chip designs. Domestic Chinese foundries are capturing medical device socket opportunities previously served by Taiwan-based suppliers.
Direct procurement relationships between headset OEMs and foundries are displacing traditional merchant semiconductor distribution. Meta Platforms and ByteDance negotiate wafer starts directly with Samsung Foundry and TSMC, bypassing Qualcomm and MediaTek for custom XR silicon. This pattern concentrates most visibly in California and Shenzhen where vertically integrated hardware teams maintain foundry liaison engineers.
VR Device Chips Market Segmentation
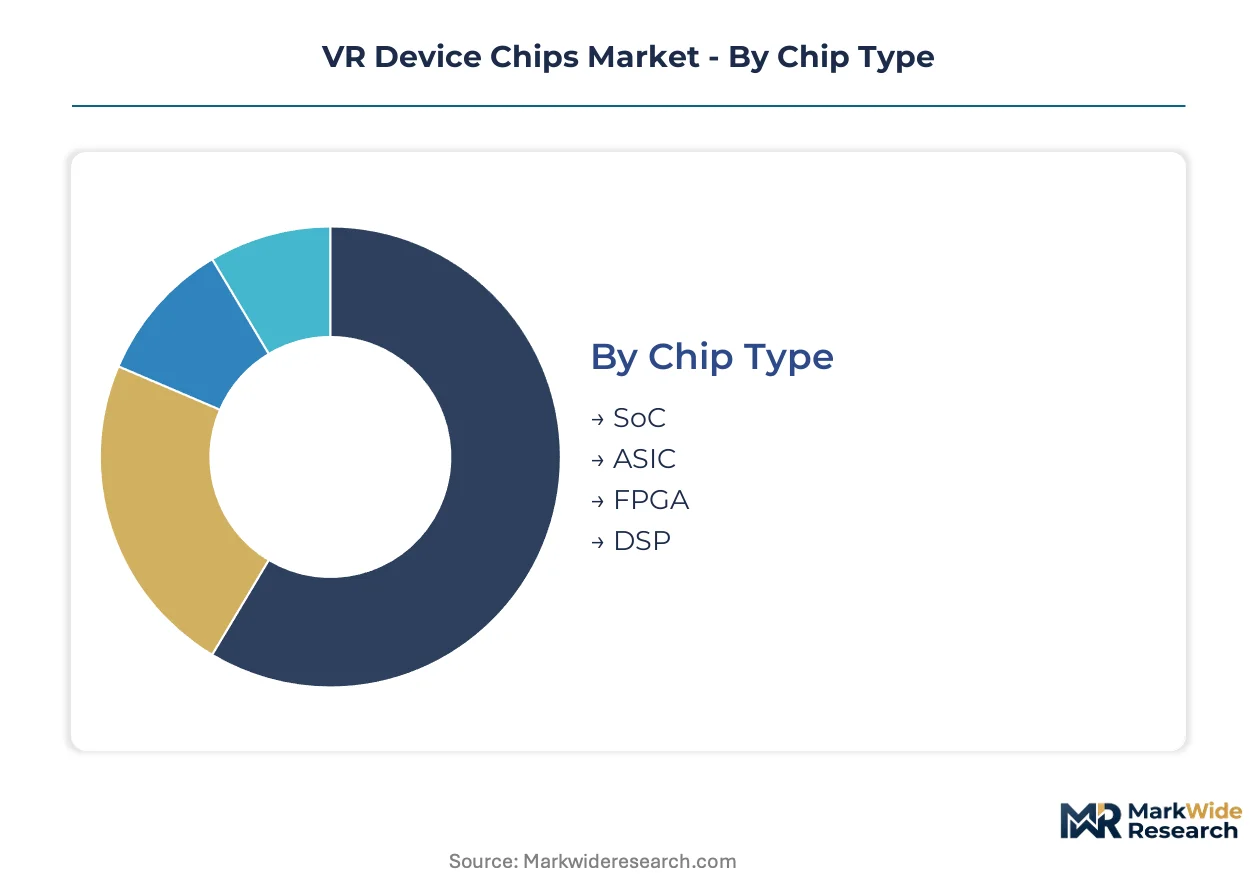
VR device chip architectures fragment across functional specialization, integration density, and deployment context. Each dimension shapes procurement criteria, thermal constraints, and software ecosystem requirements differently.
Chip Type:
Cost tier determines integration approach, with premium standalone headsets favoring maximum die consolidation while tethered systems accept discrete component strategies.
- SoC:Single-die integration of CPU, GPU, and neural accelerators reduces board area and power leakage for battery-constrained standalone headsets. Qualcomm Snapdragon XR and Samsung Exynos variants anchor Meta Quest and ByteDance Pico product lines, with foundry capacity allocation at TSMC and Samsung Foundry constraining availability for second-tier OEMs.
- ASIC:Custom silicon delivers optimized performance-per-watt for fixed-function workloads like foveated rendering and lens distortion correction. Apple Vision Pro employs proprietary ASIC arrays for spatial computing pipelines, with design costs amortized across projected multi-year production runs.
- FPGA:Reconfigurable logic enables rapid prototyping of display interface standards and sensor fusion algorithms before ASIC commitment. Xilinx and Intel Agilex devices populate developer kits and enterprise evaluation platforms.
- DSP:Dedicated digital signal processors handle audio spatialization and haptic feedback loops with deterministic latency. Cirrus Logic and Knowles components integrate into premium audio subsystems.
SoC commands the established base. The steepest expansion runs through ASIC as vertically integrated OEMs pursue custom silicon roadmaps.
Technology:
Application requirements dictate which technology layer receives R&D prioritization, with graphics processing consuming the largest engineering headcount across the ecosystem.
- Embedded Systems:Real-time operating systems and bare-metal firmware manage motion-to-photon latency budgets below 20ms. NXP and Texas Instruments supply microcontroller tiers for tracking subsystems and power management.
- Wireless Communication:60GHz WiGig and Wi-Fi 6E/7 modules enable untethered streaming with sub-5ms transport latency. Qualcomm FastConnect and MediaTek Filogic platforms compete on beamforming stability for multi-room deployment.
- Sensor Fusion:Inertial measurement unit aggregation with camera-based inside-out tracking demands specialized co-processors. STMicroelectronics and Bosch Sensortec dominate IMU supply, while depth sensor fusion algorithms differentiate premium tiers.
- Graphics Processing:Stereoscopic rendering at 90-120Hz drives GPU architecture decisions, with NVIDIA GeForce and AMD RDNA cores serving PC-tethered configurations. Mobile-derived architectures from Arm Mali and Imagination PowerVR scale for thermal-constrained standalone devices.
Graphics processing commands the established base. The steepest expansion runs through sensor fusion as inside-out tracking precision becomes the primary premium differentiator.
Application:
Volume concentration varies sharply by application, with gaming generating unit scale while healthcare and training expand value per socket through specialized certification requirements.
- Gaming:Consumer entertainment drives the largest shipment volumes, with SteamVR and Meta Horizon platforms creating chipset requirements for high-refresh displays and low-latency controller tracking. Sony PlayStation VR2 and Valve Index anchor discrete GPU demand from AMD and NVIDIA.
- Education:Institutional deployment of immersive history, science, and vocational modules creates demand for durable, sanitizable hardware with centralized fleet management. Lenovo and HTC Vive Focus target K-12 and university procurement channels with simplified SoC configurations.
- Healthcare:FDA and EMA software-as-medical-device pathways legitimize surgical rehearsal and pain management applications, requiring chips with deterministic timing and isolation architectures. Stryker and Johnson & Johnson MedTech pilot platforms with custom sensor integration.
- Training:Aviation, energy, and defense sectors deploy mixed-reality procedural guidance with pass-through camera processing for safety-critical environments. Boeing and Siemens Energy negotiate directly with foundries for enterprise-specific silicon.
Gaming commands the established base. The steepest expansion runs through training as industrial safety regulations mandate immersive competency verification.
End User:
Customer type shapes procurement volume, support requirements, and pricing elasticity, with enterprise buyers demanding extended availability commitments absent from consumer channels.
- Consumers:Individual purchasers prioritize content library breadth and standalone convenience over raw specifications, with Meta Quest and Sony dominating through subsidized hardware and exclusive software. Price sensitivity constrains bill-of-materials to mid-tier SoC configurations.
- Enterprises:Corporate IT departments require fleet management, security certification, and multi-year supply guarantees for training and collaboration deployments. HTC Vive Business and Meta for Work platforms address procurement workflows with dedicated support tiers.
- Developers:Engineering teams evaluation platforms demand debug accessibility, reference design documentation, and early access to pre-production silicon. Qualcomm Spaces and NVIDIA Omniverse SDKs anchor toolchains for content creation and hardware optimization.
- Educational Institutions:School districts and universities negotiate volume pricing with durability and sanitization specifications, often through VAR channels rather than direct OEM relationships. Lenovo and Pico maintain education-specific SKUs with extended warranty terms.
Consumers command the established base. The steepest expansion runs through enterprises as aviation, energy, and healthcare sectors mandate immersive training infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics assembly is attracting VR module packaging investments near Noida and Chennai, while China's MIIT cybersecurity mandates reshape domestic foundry priorities for biometric hardware.
United States
FAA and defense procurement for aviation training simulators drives enterprise headset demand. FDA software-as-medical-device pathways legitimize surgical rehearsal platforms requiring deterministic chip architectures. Silicon Valley and Seattle maintain R&D clusters where Meta Platforms and Microsoft negotiate direct wafer allocations with TSMC for custom XR silicon.
China
Domestic headset OEMs ByteDance and Pico scale production for local consumer and education markets. MIIT mandates cybersecurity review for biometric data processing hardware, forcing localized encryption engine designs. Semiconductor Manufacturing International Corporation advances 7nm production in Shanghai for NMPA-registered medical VR systems, reducing import dependency.
Germany
Industrial automation giants Siemens Energy and automotive suppliers deploy mixed-reality maintenance training. EU AI Act transparency requirements apply to biometric VR systems deployed across Bavarian manufacturing facilities. Munich and Stuttgart engineering clusters concentrate optoelectronics talent for laser scanning display development.
South Korea
Samsung Electronics integrates captive Exynos variants into its own Gear and Odyssey product lines. MFDS medical device registration creates parallel certification pathways for healthcare VR platforms. Seoul metropolitan area anchors both foundry operations at Samsung Foundry and display panel integration with chip packaging.
Japan
METI funding for next-generation display technologies supports foveated rendering research. Sony PlayStation VR2 production anchors discrete GPU demand from AMD for tethered gaming configurations. Tokyo and Osaka metropolitan areas concentrate precision optics expertise for pancake lens and waveguide integration with custom silicon.
VR Device Chips Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated platform vendors and specialized component suppliers. Merchant semiconductor vendors compete with captive silicon divisions of major headset manufacturers. Three archetypes dominate: mobile-derived SoC specialists, discrete GPU incumbents, and custom ASIC designers serving single OEMs. Capacity reservation agreements and direct foundry partnerships represent the primary competitive moves, alongside strategic IP licensing for sensor fusion algorithms.
Within the mobile-XR platform tier, Qualcomm Incorporated and MediaTek Inc occupy positions as merchant silicon suppliers to multiple headset brands. NVIDIA Corporation and Advanced Micro Devices Inc exemplify the discrete graphics camp serving tethered enterprise and gaming configurations. Samsung Electronics Co Ltd represents the captive integration model, controlling in-house Exynos supply for its own hardware lines.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| NVIDIA Corporation |
| Advanced Micro Devices Inc |
| Intel Corporation |
| MediaTek Inc |
| Broadcom Inc |
| Samsung Electronics Co Ltd |
| Spectra7 Microsystems |
| Imagination Technologies Limited |
| Others |
Pricing and Supply Chain Analysis
Hsinchu Science Park's foundry capacity allocation decisions cascade directly into downstream pricing power for VR headset OEMs. When Taiwan Semiconductor Manufacturing Company prioritizes AI accelerator wafer starts, XR SoC availability tightens and merchant chip vendors gain leverage on contract terms.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between standard consumer SoCs and enterprise-tier silicon with deterministic timing guarantees. Pricing stratifies across premium medical-grade, standard enterprise, and economy consumer tiers based on validation depth and volume commitments. Cost compression in the consumer tier is intensifying because domestic Chinese foundries are scaling 7nm production for local headset manufacturers. Educational institutions exhibit the highest price sensitivity due to budget-constrained procurement cycles, while healthcare systems prioritize certification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for VR module assemblers. Manufacturing concentrates in Taiwan, South Korea, and China, with advanced node logic fabrication anchored in Hsinchu and Pyeongtaek corridors. Production rests on Ajinomoto Build-up Film substrates, high-bandwidth memory stacks, and silicon carbide power regulators. Single-source vulnerability in advanced packaging materials constrains premium SoC output. Distribution runs through direct foundry-OEM relationships that displace traditional merchant semiconductor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards participants who control scarce photonics integration expertise and direct foundry access. The gap between laser scanning display talent pools in Eindhoven and San Francisco versus broader engineering availability defines sustainable competitive position.
For Market Incumbents: Build captive silicon roadmaps by embedding foundry liaison engineers in California and Shenzhen design centers. Secure multi-year capacity reservation agreements at Samsung Foundry and TSMC before AI accelerator demand further crowds XR SoC allocation. Counter the threat of vertically integrated headset OEMs like Meta Platforms and ByteDance bypassing merchant suppliers by deepening certification investments for FDA and NMPA pathways. For New Entrants and Emerging Players: Build out white-space positions in enterprise maintenance training modules for aviation and energy sectors where procurement workflows favor specialized suppliers over consumer-platform incumbents. Target India's PLI scheme clusters near Noida and Chennai for packaging investments that serve education and institutional markets. Establish go-to-market partnerships with VAR channels that already hold fleet management contracts with school districts and regional hospital systems. For Investors and Strategic Acquirers: Long-term, this sits as a capability-scarcity play because photonics integration expertise and direct foundry relationships cannot be replicated through capital deployment alone. Acquisition targets should display in-house laser scanning display engineering or established liaison teams at advanced foundries. Monitor FDA software-as-medical-device clearance velocity as the inflection signal for healthcare VR chip demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Custom ASIC Development | Apple Vision Pro demonstrates performance-per-watt advantages from proprietary spatial computing silicon arrays. |
| Direct Foundry Partnership | Meta Platforms and ByteDance negotiate wafer starts directly with TSMC and Samsung Foundry, bypassing merchant vendors. |
| Healthcare Certification Investment | FDA and EMA software-as-medical-device pathways legitimize surgical rehearsal platforms with deterministic chip architectures. |
| Chiplet Heterogeneous Integration | Boeing and Siemens Energy pilot multi-die packages combining logic, memory, and I/O on organic substrates. |
| Localized Encryption Engine Design | China's MIIT mandates domestically certified algorithms for NMPA-registered medical VR systems, fragmenting global chip designs. |
Research Methodology
Desk research of foundry capacity reports, semiconductor trade data, and regulatory filing databases preceded structured interviews with headset OEM procurement directors, foundry account managers, and biomedical engineering leads at hospital systems. Primary fieldwork with enterprise VR deployment teams at aviation and energy operators validated secondary estimates of training segment chip requirements. Analysis combined bottom-up bill-of-materials modeling with top-down market sizing across the analysis window.
Assumptions regarding foundry capacity allocation between AI accelerators and XR SoCs were held fixed at current reported ratios, while healthcare certification timelines and domestic Chinese foundry yield trajectories were varied across sensitivity scenarios. The quantitative framework modeled volume and value outputs across chip type, technology layer, application, and end user segments. CAGRs were derived from regression analysis of historical shipment data against content-per-device trends and foundry capacity expansion schedules.
Practitioners should monitor TSMC and Samsung Foundry quarterly earnings disclosures for XR-specific revenue breakdowns as early signals of capacity reallocation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market