
 5G PCB Market | 2026-2036
5G PCB Market Size, Share, and Industry Trends Forecast 2026-2036
5G PCB Market Analysis
Project finance for millimeter-wave infrastructure is tilting competitive dynamics toward capital-intensive manufacturers with proven high-frequency substrate capabilities. Shennan Circuits leverages its vertically integrated substrate operations to secure long-dated supply agreements with base station builders. Nippon Mektron anchors its position through specialized low-loss material formulations that sustain premium pricing in Japanese domestic networks. AT&S competes via European project-financed 5G rollouts where local content requirements favor regional fabrication.
A 5G printed circuit board is a high-frequency electronic interconnect substrate engineered with controlled impedance, low dielectric constant materials, and precision layer stacking to transmit radio frequency signals above 6 GHz with minimal signal loss. These boards enable the dense antenna arrays, beamforming modules, and backhaul interfaces that define fifth-generation wireless infrastructure. Multi-layer PCB configurations currently dominate value capture due to the complexity of integrating RF, digital, and power planes in single substrates. Millimeter Wave Technology represents the fastest-expanding technology segment as carriers deploy frequency bands above 24 GHz requiring ultra-low-loss dielectrics. Base station applications concentrate the largest share of volume demand given the massive antenna element counts in massive MIMO architectures.
The Federal Communications Commission in the United States continues reallocating mid-band spectrum, which directly expands the addressable equipment base requiring compliant high-frequency boards. China's Ministry of Industry and Information Technology enforces GB standards for electromagnetic compatibility that filter out substrate suppliers unable to meet stringent insertion-loss specifications. The European Union's RoHS and REACH frameworks constrain material chemistries, pushing fabricators toward halogen-free prepregs with reworked resin systems. Stakeholders must track how spectrum auction outcomes in major economies redirect PCB specification requirements before committing to capacity expansions.
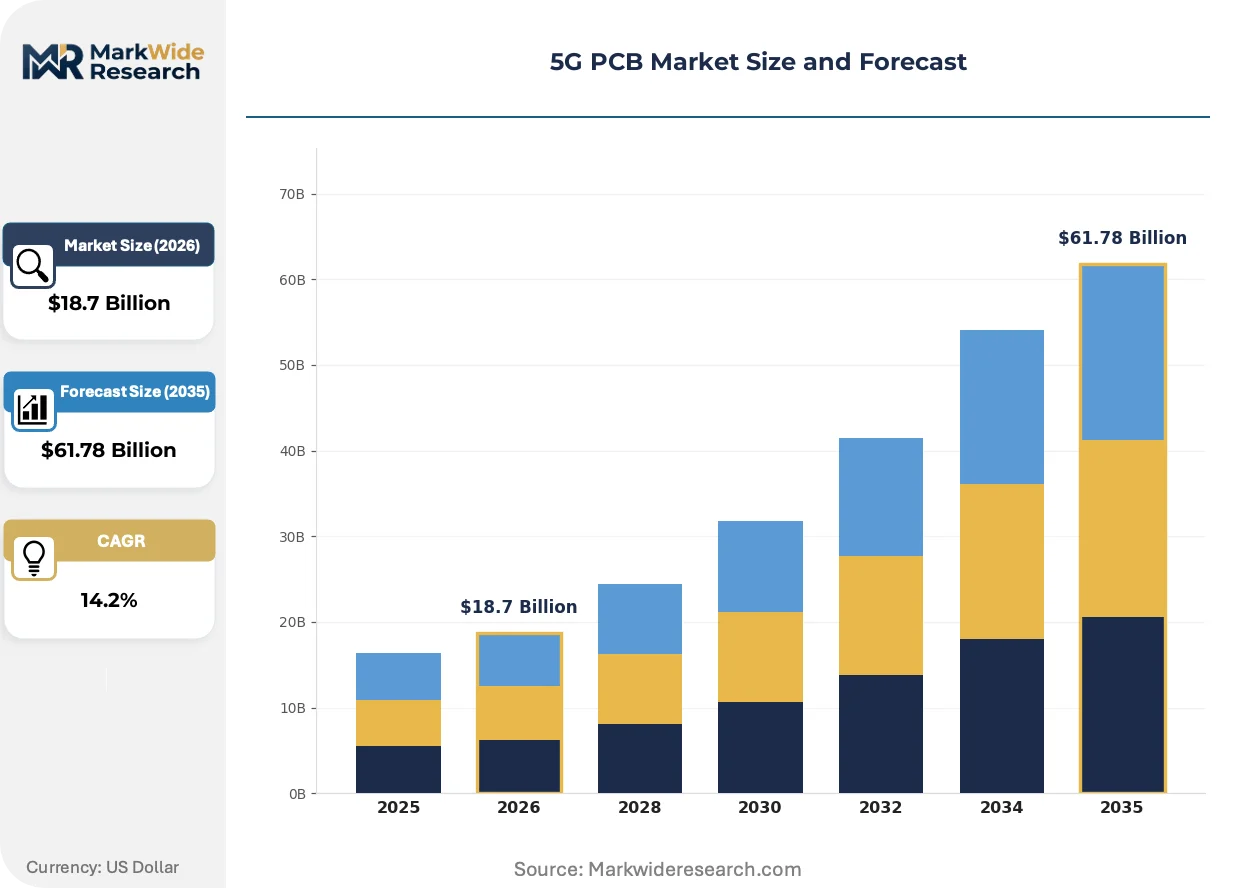
Market Dynamics
Millimeter-wave spectrum commercialization is compressing substrate qualification cycles and forcing fabricators to synchronize R&D roadmaps with carrier deployment timelines rather than traditional product release schedules.
Growth Catalysts
- Mid-band spectrum reallocation:The FCC's ongoing 3.5 GHz and C-band auctions expand the installed base of massive MIMO equipment requiring high-frequency boards.
- Sub-6 GHz infrastructure buildout:China's MIIT mandates for 5G standalone network coverage accelerate procurement of multi-layer substrates for macro base stations.
- Low-loss dielectric formulations:Advanced polytetrafluoroethylene composites enable signal integrity at 28 GHz and above, unlocking millimeter-wave small cell density.
Market Restraints
- Copper foil supply concentration:Rolled annealed copper production clusters in Japan and Taiwan, exposing fabricators to single-source risk for ultra-thin foils below 12 microns.
- REACH substance restrictions:The EU's ban on specific brominated flame retardants forces resin system reformulation, extending qualification timelines by 8-14 months.
- Hybrid bonding equipment costs:Through-silicon via and microvia drilling capital requirements exceed $40 million per line, freezing out mid-tier entrants.
Strategic Opportunities
- Open RAN disaggregation:Interface standardization between radio units and distributed units creates entry points for specialized board suppliers outside incumbent vendor lock-in.
- Indian production-linked incentives:The PLI scheme for telecom equipment manufacturing subsidizes domestic PCB fabrication for 5G gear destined for South Asian markets.
- Thermal management convergence:Integration of embedded copper coin and vapor chamber technologies into antenna-integrated boards addresses passive intermodulation in high-power arrays.
Industry Challenges
- Electromagnetic simulation talent scarcity:Full-wave solver expertise for 3D field analysis of complex via transitions commands premium compensation and extended recruitment cycles.
- Insertion loss certification backlog:GB/T 12629 testing queue times at MIIT-accredited laboratories stretch to 16 weeks, delaying customer qualification milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G PCB Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PCB, Flexible PCB, Rigid-Flex PCB, Multi-layer PCB Technology: RFID Technology, Microwave Technology, Millimeter Wave Technology, Optical Technology End User: Telecommunications, Consumer Electronics, Automotive, Industrial Application: Base Stations, Mobile Devices, IoT Devices, Network Infrastructure |
| Companies Covered | Shennan Circuits, Avary Holding, Zhen Ding Technology Holding, Nippon Mektron, WUS Printed Circuit, AT&S, TTM Technologies, Unimicron Technology, Compeq Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G PCB Market Emerging Trajectories
Substrate engineering is pivoting from incremental dielectric constant reduction toward holistic signal-power-thermal co-design as antenna integration density escalates.
Embedded dielectric films with tunable z-axis CTE are digitizing thermal-mechanical design workflows. Base station OEMs now specify these materials for 64T64R arrays where CTE mismatch between ceramic antenna elements and organic substrates induces solder joint fatigue. The shift compresses traditional prototyping iterations from twelve weeks to four.
China's GB standards for electromagnetic compatibility are tightening insertion-loss tolerances across the 24-40 GHz range. MIIT enforcement actions against non-compliant substrate imports redirect procurement toward domestic fabricators with certified measurement traceability. European module suppliers face exclusion from state-backed base station tenders unless they establish local testing partnerships.
Carrier procurement teams now mandate open disaggregated interface compliance before board qualification. Tier-one OEMs respond by unbundling radio unit substrates from system-level contracts, creating direct purchasing relationships with specialized fabricators. South Korean operators lead this transition, with SK Telecom and KT issuing separate RF board RFPs distinct from macro vendor selection.
5G PCB Market Segmentation
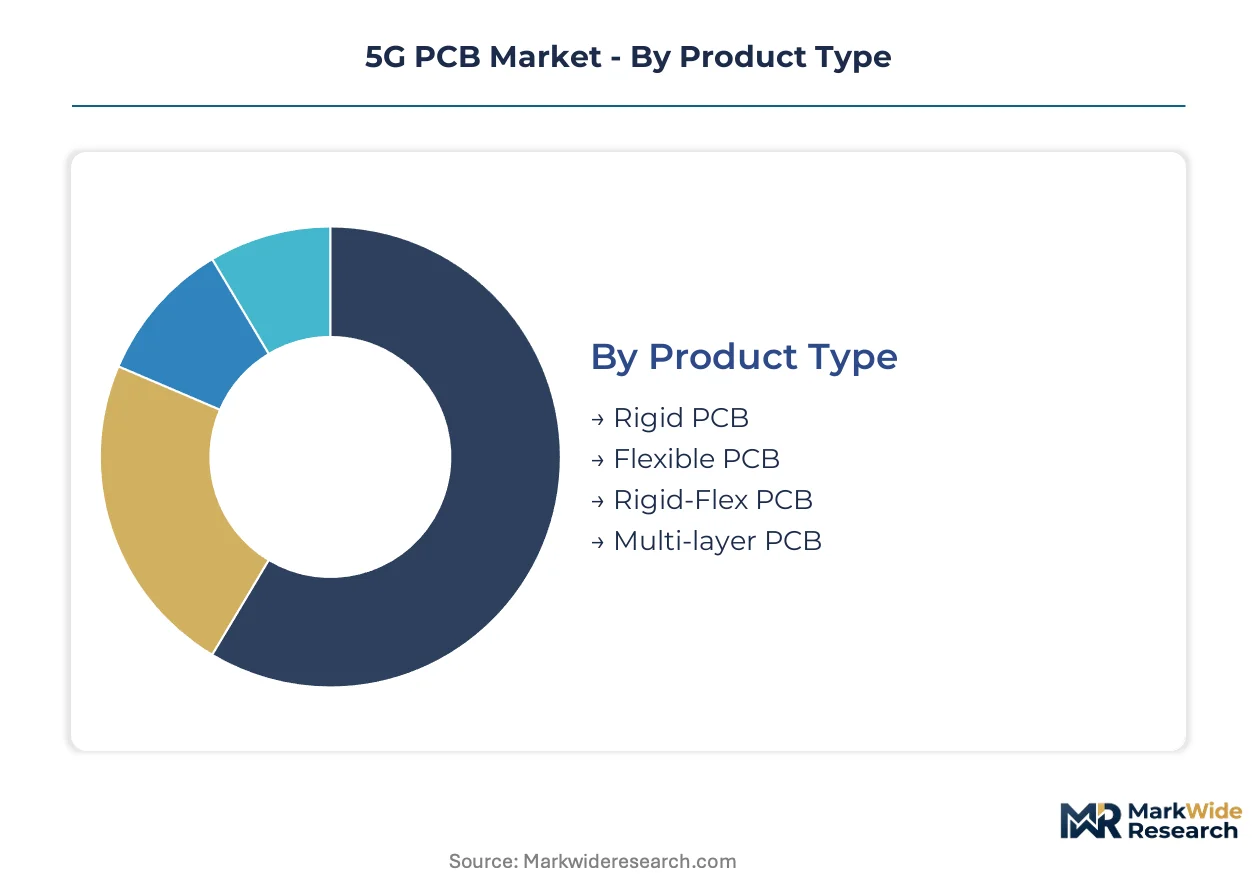
Segmentation in 5G PCBs reveals distinct procurement rhythms across product architectures and frequency technologies. Cycle-time variations between qualification-heavy millimeter-wave substrates and commoditized flexible circuits dictate working capital requirements and inventory strategies for fabricators.
Product Type:
Replacement cycles stretch from 18 months for standard rigid boards to 36 months for qualified multi-layer substrates in base station applications.
- Multi-layer PCB:These substrates integrate RF, digital, and power planes through precision layer stacking with controlled impedance routing. Demand concentrates in Guangdong Province's manufacturing corridor where telecom operators source 64T64R massive MIMO antenna arrays requiring 12-20 layer configurations.
- Rigid PCB:Standard fiberglass-reinforced epoxy laminates serve lower-frequency sub-6 GHz infrastructure with established supply chains and compressed qualification timelines. Procurement from European module suppliers accelerates for Open RAN radio units where interface standardization unbundles sourcing from system vendors.
- Flexible PCB:Polyimide-based substrates enable compact antenna integration in mobile devices and wearables.
- Rigid-Flex PCB:Hybrid constructions bridge mechanical constraints in automotive antenna modules and industrial sensors.
Multi-layer PCB anchors the volume base while Rigid-Flex PCB gains share at the steepest rate.
Technology:
Cost tiers separate commodity RFID substrates from precision millimeter-wave dielectrics commanding 4-6x material premiums.
- Millimeter Wave Technology:Ultra-low-loss polytetrafluoroethylene composites and ceramic-filled hydrocarbons enable signal integrity above 24 GHz. South Korean carriers SK Telecom and KT drive procurement for small cell density deployments in Seoul's urban corridors.
- Microwave Technology:Mid-range dielectric constant materials in the 3-6 GHz range balance performance against cost for sub-6 GHz macro coverage. China's MIIT mandates accelerate domestic qualification of halogen-free prepregs meeting GB/T 12629 insertion-loss specifications.
- RFID Technology:Standard FR-4 derivatives support inventory tracking and asset management in logistics networks.
- Optical Technology:Photonic-integrated substrates address fronthaul bandwidth aggregation in centralized radio access architectures.
Microwave Technology anchors the volume base while Millimeter Wave Technology expands most quickly.
End User:
Customer type determines specification stringency, with telecommunications procurement teams mandating full electromagnetic certification versus industrial buyers accepting reduced test matrices.
- Telecommunications:Base station OEMs and carriers specify insertion-loss tolerances, thermal cycling resilience, and passive intermodulation performance. FCC spectrum reallocation in the United States expands the addressable equipment base for C-band and 3.5 GHz deployments.
- Consumer Electronics:Smartphone manufacturers drive high-volume flexible circuit demand with compressed 9-12 month product lifecycles.
- Automotive:V2X communication modules and antenna-integrated substrates face AEC-Q200 reliability qualification.
- Industrial:Private 5G networks for manufacturing automation utilize ruggedized boards with extended temperature specifications.
Telecommunications anchors the volume base while Automotive gains share at the steepest rate.
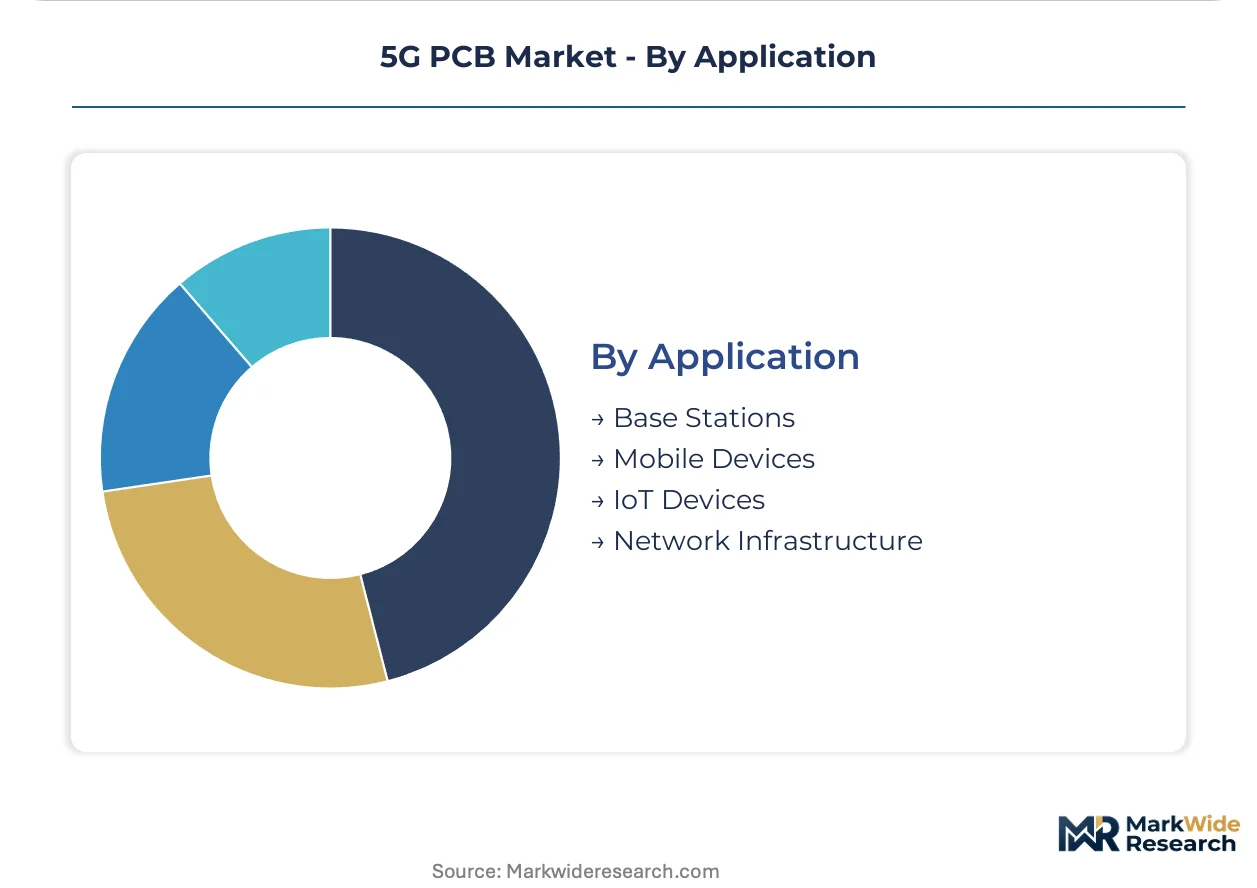
Application:
Supply concentration varies sharply, with base station substrates consolidating among qualified high-frequency specialists while mobile device boards fragment across numerous flex circuit suppliers.
- Base Stations:Massive MIMO architectures demand antenna-integrated boards with embedded thermal management and precise phase-match routing. China's state-backed tenders redirect procurement toward domestic fabricators with MIIT-certified measurement traceability.
- Mobile Devices:Smartphone antenna modules and RF front-end substrates prioritize miniaturization and cost optimization.
- IoT Devices:Low-power wide-area network modules utilize simplified multi-layer constructions for sensor connectivity.
- Network Infrastructure:Core routing and transport equipment requires backplane substrates with high layer counts and signal integrity.
Base Stations anchors the volume base while IoT Devices climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National spectrum allocation programs and state-backed infrastructure tenders are redirecting procurement flows toward qualified domestic fabricators with certified electromagnetic measurement capabilities.
China
MIIT mandates for 5G standalone network coverage accelerate procurement of multi-layer substrates for macro base stations. GB standards for electromagnetic compatibility tighten insertion-loss tolerances across the 24-40 GHz range, filtering out non-compliant imports. Guangdong Province's PCB manufacturing corridor concentrates demand as telecom operators source 64T64R massive MIMO antenna arrays requiring 12-20 layer configurations.
South Korea
SK Telecom and KT drive procurement for small cell density deployments in Seoul's urban corridors using millimeter-wave frequency bands above 24 GHz. The national spectrum auction framework prioritizes ultra-dense network architectures requiring ultra-low-loss dielectrics. Busan-Ulsan manufacturing clusters anchor substrate qualification programs synchronized with carrier deployment timelines.
United States
FCC reallocation of mid-band spectrum at 3.5 GHz and C-band expands the addressable equipment base for massive MIMO deployments. Federal infrastructure spending programs prioritize domestic supply chain resilience for critical telecommunications components. Texas and Arizona fabrication hubs attract capacity investments targeting Open RAN radio unit production.
Japan
METI industrial policy supports domestic substrate manufacturers specializing in rolled annealed copper foils below 12 microns for high-frequency applications. JIS standards for telecommunications equipment enforce stringent reliability qualifications that sustain premium pricing in domestic networks. Kanto and Kansai manufacturing belts concentrate R&D activities for next-generation antenna-integrated boards.
Germany
EU Green Deal implementation and REACH substance restrictions push fabricators toward halogen-free prepregs with reworked resin systems. The national telecommunications regulator aligns spectrum awards with local content requirements favoring regional fabrication. Bavaria and Baden-Württemberg precision manufacturing clusters supply backplane substrates for core routing and transport equipment.
5G PCB Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. The vendor base organizes around three strategic archetypes: vertically integrated substrate operators capturing long-dated supply agreements, specialized material formulators commanding premium pricing through proprietary dielectric formulations, and regional fabricators leveraging local content requirements in project-financed rollouts. Dominant competitive moves include backward integration into copper foil production and strategic partnerships with base station OEMs for synchronized R&D roadmaps.
Among Asia-Pacific-based fabricators, Shennan Circuits, Nippon Mektron, and AT&S occupy positions representing distinct competitive vectors. Shennan Circuits exemplifies the vertically integrated archetype with captive substrate operations. Nippon Mektron anchors the specialized material formulation tier. AT&S represents the regional fabrication model capitalizing on European project-financed 5G rollouts.
| Leading Market Players |
|---|
| Shennan Circuits |
| Avary Holding |
| Zhen Ding Technology Holding |
| Nippon Mektron |
| WUS Printed Circuit |
| AT&S |
| TTM Technologies |
| Unimicron Technology |
| Compeq Manufacturing |
| Others |
Supply Flow & Price Mechanics
Rolled annealed copper production clusters in Japan and Taiwan concentrate upstream supply for ultra-thin foils below 12 microns, anchoring margin pools with substrate fabricators qualified for millimeter-wave base station deployments. This geographic lock on critical input material shapes pricing power across the value chain, with qualified suppliers commanding sustained premiums while unqualified competitors face exclusion from carrier procurement programs.
Pricing Analysis
Certification level under GB/T 12629 and MIIT electromagnetic compatibility standards creates the primary spread between pricing tiers, with qualified domestic fabricators in Guangdong Province capturing 3-4x material premiums over unqualified imports. Three-tier pricing structure separates premium millimeter-wave substrates with certified measurement traceability from standard multi-layer boards for sub-6 GHz infrastructure and economy-grade rigid PCBs for industrial applications. Cost compression in the standard tier is intensifying as Open RAN interface standardization unbundles sourcing from system vendors and expands the qualified supplier base. Telecommunications procurement teams show lowest price sensitivity given qualification timelines and performance guarantees, while industrial private network buyers prioritize cost optimization over certification depth.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Shennan Circuits, Nippon Mektron, and AT&S, with each anchoring distinct regional supply zones through captive substrate operations or specialized material formulations. Raw material dependencies center on polytetrafluoroethylene composites from Japanese chemical suppliers, ceramic-filled hydrocarbons from South Korean formulators, and halogen-free prepregs reworked for REACH compliance in European fabrication hubs. Single-source vulnerability runs through ultra-thin copper foil supply below 12 microns, where Japanese and Taiwanese producers control annealing expertise essential for high-frequency signal integrity. Distribution runs through direct purchasing relationships between specialized fabricators and base station OEMs, bypassing traditional system-level contracting as carriers mandate open disaggregated interface compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as Open RAN disaggregation unbundles radio unit substrates from macro vendor lock-in, creating entry niches for specialized fabricators outside incumbent supply relationships. This demand-side architectural shift fragments procurement authority and multiplies addressable supplier relationships across carrier deployment programs.
For Market Incumbents: Harden supply relationships through backward integration into copper foil production and synchronized R&D roadmaps with base station OEMs. Defensive moves should prioritize captive supply of ultra-thin annealed copper below 12 microns to neutralize single-source exposure, while certification investment in MIIT-accredited measurement traceability secures position in China's state-backed tender programs. The emerging threat is specialized millimeter-wave material formulators displacing volume fabricators in premium frequency segments.
For New Entrants and Emerging Players: Build out qualification capabilities for halogen-free prepregs meeting GB/T 12629 insertion-loss specifications to access China's domestic procurement redirection. The most penetrable white-space sits in Indian production-linked incentive schemes subsidizing domestic PCB fabrication for South Asian 5G gear, with thermal management convergence into antenna-integrated boards offering a differentiated go-to-market angle against established multi-layer suppliers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated substrate operators with captive high-frequency material operations and established carrier qualification relationships. Long-term viability across the projection horizon rests on fabricators capable of compressing substrate qualification cycles to match millimeter-wave deployment timelines rather than traditional product release schedules. The signal to monitor is carrier procurement team mandates for open disaggregated interface compliance, which unbundle radio unit substrates and redirect purchasing authority toward specialized suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil | Captive supply of ultra-thin annealed foils below 12 microns neutralizes Japanese-Taiwanese single-source concentration. |
| MIIT Certification Investment | GB/T 12629 measurement traceability secures access to China's state-backed base station tender programs. |
| Open RAN Interface Qualification | Radio unit substrate unbundling creates direct purchasing relationships outside incumbent vendor lock-in. |
| Thermal Management Convergence | Embedded copper coin and vapor chamber integration addresses passive intermodulation in high-power 64T64R arrays. |
| Indian PLI Scheme Participation | Domestic fabrication subsidies for 5G gear unlock South Asian procurement flows outside Chinese supply concentration. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with substrate engineering directors, carrier procurement managers, base station OEM supply chain leads, and electromagnetic simulation specialists; alongside secondary validation through MIIT GB standard filings, FCC spectrum auction records, carrier RFP documentation, and customs trade data for high-frequency laminate imports. Bottom-up triangulation across fabricator capacity disclosures and top-down reconciliation against carrier deployment capex schedules anchored volume and value estimates.
Forecast inputs incorporated technology migration curves from sub-6 GHz to millimeter-wave frequency bands, regional spectrum allocation timelines, and substrate qualification cycle compression rates across the projection horizon. Segmentation modeling spanned product architecture, frequency technology, end-user procurement stringency, and application-specific thermal-mechanical requirements. CAGRs were derived from fitted diffusion curves weighted by carrier deployment schedules and OEM inventory build patterns.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier fabricators or accelerated Open RAN procurement unbundling would shift outcomes beyond modeled ranges. Quarterly review of MIIT certification queue times, FCC spectrum reallocation announcements, and carrier RFP unbundling language is advised to detect inflection in competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market