
 I2C Bus Market | 2026-2036
I2C Bus Market Size, Share, and Industry Trends Forecast 2026-2036
I2C Bus Market Foresight
Silicon-on-insulator substrates is repositioning cost-performance tradeoffs for high-speed I2C transceivers in automotive and industrial nodes. Texas Instruments Incorporated leverages its foundry partnerships to sustain volume supply of automotive-grade I2C level shifters. NXP Semiconductors anchors its position through dominance in multi-master arbitration IP for vehicle network gateways. STMicroelectronics differentiates by integrating I2C with MEMS sensor hubs for smartphone and wearable OEMs.
The I2C bus is a two-wire serial communication protocol operating on serial data and serial clock lines at rates from 100 kbit/s standard mode through 3.4 Mbit/s high-speed mode, designed for short-distance chip-to-chip interconnect in embedded systems. Consumer electronics application remains the largest volume pool, though automotive is displacing it as the fastest-expanding segment due to zonal E/E architecture proliferation. Fast Mode Plus data rate capability is capturing premium margin allocation as industrial automation buyers specify 1 Mbit/s throughput for real-time sensor polling.
FCC electromagnetic compatibility rules constrain signal integrity design for I2C implementations in US-market medical devices, while EU RoHS and REACH directives govern halogen-free PCB substrate requirements across European-bound shipments. China's GB standards and MIIT certification protocols mandate domestic electromagnetic interference testing for I2C-containing modules sold into state infrastructure projects. Stakeholders must monitor how regional semiconductor subsidy regimes alter foundry capacity allocation for mixed-signal I2C peripheral production.
Market Dynamics
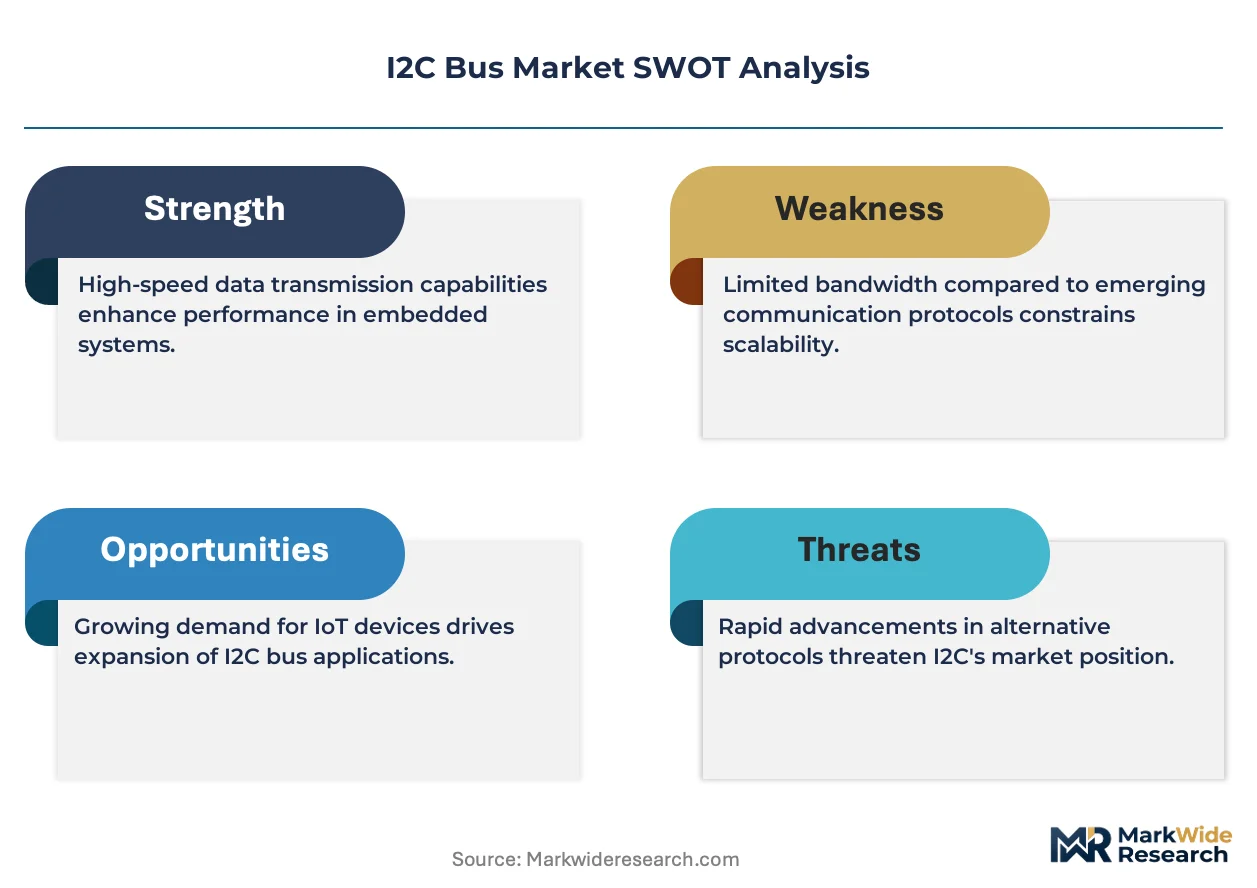
Automotive zonal E/E architectures are forcing I2C bus redesigns for sensor cluster density, while EU hardware security mandates and China foundry localization reshape supply-side configuration.
Growth Catalysts
- EU Cyber Resilience Act hardware mandates:Connected device manufacturers must implement secure bus protocols, driving I2C controller upgrades with embedded cryptographic authentication.
- China domestic foundry expansion:Local mixed-signal capacity for I2C-compatible peripherals is reducing import dependency for state infrastructure OEM supply chains.
- Fast Mode Plus industrial specification:Real-time sensor polling at 1 Mbit/s throughput is displacing legacy SPI implementations in factory automation nodes.
Market Restraints
- Silicon-on-insulator substrate cost premiums:High-speed automotive transceivers face margin compression from 300mm SOI wafer supply tightness.
- Single-source arbitration IP concentration:Vehicle gateway multi-master logic remains dependent on a narrow licensor base.
- FCC EMC testing burden:US-market medical device I2C implementations require expensive signal integrity validation cycles.
Strategic Opportunities
- India PLI scheme semiconductor incentives:Domestic assembly of I2C sensor modules for smartphone OEMs qualifies for production-linked subsidies.
- MEMS sensor hub convergence:Wearable OEMs are consolidating accelerometer, gyroscope and environmental sensing behind unified I2C backplanes.
- EU RoHS halogen-free substrate transition:PCB material suppliers capturing premium positioning through REACH-compliant laminate certification.
Industry Challenges
- Multi-master firmware complexity:Embedded engineering talent capable of clock-stretching arbitration debugging remains scarce across automotive tier-1s.
- Legacy 5V logic integration:Industrial retrofit projects face voltage-level translation failures when interfacing modern 1.8V I2C cores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | I2C Bus Market |
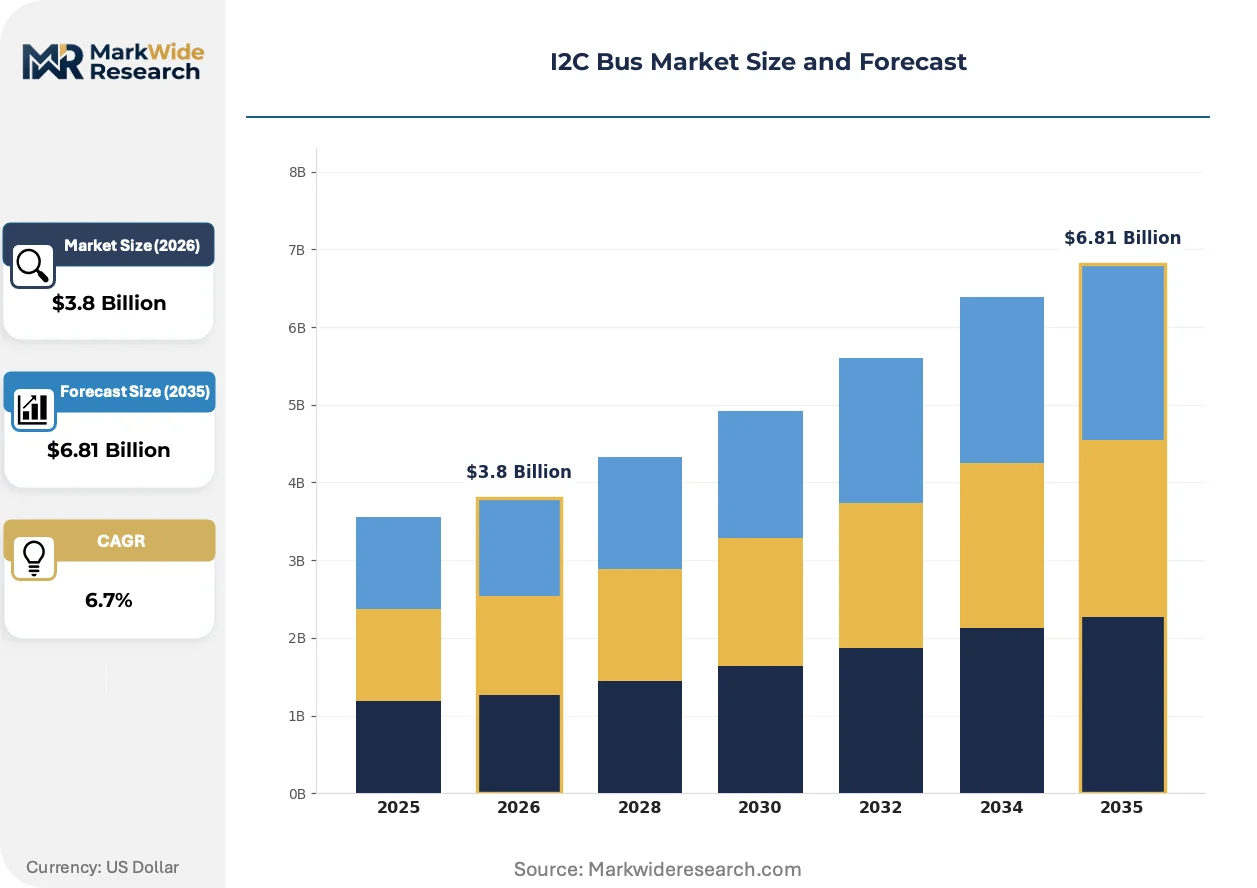
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Microcontrollers, Sensors, Memory Devices, Display Controllers Application: Consumer Electronics, Automotive, Medical Devices, Industrial Automation Data Rate: Standard Mode, Fast Mode, Fast Mode Plus, High-Speed Mode Interface: Single Master, Multi-Master, Slave, Multi-Slave |
| Companies Covered | Texas Instruments Incorporated, NXP Semiconductors, STMicroelectronics, Microchip Technology Inc., Renesas Electronics Corporation, Infineon Technologies, Analog Devices, Inc., ON Semiconductor Corporation, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
I2C Bus Market Shifts & Advancements
Silicon substrate engineering, electromagnetic compliance regimes and procurement centralization are compressing design cycles and reshaping vendor selection criteria across I2C ecosystem participants.
Silicon-on-insulator technology is integrating high-voltage isolation directly into automotive I2C transceiver dies, eliminating external level-shifter components. Tier-1 suppliers in Germany and Japan are qualifying SOI-based devices for 48V mild-hybrid battery management systems. This integration is collapsing bill-of-material counts while tightening foundry partnerships around specialty substrate supply.
EU REACH halogen-free mandates are forcing PCB laminate reformulation for I2C module shipments bound for European medical and industrial OEMs. Substrate suppliers must now document full material disclosure across flame-retardant chemistries. German automotive harness manufacturers are responding by consolidating qualified laminate vendors to three approved sources per program.
Chinese smartphone OEMs are centralizing I2C sensor procurement through captive semiconductor divisions, bypassing traditional distribution channels. Direct foundry relationships for MEMS hub controllers are replacing multi-tier component sourcing. This concentration is most visible in Shenzhen and Dongguan manufacturing clusters, where vertical integration into mixed-signal design accelerates.
I2C Bus Market Segmentation
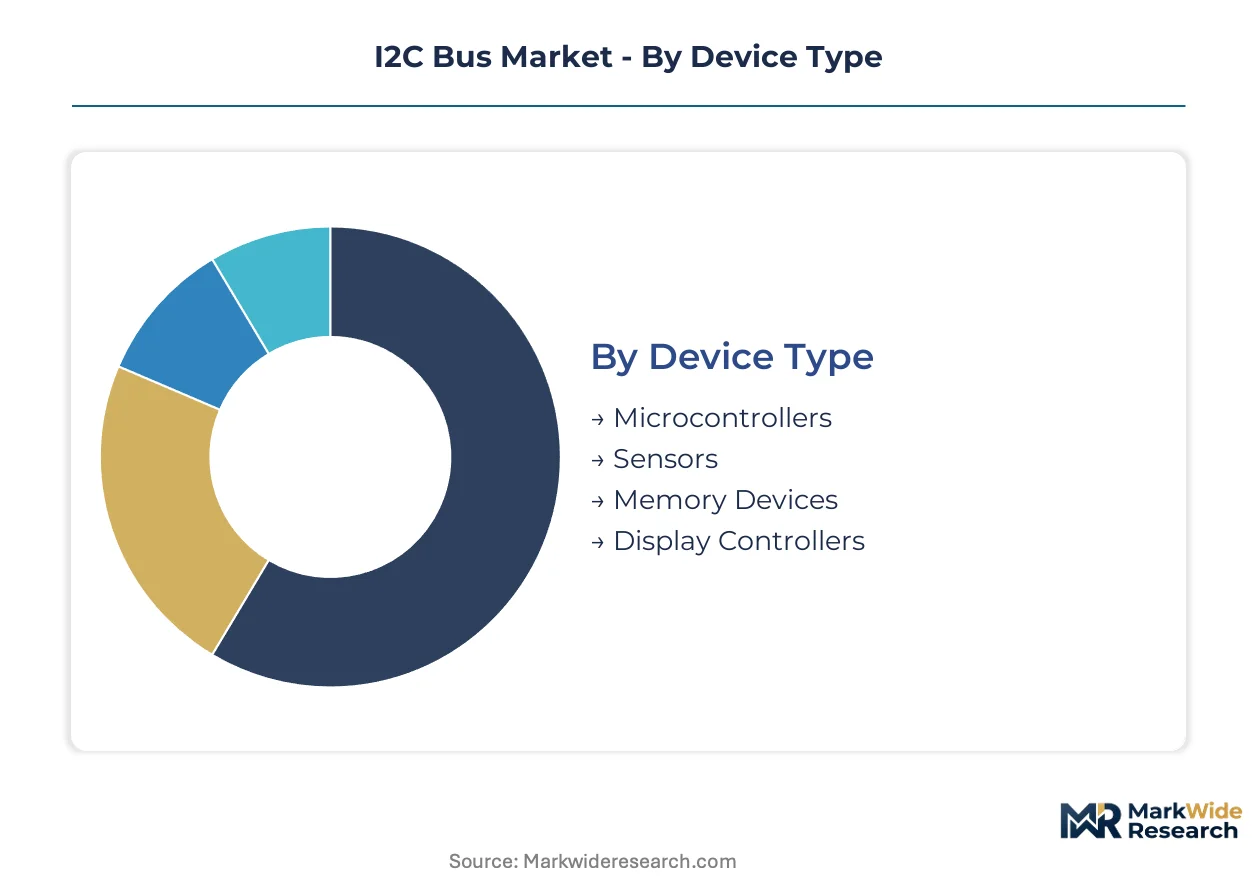
I2C bus segmentation reveals how specification tiers, device architectures, and interface configurations align with divergent end-use requirements. Technical tradeoffs between speed, power, and complexity drive procurement patterns across automotive, industrial, and consumer domains.
Device Type:
Silicon integration levels distinguish cost-performance positioning across the four device categories.
- Sensors:MEMS accelerometers, gyroscopes, and environmental monitors dominate unit volume through smartphone and wearable OEM procurement. Automotive zonal E/E architectures are expanding sensor cluster density for battery thermal management and cabin comfort systems.
- Microcontrollers:Mixed-signal MCUs with embedded I2C peripherals anchor industrial automation nodes and body electronics modules. China domestic foundries are scaling 40nm-90nm production for local OEM supply chains, reducing import dependency.
- Memory Devices:EEPROM and serial flash for configuration storage in medical devices and telecom infrastructure.
- Display Controllers:OLED driver ICs and touch panel controllers for consumer electronics panels.
Mature deployment sits with Microcontrollers. Newer deployment is concentrated in Sensors.
Application:
End-use differentiation separates high-volume consumer procurement from specification-intensive automotive and medical qualification cycles.
- Automotive:Zonal E/E architectures mandate I2C redesigns for sensor cluster density in battery management and ADAS peripheral networks. 48V mild-hybrid systems require high-voltage isolation integration.
- Industrial Automation:Factory nodes specify Fast Mode Plus 1 Mbit/s throughput for real-time sensor polling, displacing legacy SPI in motion control and process monitoring.
- Consumer Electronics:Smartphone and wearable OEMs drive volume through MEMS hub consolidation behind unified I2C backplanes.
- Medical Devices:FCC EMC testing constrains signal integrity design for US-market diagnostic equipment and patient monitors.
Volume concentration remains in Consumer Electronics. Steepest expansion trajectory is in Automotive.
Data Rate:
Speed-grade selection determines power consumption, trace length tolerance, and EMI compliance margins.
- Fast Mode Plus:1 Mbit/s specification captures premium margin allocation as industrial buyers mandate real-time throughput for sensor polling. German automotive tier-1s are qualifying devices for 48V battery management networks.
- High-Speed Mode:3.4 Mbit/s operation requires active pull-up buffering and PCB layout discipline. Limited deployment in high-resolution camera interfaces and FPGA configuration buses.
- Fast Mode:400 kbit/s legacy support in consumer electronics and basic sensor networks.
- Standard Mode:100 kbit/s baseline for cost-constrained legacy industrial retrofit projects.
Legacy volume sits with Fast Mode. Specification migration is accelerating toward Fast Mode Plus.
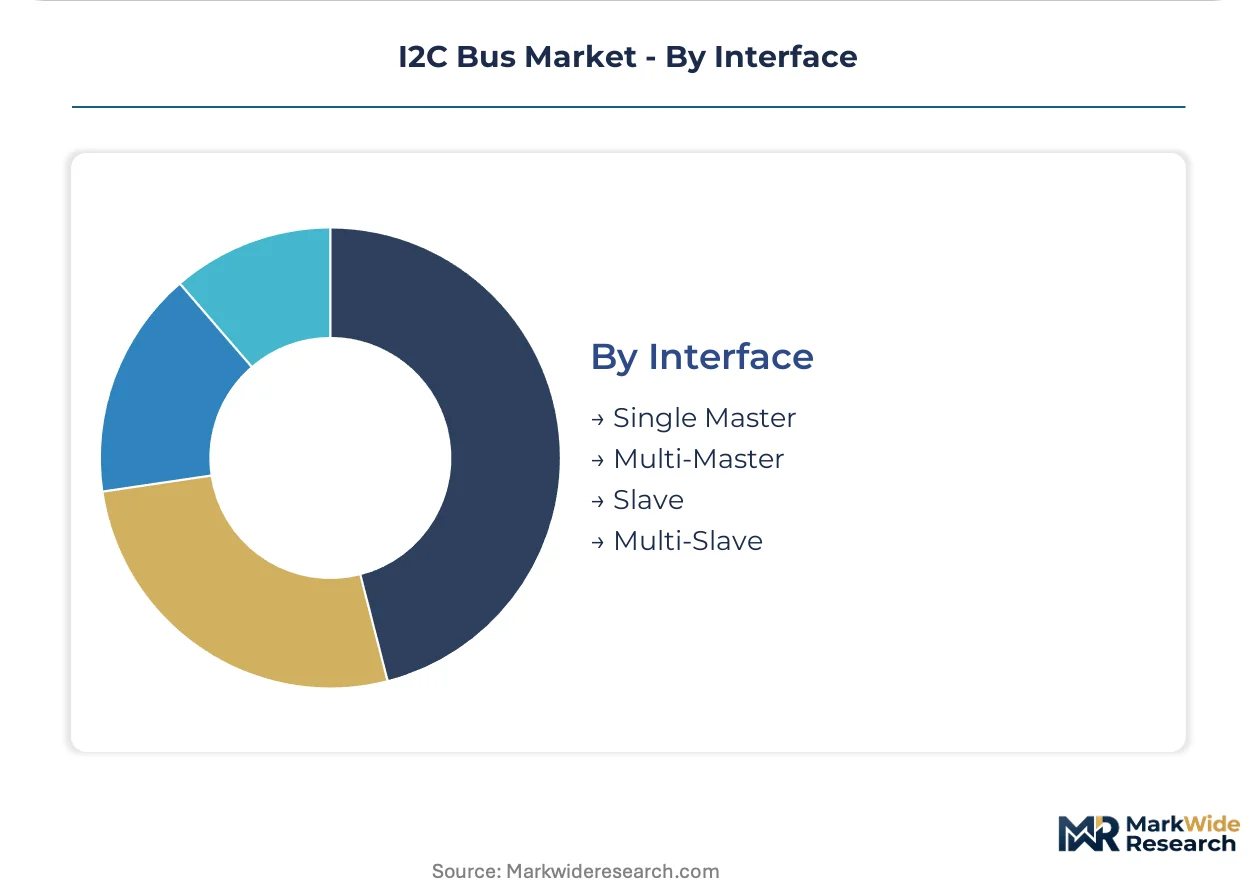
Interface:
Master-slave configuration complexity scales with system architecture requirements and firmware development burden.
- Multi-Master:Arbitration IP enables vehicle gateway consolidation of sensor domains across powertrain, chassis, and body electronics. Clock-stretching complexity creates firmware talent scarcity across automotive tier-1s.
- Single Master:Simplified stack implementation dominates consumer electronics and basic industrial nodes where one host processor controls all peripherals.
- Slave:Peripheral-only devices for dedicated sensor or memory functions in distributed architectures.
- Multi-Slave:Addressable peripheral arrays in dense sensor clusters for HVAC and building automation.
Design simplicity favors Single Master. Functional expansion is driving Multi-Master adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of I2C bus procurement volume through domestic smartphone OEM supply chains and state infrastructure projects. Germany and Japan anchor automotive-grade qualification demand through zonal E/E architecture deployment. The United States sustains medical device and industrial automation specification leadership.
China
Shenzhen and Dongguan manufacturing clusters drive I2C sensor hub procurement for smartphone and wearable OEMs. MIIT certification protocols mandate domestic electromagnetic interference testing for modules sold into state infrastructure projects. Domestic foundries in Shanghai and Beijing are scaling 40nm-90nm mixed-signal production to reduce import dependency for local supply chains.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich are qualifying Fast Mode Plus devices for 48V mild-hybrid battery management systems. KBA vehicle type approval processes enforce hardware-level security validation for connected bus architectures. Bavarian harness manufacturers are consolidating qualified laminate vendors to three approved sources per program under REACH halogen-free mandates.
United States
FCC electromagnetic compatibility rules constrain signal integrity design for I2C implementations in medical devices and diagnostic equipment. Boston and San Francisco Bay Area clusters concentrate FDA-cleared device development requiring expensive EMC validation cycles. Industrial automation buyers in the Midwest specify 1 Mbit/s throughput for real-time sensor polling in factory nodes.
Japan
METI industrial standards guide I2C deployment in precision manufacturing and robotics applications. Nagoya and Osaka industrial corridors anchor demand for high-reliability transceivers in motion control systems. Domestic semiconductor houses are deepening foundry partnerships for automotive-grade mixed-signal peripheral production.
South Korea
Seoul Capital Area electronics conglomerates drive I2C display controller procurement for OLED panel manufacturing. MFDS medical device regulations align with international EMC standards for diagnostic equipment exports. Busan-Ulsan industrial zones concentrate MEMS sensor packaging for smartphone OEM vertical integration strategies.
I2C Bus Market Competitive Landscape
Foundry partnership expansion dominates the current landscape as vendors secure specialty substrate supply for automotive-grade production. The market structures around three tiers: integrated device manufacturers with captive fabrication, fabless specialists licensing arbitration IP, and foundry-dependent mixed-signal houses. Two strategic archetypes prevail: SOI substrate pioneers collapsing bill-of-material counts, and MEMS hub integrators consolidating sensor backplanes. Capacity expansion and technology licensing represent the dominant competitive moves.
Among integrated device manufacturers, Texas Instruments Incorporated, NXP Semiconductors, and STMicroelectronics exemplify distinct positioning archetypes. Texas Instruments leverages foundry partnerships to sustain volume supply of automotive-grade level shifters. NXP Semiconductors occupies a position anchored in multi-master arbitration IP for vehicle network gateways. STMicroelectronics represents the MEMS sensor hub convergence play, integrating I2C with environmental and motion sensing for smartphone and wearable OEMs.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| NXP Semiconductors |
| STMicroelectronics |
| Microchip Technology Inc. |
| Renesas Electronics Corporation |
| Infineon Technologies |
| Analog Devices, Inc. |
| ON Semiconductor Corporation |
| Broadcom Inc. |
| Others |
Supply & Pricing Matrix
300mm silicon-on-insulator wafer spot prices cascade through automotive-grade I2C transceiver production, compressing margins for high-speed devices while concentrating pricing power among substrate-integrated suppliers serving 48V battery management programs.
Pricing Analysis
Volume concentration in consumer-grade Fast Mode devices trades margin for scale, while Fast Mode Plus automotive qualification captures premium positioning through AEC-Q100 certification tiers. SOI substrate cost premiums are intensifying price erosion at the high-performance tier as foundry capacity tightens. Industrial automation buyers exhibit lowest price sensitivity due to real-time throughput mandates, whereas smartphone OEM procurement teams drive aggressive cost compression through consolidated MEMS hub sourcing.
Supply Chain Analysis
Photoresist and specialty substrate supply rests on Japanese and German chemical producers, while mixed-signal foundry capacity concentrates in Taiwan, South Korea, and China. 300mm SOI wafer fabrication, automotive-grade epoxy molding compounds, and MEMS sensor packaging equipment anchor critical input dependencies. Single-source vulnerability in multi-master arbitration IP licensing creates concentration risk for vehicle gateway suppliers. Distribution runs through authorized component distributors and direct foundry relationships, with Chinese smartphone OEMs accelerating captive semiconductor division procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
I2C bus market consolidation accelerates as SOI substrate integration investments force smaller mixed-signal houses into partnership or exit, leaving only scale players with automotive qualification capabilities.
For Market Incumbents: Deploy foundry partnership deepening to secure 300mm SOI wafer allocation for automotive-grade production. Anchor defensive positioning through AEC-Q100 certification maintenance and multi-master arbitration IP portfolio expansion. Counter emerging fabless specialists by controlling MEMS sensor hub reference design channels. For New Entrants and Emerging Players: EU Cyber Resilience Act hardware mandates in Germany and France open a window for cryptographic-authentication I2C controller development. Target industrial automation nodes specifying Fast Mode Plus throughput as the most penetrable segment. Pursue qualification partnerships with German automotive tier-1s as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mixed-signal specialists with existing automotive qualification in Japan and South Korea. Long-term viability hinges on substrate integration capabilities and foundry access agreements. Watch SOI wafer spot price stabilization as the inflection signal for margin recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| SOI Substrate Integration | Eliminates external level-shifter components for 48V mild-hybrid battery management systems. |
| Multi-Master Arbitration IP Licensing | Secures recurring revenue from vehicle gateway consolidation across powertrain and chassis domains. |
| MEMS Sensor Hub Convergence | Captures smartphone and wearable OEM consolidation behind unified I2C backplane architectures. |
| Automotive Qualification Investment | Unlocks premium positioning through AEC-Q100 certification for zonal E/E architecture deployment. |
| China Domestic Foundry Partnership | Reduces import dependency for state infrastructure OEM supply chains under MIIT certification protocols. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with automotive platform engineers, MEMS sensor procurement managers, mixed-signal design directors, and foundry account executives combined with bottom-up and top-down triangulation. Secondary validation drew from MIIT certification databases, KBA type approval registries, FCC EMC test filings, and SEMI silicon substrate shipment reports.
Granularity-level modeling operated at device type, data rate tier, and regional production cluster dimensions. Value outputs across the projection horizon reflect segment-specific volume assumptions and price trajectory modeling. CAGRs derive from historical shipment correlation with semiconductor capital expenditure cycles and automotive E/E architecture transition timelines. Forecast inputs incorporated foundry capacity expansion announcements and EU hardware security mandate implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for silicon-on-insulator substrate integration would alter the outlook. Forecasts reflect assumptions around automotive zonal architecture penetration rates and China domestic foundry yield maturation. Supply chain disruption from specialty substrate shortages or regulatory timeline shifts warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Ethernet Access Device Market