
 Gigabit Passive Optical Network (GPON) Chipset Market | 2026-2036
Gigabit Passive Optical Network (GPON) Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Gigabit Passive Optical Network (GPON) Chipset Market Foresight
Market Context
China's domestic semiconductor fabrication expansion is reconfiguring supply dynamics for GPON chipset sourcing across Asia. Broadcom leverages its merchant silicon portfolio to sustain design wins with Western telecom equipment vendors. Huawei Technologies anchors vertical integration from chipset design through optical line terminal assembly, controlling cost structures that competitors struggle to match. Marvell Technology specializes in high-density PON MAC architectures, differentiating through integration of packet processing and optical PHY layers.
Technical Definition and Structural Segments
A Gigabit Passive Optical Network chipset comprises the integrated circuits enabling point-to-multipoint fiber access topology, typically operating at downstream rates of 2.488 Gbps and upstream rates of 1.244 Gbps per ITU-T G.984 specifications, with newer XGS-PON variants doubling symmetric throughput to 9.953 Gbps. Optical Line Terminal chipsets dominate value capture given their centralized aggregation function and higher semiconductor content per port, while Optical Network Terminal chipsets compete on volume scale as subscriber premises installations multiply. The technology dimension shows WDM architectures gaining traction in metro aggregation backbones where DWDM overlays extend PON reach, though TDM remains the cost-optimized standard for mass-market FTTH deployments.
Regulatory Frame and Outlook
ITU-T standards bodies shape interoperability mandates that determine chipset certification requirements, while national regulators including the FCC in the United States and MIIT in China enforce spectrum allocation and electromagnetic compatibility rules that filter market access. The EU Green Deal and associated CSRD disclosures are pressuring network operators to document energy efficiency per port, shifting procurement criteria toward low-power chipset designs. Stakeholders must monitor standardization timelines for NG-PON2 and 50G-PON to calibrate R&D allocation against replacement cycle timing in operator infrastructure budgets.
Market Dynamics
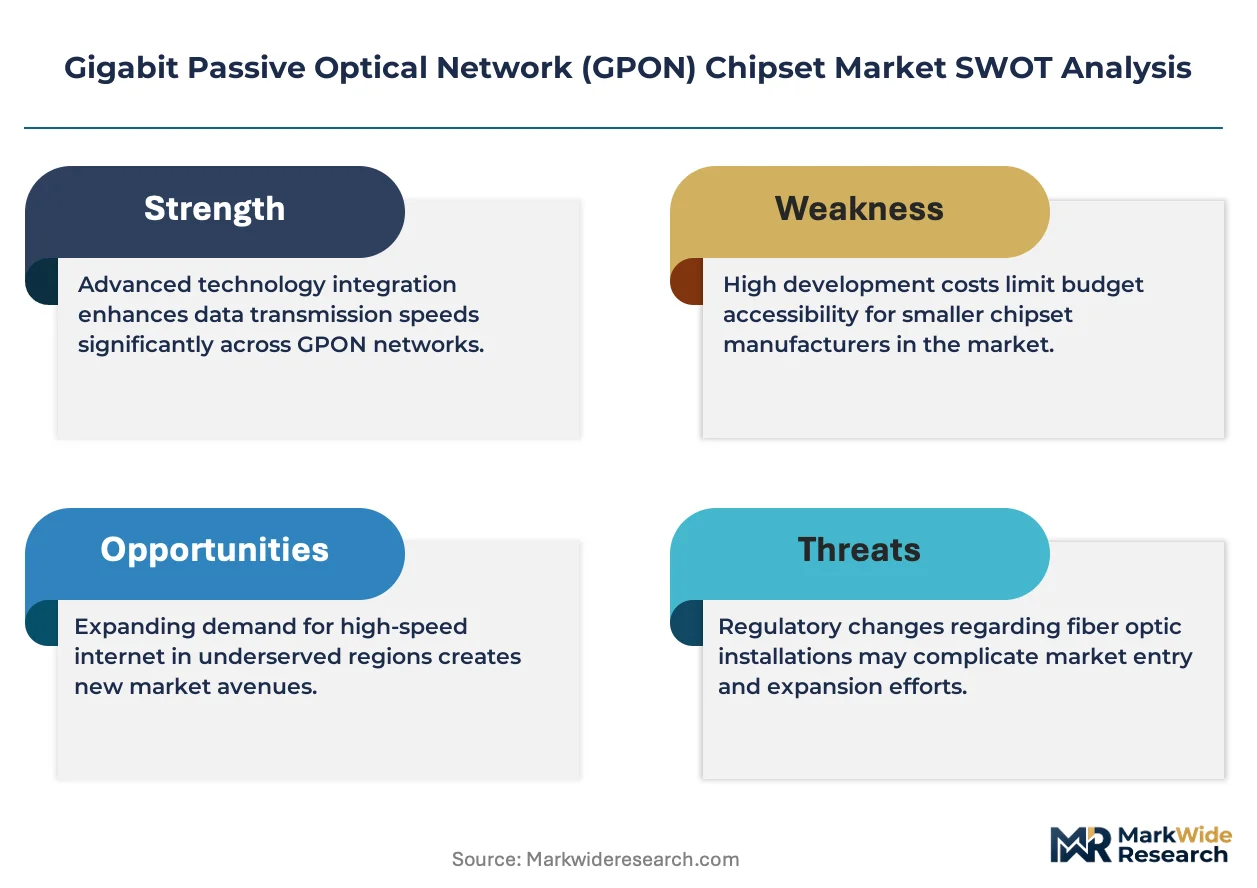
China's state-backed fiber infrastructure programs are compressing replacement cycles for GPON chipsets as operators race to upgrade from 2.5G to 10G symmetric XGS-PON architectures ahead of 50G-PON standardization.
Growth Catalysts
- ITU-T G.984 Evolution:Standards advancement toward XGS-PON and NG-PON2 is mandating higher-performance silicon, forcing chipset refreshes across installed base.
- China FTTH Deployment:State-directed broadband infrastructure investment under MIIT guidance continues at scale, anchoring global volume demand for OLT and ONU chipsets.
- EU Green Deal CSRD Pressure:Energy efficiency disclosure requirements are filtering procurement criteria toward low-power chipset designs with superior watts-per-port metrics.
Market Restraints
- Silicon Supply Concentration:Advanced node fabrication for high-density PON MACs concentrates among limited foundry capacity, creating allocation risk during demand surges.
- Copper Substitution Threat:DOCSIS 4.0 and advanced coaxial technologies from cable operators compete for multi-gigabit subscriber access in North American and European markets.
- Standardization Friction:Timing uncertainty around 50G-PON ITU-T finalization is freezing operator capex commitments and extending current-generation chipset lifecycles.
Strategic Opportunities
- Rural Broadband Subsidies:US BEAD program and similar national funds are unlocking greenfield fiber deployment in previously uneconomic subscriber density zones.
- Converged 5G Fronthaul:PON architectures are extending into mobile transport networks, creating chipset demand for unified fiber infrastructure serving fixed and wireless access.
- India BharatNet Expansion:Government-mandated rural fiberization under Department of Telecommunications targets is generating volume demand for cost-optimized ONU chipsets.
Industry Challenges
- Optical PHY Integration Complexity:Combining burst-mode receivers with digital signal processing in single-die architectures demands scarce mixed-signal design expertise.
- Multi-Generational Interoperability:Chipset vendors must maintain backward compatibility with legacy G-PON while supporting XGS-PON and pre-standard 50G-PON modes simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gigabit Passive Optical Network (GPON) Chipset Market |
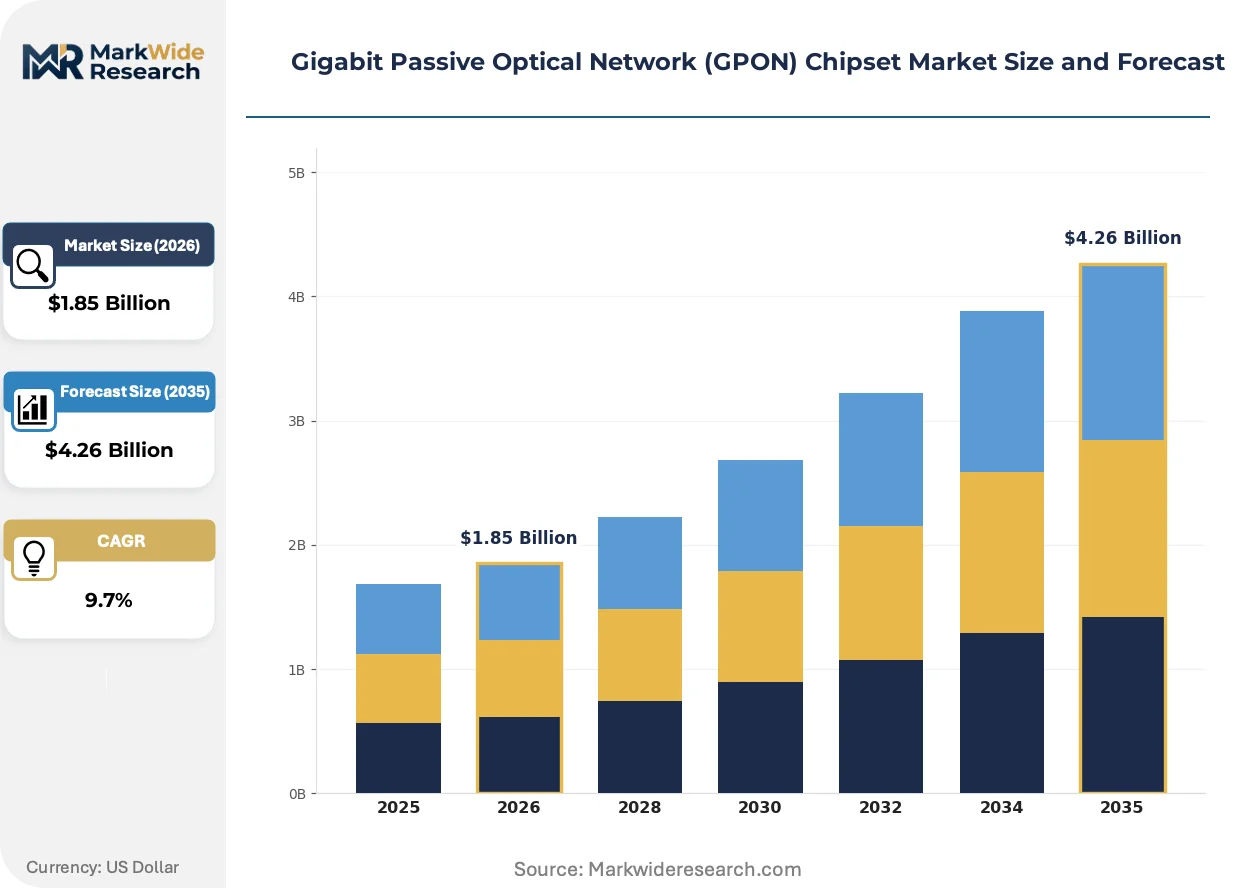
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Line Terminal, Optical Network Terminal, Network Controller, Transceiver, Amplifier Technology: WDM, TDM, DWDM, FTTH, FTTP, PON Application: Telecom Operators, ISPs, Enterprise Networks, Data Centers, Content Delivery Networks, Cloud Services End User: Telecommunication Equipment Manufacturers, Network Service Providers, System Integrators, Managed Service Providers |
| Companies Covered | Cisco Systems, Nokia Corporation, Huawei Technologies, Fujitsu, ZTE Corporation, Broadcom, ADTRAN, Marvell Technology, Calix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gigabit Passive Optical Network (GPON) Chipset Market Shifts & Advancements
Chipset architectures are converging toward higher integration levels as operators demand single-solution platforms spanning multiple PON generations, compressing vendor differentiation to software-defined feature activation.
Silicon photonics is migrating from discrete transceiver modules into co-packaged optical engines within PON MAC chipsets. Tier-1 equipment vendors in China and Japan are qualifying these integrated solutions for metro aggregation OLT line cards. This migration from separate optical subassemblies is reducing board space requirements and enabling 16-port density in single-slot chassis configurations.
CSRD disclosure mandates from the EU Green Deal are forcing chipset vendors to document embodied carbon and operational power metrics across product lifecycles. Equipment manufacturers sourcing for European operator deployments now require Environmental Product Declarations as standard tender documentation. This regulatory pressure is accelerating design prioritization of sleep-mode power states and dynamic voltage scaling in MAC architectures.
Chinese state-owned operators are consolidating procurement through centralized framework agreements, compressing vendor margins while demanding faster customization cycles. Equipment vendors are responding with reference design partnerships that pre-integrate chipsets from qualified suppliers, reducing qualification timelines for new OLT platforms. This procurement consolidation is most visible in tenders from China Telecom and China Unicom, where multi-year volume commitments now dominate supplier selection criteria.
Gigabit Passive Optical Network (GPON) Chipset Market Segmentation
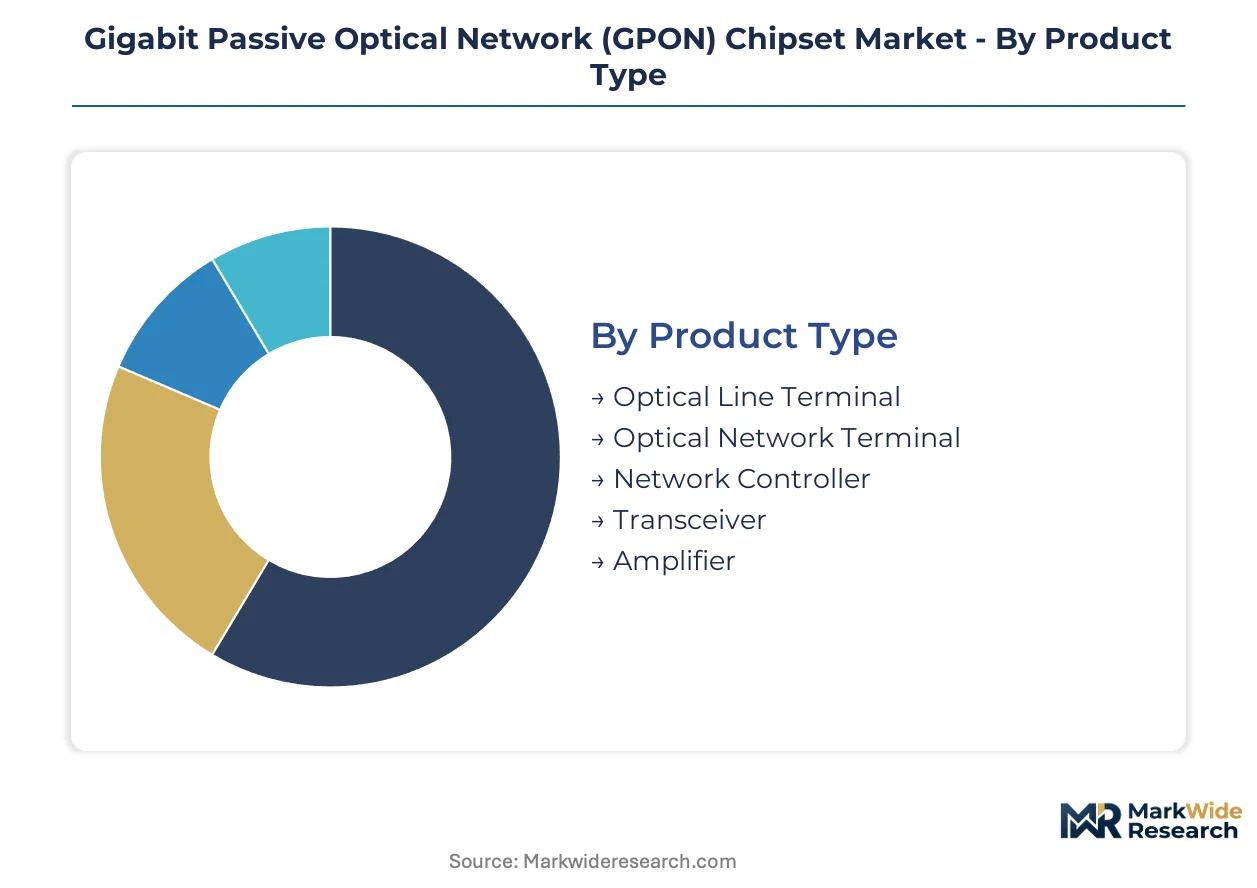
GPON chipset procurement patterns diverge sharply across deployment contexts, with after-sales service intensity varying from minimal for consumer premises equipment to extensive for carrier-grade optical line terminals requiring firmware lifecycle management and field engineering support. Equipment vendors calibrate inventory strategies and supplier qualification depth according to these service tier expectations, creating distinct commercial rhythms within each segment category.
Product Type:
After-sales service intensity peaks with Optical Line Terminal chipsets, where operators demand multi-year firmware update commitments and field failure analysis, while Optical Network Terminal chipsets operate on commodity replacement cycles with minimal vendor touch.
- Optical Line Terminal:Central office aggregation chipsets integrating PON MAC, packet processing, and optical PHY layers in high-port-density configurations. China Telecom and China Unicom tenders concentrate demand here, with procurement frameworks demanding five-year roadmap alignment from silicon vendors. By volume, Optical Network Terminal leads. By growth pace, Optical Line Terminal is ahead.
- Optical Network Terminal:Subscriber premises silicon optimized for cost-per-port metrics in residential FTTH deployments. Indian BharatNet and US BEAD-funded rural builds are absorbing millions of units annually, though margin compression from Chinese state-procurement consolidation limits vendor profitability.
- Network Controller:Traffic management silicon enabling bandwidth allocation across multiple PON branches. Demand concentrates in Japan's NTT East and NTT West metro aggregation expansions.
- Transceiver:Burst-mode optical modules converting electrical signals to 1490nm downstream and 1310nm upstream wavelengths. European operators under CSRD pressure are specifying low-power variants.
- Amplifier:Signal conditioning circuits extending PON reach beyond 20km standard distances. Deployment is sparse outside rural Australian and Canadian fiber overbuilds.
Cost tier separation between central office and premises silicon creates a bifurcated supply structure, with foundry allocation prioritizing high-margin OLT wafer starts during capacity constraints.
Technology:
Volume scale concentrates in TDM-based mass-market deployments, while technology leadership and pricing power cluster in wavelength-division variants serving metro aggregation backbones.
- WDM:Wavelength-division multiplexing architectures enabling multiple PON overlays on single fiber strands through coarse or dense channel spacing. NTT's 10G-EPON and XGS-PON convergence trials in Tokyo and Osaka are validating these chipsets for unified mobile fronthaul.
- TDM:Time-division multiplexing remains the cost-optimized foundation for ITU-T G.984-compliant mass-market FTTH, with Chinese operators deploying tens of millions of ports annually. MIIT-mandated gigabit city programs sustain this segment's volume dominance despite thinner silicon margins.
- DWDM:Dense wavelength-division overlays extending PON reach to 60km+ for rural aggregation. Trials are active in Germany's Telekom and France's Orange long-reach access networks.
- FTTH:Fiber-to-the-home-optimized silicon emphasizing low-power sleep modes and rapid burst-mode synchronization. US BEAD subsidy eligibility requirements are shaping procurement specifications.
- FTTP:Fiber-to-the-premises variants supporting multi-dwelling unit and commercial building architectures. Demand clusters in South Korean apartment complexes and Spanish urban renewal projects.
- PON:Generic passive optical network silicon maintaining backward compatibility across G-PON, XGS-PON, and pre-standard 50G-PON modes. Multi-generational interoperability mandates from ITU-T are forcing complex firmware architectures.
Application context determines technology selection more than raw performance metrics, with TDM commanding residential volume and WDM variants capturing enterprise and mobile backhaul premiums.
Application:
Customer type fragmentation spans asset-heavy national carriers with centralized procurement frameworks to lean cloud operators sourcing through merchant silicon channels.
- Telecom Operators:Incumbent carriers including Verizon, Deutsche Telekom, and BT Group deploying GPON as primary residential access infrastructure. Their centralized RFP processes demand multi-source silicon qualification and decade-long supply commitments.
- ISPs:Competitive broadband providers including Altice USA and Iliad building fiber overbuilds in cable-dominated markets. Their procurement favors merchant chipset ecosystems enabling rapid OLT platform swaps.
- Enterprise Networks:Campus and private fiber installations prioritizing deterministic latency and physical security over cost optimization. Financial services clusters in Singapore and Zurich are early adopters of encrypted PON variants.
- Data Centers:Hyperscale operators trialing PON for intra-campus connectivity and edge aggregation. Microsoft and Google pilot programs are validating power efficiency claims against active optical alternatives.
- Content Delivery Networks:Cache server interconnection requiring symmetric 10G throughput. Demand is nascent, concentrated in Akamai and Cloudflare edge expansion nodes.
- Cloud Services:AWS, Azure, and GCP evaluating PON for metro fiber access to distributed cloud regions. Procurement cycles remain elongated given internal silicon development priorities.
Telecom operators absorb the majority of OLT chipset volume, while cloud and CDN applications represent the steepest expansion trajectory despite smaller current bases.
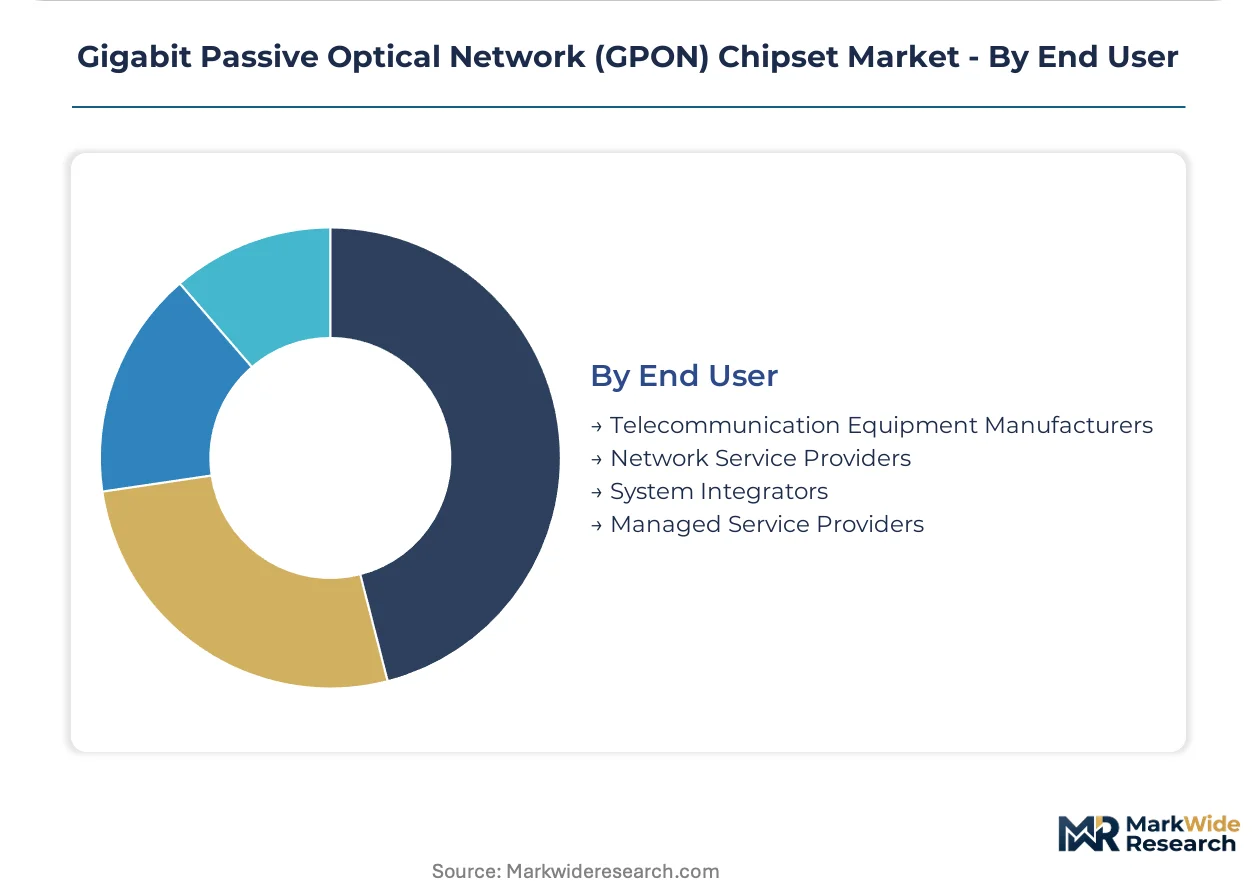
End User:
Supply chain position determines procurement sophistication, with equipment manufacturers demanding die-level customization and managed service providers accepting reference-design platforms.
- Telecommunication Equipment Manufacturers:Huawei, ZTE, Nokia, and Ericsson designing proprietary OLT line cards with captive or merchant silicon strategies. Their qualification timelines stretch 18-24 months, freezing chipset vendor selection early in platform development.
- Network Service Providers:Wholesale fiber operators including Crown Castle and Uniti leasing infrastructure to retail ISPs. Their procurement emphasizes interoperability certification across multiple equipment vendors.
- System Integrators:Regional deployment specialists bundling OLT installation with civil works. Indian and Indonesian market entrants favor turnkey chipset-plus-software packages reducing engineering overhead.
- Managed Service Providers:Outsourced network operators serving municipal and utility fiber builds. Their procurement is price-sensitive, accepting second-source merchant silicon to maintain margin on fixed-fee contracts.
Equipment manufacturers command the deepest vendor relationships, while managed service providers are gaining procurement influence as outsourced network operations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes GPON chipsets at volumes dwarfing all other markets, yet deployment patterns diverge sharply: Chinese operators prioritize centralized optical line terminals for state-directed fiberization, while US and European procurement emphasizes interoperability across multi-vendor ecosystems and energy disclosure compliance.
China
MIIT-mandated gigabit city programs and state-backed broadband infrastructure investment compress replacement cycles from 2.5G to XGS-PON architectures. The regulator enforces domestic semiconductor sourcing quotas that reconfigure supply dynamics for optical line terminal assembly. Shenzhen and Dongguan manufacturing clusters anchor vertical integration from chipset design through equipment production.
United States
Rural broadband subsidies through the BEAD program unlock greenfield fiber deployment in low-density subscriber zones. FCC spectrum allocation and electromagnetic compatibility rules filter market access for imported silicon. Equipment qualification timelines in Texas and California engineering centers stretch 18-24 months, freezing chipset vendor selection early in platform development.
Japan
NTT East and NTT West metro aggregation expansions drive demand for wavelength-division multiplexing chipsets serving unified mobile fronthaul. METI industrial policy supports domestic silicon photonics research co-packaged with PON MAC architectures. Tokyo and Osaka trial sites validate 10G-EPON and XGS-PON convergence for converged 5G transport networks.
Germany
Telekom and Orange long-reach access network trials activate dense wavelength-division overlays extending PON reach beyond 60 kilometers. EU Green Deal CSRD disclosure mandates pressure procurement criteria toward documented energy efficiency per port. Berlin and Munich equipment integration labs qualify low-power chipset designs for European operator tenders.
India
BharatNet rural fiberization targets under Department of Telecommunications guidance generate volume demand for cost-optimized optical network terminal chipsets. TRAI spectrum management frameworks shape electromagnetic compatibility certification requirements. Bengaluru and Hyderabad system integrators favor turnkey chipset-plus-software packages reducing engineering overhead for municipal builds.
Gigabit Passive Optical Network (GPON) Chipset Market Competitive Landscape
Capability concentration sits with vertically integrated equipment manufacturers commanding captive silicon strategies; scale advantage sits with merchant semiconductor vendors supplying multi-source qualification pipelines. The vendor base stratifies across three tiers: proprietary chipset designers serving captive equipment lines, merchant silicon specialists integrating packet processing with optical PHY layers, and fabless designers outsourcing fabrication to secure foundry allocation. Dominant competitive moves include reference design partnerships compressing qualification timelines and strategic pre-integration with qualified suppliers.
Within the vertically integrated tier, Huawei Technologies and ZTE Corporation occupy positions exemplifying state-backed infrastructure control from design through deployment. Among merchant silicon specialists, Broadcom and Marvell Technology sit within the ecosystem enabling rapid platform swaps for competitive broadband providers. Cisco Systems and Nokia Corporation anchor the equipment manufacturer archetype demanding multi-year supply commitments and roadmap alignment from silicon vendors.
| Leading Market Players |
|---|
| Cisco Systems |
| Nokia Corporation |
| Huawei Technologies |
| Fujitsu |
| ZTE Corporation |
| Broadcom |
| ADTRAN |
| Marvell Technology |
| Calix |
| Others |
Supply & Pricing Matrix
Single-source dependency on advanced-node foundry capacity for high-density PON MACs determines both pricing tier spreads and supply chain shape, with Chinese state-procurement consolidation compressing margins while Taiwan Semiconductor Manufacturing Company allocation bottlenecks create premium pricing for OLT silicon during demand surges.
Pricing Analysis
Geographic price spreads separate Chinese domestic tenders from Western multi-vendor deployments, with MIIT-mandated framework agreements driving cost-optimized ONU chipsets below merchant silicon premiums by volume scale. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service intensity, with European CSRD disclosure requirements adding compliance cost premiums. Price erosion runs through the ONU segment as BharatNet and BEAD-funded rural builds absorb millions of units annually. Managed service providers exhibit highest price sensitivity, while telecom operators with centralized procurement frameworks prioritize roadmap alignment over unit cost.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan, South Korea, and the United States for advanced-node PON MAC fabrication, with 300mm wafer supply tethered to TSMC, Samsung Foundry, and Intel Foundry Services capacity allocation. Photonic components including burst-mode receivers and 1490nm laser diodes rest on Japanese and Chinese component suppliers. Single-source vulnerability concentrates in TSMC's 7nm and 5nm nodes for high-density OLT silicon. Distribution runs through equipment manufacturer qualification pipelines, with 18-24 month vendor selection timelines freezing supply chain flexibility early in platform development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Chinese state-owned operators consolidating procurement through multi-year framework agreements, fragmenting vendor margins while demanding faster customization cycles that favor vertically integrated equipment manufacturers.
For Market Incumbents: Entrench position through captive silicon strategies controlling cost structures that merchant competitors cannot match, while deepening backward integration into optical PHY design to defend against Marvell and Broadcom integration moves. Prioritize five-year roadmap alignment with China Telecom and China Unicom tenders to lock out emerging merchant silicon entrants. Certification investment in ITU-T G.984 interoperability testing creates switching costs for operator procurement committees. For New Entrants and Emerging Players: Rural Indian broadband underpenetration offers white-space volume for cost-optimized ONU chipsets, with BharatNet municipal builds favoring turnkey chipset-plus-software packages reducing engineering overhead. US BEAD-funded low-density subscriber zones present second white-space target, with interoperability certification enabling multi-vendor equipment swaps. Go-to-market angle should emphasize merchant silicon ecosystems for competitive broadband providers seeking rapid OLT platform flexibility. For Investors and Strategic Acquirers: EU Green Deal CSRD disclosure mandates reshape the acquisition landscape toward low-power chipset designers with documented Environmental Product Declarations and sleep-mode power state architectures. Long-term viability over the projection horizon favors fabless designers with secured foundry allocation and multi-generational firmware expertise. Signal to watch is 50G-PON ITU-T standardization timing, which would trigger operator capex release and chipset refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Reference Design Partnership | Pre-integration with qualified suppliers compresses 18-24 month qualification timelines for China Telecom tenders. |
| Silicon Photonics Co-packaging | Migration from discrete transceivers enables 16-port density in single-slot OLT chassis for NTT deployments. |
| Multi-generational Firmware Architecture | Backward compatibility across G-PON, XGS-PON, and pre-standard 50G-PON modes satisfies ITU-T mandates. |
| Environmental Product Declaration | CSRD-compliant documentation unlocks European operator procurement criteria emphasizing watts-per-port metrics. |
| Turnkey Chipset-plus-Software Package | Reduces engineering overhead for Indian system integrators serving BharatNet municipal fiber builds. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with optical line terminal platform engineers, telecom procurement managers, foundry capacity planners, and regulatory affairs specialists at MIIT and FCC. Secondary validation drew from ITU-T G.984 standardization documents, SEC 10-K filings from merchant silicon vendors, MIIT broadband infrastructure program disclosures, and equipment manufacturer tender announcements. Bottom-up unit shipment estimates triangulated against top-down operator capex allocation models.
Calibration against historical replacement cycles and standardization timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application context, and end-user procurement sophistication. CAGRs were derived from operator deployment schedules and chipset refresh cadences, with inputs from silicon photonics adoption curves and CSRD disclosure compliance trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed vertically integrated equipment manufacturers or sudden TSMC capacity reallocation would shift outcomes. Cross-checking against MIIT gigabit city program budget disclosures and FCC BEAD fund release schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Global Wireless Gigabit Market