
 4G Smart Device Chip Market | 2026-2036
4G Smart Device Chip Market Size, Share, and Industry Trends Forecast 2026-2036
4G Smart Device Chip Market Analysis
Modular chipset bundling is hardening as the dominant procurement pattern among mid-tier device OEMs. Qualcomm leverages its integrated modem-application processor platforms to sustain design-win momentum across emerging market smartphone brands. MediaTek anchors volume production through turnkey reference designs that compress development cycles for budget handset makers. UNISOC competes aggressively on price while extending connectivity stacks into industrial IoT verticals previously served by narrowband specialists.
A 4G smart device chip is a semiconductor die or multi-die assembly that enables cellular communication over LTE, LTE-Advanced, or low-power variants such as LTE-M and NB-IoT, typically fabricated on 12-inch silicon wafers using 22nm to 7nm process nodes depending on performance tier and power envelope. Its primary purpose is to encode, modulate, and demodulate radio frequency signals while managing protocol stacks that allow smartphones, tablets, wearables, and IoT endpoints to attach to mobile operator networks. System on Chip configurations command the deepest margin pools because they consolidate baseband, application processing, and graphics functions onto single die, whereas Modem Chip specialists face commoditization pressure as integrated alternatives capture socket share. LTE-Advanced technology segments retain volume leadership in premium-tier handsets, while NB-IoT and LTE-M adoption accelerates in utility metering and asset tracking hardware where extended battery life outweighs bandwidth requirements.
FCC equipment authorization rules in the United States constrain modem firmware architectures by mandating specific emission masks and carrier aggregation behaviors that ripple backward into silicon design. ETSI harmonized standards across Europe, enforced through CE marking conformity assessment, shape interoperability testing burdens that favor vendors with established certification laboratories. China's MIIT radio transmission type approval and network access license requirements create a dual-track compliance pathway that filters out smaller fabless competitors lacking in-country regulatory affairs capacity. Stakeholders must monitor spectrum refarming timelines in major economies, as 4G band reallocation decisions will determine residual silicon demand curves and inventory valuation risks for distributors holding long-dated modem positions.
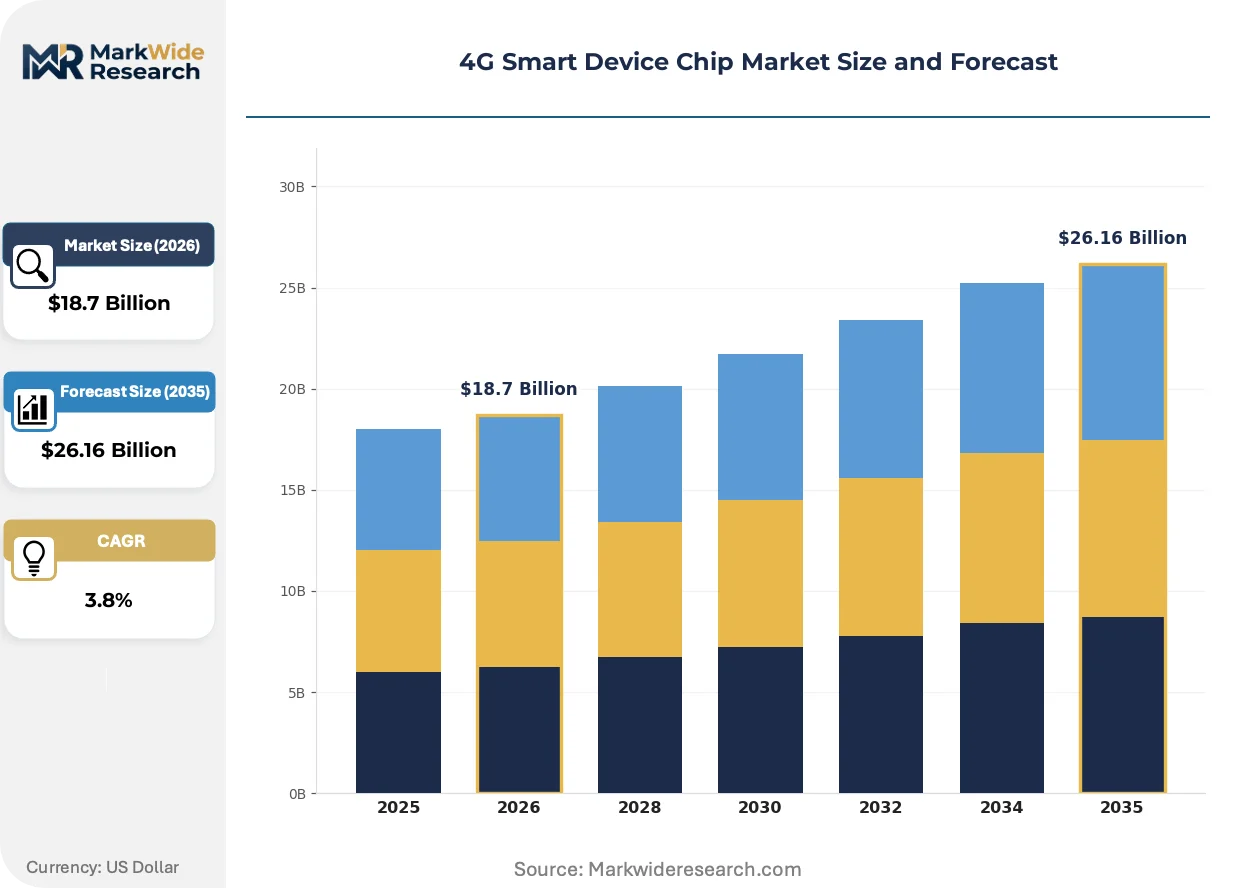
Market Dynamics
Modular chipset bundling is hardening as the dominant procurement pattern among mid-tier device OEMs, compressing development cycles while locking in platform dependencies that reshape competitive positioning across the LTE ecosystem.
Growth Catalysts
- LTE-M Protocol Expansion:Low-power wide-area connectivity requirements from utility metering and asset tracking hardware are pulling silicon volumes into industrial IoT verticals previously served by narrowband specialists.
- MIIT Spectrum Allocation:China's radio transmission type approval policies continue influencing modem architecture roadmaps, filtering out smaller fabless competitors lacking in-country regulatory affairs capacity.
- Southeast Asian Assembly Concentration:Chip-on-package configurations are absorbing rising volumes as regional electronics manufacturing services expand capacity for budget handset production.
Market Restraints
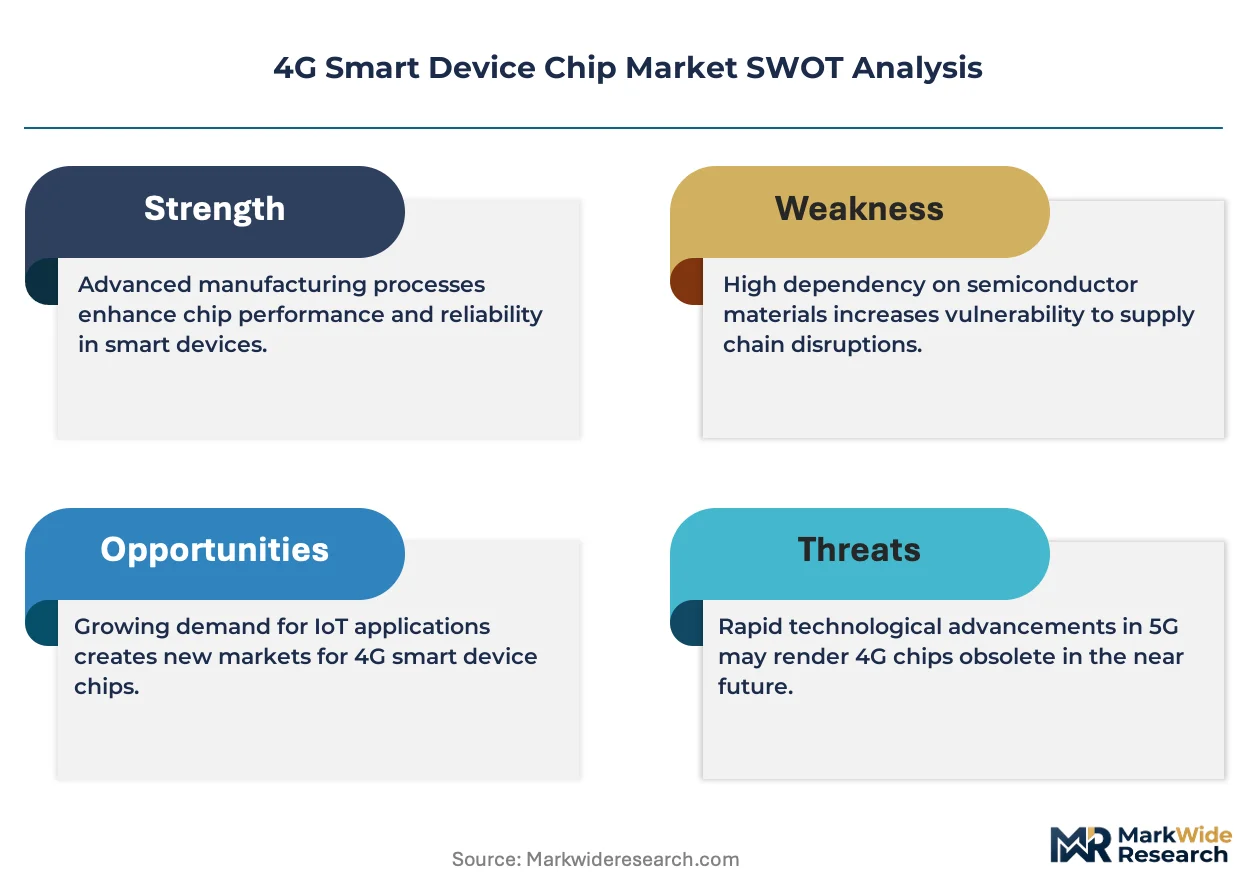
- Silicon Wafer Input Volatility:12-inch wafer pricing fluctuations constrain margin stability for fabless modem specialists competing against integrated platform vendors.
- Process Node Concentration:Advanced lithography capacity at leading foundries concentrates supply risk in Taiwan and South Korea, creating vulnerability for 7nm-tier performance segments.
- NB-IoT Bandwidth Limitation:Narrowband protocols face substitution pressure from emerging low-power alternatives in applications requiring intermittent high-data bursts.
Strategic Opportunities
- India PLI Scheme Incentive:Production-linked incentive frameworks for electronics manufacturing are drawing chipset packaging investments into Gujarat and Tamil Nadu corridors.
- Wearable Form Factor Convergence:Health-monitoring wearables are merging LTE-M connectivity with biometric sensors, opening socket opportunities in fitness and medical adjacencies.
- FCC Equipment Authorization Tailwind:Emission mask mandates for carrier aggregation behaviors are favoring vendors with established US certification laboratories and pre-validated firmware stacks.
Industry Challenges
- RF Engineering Talent Scarcity:Modem firmware optimization requires specialized expertise in carrier aggregation algorithms that outpaces university pipeline output.
- Dual-Track Certification Timelines:China's network access license requirements impose parallel compliance pathways that extend product launch schedules for new market entrants.
- Legacy Band Support Burden:Maintaining backward compatibility with refarmed spectrum allocations forces die area expansion that conflicts with cost-down imperatives in economy tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4G Smart Device Chip Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: System on Chip, Integrated Circuit, Application Specific Integrated Circuit, Modem Chip Technology: LTE, LTE-Advanced, LTE-M, NB-IoT End User: Smartphones, Tablets, Wearable Devices, IoT Devices Form Factor: Chip-on-Board, Package-on-Package, Ball Grid Array, Quad Flat No-lead |
| Companies Covered | Qualcomm, MediaTek, HiSilicon, Intel, Marvell, UNISOC, Samsung Electronics, Broadcom, Spreadtrum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4G Smart Device Chip Market Emerging Trajectories
Silicon integration trajectories and procurement model evolution are actively compressing the traditional boundary between modem specialists and application processor vendors across the LTE ecosystem.
System-on-Chip architectures are integrating baseband, application processing, and graphics functions onto single die configurations. Mid-tier smartphone OEMs are adopting these consolidated platforms at accelerating pace to compress bill-of-materials complexity. This integration is reshaping margin pools away from standalone modem suppliers toward vertically consolidated platform vendors.
ETSI harmonized standards enforced through CE marking conformity assessment are tightening interoperability testing burdens across European markets. Industrial IoT device manufacturers face expanded documentation requirements for LTE-M and NB-IoT equipment categories. German automotive telematics suppliers are responding by pre-certifying modules against anticipated MDR-aligned reliability benchmarks.
Turnkey reference design procurement is displacing discrete component sourcing among budget handset makers in emerging markets. MediaTek and UNISOC are capturing socket share by delivering complete hardware-software bundles that eliminate RF tuning cycles. This pattern is most visible in Southeast Asian and African markets where time-to-market compression outweighs customization requirements.
4G Smart Device Chip Market Segmentation
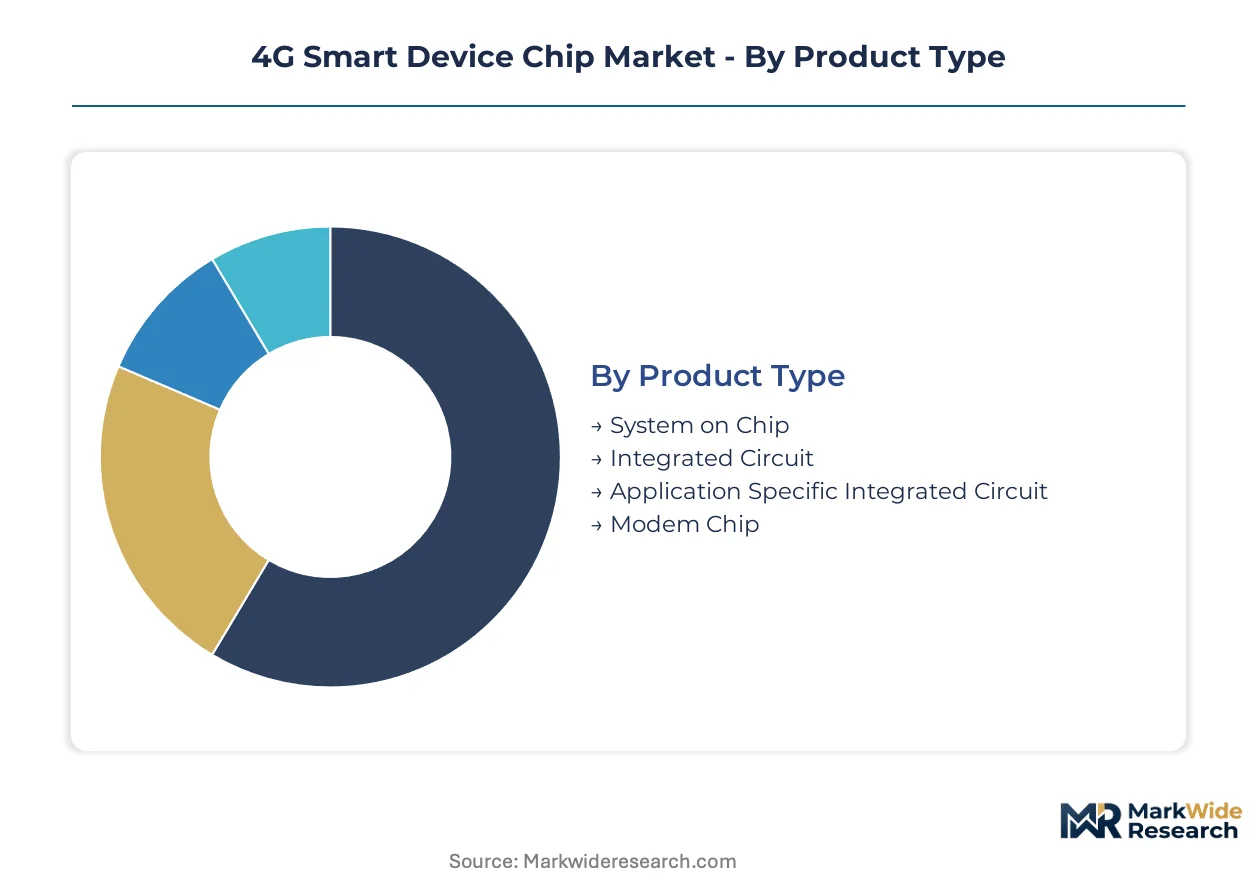
4G smart device chip segmentation reflects the tension between integration depth and specialized function. Procurement patterns diverge sharply across smartphone OEMs prioritizing bill-of-materials compression versus industrial IoT deployers optimizing for decade-long field lifespans.
Product Type:
Silicon integration depth determines margin capture and socket access across the LTE ecosystem.
- System on Chip:Consolidates baseband, application processing, and graphics functions onto single die configurations. Premium-tier smartphone OEMs in South Korea and Taiwan are standardizing on these platforms to eliminate discrete modem procurement and reduce RF tuning cycles.
- Modem Chip:Standalone baseband processors serving industrial IoT verticals where protocol flexibility outweighs integration economies. Utility metering deployments across Germany and Japan specify discrete modems to enable firmware customization for regional carrier aggregation profiles.
- Integrated Circuit:General-purpose logic devices supporting peripheral functions in cost-optimized handset designs.
- Application Specific Integrated Circuit:Custom-fabricated dies for automotive telematics modules requiring deterministic latency guarantees.
Mature deployment sits with Integrated Circuit configurations in economy handsets. Newer deployment is concentrated in System on Chip platforms gaining share across mid-tier smartphone portfolios.
Technology:
Protocol selection maps directly to power envelope requirements and data throughput specifications.
- LTE-Advanced:Carrier aggregation and MIMO antenna configurations delivering peak spectral efficiency. South Korean consumer electronics manufacturers specify these modems for flagship smartphone lines where video streaming bandwidth demands dominate procurement criteria.
- NB-IoT:Narrowband protocols optimized for 10-year battery life in stationary sensor applications. Water utility operators across Spain and Italy are deploying these chips in smart meter retrofits where penetration through concrete basements matters more than data rates.
- LTE:Baseline 4G connectivity serving cost-sensitive handset segments in emerging markets.
- LTE-M:Machine-type communications bridging mobility support with power-constrained operation.
Mature deployment sits with baseline LTE in replacement handset cycles. Newer deployment is concentrated in NB-IoT expanding fastest across European utility infrastructure mandates.
End User:
Application context dictates thermal constraints, certification burdens, and lifecycle expectations.
- Smartphones:High-volume socket opportunity with compressed product cycles and aggressive cost-down roadmaps. Indian and Indonesian OEMs are migrating from discrete modem-application processor pairings toward turnkey integrated platforms to accelerate certification timelines.
- IoT Devices:Fragmented demand spanning asset trackers, environmental sensors, and industrial controllers. German automotive suppliers specify automotive-grade LTE-M modules for fleet telematics where ETSI harmonized standards mandate extended temperature range validation.
- Tablets:Mid-tier connectivity requirements in education and enterprise verticals.
- Wearable Devices:Severe form factor constraints driving chip-on-package adoption for fitness and medical adjacencies.
Mature deployment sits with Tablets in institutional refresh cycles. Newer deployment is concentrated in Wearable Devices where health-monitoring convergence is opening socket opportunities.
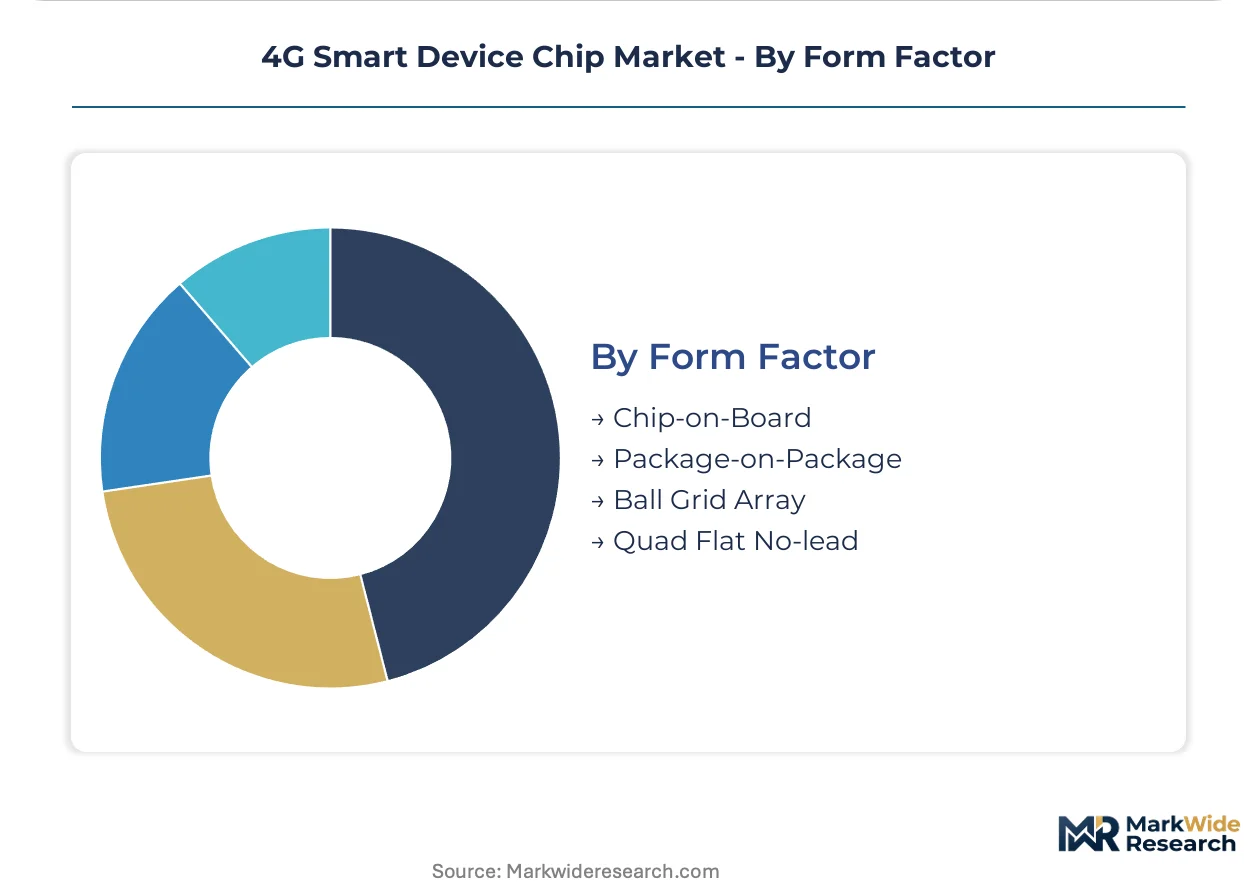
Form Factor:
Packaging technology selection traces assembly automation capabilities and thermal dissipation requirements.
- Package-on-Package:Stacked memory-processor configurations enabling minimal PCB footprint. Southeast Asian electronics manufacturing services are expanding capacity for these configurations to serve budget handset brands targeting African and South Asian distribution channels.
- Ball Grid Array:High pin-count interconnect supporting dense routing for application processor-modem combinations. Japanese industrial automation vendors specify BGA-packaged LTE-M chips for factory floor sensors where vibration resistance is non-negotiable.
- Chip-on-Board:Direct die attach for severe cost minimization in high-volume consumer applications.
- Quad Flat No-lead:Leadless packages optimizing thermal performance in space-constrained wearable designs.
Mature deployment sits with Chip-on-Board in economy-tier production. Newer deployment is concentrated in Package-on-Package configurations climbing fastest through Southeast Asian assembly hub expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Thailand are absorbing chip-on-package assembly capacity as Chinese manufacturers diversify production footprints amid tariff exposure.
China
MIIT spectrum allocation policies filter modem architecture roadmaps through dual-track certification pathways. Network access license requirements extend product launch schedules for entrants lacking in-country regulatory affairs capacity. Shenzhen and Dongguan electronics corridors concentrate turnkey reference design procurement for budget handset brands.
United States
FCC equipment authorization rules constrain modem firmware architectures through mandated emission masks and carrier aggregation behaviors. Carrier certification laboratories favor vendors with pre-validated firmware stacks and established US testing infrastructure. Austin and San Diego semiconductor clusters anchor baseband optimization engineering for premium-tier smartphone sockets.
South Korea
Flagship smartphone manufacturers specify LTE-Advanced modems with carrier aggregation and MIMO configurations for video streaming bandwidth demands. METI-aligned standards influence regional interoperability testing protocols for adjacent export markets. Seoul Capital Area fabs concentrate 7nm-tier lithography capacity for integrated modem-application processor platforms.
Germany
Automotive telematics suppliers pre-certify LTE-M modules against ETSI harmonized standards and anticipated MDR-aligned reliability benchmarks. CE marking conformity assessment shapes documentation requirements for industrial IoT equipment categories. Bavarian industrial automation corridors specify BGA-packaged chips for factory floor sensors requiring vibration resistance.
India
Production-linked incentive frameworks for electronics manufacturing draw chipset packaging investments into Gujarat and Tamil Nadu corridors. TRAI spectrum management influences carrier aggregation profile specifications for domestic network deployment. Bengaluru and Hyderabad design centers compress RF tuning cycles for mid-tier smartphone OEMs migrating toward integrated platforms.
4G Smart Device Chip Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across modem and system-on-chip segments. Market structure tilts toward consolidated platform vendors capturing margin pools through silicon integration depth. Three archetypes dominate: vertically integrated semiconductor conglomerates, fabless modem specialists, and turnkey reference design providers. Competitive moves concentrate on strategic partnerships for certification laboratory access and geographic expansion into PLI-incentivized assembly corridors.
Within the integrated platform tier, Qualcomm and MediaTek exemplify divergent approaches to socket capture. Qualcomm anchors premium-tier smartphone design wins through consolidated modem-application processor offerings. MediaTek occupies a position compressing development cycles for budget handset makers via turnkey hardware-software bundles. UNISOC sits within the price-aggressive specialist archetype, extending connectivity stacks into industrial IoT verticals.
| Leading Market Players |
|---|
| Qualcomm |
| MediaTek |
| HiSilicon |
| Intel |
| Marvell |
| UNISOC |
| Samsung Electronics |
| Broadcom |
| Spreadtrum |
| Others |
Supply Flow & Price Mechanics
12-inch silicon wafer pricing fluctuations cascade through modem chip procurement tiers, compressing margins for fabless specialists while integrated platform vendors absorb volatility through captive foundry relationships and volume scale.
Pricing Analysis
Cost-down pressure on economy-tier modem chips accelerates because turnkey reference designs from MediaTek and UNISOC eliminate RF tuning cycles for budget handset makers. Three-tier pricing structure across premium, standard, and economy levels separates Qualcomm's integrated platforms from discrete modem specialists and commodity LTE basebands. Price differentiation hinges on certification grade—FCC pre-validation and MIIT network access licenses command 15-25% premiums—and volume scale, with million-unit annual commitments unlocking steepest discounts. Indian and Indonesian OEMs exhibit highest price sensitivity, while German automotive telematics suppliers prioritize deterministic latency guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale smartphone manufacturer demand, while distribution runs through electronics manufacturing services for mid-tier device brands in Southeast Asian assembly corridors. Geographic supply concentration centers on Taiwan and South Korea for 7nm-tier lithography capacity, with China anchoring legacy 22-28nm production for cost-optimized segments. Raw material dependencies include 12-inch silicon wafers, high-purity photoresists, and rare-earth elements for RF front-end components. Single-source vulnerability at leading foundries creates exposure for advanced node allocation during capacity crunches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced lithography capacity constraints at Taiwan Semiconductor Manufacturing and Samsung Foundry prop pricing power for integrated platform vendors, while fabless modem specialists face margin compression from input cost volatility and socket share erosion.
For Market Incumbents: Anticipate socket share erosion from turnkey reference design providers by deepening backward integration into 12-inch wafer supply agreements and expanding captive certification laboratory capacity in Shenzhen and Austin. Lock in multi-year foundry allocation for 7nm-tier production to defend against supply crunches. Prioritize MIIT network access license pre-validation to compress dual-track certification timelines for Chinese market entry.
For New Entrants and Emerging Players: Electronics manufacturing services partnerships in Vietnam and Thailand offer the most penetrable channel for chip-on-package configurations serving African and South Asian distribution networks. Target industrial IoT verticals—utility metering and asset tracking—where discrete modem procurement persists and firmware customization requirements filter out integrated platform incumbents. Lead with LTE-M protocol stacks optimized for decade-long field lifespans rather than competing on smartphone socket share.
For Investors and Strategic Acquirers: MIIT spectrum refarming announcements are the leading indicator that residual 4G silicon demand curves will steepen or flatten. Frame long-term viability around decade-long IoT deployment windows rather than handset replacement cycles. Acquisition target archetype: fabless modem specialists with established ETSI harmonized standards certification and European automotive telematics design wins. Watch for FCC equipment authorization rule changes as inflection signals for US market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Long-term wafer supply agreements with TSMC or Samsung Foundry secure 7nm-tier allocation during crunches. |
| Certification Laboratory Expansion | In-house FCC and MIIT testing infrastructure compresses dual-track compliance timelines for new product launches. |
| Turnkey Reference Design Partnership | Hardware-software bundles with Southeast Asian electronics manufacturing services accelerate time-to-market for budget handset brands. |
| Industrial IoT Vertical Extension | LTE-M and NB-IoT protocol stacks penetrate utility metering and asset tracking segments previously served by narrowband specialists. |
| Automotive-Grade Qualification | AEC-Q100 validation and ETSI harmonized standards pre-certification unlock German telematics and Japanese factory floor sensor sockets. |
Methodological Framework
Independent corroboration across primary interviews with baseband optimization engineers, regulatory affairs directors at fabless modem specialists, smartphone OEM procurement leads, and industrial IoT device manufacturing heads underwrites the qualitative findings. Secondary validation draws from MIIT network access license filings, FCC equipment authorization databases, ETSI harmonized standards documentation, and SEC 10-K disclosures from listed semiconductor vendors. Bottom-up demand modeling across smartphone, IoT device, wearable, and tablet endpoints triangulates against top-down foundry capacity and wafer supply estimates.
Comparable-period anchoring to historical LTE deployment cycles and spectrum refarming timelines structures the projection horizon. The analytical framework models segmentation across product type—System on Chip, Modem Chip, Integrated Circuit, Application Specific Integrated Circuit—technology protocol, end-user application, and form factor packaging. CAGRs derive from unit volume trajectories weighted by average selling price evolution across premium, standard, and economy tiers. Industry-specific forecast inputs include MIIT spectrum allocation policy shifts and PLI scheme incentive uptake in Gujarat and Tamil Nadu corridors.
Several conditions sit outside the modeled scope, including unannounced foundry node transitions, geopolitical disruption to Taiwan Strait logistics, and abrupt 4G band reallocation decisions by major economies. Forecasts reflect assumptions about sustained IoT device deployment growth and stable regulatory certification pathways. Periodic stress-testing of base assumptions against foundry utilization rates and inventory valuation risks for distributors holding long-dated modem positions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Industrial Internet Chip Market