
 Global Wireless Gigabit Market | 2026-2036
Global Wireless Gigabit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Gigabit Market Foresight
Enterprise procurement of millimeter-wave backhaul equipment is consolidating around fewer vendor relationships as telecom operators and industrial automation firms narrow supplier lists. Qualcomm Technologies Inc. leverages its integrated modem-RF platform to anchor design wins across North American carrier trials. Broadcom Inc. competes through merchant silicon for enterprise access points. Intel Corporation sustains relevance via WiGig module partnerships with consumer electronics manufacturers.
Wireless gigabit denotes multi-gigabit-per-second data transmission through unlicensed millimeter-wave (57-71 GHz), sub-terahertz, or optical free-space links, typically achieving 1-7 Gbps at distances under 300 meters for indoor deployments. Its primary commercial purpose is eliminating fiber pulls in dense venues, smart factories, and campus networks where cable installation costs exceed radio hardware premiums. WiGig chipset supply dominates near-term volume, while millimeter-wave backhaul captures the dominant share of infrastructure margin pools. Enterprise deployment categories are expanding fastest as smart factory and campus network rollouts absorb systems previously sold into public venue configurations.
The FCC governs unlicensed 60 GHz and 6 GHz allocations in the United States, while ETSI harmonizes millimeter-wave rules across European member states and MIIT certifies radio transmission equipment in China; these frameworks determine which modulation schemes and power levels achieve market access. ISO and IEC performance benchmarks shape procurement specifications for defense and healthcare end users. Stakeholders must monitor spectrum reallocation proceedings in multiple jurisdictions to anticipate chipset architecture pivots.
Market Dynamics
Enterprise procurement of millimeter-wave backhaul equipment is consolidating around fewer vendor relationships as telecom operators and industrial automation firms narrow supplier lists. This concentration dynamic is compressing margins for second-tier chipset vendors while rewarding integrated platform providers with design win velocity.
Growth Catalysts
- FCC 6 GHz band expansion:The United States regulator's unlicensed spectrum allocation is accelerating chipset certification timelines for enterprise access point manufacturers.
- Smart factory corridors:South Korea's industrial automation clusters are absorbing millimeter-wave backhaul systems for machine-to-machine communication at sub-300-meter distances.
- Optical free-space convergence:Hybrid radio-optical links are eliminating fiber pulls in dense venues where cable installation costs exceed radio hardware premiums.
Market Restraints
- Gallium nitride substrate costs:Millimeter-wave power amplifier fabrication depends on specialized semiconductor materials with volatile supply chains concentrated in East Asian foundries.
- Line-of-sight propagation limits:60 GHz signal attenuation from atmospheric absorption and physical obstructions constrains deployment architecture in urban environments.
- MIIT certification timelines:China's radio transmission equipment approval process creates market access friction for foreign chipset vendors seeking campus network contracts.
Strategic Opportunities
- India's smart city mandates:The country's urban infrastructure digitization programs are creating procurement channels for unlicensed spectrum backhaul in municipal networks.
- Sub-terahertz research corridors:Germany's industrial research clusters are piloting 140 GHz links for intra-factory communication beyond WiGig capacity.
- CE marking harmonization:ETSI's millimeter-wave rule convergence across European member states is reducing SKU fragmentation for access point manufacturers.
Industry Challenges
- RF front-end engineering scarcity:Millimeter-wave antenna design and beamforming algorithm development require specialized talent pools concentrated at a handful of research institutions.
- Legacy Ethernet integration:Enterprise IT departments face configuration complexity when bridging 802.11ad/ay systems with existing copper infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Gigabit Market |
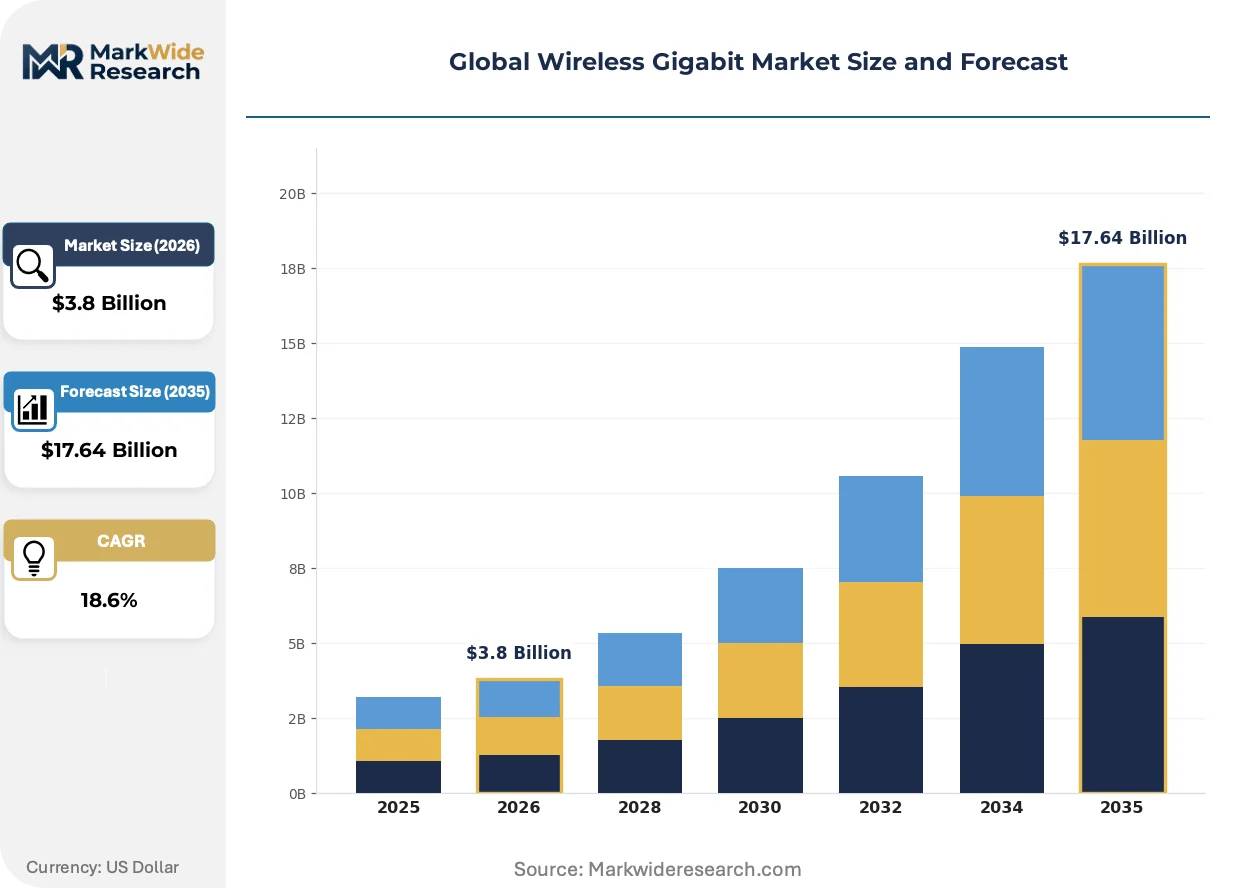
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: WiGig, Li-Fi, 5G NR, Millimeter Wave, Ultra-Wideband, Free Space Optics Application: Virtual Reality, Augmented Reality, High-Definition Streaming, Smart Factories, Autonomous Drones, Digital Signage Deployment: Indoor, Outdoor, Enterprise, Public Venues, Smart City Infrastructure, Campus Networks End User: Telecom Operators, Consumer Electronics Manufacturers, Industrial Automation Firms, Healthcare Providers, Educational Institutions, Defense Agencies |
| Companies Covered | Qualcomm Technologies Inc., Intel Corporation, Broadcom Inc., Peraso Technologies Inc., Sivers Semiconductors AB, STMicroelectronics, Tensorcom Inc., Cisco Systems Inc., Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Gigabit Market Shifts & Advancements
Silicon architecture decisions are reshaping competitive positioning as integrated modem-RF platforms displace discrete component stacks. Vendors are racing to anchor design wins through certification velocity and reference design completeness rather than raw performance benchmarks.
Beamforming antenna arrays are integrating phased-array silicon with embedded calibration engines to reduce installation complexity. Smart factory operators in South Korea and China are adopting these self-optimizing systems to minimize RF engineering deployment costs. The technology is integrating previously separate beam management and power amplification functions into single-chip solutions that compress bill-of-materials overhead.
ETSI's harmonized millimeter-wave framework is eliminating national derogations that previously forced multi-SKU strategies across European member states. Industrial access point manufacturers are consolidating product lines around unified radio designs that satisfy CE marking requirements from Lisbon to Tallinn. German and French campus network deployments are responding with accelerated procurement cycles as regulatory uncertainty diminishes.
Enterprise buyers are consolidating vendor relationships around integrated platform providers capable of spanning access point, backhaul, and management software layers. Systems integrators previously aggregating best-of-breed components are ceding ground to turnkey suppliers in North American carrier trials. This concentration is most visible in China's state-affiliated campus network deployments where single-source accountability reduces procurement friction.
Global Wireless Gigabit Market Segmentation
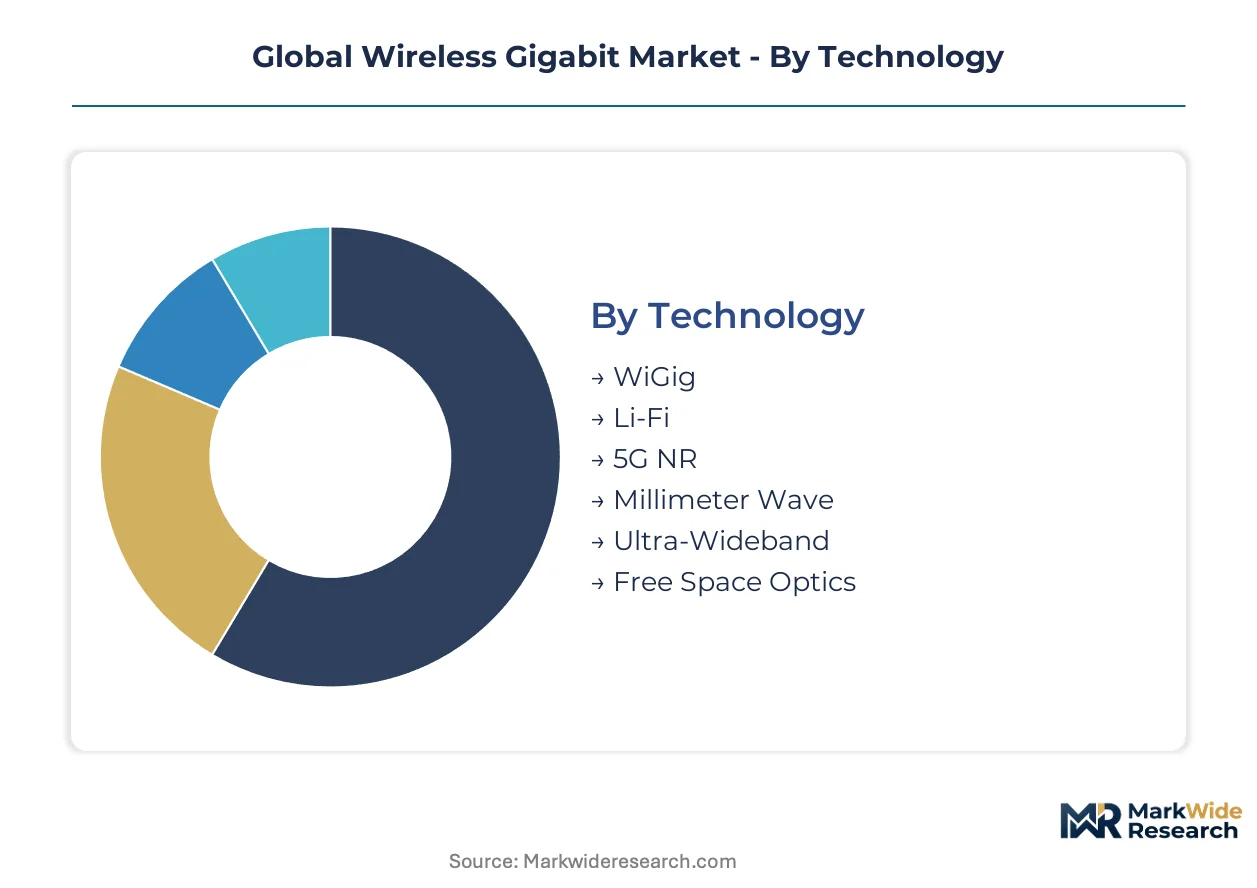
Wireless gigabit technology fragments across multiple transmission modalities and deployment contexts. Each segment carries distinct margin profiles, certification requirements, and vendor concentration patterns that shape procurement decisions.
Technology:
WiGig dominates near-term volume shipments while millimeter-wave backhaul commands infrastructure margin pools.
- WiGig:802.11ad/ay chipsets deliver 1-7 Gbps over 57-71 GHz unlicensed spectrum. Qualcomm anchors design wins across North American carrier trials for indoor enterprise access points.
- Millimeter Wave:E-band and V-band radios achieve multi-gigabit backhaul at sub-300-meter distances. South Korea's smart factory corridors absorb these systems for machine-to-machine communication where fiber installation costs exceed hardware premiums.
- Li-Fi:Visible light communication using LED modulation for secure, interference-free transmission in electromagnetic-sensitive environments.
- 5G NR:3GPP-standardized millimeter-wave integration with cellular core networks for operator-managed enterprise services.
- Ultra-Wideband:Short-range precision positioning and data transmission in industrial automation settings.
- Free Space Optics:Laser-based links eliminating fiber pulls in dense urban venues with strict line-of-sight requirements.
Today's leader: Millimeter Wave. Tomorrow's challenger: Free Space Optics.
Application:
Enterprise and industrial use cases are displacing consumer-facing configurations as primary revenue contributors.
- Smart Factories:Real-time machine vision and robotic coordination demand sub-millisecond latency. China's campus network deployments prioritize these industrial automation clusters for 802.11ay infrastructure.
- Virtual Reality:Untethered VR headsets require sustained multi-gigabit throughput to edge compute nodes. South Korean electronics manufacturers drive chipset certification timelines for consumer hardware integration.
- Augmented Reality:Enterprise AR maintenance systems utilize millimeter-wave hotspots for warehouse and field service environments.
- High-Definition Streaming:Venue-based 8K distribution systems in stadiums and conference centers.
- Autonomous Drones:Command-and-control links requiring high-bandwidth, low-latency connectivity for beyond-visual-line-of-sight operations.
- Digital Signage:Retail and transit displays with centralized content management over wireless backhaul.
Smart Factories capture dominant procurement volume. Autonomous Drones show steepest expansion trajectory among emerging categories.
Deployment:
Indoor configurations retain volume leadership while outdoor infrastructure commands premium pricing.
- Enterprise:Campus-wide networks spanning office, manufacturing, and logistics facilities. Germany's industrial research clusters pilot 140 GHz sub-terahertz links for intra-factory communication.
- Indoor:Dense-venue hotspots in convention centers and transportation hubs. FCC 6 GHz band expansion accelerates access point certification for US installations.
- Outdoor:Street-level small cell backhaul and municipal network extensions.
- Public Venues:Stadiums, airports, and exhibition halls with concentrated user density.
- Smart City Infrastructure:India's urban digitization programs create procurement channels for unlicensed spectrum municipal networks.
- Campus Networks:University and corporate environments with unified wireless-wireline integration.
Enterprise deployment absorbs systems previously sold into public venue configurations. Campus Networks gain share fastest among institutional buyers.
End User:
Procurement authority is consolidating around integrated platform providers capable of spanning hardware and software layers.
- Industrial Automation Firms:Machine builders and system integrators specifying millimeter-wave for robotic coordination. These buyers narrow supplier lists to vendors with complete modem-RF platforms.
- Telecom Operators:Carriers trialing fixed wireless access and enterprise private networks. North American operators favor turnkey suppliers over best-of-breed component aggregators.
- Consumer Electronics Manufacturers:Laptop and peripheral vendors integrating WiGig modules for docking and display extension.
- Healthcare Providers:Medical imaging and telepresence systems requiring high-bandwidth, low-interference connectivity.
- Educational Institutions:Universities deploying campus-wide infrastructure for research and instructional technology.
- Defense Agencies:Secure, spectrum-resilient communication systems with ISO and IEC performance benchmarks shaping procurement specifications.
Industrial Automation Firms lead current demand concentration. Defense Agencies represent the most stringent certification pathway for vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's smart factory corridors absorb millimeter-wave systems at sub-300-meter distances, while China's campus network deployments prioritize 802.11ay infrastructure for industrial automation clusters.
United States
Enterprise access point manufacturers accelerate chipset certification timelines following the FCC's 6 GHz band expansion. The regulator's unlicensed spectrum allocation enables dense-venue deployments in convention centers and transportation hubs. North American carrier trials favor turnkey suppliers over best-of-breed component aggregators in major metropolitan markets.
Germany
Industrial research clusters pilot 140 GHz sub-terahertz links for intra-factory communication beyond WiGig capacity. ETSI's harmonized millimeter-wave framework eliminates national derogations that previously forced multi-SKU strategies. Campus network deployments in Munich and Stuttgart respond with accelerated procurement cycles as regulatory uncertainty diminishes.
China
State-affiliated campus network deployments concentrate procurement authority around single-source vendors to reduce friction. MIIT certification timelines create market access friction for foreign chipset vendors seeking contracts in Beijing and Shanghai. Yangtze River Delta manufacturing hubs absorb systems previously sold into public venue configurations.
South Korea
Electronics manufacturers drive chipset certification timelines for consumer hardware integration in untethered VR headsets. Smart factory corridors in Gyeonggi Province deploy millimeter-wave backhaul for machine-to-machine communication. The Seoul Capital Area anchors demand concentration for multi-gigabit-per-second indoor enterprise access points.
Japan
METI coordinates unlicensed spectrum allocations that mirror FCC and ETSI frameworks to accelerate chipset architecture pivots. Industrial automation firms in the Chubu region narrow supplier lists to vendors with complete modem-RF platforms. Osaka-based system integrators specify millimeter-wave for robotic coordination in precision manufacturing environments.
Global Wireless Gigabit Market Competitive Landscape
United States producers anchor one tier; East Asian specialists hold integrated platform advantages in certification velocity. The vendor base compresses around fewer relationships as telecom operators and industrial automation firms narrow supplier lists. Three archetypes dominate: integrated modem-RF platform providers, merchant silicon specialists, and module partnership vendors. Design win velocity and reference design completeness now outweigh raw performance benchmarks as competitive levers.
Within the integrated platform tier, Qualcomm Technologies Inc. and Intel Corporation exemplify archetypes that span hardware and software layers. Broadcom Inc. occupies a position among merchant silicon competitors supplying enterprise access point manufacturers. These three anchors represent the concentration dynamic compressing margins for second-tier chipset vendors while rewarding certification velocity.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Intel Corporation |
| Broadcom Inc. |
| Peraso Technologies Inc. |
| Sivers Semiconductors AB |
| STMicroelectronics |
| Tensorcom Inc. |
| Cisco Systems Inc. |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Certification tier divergence between FCC-approved and MIIT-pending chipset architectures manifests in both pricing power and supply chain configurations. Premium-tier vendors command hardware premiums through accelerated regulatory velocity while second-tier suppliers absorb margin compression from extended approval timelines.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for millimeter-wave power amplifiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and beamforming algorithm sophistication. Price erosion runs through economy-tier WiGig modules as merchant silicon vendors consolidate design wins. Industrial automation firms show least price sensitivity due to fiber-pull avoidance economics, while consumer electronics manufacturers face acute margin pressure.
Supply Chain Analysis
Freight cost volatility from East Asian foundries to North American assembly plants is compressing landed cost predictability for gallium nitride substrates. Supply concentrates in Taiwan, South Korea, and China for phased-array silicon fabrication. Raw material dependencies span gallium nitride wafers, advanced packaging substrates, and precision RF connectors. Single-source vulnerability in GaN substrate supply creates procurement risk. Distribution runs through direct OEM relationships and tier-one systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FCC 6 GHz band expansion and ETSI harmonization milestones accelerate procurement cycles beyond underlying demand growth.
For Market Incumbents: Cement platform stickiness through backward integration into beamforming calibration engines and captive gallium nitride sourcing. Defend against merchant silicon encroachment by anchoring reference design completeness for smart factory deployments. Prioritize certification velocity in China's MIIT pipeline to preserve campus network access.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in enterprise access points offers white-space entry for sub-terahertz specialists targeting Germany's industrial research corridors. India's smart city mandates present the most penetrable geography for unlicensed spectrum backhaul newcomers. Pursue channel partnerships with systems integrators over direct carrier trials.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated modem-RF platform providers possessing both FCC and ETSI certification momentum. Long-term viability favors vendors with software-defined beam management capabilities and recurring management software revenue. Watch for MIIT approval acceleration as inflection signal for foreign vendor market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Qualcomm's modem-RF consolidation reduces bill-of-materials for carrier trials. |
| Regulatory Certification Investment | ETSI harmonization eliminates multi-SKU requirements across Lisbon to Tallinn. |
| Backward Integration | GaN substrate sourcing secures supply against East Asian foundry concentration. |
| Geographic Expansion | India's smart city mandates create municipal procurement channels. |
| Strategic Partnership | Beamforming algorithm licensing bridges RF engineering talent scarcity. |
Research Methodology
Multiple input streams — chipset vendor technical disclosures, carrier procurement documentation, and regulatory filing databases — were reconciled against secondary validation. Primary interviews spanned RF engineering directors at industrial automation firms, enterprise IT procurement officers, and regulatory affairs leads at semiconductor manufacturers. Secondary sources included FCC equipment authorization databases, ETSI harmonization standards, MIIT radio transmission approvals, and SEC supplier disclosure filings. Bottom-up volume estimates triangulated against top-down infrastructure spending projections.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed transmission modality, deployment context, end-user archetype, and regional regulatory cluster. CAGRs derived from slope-intercept modeling of infrastructure deployment trajectories and chipset shipment volumes. Forecast inputs incorporated spectrum reallocation proceedings and smart factory automation adoption curves.
Caveats apply where MIIT certification delays, gallium nitride supply disruptions, or beamforming talent scarcity could materially shift the outlook. Forecasts reflect documented assumptions about regulatory velocity and enterprise procurement consolidation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
IPC Soc Chip Market