
 5G CPE Chip Market | 2026-2036
5G CPE Chip Market Size, Share, and Industry Trends Forecast 2026-2036
5G CPE Chip Market Insights
Subscription-based firmware management is hardening into a core revenue layer alongside silicon sales, as carriers lock in multi-year service contracts for over-the-air feature activation. Qualcomm Incorporated leverages its Snapdragon X-series modem-RF integration to dominate premium tier placements with North American carriers. MediaTek Inc. competes aggressively on cost-optimized sub-6 GHz platforms for emerging market ISPs. Samsung Electronics anchors its position through captive demand from its network infrastructure division and in-house foundry supply.
A 5G CPE chip is a system-on-chip or discrete modem processor that encodes and decodes 5G NR waveforms, typically fabricated on 7nm or smaller process nodes, to enable wireline-replacement broadband in customer premises equipment. These devices translate cellular signals into Wi-Fi or Ethernet for residential, enterprise, and industrial sites lacking fiber infrastructure. Gateway deployments command the deepest margin pools where edge routing and security functions merge with modem duties. Sub-6 GHz technology sustains volume leadership due to superior building penetration and lower infrastructure cost versus mmWave. Residential end users generate the largest absolute unit demand as fixed wireless access displaces DSL and cable in suburban markets.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct RF emission and spectrum efficiency standards that dictate modem architecture and certification timelines. REACH and RoHS compliance in the European Union further constrain substrate and packaging material choices for chips sold into that market. Stakeholders must monitor spectrum reallocation proceedings and foundry node transitions as the primary variables affecting product roadmaps and geographic market entry sequencing.
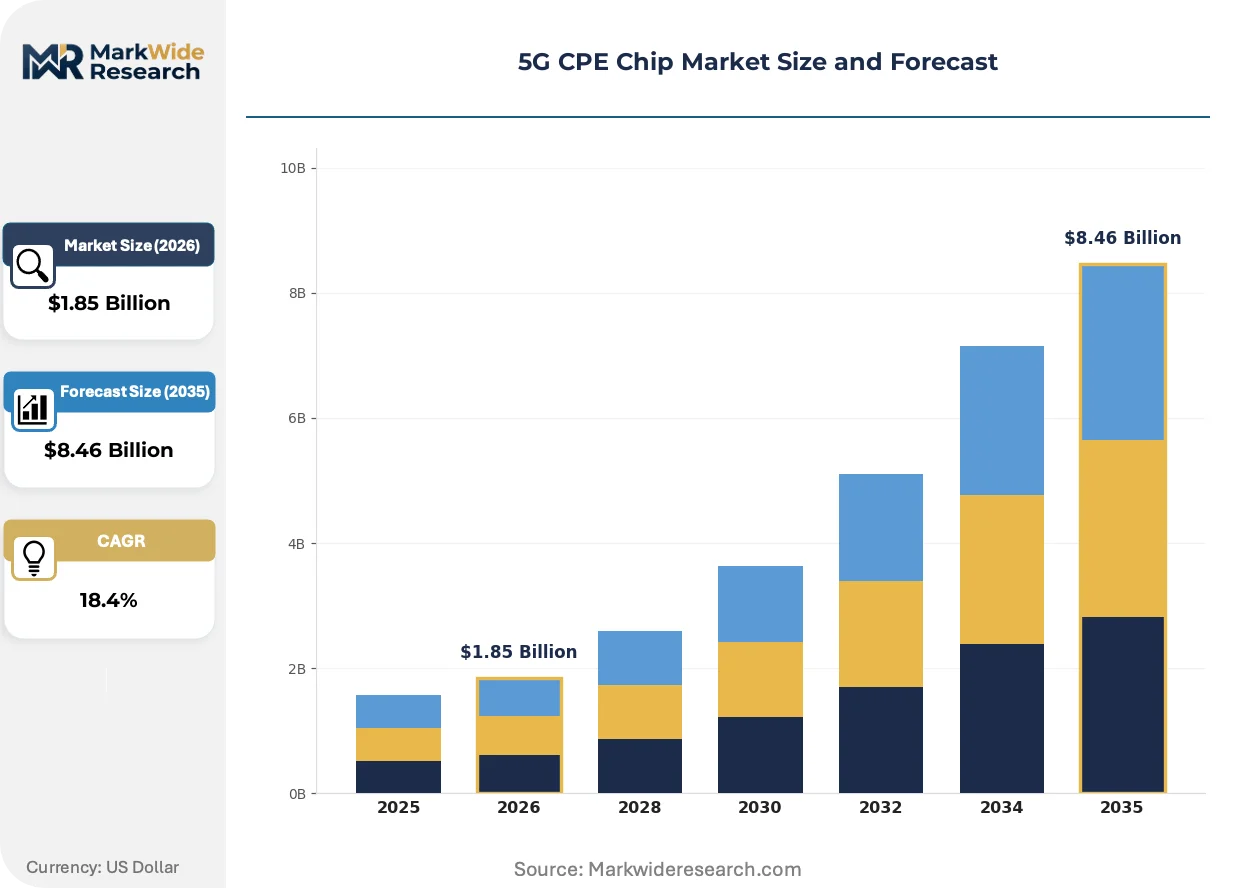
Market Dynamics
Fixed wireless access substitution is compressing wireline infrastructure timelines, forcing chip vendors to integrate routing and security functions directly into modem silicon to capture gateway margin pools.
Growth Catalysts
- MIIT spectrum allocation:China's 5G mid-band refarming accelerates sub-6 GHz CPE deployment across tier-2 cities lacking fiber backhaul.
- Dual carbon goals:Beijing's emissions mandates favor wireless broadband over copper trenching, reshaping domestic procurement specifications.
- Semiconductor cluster concentration:Foundry capacity in Shanghai, Shenzhen, and Hsinchu anchors integrated modem production for cost-optimized platforms.
Market Restraints
- Advanced node supply concentration:Taiwan-based foundries control 7nm and smaller production, creating geographic single-point vulnerability.
- mmWave infrastructure economics:Dense small-cell requirements limit carrier willingness to fund high-frequency fixed wireless outside dense urban cores.
- REACH substrate constraints:EU material restrictions on lead-free packaging raise certification costs for chips entering European distribution channels.
Strategic Opportunities
- Industrial IoT gateways:Manufacturing sites in Germany's Ruhr region and Japan's Kansai corridor seek private 5G networks with on-premise CPE.
- Subscription firmware monetization:Carriers in South Korea bundle over-the-air feature activation into multi-year service contracts.
- Rural broadband mandates:USDA Rural Utilities Service loans in the United States subsidize fixed wireless equipment for underserved census tracts.
Industry Challenges
- RF systems integration talent:Modem-RF co-design expertise concentrates in San Diego, Seoul, and Helsinki, constraining vendor hiring pipelines.
- Multi-regional certification timelines:FCC, ETSI, and MIIT testing sequences add nine to fourteen months to product launch schedules.
- Legacy DSL interworking:Hybrid CPE supporting copper fallback requires dual PHY integration that complicates software stack maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G CPE Chip Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Modem, Gateway, Combined Device End User: Residential, Commercial, Industrial, Telecommunications Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Sub-6 GHz, mmWave, OFDM, Massive MIMO |
| Companies Covered | Qualcomm Incorporated, MediaTek Inc., Samsung Electronics, Huawei Technologies, Broadcom Inc., NXP Semiconductors, Marvell Technology, Infineon Technologies, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G CPE Chip Market Trends and Innovations
Silicon vendors are compressing discrete component counts through die-stacking and advanced packaging, collapsing the traditional boundary between modem baseband and RF front-end.
Integrated modem-RF system-on-chip designs are rewriting the cost structure of residential gateway production. Tier-1 carriers in the United States and Japan now specify single-chip solutions for sub-6 GHz CPE to reduce bill-of-materials complexity. This integration is rewriting supplier power dynamics, favoring vendors with captive RF filter and power amplifier technologies.
ETSI's updated spectrum efficiency standards for the 3.5 GHz band are forcing architectural revisions in European-bound silicon. The regulations mandate tighter adjacent channel leakage limits, compelling vendors to add digital pre-distortion blocks that consume additional die area. Premium-tier gateway manufacturers in Germany and France absorb these costs through higher average selling prices, while budget ISPs delay certification to avoid margin compression.
Carrier procurement teams are consolidating vendor lists and demanding multi-year firmware roadmaps as contract prerequisites. This behavior concentrates design wins among silicon vendors with established carrier relationships and field engineering presence. The shift is most visible in North American markets, where Verizon and T-Mobile have reduced qualified modem suppliers from six to three over the past eighteen months.
5G CPE Chip Market Segmentation
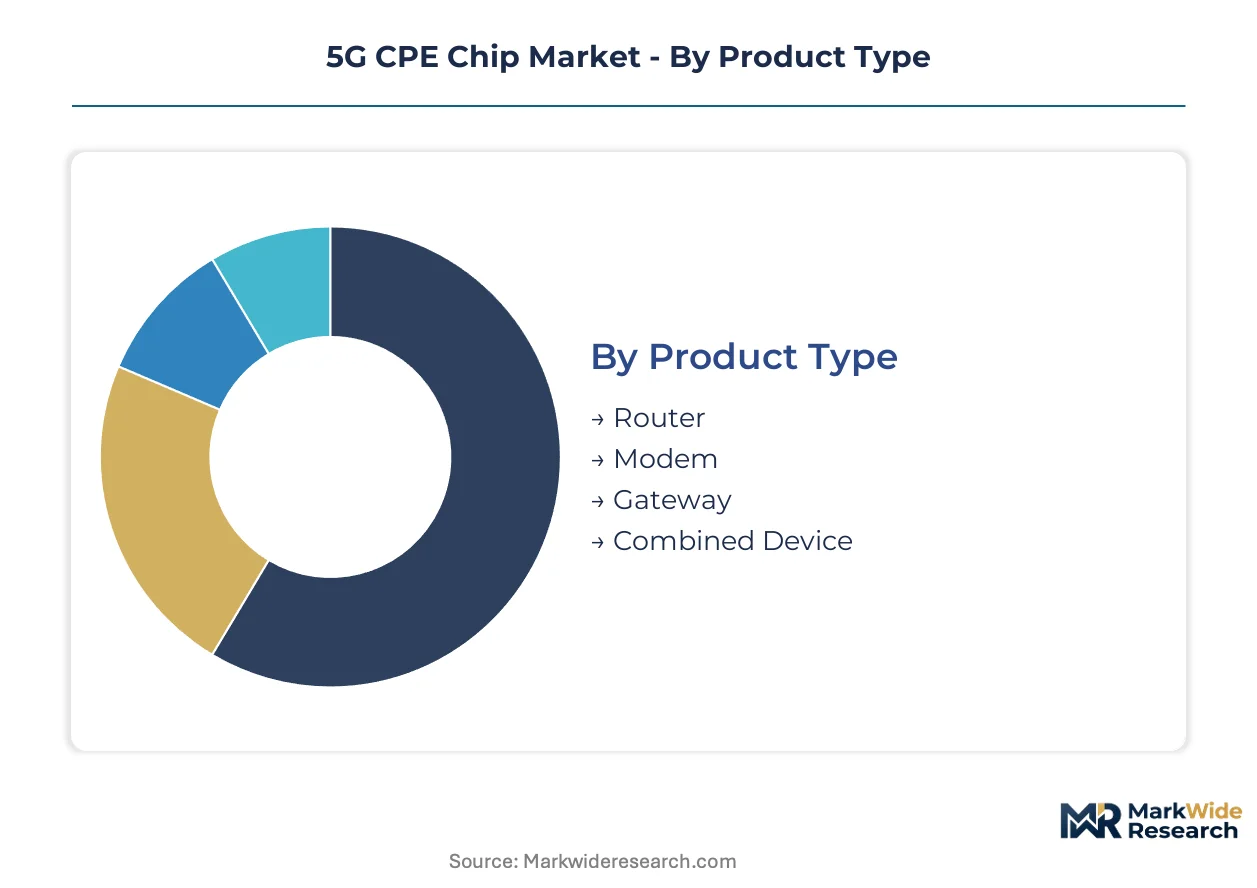
Chipset vendors calibrate die size, RF integration levels, and software stack complexity against distinct buyer procurement criteria across product tiers. Segmentation clarity determines which foundry nodes and certification investments align with specific margin pools.
Product Type:
Carrier procurement teams prioritize gateway and combined device architectures for residential fixed wireless access rollouts, compressing discrete component counts to reduce bill-of-materials overhead.
- Gateway:Integrated modem-RF system-on-chip designs merge baseband processing with edge routing and security functions. Demand concentrates with tier-1 carriers in the United States and Japan seeking single-chip sub-6 GHz solutions to simplify residential deployments.
- Combined Device:Hybrid architectures supporting dual connectivity modes command premium positioning. Manufacturing sites in Germany's Ruhr region and Japan's Kansai corridor drive procurement for private 5G networks requiring on-premise fallback capabilities.
- Router:Standalone routing silicon without integrated cellular modems serves enterprise Wi-Fi backhaul applications.
- Modem:Discrete modem processors enable custom gateway designs for specialized industrial deployments.
Volume sits with Gateway; growth tilts toward Combined Device.
End User:
Residential broadband substitution generates absolute unit demand, while industrial private networks command steepest price premiums per socket.
- Residential:Fixed wireless access displaces DSL and cable in suburban markets lacking fiber infrastructure. China's tier-2 cities lacking fiber backhaul accelerate sub-6 GHz CPE deployment under MIIT spectrum allocation directives.
- Industrial:Manufacturing facilities deploy private 5G networks with on-premise CPE for deterministic latency control. Germany's automotive plants and Japan's precision electronics factories anchor demand for ruggedized gateway platforms with edge computing integration.
- Commercial:Small and medium enterprises adopt cloud-managed CPE for branch connectivity.
- Telecommunications:Carriers deploy carrier-grade CPE for managed service offerings to enterprise clients.
Residential captures unit leadership; industrial posts the steepest expansion trajectory.
Deployment:
Edge computing architectures are displacing pure cloud-based management as carriers seek latency reduction for time-sensitive applications.
- Edge Computing:On-device processing collapses round-trip latency for industrial automation and autonomous systems. South Korean carriers bundle over-the-air feature activation into multi-year service contracts, hardening subscription firmware monetization alongside silicon sales.
- Hybrid:Split architectures balance local packet processing with centralized policy management. USDA Rural Utilities Service loans in the United States subsidize hybrid-deployment fixed wireless equipment for underserved census tracts.
- On-Premise:Fully localized deployments serve air-gapped industrial security requirements.
- Cloud-Based:Centralized management dominates consumer-tier residential offerings.
Cloud-based retains volume dominance; edge computing climbs fastest.
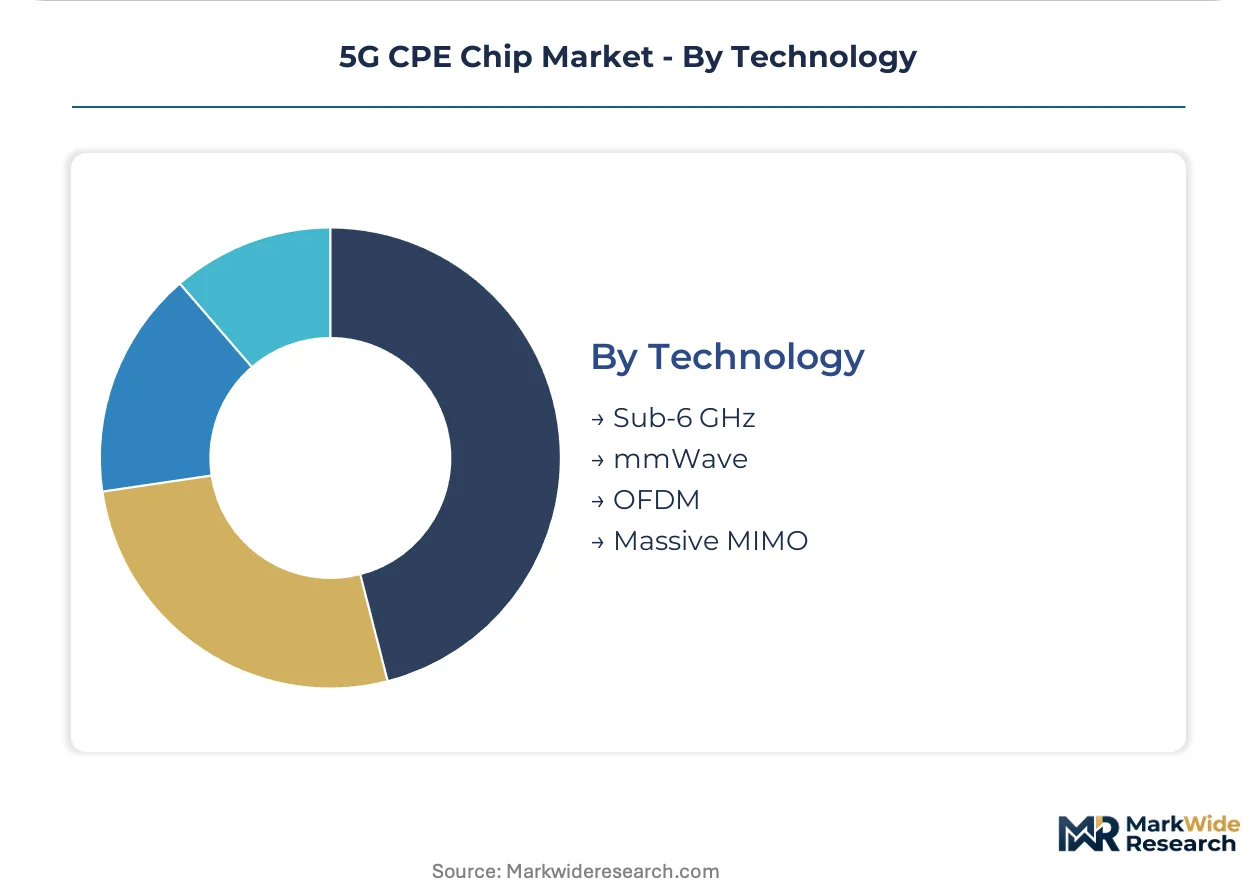
Technology:
RF front-end integration decisions hinge on spectrum availability, building penetration requirements, and infrastructure economics across deployment geographies.
- Sub-6 GHz:Mid-band frequencies deliver superior building penetration and lower small-cell density requirements versus mmWave. China's coastal semiconductor clusters anchor integrated modem production for cost-optimized sub-6 GHz platforms serving domestic and export markets.
- Massive MIMO:Multi-user beamforming architectures multiply spectral efficiency in dense urban deployments. ETSI's updated 3.5 GHz spectrum efficiency standards mandate tighter adjacent channel leakage limits, compelling digital pre-distortion block integration that consumes additional die area.
- mmWave:High-frequency operation requires dense small-cell infrastructure, limiting carrier willingness outside dense urban cores.
- OFDM:Orthogonal frequency division multiplexing underpins waveform flexibility across licensed and unlicensed spectrum.
Sub-6 GHz holds volume leadership; Massive MIMO gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian foundry clusters while consumption spreads across suburban broadband markets in North America, Europe, and China. Taiwan-based fabs control advanced node supply for integrated modem-RF designs. Carrier procurement teams in multiple geographies now demand multi-year firmware roadmaps as contract prerequisites.
United States
Verizon and T-Mobile fixed wireless access rollouts drive residential gateway demand across suburban census tracts lacking fiber infrastructure. FCC spectrum auctions and USDA Rural Utilities Service loans subsidize equipment deployment for underserved areas. San Diego anchors modem-RF co-design talent pools that supply North American carrier certification pipelines.
China
MIIT's mid-band spectrum refarming accelerates sub-6 GHz CPE deployment across tier-2 cities without fiber backhaul. Beijing's dual carbon goals favor wireless broadband over copper trenching in domestic procurement specifications. Shanghai and Shenzhen semiconductor clusters anchor integrated modem production for cost-optimized platforms serving export markets.
Germany
Automotive plants in Baden-Württemberg and precision electronics factories across Bavaria anchor demand for ruggedized industrial gateways with edge computing integration. ETSI's updated 3.5 GHz spectrum efficiency standards mandate tighter adjacent channel leakage limits for European-bound silicon. The Ruhr region's manufacturing sites seek private 5G networks with on-premise CPE for deterministic latency control.
South Korea
SK Telecom and KT bundle over-the-air feature activation into multi-year service contracts, hardening subscription firmware monetization alongside silicon sales. METI-aligned spectrum policy supports dense urban Massive MIMO deployments. Seoul's carrier engineering teams consolidate vendor lists and demand single-chip sub-6 GHz solutions to reduce residential deployment complexity.
Japan
NTT DoCoMo and KDDI specify integrated modem-RF system-on-chip designs for residential gateway procurement to simplify fixed wireless access rollouts. METI industrial policy supports private 5G network licensing for manufacturing automation. The Kansai corridor's precision electronics factories drive demand for hybrid CPE architectures with on-premise fallback capabilities.
5G CPE Chip Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the 5G CPE chip market. Taiwan-based foundries concentrate 7nm and smaller production capacity, creating geographic single-point vulnerability for integrated modem supply. Three archetypes dominate: captive semiconductor divisions of network infrastructure vendors, independent modem specialists with RF integration capabilities, and diversified communications silicon suppliers. Capacity expansion at leading-edge nodes and strategic partnerships for filter and power amplifier technologies represent the dominant competitive moves reshaping supplier power dynamics.
Within the modem-RF integration tier, Qualcomm Incorporated and MediaTek Inc. exemplify divergent positioning strategies—one leveraging Snapdragon X-series architectures for premium carrier placements, the other competing on cost-optimized sub-6 GHz platforms for emerging market ISPs. Samsung Electronics anchors a third archetype through captive demand from its network infrastructure division and in-house foundry supply, representing the vertically integrated model that competing fabless vendors cannot replicate.
| Leading Market Players |
|---|
| Qualcomm Incorporated |
| MediaTek Inc. |
| Samsung Electronics |
| Huawei Technologies |
| Broadcom Inc. |
| NXP Semiconductors |
| Marvell Technology |
| Infineon Technologies |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor divisions of network infrastructure vendors anchor pricing discipline through in-house foundry supply and multi-year carrier contracts, compressing margin pools for fabless competitors while concentrating procurement leverage with tier-1 telecommunications operators in the United States, Japan, and South Korea.
Pricing Analysis
Margin tightening in gateway-tier silicon reflects carrier consolidation of qualified modem suppliers from six to three over eighteen months. Three-tier pricing structure across premium, standard, and economy levels separates Snapdragon X-series placements from cost-optimized sub-6 GHz platforms and discrete modem processors. Certification investment for FCC, ETSI, and MIIT testing sequences compresses gross margins for emerging market ISPs most acutely. Industrial private network buyers absorb premium pricing for ruggedized edge-computing integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale carrier procurement, while distribution runs through specialized semiconductor distributors for emerging market ISPs. Taiwan, South Korea, and the United States anchor 7nm and smaller foundry capacity for integrated modem-RF production. Advanced node supply draws from silicon wafers, RF filter substrates, and power amplifier compound semiconductors. Single-source vulnerability at Taiwan-based fabs creates geographic concentration risk. Contract-based long-term offtake agreements dominate downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into RF filter and power amplifier technologies determines supplier power dynamics and margin capture.
For Market Incumbents: Deepen captive RF integration through die-stacking and advanced packaging investments to defend against MediaTek's cost-optimized sub-6 GHz aggression. Secure multi-year firmware roadmap commitments from Verizon and T-Mobile before carrier vendor lists consolidate further. Add foundry capacity in South Korea to diversify beyond Taiwan single-point exposure.
For New Entrants and Emerging Players: Capture industrial IoT gateway white space in Germany's Ruhr region and Japan's Kansai corridor where private 5G network licensing creates demand for ruggedized platforms with deterministic latency control. Target USDA Rural Utilities Service loan-subsidized deployments in underserved United States census tracts. Lead with over-the-air feature activation bundling to match South Korean carrier subscription monetization models.
For Investors and Strategic Acquirers: METI-aligned spectrum policy supporting dense urban Massive MIMO deployments is the leading indicator that Japanese industrial automation demand will sustain premium-tier pricing. Prioritize acquisition targets with established ETSI certification pipelines and field engineering presence in European automotive manufacturing clusters. Watch for MIIT mid-band refarming announcements as inflection signals for Chinese tier-2 city procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| RF Front-End Integration | Collapsing modem baseband and RF boundary rewrites residential gateway cost structures for tier-1 carriers. |
| Multi-Regional Certification Investment | FCC, ETSI, and MIIT testing sequences extend product launch timelines and concentrate design wins among established vendors. |
| Subscription Firmware Monetization | South Korean carriers bundle over-the-air feature activation into multi-year contracts, hardening recurring revenue alongside silicon sales. |
| Advanced Node Capacity Expansion | Foundry investment in 7nm and smaller processes anchors integrated modem production for cost-optimized platform competitiveness. |
| Industrial Gateway Edge Computing Integration | German automotive plants and Japanese precision electronics factories demand ruggedized platforms with on-premise processing capabilities. |
Research Methodology
Multi-period observation of carrier procurement patterns, foundry node transitions, and spectrum reallocation proceedings anchored the trend analysis, supplemented by interviews with semiconductor engineering directors, carrier procurement managers, RF systems architects, and foundry account executives. Secondary validation drew from FCC spectrum auction records, ETSI standardization documents, MIIT policy circulars, SEC semiconductor company filings, and customs trade data for chip exports. Bottom-up unit demand modeling and top-down value chain analysis were triangulated against foundry capacity utilization reports.
Input-output matrix framing structured the forecast across product type, end user, deployment architecture, and technology segments. Volume and value outputs were calibrated through the projection horizon using adoption curve analysis for fixed wireless access substitution rates. CAGRs were derived from regression against historical semiconductor pricing cycles and carrier capex disclosure patterns. Foundry yield assumptions and spectrum allocation timelines served as industry-specific forecast inputs.
The model holds under stable foundry capacity expansion and carrier fixed wireless access deployment commitments; deviation in Taiwan geopolitical conditions or MIIT spectrum reallocation timing would shift volume trajectories. Periodic stress-testing of base assumptions is recommended given regulatory proceeding uncertainty and advanced node supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market