
 Communication Standard Logic IC Market | 2026-2036
Communication Standard Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Standard Logic IC Market Outlook
China is fragmenting communication standard logic IC supply chains as domestic foundries add 28nm and 40nm capacity for baseband processors and interface chips. STMicroelectronics leverages its European manufacturing footprint to sustain automotive-qualified logic supply. Broadcom anchors North American demand through merchant silicon for data centers and carrier networks. NXP Semiconductors dominates industrial and automotive segments with AEC-Q100 qualified portfolios.
Communication standard logic ICs implement Boolean functions in TTL, CMOS, or BiCMOS process nodes typically ranging from 350nm to 28nm, translating binary signals across voltage thresholds for data processing, signal conditioning, and protocol bridging in electronic systems. CMOS variants command the largest volume pool due to power efficiency in battery-backed telecom infrastructure. Signal Condition applications within Communication Systems represent the fastest structural expansion as 5G massive MIMO deployments multiply RF-to-digital interface counts. Embedded deployment modes capture margin concentration through long-term supply agreements with base station OEMs.
FCC equipment authorization rules in the United States shape electromagnetic compatibility requirements for logic ICs in wireless infrastructure, while MIIT certification in China mandates domestic testing for network equipment silicon. ETSI standards in Europe enforce interoperability benchmarks that constrain product architectures. Stakeholders must monitor foundry allocation cycles and regional content mandates as sovereign semiconductor policies reshape accessible supply pools.
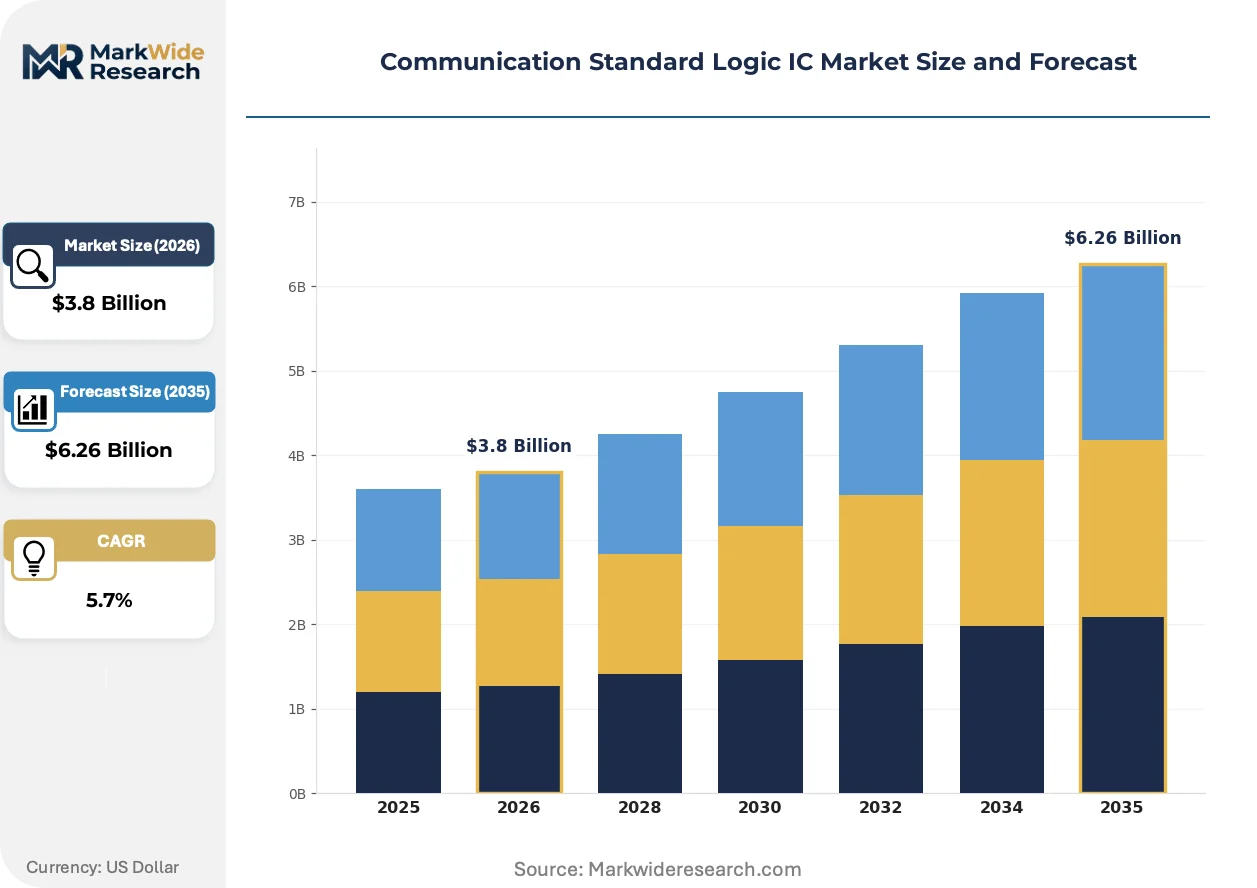
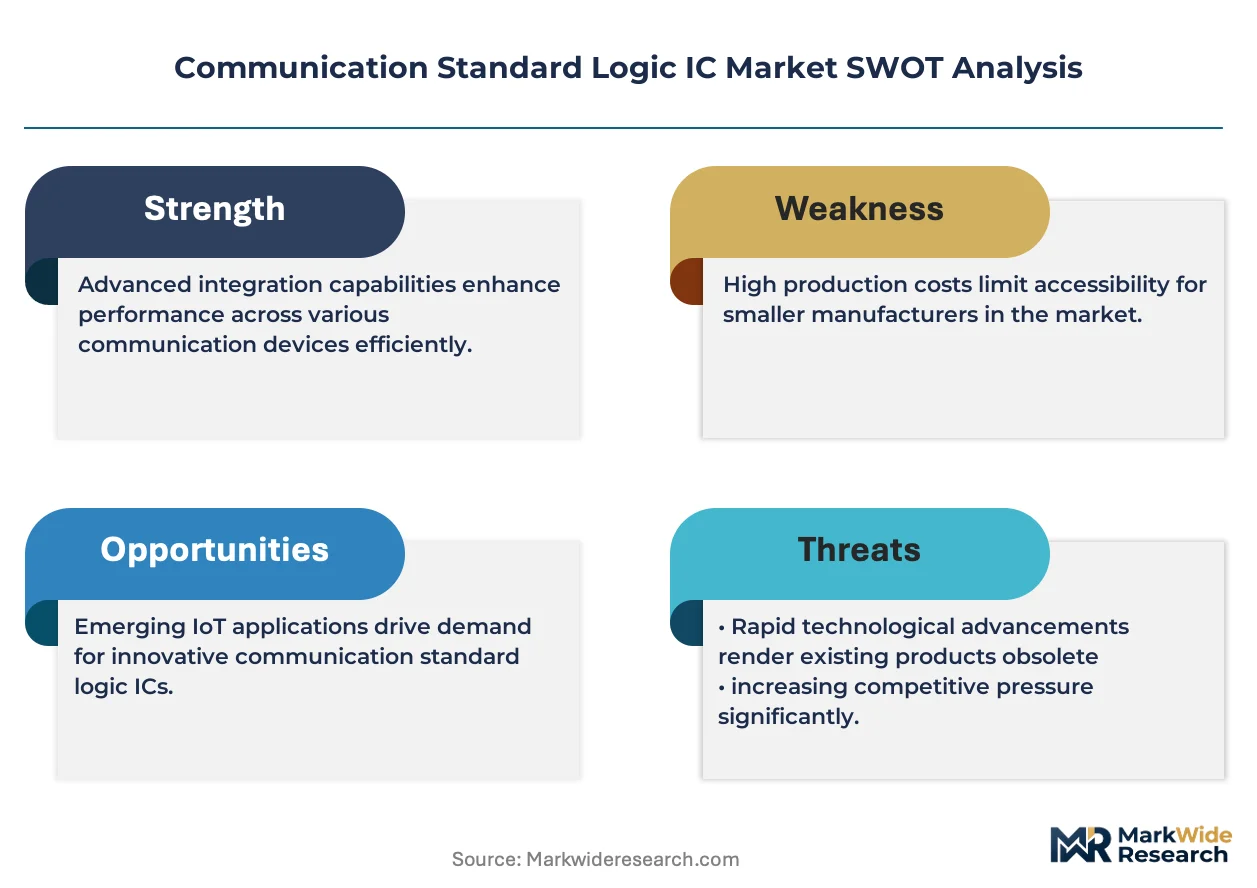
Market Dynamics
Telecommunications infrastructure build-outs are fragmenting foundry allocation cycles as sovereign semiconductor policies force dual-sourcing requirements onto baseband processor and interface chip procurement.
Growth Catalysts
- 5G Massive MIMO Deployments:RF-to-digital interface multiplication in base stations drives demand for signal conditioning logic. Base station OEMs in East Asian manufacturing clusters anchor volume commitments.
- MIIT Domestic Content Mandates:China's Ministry of Industry and Information Technology thresholds for network equipment silicon redirect procurement toward domestic foundry capacity at 28nm and 40nm nodes.
- Automotive Ethernet Bridging:AEC-Q100 qualified logic ICs for in-vehicle networking create qualified supply scarcity that commands long-term supply agreements.
Market Restraints
- Foundry Concentration Risk:Advanced node capacity for BiCMOS and CMOS variants concentrates in Taiwan and South Korea, creating allocation vulnerability during geopolitical tension.
- Raw Material Input Volatility:Silicon wafer and specialty gas costs fluctuate with energy price swings in German and Japanese chemical processing hubs.
- Legacy TTL Substitution:Obsolete 350nm bipolar processes face displacement by modern CMOS equivalents, stranding specialized packaging equipment.
Strategic Opportunities
- Open RAN Architecture Penetration:Disaggregated base station designs in India and Southeast Asia create merchant silicon slots previously captive to integrated OEM solutions.
- EU Green Deal Semiconductor Incentives:European Chips Act funding for 28nm capacity expansion offers qualified supply alternatives outside East Asian concentration.
- Silicon-Photonics Convergence:Co-packaged optics in data center switches merges CMOS logic with photonic interfaces, opening new design-win categories.
Industry Challenges
- AEC-Q100 Certification Timeline:Automotive qualification cycles extend 18-24 months, delaying revenue recognition for new process node introductions.
- Legacy System Integration Friction:5V TTL interfacing with modern 1.8V CMOS cores requires level-shifter design complexity that extends development schedules.
- Specialized Analog-Mixed Signal Talent Scarcity:BiCMOS process expertise concentrates among retiring design engineers in European and Japanese semiconductor divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Standard Logic IC Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TTL, CMOS, BiCMOS, Others Application: Data Processing, Signal Condition, Communication Systems, Control Systems End User: Aerospace, Telecommunications, Consumer Electronics, Industrial Automation Deployment: Embedded, Standalone, Integrated, Modular |
| Companies Covered | STMicroelectronics, Renesas Electronics, Broadcom, Qualcomm Technologies, NXP Semiconductors, Analog Devices, MediaTek, Marvell Semiconductor, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Standard Logic IC Market Strategic Shifts
Process node migration and packaging evolution are compressing power-performance trade-offs while regulatory mandates force geographic diversification of qualified supply sources.
FinFET-based CMOS at 22nm and below is rendering obsolete planar transistor structures in high-speed interface logic. Data center switch vendors now specify sub-picosecond jitter performance that planar CMOS cannot deliver. This transition is rendering obsolete legacy foundry equipment at 40nm and above for premium signal conditioning applications.
ETSI interoperability benchmarks for network equipment are constraining product architectures across European carrier procurement. FCC equipment authorization rules in the United States simultaneously shape electromagnetic compatibility requirements for wireless infrastructure logic. Dual certification burdens are forcing redundant test matrix investments that favor large semiconductor houses with dedicated regulatory affairs teams.
Consolidated procurement through base station OEM captive purchasing departments is displacing traditional distribution channels for high-volume logic ICs. Direct long-term supply agreements now lock in allocation priority ahead of spot market availability. This concentration is most visible in Shenzhen and Shanghai manufacturing corridors where Huawei and ZTE procurement teams negotiate exclusive foundry capacity reservations.
Communication Standard Logic IC Market Segmentation
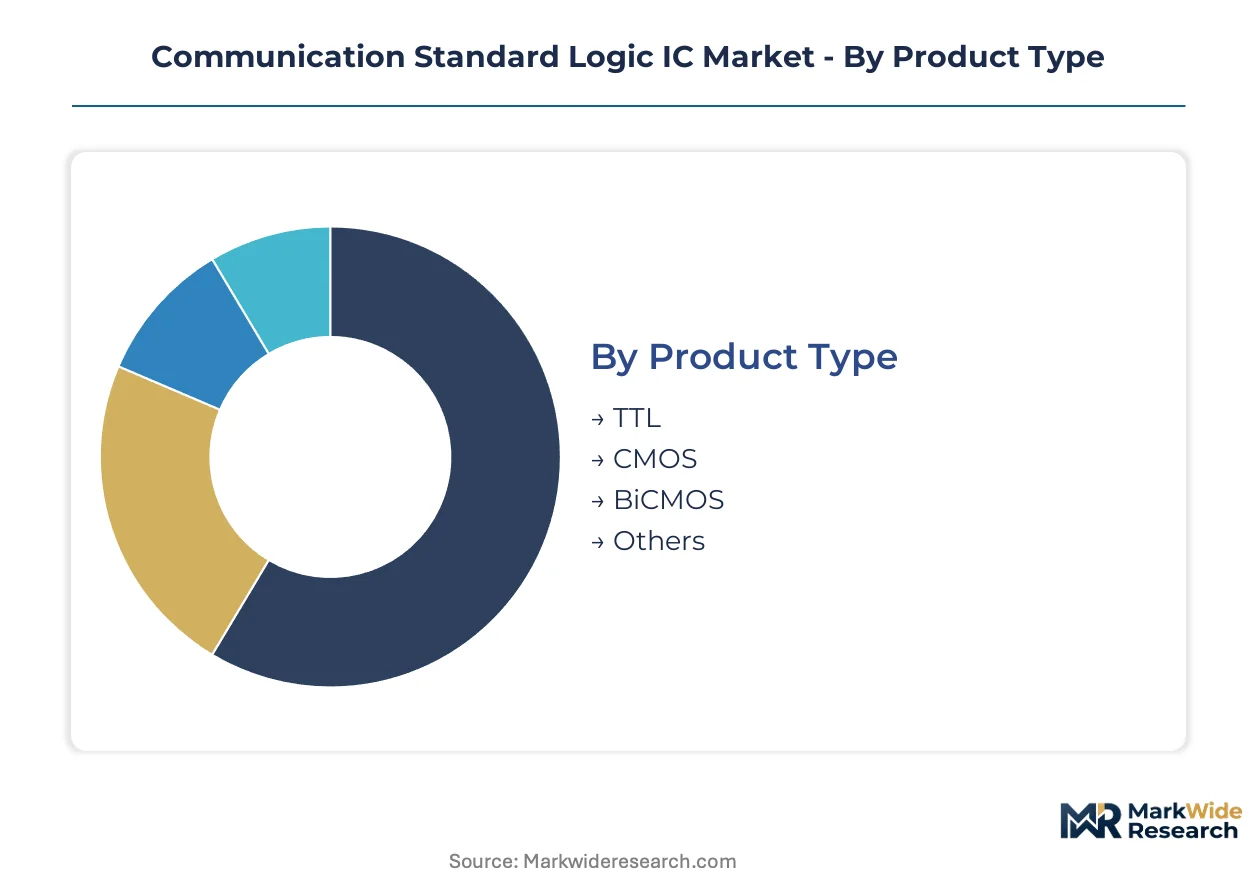
Communication standard logic ICs fragment across process technologies, voltage thresholds, and integration depths that dictate procurement patterns. Each segmentation dimension carries distinct margin profiles and qualification burdens that reshape competitive positioning across telecommunications, automotive, and industrial verticals.
Product Type:
Mature bipolar architectures coexist with emerging FinFET CMOS variants as foundries extend node roadmaps for power-sensitive applications.
- TTL:Bipolar junction transistor logic operates at 5V thresholds with high current drive capability for legacy industrial interfaces. Demand concentrates in German factory automation retrofits where 24V-to-5V level translation preserves installed base compatibility.
- CMOS:Complementary metal-oxide-semiconductor variants dominate volume pools through sub-picowatt static power consumption in battery-backed telecom infrastructure. Shenzhen and Shanghai base station manufacturing corridors anchor procurement for 1.8V and 3.3V core logic as 5G massive MIMO deployments multiply gate counts per rack.
- BiCMOS:Merged bipolar-CMOS processes deliver high-speed switching with analog precision for RF front-end interfaces.
- Others:Emerging gallium-nitride logic and silicon-germanium variants serve specialized millimeter-wave applications.
CMOS handles the majority of throughput; BiCMOS is the fastest mover on share as RF-to-digital integration intensifies.
Application:
Signal conditioning functions command premium pricing as data rates exceed 100Gbps in carrier backhaul equipment.
- Signal Condition:High-speed level shifters, buffers, and equalizers restore signal integrity across PCB trace losses and connector impedance mismatches. South Korean 5G base station OEMs drive fastest volume expansion as 64T64R antenna configurations multiply serdes lane counts per subsystem.
- Communication Systems:Protocol bridging and clock distribution logic enable synchronous data transfer across heterogeneous network elements. Japanese optical transport equipment manufacturers anchor demand for jitter-compliant buffers in 400G coherent transponder designs.
- Data Processing:Boolean arithmetic and register file functions support computational workloads in edge routing silicon.
- Control Systems:State machines and sequencing logic manage power-up sequences and fault protection in industrial controllers.
Signal Condition captures the steepest expansion trajectory; Communication Systems retains the largest installed base commitment.
End User:
Telecommunications procurement concentrates volume while aerospace qualification timelines stretch revenue recognition cycles.
- Telecommunications:Base station OEMs and optical transport vendors consume highest absolute volumes through direct foundry allocation agreements. China's MIIT domestic content mandates redirect procurement toward SMIC and Hua Hong Semiconductor for 28nm baseband logic.
- Aerospace:DO-254 design assurance and extended temperature range requirements constrain supplier pools to qualified heritage vendors. Satellite payload manufacturers in Toulouse and Munich drive demand for radiation-hardened CMOS in LEO constellation deployments.
- Consumer Electronics:Smartphone peripheral logic and IoT edge nodes prioritize cost-optimized 40nm CMOS from Taiwanese foundries.
- Industrial Automation:Programmable logic controllers and motor drives require 125°C ambient operation with 15-year supply continuity guarantees.
Telecommunications anchors absolute volume throughput; Aerospace climbs the fastest on per-unit value realization.
Deployment:
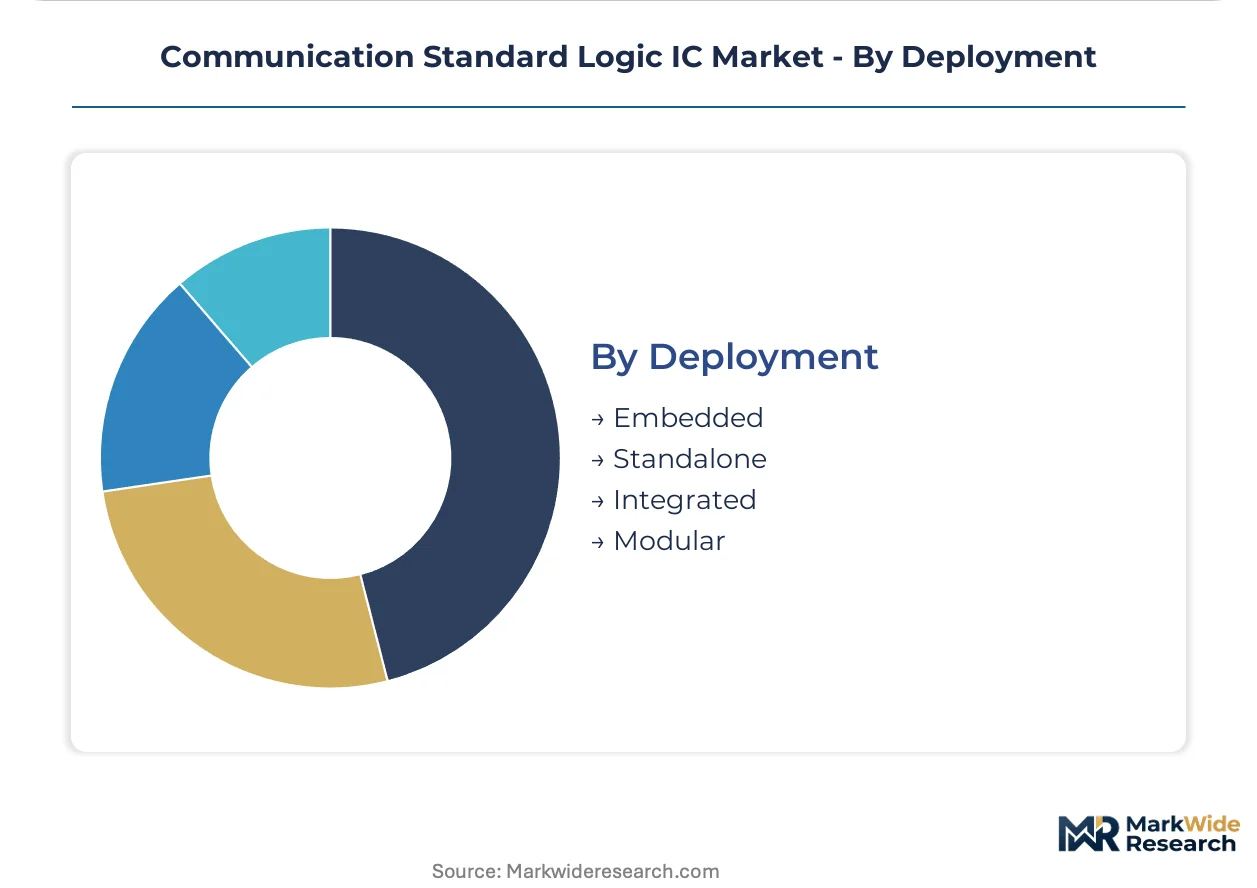
Integration depth determines margin capture as discrete logic faces displacement by SoC integration in cost-optimized designs.
- Embedded:Logic cores integrated within baseband processors and network switch ASICs eliminate discrete component count. Huawei HiSilicon and Qualcomm anchor highest consumption through captive synthesis flows in 7nm and 5nm mobile platforms.
- Modular:Standardized small-outline packages enable second-source procurement flexibility for supply chain resilience. Dell and HPE server manufacturing in Penang and Guadalajara drive demand for interchangeable buffer and translator modules.
- Standalone:Discrete packaged logic persists in legacy system maintenance and low-volume custom configurations.
- Integrated:Multi-die chiplets merge logic with memory and analog functions in advanced packaging.
Embedded deployment secures the dominant volume position; Modular formats gain share fastest as dual-sourcing mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for communication standard logic ICs concentrates in East Asian manufacturing corridors, with sovereign semiconductor policies forcing geographic diversification of qualified supply sources across multiple jurisdictions.
China
MIIT domestic content mandates redirect baseband processor procurement toward SMIC and Hua Hong Semiconductor at 28nm and 40nm nodes. The country's dual carbon goals constrain energy-intensive chemical processing for silicon wafer production. Shenzhen and Shanghai manufacturing corridors host Huawei and ZTE procurement teams negotiating exclusive foundry capacity reservations for 5G massive MIMO deployments.
United States
FCC equipment authorization rules shape electromagnetic compatibility requirements for wireless infrastructure logic. The CHIPS and Science Act funds domestic 28nm capacity expansion to reduce reliance on East Asian foundry allocation. Texas and Arizona semiconductor manufacturing clusters anchor merchant silicon production for data center switch vendors.
South Korea
Samsung Foundry and SK Hynix anchor advanced CMOS capacity for high-speed interface logic serving 64T64R antenna configurations. The country's national semiconductor strategy prioritizes BiCMOS process expertise for RF-to-digital integration. Seoul and Suwon manufacturing complexes drive fastest volume expansion in signal conditioning ICs for 5G base station OEMs.
Germany
EU Green Deal semiconductor incentives under the European Chips Act fund 28nm capacity expansion at Bosch and Infineon facilities. REACH and RoHS regulations constrain material inputs for legacy TTL packaging equipment. Dresden and Munich industrial clusters sustain automotive-qualified logic supply through AEC-Q100 certified production lines.
Japan
METI industrial policy supports silicon photonics convergence research merging CMOS logic with photonic interfaces. JIS standards enforce interoperability benchmarks for optical transport equipment manufacturers. Tokyo and Nagoya manufacturing bases anchor demand for jitter-compliant buffers in 400G coherent transponder designs.
Communication Standard Logic IC Market Competitive Environment
Integrated device manufacturers and fabless semiconductor houses split the market between captive foundry allocation and merchant silicon flexibility. The vendor base organizes around three strategic archetypes: diversified conglomerates with internal fabrication, specialized analog-mixed signal boutiques, and scale-driven fabless designers. Consolidation pressure intensifies as dual-sourcing mandates favor large houses with dedicated regulatory affairs teams. Competitive moves center on foundry partnership exclusives and geographic diversification of qualified supply sources.
Within the diversified conglomerate tier, STMicroelectronics exemplifies European manufacturing footprint strategies for automotive-qualified logic. NXP Semiconductors occupies a position in industrial and automotive segments through AEC-Q100 portfolio concentration. Broadcom anchors North American merchant silicon supply for data center and carrier network applications.
| Leading Market Players |
|---|
| STMicroelectronics |
| Renesas Electronics |
| Broadcom |
| Qualcomm Technologies |
| NXP Semiconductors |
| Analog Devices |
| MediaTek |
| Marvell Semiconductor |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
Taipei and Hsinchu foundry clusters anchor global CMOS logic capacity, with allocation priority during supply crunches translating directly into pricing power for AEC-Q100 qualified variants. Base station OEM procurement teams in Shenzhen negotiate long-term offtake agreements that lock in volume discounts, while spot-market buyers absorb 40-60% premiums during allocation cycles.
Pricing Analysis
MIIT domestic content mandates dictate the pricing tier structure across the Chinese telecommunications procurement landscape. Three-tier pricing stratifies across automotive-qualified premium tiers with 18-24 month certification timelines, industrial-standard mid-tiers with 10-year supply guarantees, and cost-optimized economy tiers for consumer peripheral logic. Cost compression in the economy tier is intensifying as 40nm CMOS faces displacement by 28nm FinFET equivalents. Automotive OEMs exhibit the lowest price sensitivity due to AEC-Q100 qualification switching costs, while consumer electronics buyers drive aggressive spot-market negotiation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for baseband processor and interface chip procurement. Taiwan, South Korea, and China concentrate advanced node CMOS and BiCMOS capacity, with silicon wafers, specialty gases, and photoresist materials drawing from German and Japanese chemical processing hubs. Single-source vulnerability concentrates in East Asian foundry allocation cycles during geopolitical tension. Distribution runs through direct OEM procurement departments rather than traditional component distribution, with Huawei and ZTE procurement teams in Shenzhen and Shanghai negotiating exclusive capacity reservations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Communication standard logic IC supply chains operate as a defensive-moat market where AEC-Q100 certification timelines create 18-24 month switching costs that entrench qualified suppliers. Regulatory fragmentation across FCC, MIIT, and ETSI jurisdictions compounds this moat by forcing redundant test matrix investments.
For Market Incumbents: Harden foundry partnership exclusives in European and North American jurisdictions to offset MIIT domestic content mandates redirecting Chinese procurement toward SMIC and Hua Hong Semiconductor. Expand 28nm automotive-qualified capacity at Dresden and Arizona facilities before EU Green Deal incentives sunset. Vertical integration into silicon wafer sourcing mitigates raw material volatility from German chemical processing hubs.
For New Entrants and Emerging Players: Open RAN disaggregated base station architectures in India and Southeast Asia represent the most penetrable entry point for merchant silicon slots previously captive to integrated Huawei and ZTE solutions. Automotive Ethernet bridging for in-vehicle networking creates qualified supply scarcity that commands long-term supply agreement structures. Partner with Indian telecom operators bypassing traditional OEM procurement channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-qualified logic suppliers with AEC-Q100 portfolio concentration and 15-year supply continuity guarantees. Target acquisition archetypes include European analog-mixed signal boutiques with retiring BiCMOS process expertise and captive foundry allocation in automotive-certified production lines. Watch for inflection in silicon-photonics convergence adoption within data center switch vendor roadmaps.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Exclusives | Locks allocation priority at TSMC and Samsung Foundry ahead of spot-market availability during supply crunches. |
| AEC-Q100 Certification Investment | Creates 18-24 month switching costs that entrench suppliers with automotive OEM procurement committees. |
| Silicon-Photonics R&D Partnership | Positions for co-packaged optics design wins with Broadcom and Marvell in data center switch silicon. |
| EU Green Deal Capacity Expansion | Captures Bosch and Infineon incentives for 28nm automotive-qualified production lines at Dresden. |
| Open RAN Merchant Silicon Launch | Displaces captive Huawei and ZTE solutions in Indian and Southeast Asian disaggregated base station deployments. |
Study Parameters
Cross-validation between primary fieldwork with base station OEM procurement directors and secondary analysis of MIIT certification databases anchors the qualitative findings. Semiconductor industry interviews spanned foundry planning officers, automotive Tier 1 supplier procurement leads, analog-mixed signal design directors, and regulatory affairs specialists navigating FCC equipment authorization. Secondary sources included ETSI interoperability benchmark filings, SEC 10-K semiconductor segment disclosures, and customs trade data for silicon wafer imports. Bottom-up wafer allocation estimates triangulated against top-down telecommunications infrastructure capex projections.
Calibration against historical foundry utilization rates and base station deployment trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include process technology node, voltage threshold architecture, application function, end-user vertical, and deployment integration depth. CAGRs derived from wafer start forecasts by node, adjusted for yield learning curves and die size compression trends. Industry-specific inputs incorporated 5G massive MIMO antenna configuration roadmaps and automotive Ethernet bandwidth evolution specifications.
Macroeconomic conditions sit as an overlay; deviation in telecommunications infrastructure capex cycles and automotive production volumes would shift the trajectory. Forecasts reflect assumptions around foundry allocation stability and regulatory certification timeline continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market