
 Asia Pacific Indoor LED Lighting Market | 2026-2036
Asia Pacific Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Indoor LED Lighting Market Insights
Chip-on-board (COB) LED packaging is reconfiguring thermal management architectures for high-lumen indoor fixtures. Nichia Corporation leverages its phosphor-converted white LED portfolio to dominate premium color-rendering applications. Signify N.V. anchors its regional position through smart lighting ecosystems that integrate with building management systems. Opple Lighting Co., Ltd. competes aggressively on manufacturing scale across China's domestic project channel.
Asia Pacific indoor LED lighting comprises solid-state luminaires engineered with aluminum heat sinks, efficacy ratings exceeding 100 lm/W, and driver electronics for AC grid compatibility, designed to replace fluorescent and incandescent sources in enclosed architectural spaces. Downlights and panels lead volume shipments across the residential and commercial retrofit base, while tunable white and smart lighting technologies command higher margin pools in hospitality and educational institutions. Dimmable systems retain maturity in cost-sensitive segments as RGB and connected platforms accelerate in premium specifications.
China's SAMR enforces GB energy-efficiency standards that phase out non-compliant legacy fixtures, while India's BIS certification mandates safety testing for imported LED assemblies. Japan's METI promotes JIS-aligned quality benchmarks that shape procurement criteria for large-scale commercial projects. Stakeholders must monitor regulatory divergence across national certification regimes when structuring pan-Asian product platforms and distribution strategies.
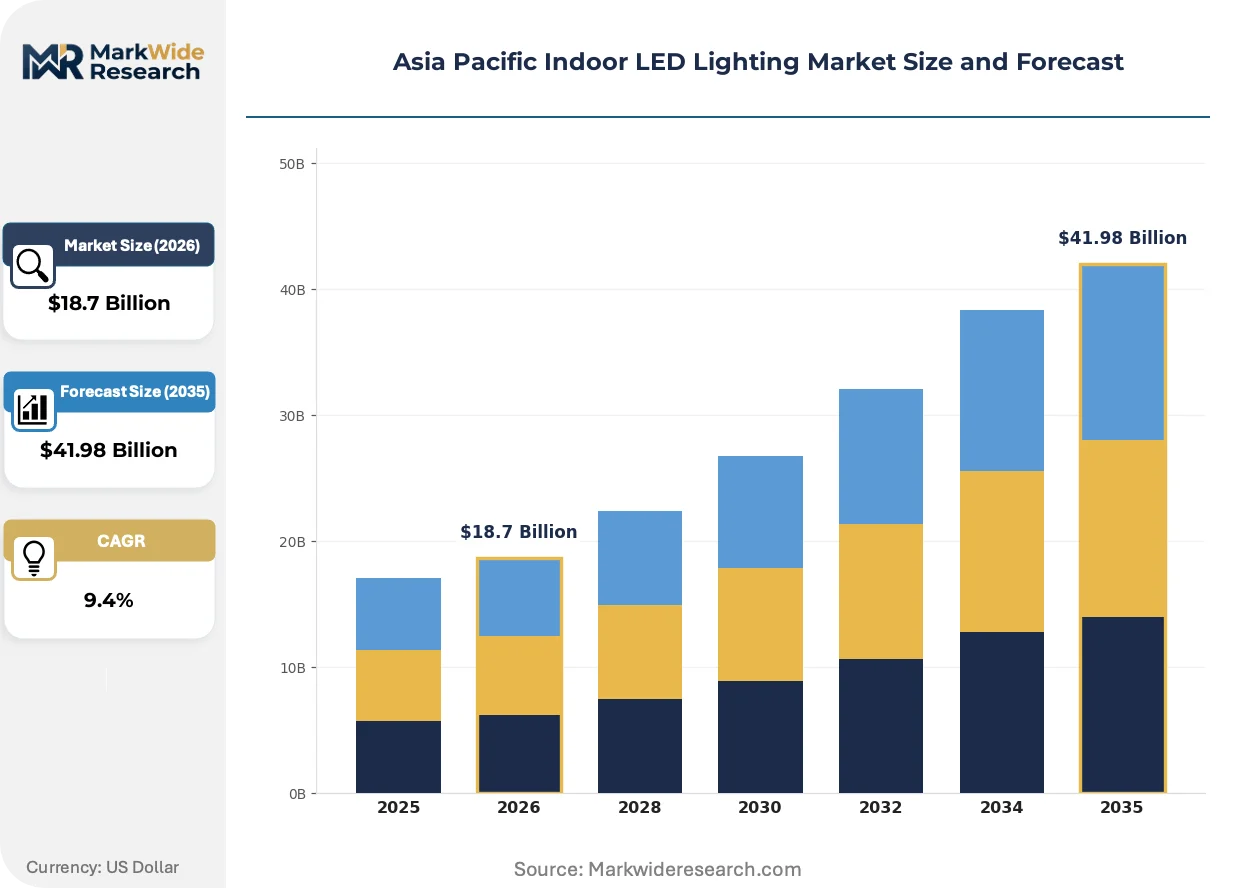
Market Dynamics
China's GB energy-efficiency standards are forcing accelerated fixture replacement across commercial real estate portfolios, while India's BIS certification mandates reshape import sourcing patterns for LED assemblies. This regulatory compression is reconfiguring supply chain priorities for manufacturers serving tier-one manufacturing cities and metropolitan commercial corridors.
Growth Catalysts
- Commercial office retrofits:Building owners across China's Pearl River Delta and India's Mumbai-Pune corridor are replacing fluorescent fixtures with high-efficacy LED panels to meet lease certification requirements and reduce operating expenditures.
- Smart building integration:Facility managers are deploying tunable white and connected lighting platforms that interface with building management systems, creating pull-through demand for sensor-enabled luminaires in hospitality and educational institutions.
- GB standards phase-out:SAMR enforcement of non-compliant legacy fixture elimination is compressing replacement cycles and redirecting procurement toward certified domestic manufacturers with established testing laboratory relationships.
Market Restraints
- Aluminum heat sink cost volatility:Raw material price fluctuations for thermal management components compress margin pools for fixture assemblers serving cost-sensitive residential retrofit segments.
- Driver electronics import concentration:Dependence on Taiwan and South Korea semiconductor suppliers for AC grid-compatible driver ICs creates supply vulnerability during regional logistics disruptions.
- Phosphor-converted white LED technical ceiling:Efficacy gains in premium color-rendering applications are approaching theoretical limits, constraining differentiation for high-CRI product lines.
Strategic Opportunities
- Vietnam manufacturing corridor:Underdeveloped LED fixture assembly capacity in northern Vietnam industrial zones offers first-mover positioning for suppliers diversifying beyond China-centric production.
- Human-centric lighting convergence:Integration of circadian rhythm tuning with IoT occupancy sensing creates premium specification opportunities in healthcare and senior living facilities.
- India PLI scheme extension:Domestic value-add incentives for LED component manufacturing are redirecting capital toward integrated chip-on-board packaging facilities serving the South Asian project channel.
Industry Challenges
- Thermal engineering talent scarcity:Fixture manufacturers face acute shortages of engineers capable of optimizing aluminum heat sink geometries for high-lumen density COB configurations.
- Multi-jurisdiction certification timelines:Simultaneous GB, BIS, and JIS testing requirements extend product launch cycles and fragment R&D resource allocation across pan-Asian platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Indoor LED Lighting Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Downlights, Panels, Troffers, Ceiling Lights Application: Residential, Commercial, Industrial, Hospitality Technology: Dimmable, Smart Lighting, RGB, Tunable White End User: Households, Retail Stores, Offices, Educational Institutions |
| Companies Covered | Foshan Electrical and Lighting Co., Ltd. (FSL), Everlight Electronics Co., Ltd., Nichia Corporation, LG Electronics, Panasonic Corporation, Signify N.V., Opple Lighting Co., Ltd., MLS Co., Ltd. (Forest Lighting), Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Indoor LED Lighting Market Trends and Innovations
Chip-on-board LED packaging architectures are compressing thermal management footprints while expanding lumen density ceilings for enclosed fixture designs. Three convergent developments are restructuring competitive positioning across the Asia Pacific indoor lighting value chain.
COB LED arrays are collapsing the physical separation between emitter surface and heat sink interface in high-output downlight and spotlight applications. Hospitality designers in Singapore and Bangkok are specifying these compact sources for ceiling-recessed installations with constrained plenum depths. The technology is collapsing traditional distinctions between architectural and commercial-grade fixture categories by enabling uniform thermal performance across premium and mid-market product tiers.
Japan's METI is enforcing JIS-aligned quality benchmarks that mandate extended lumen maintenance testing for large-scale commercial procurement. This regulatory pressure is elevating documentation requirements for phosphor degradation curves and driver reliability data. Tier-one property developers in Tokyo and Osaka are now requiring JIS certification as a gatekeeping criterion for fixture vendor qualification, compressing supplier pools to established domestic and Korean manufacturers with in-house testing infrastructure.
Building operators are unbundling lighting maintenance from capital equipment procurement, shifting toward service-based contracts with guaranteed efficacy performance. This purchasing pattern is disrupting traditional distributor relationships in Australia's commercial retrofit market, where facility management firms now contract directly with manufacturers for multi-site rollouts. The model is most visible in Sydney and Melbourne healthcare precincts, where long-term service agreements are displacing spot-buy replacement cycles.
Asia Pacific Indoor LED Lighting Market Segmentation
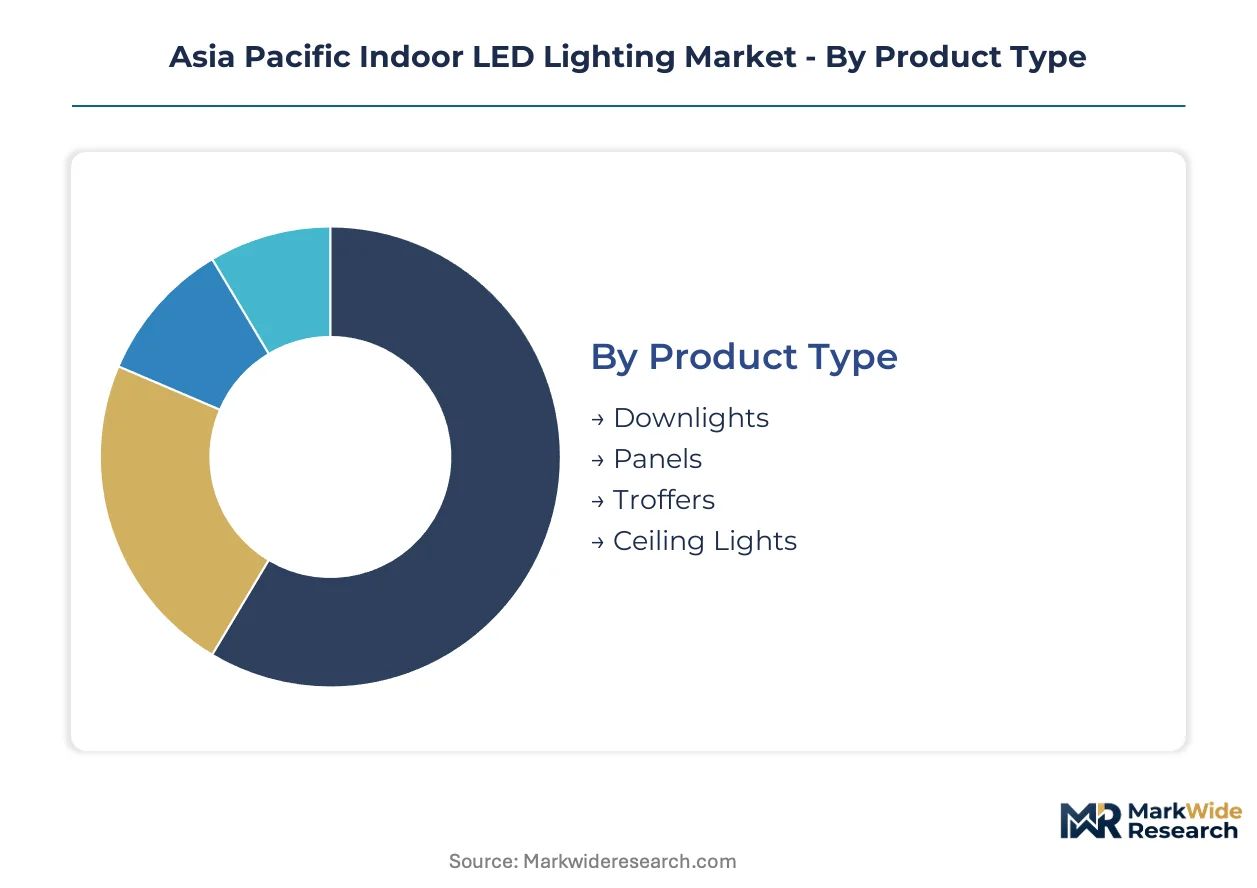
Segmentation reveals how procurement patterns diverge across fixture specifications and end-use requirements in the Asia Pacific indoor LED lighting market. Understanding these divides helps suppliers align thermal management architectures and certification strategies with specific buyer priorities across residential retrofits and commercial new-builds.
Product Type:
After-sales service intensity varies sharply across fixture categories, with recessed installations demanding specialized contractor networks for warranty fulfillment while surface-mounted products route through general electrical distributors.
- Downlights:Compact recessed fixtures engineered with COB LED arrays and aluminum heat sinks for ceiling plenum integration. Demand concentrates in Singapore and Bangkok hospitality retrofits where constrained ceiling depths mandate slim thermal profiles. These installations require certified technician networks for warranty service, elevating distributor technical support capabilities as a competitive gate.
- Panels:Flat surface-mounted or suspended luminaires utilizing edge-lit or backlit LED configurations for uniform illumination across commercial floorplates. China's Pearl River Delta manufacturing cities are replacing fluorescent troffers with high-efficacy panels to meet SAMR GB standards compliance deadlines. The scale of these retrofit rollouts favors suppliers with integrated project management and commissioning services.
- Troffers:Rectangular recessed fixtures designed for suspended ceiling grid systems, typically specified with prismatic diffusers and integrated driver compartments.
- Ceiling Lights:Surface-mounted decorative and functional luminaires spanning flush-mount and semi-flush configurations for residential and light commercial applications.
Panels hold the largest share; momentum sits with downlights as hospitality and premium residential specifications shift toward architectural-grade recessed aesthetics.
Application:
Cost tier stratification separates specification-grade hospitality deployments from volume-driven residential retrofits, with procurement authority residing in fundamentally different stakeholder groups.
- Residential:Single-family and multi-unit dwelling installations prioritizing fixture cost efficiency and retrofit compatibility with existing electrical infrastructure. India's metropolitan commercial corridors are witnessing accelerated uptake as BIS-certified products displace unorganized sector imports through channel consolidation.
- Commercial:Office, retail, and institutional spaces demanding extended lumen maintenance warranties and building management system integration. Japan's METI JIS-aligned procurement criteria now mandate documented phosphor degradation curves for large-scale Tokyo and Osaka developments, compressing qualified supplier pools.
- Industrial:High-bay and task lighting for manufacturing environments requiring robust ingress protection and vibration-resistant driver mounting.
- Hospitality:Hotels, restaurants, and entertainment venues specifying tunable white and RGB platforms for ambiance control and brand differentiation.
Commercial applications command the largest revenue pool; hospitality is climbing fastest as circadian lighting specifications penetrate healthcare-adjacent senior living developments.
Technology:
Customer type divides sharply between facility managers seeking operational simplicity and specifiers pursuing advanced control capabilities, with margin structures inverting across these buyer profiles.
- Dimmable:Analog and digital dimming protocols enabling luminous flux adjustment through phase-cut or 0-10V control signals. Cost-sensitive residential segments across India's tier-two cities retain preference for basic dimmable systems over connected alternatives.
- Smart Lighting:Networked luminaires with embedded sensors and wireless communication stacks for occupancy detection and daylight harvesting. Australia's Sydney and Melbourne healthcare precincts are unbundling maintenance through long-term service contracts with guaranteed efficacy performance, favoring smart platform suppliers.
- RGB:Multi-channel LED engines enabling saturated color output through independent red, green, and blue emitter control.
- Tunable White:Correlated color temperature adjustment from warm to cool spectra through separate warm-white and cool-white channel dimming.
Dimmable systems retain volume dominance; tunable white is gaining share fastest as educational institutions and healthcare facilities adopt human-centric lighting protocols.
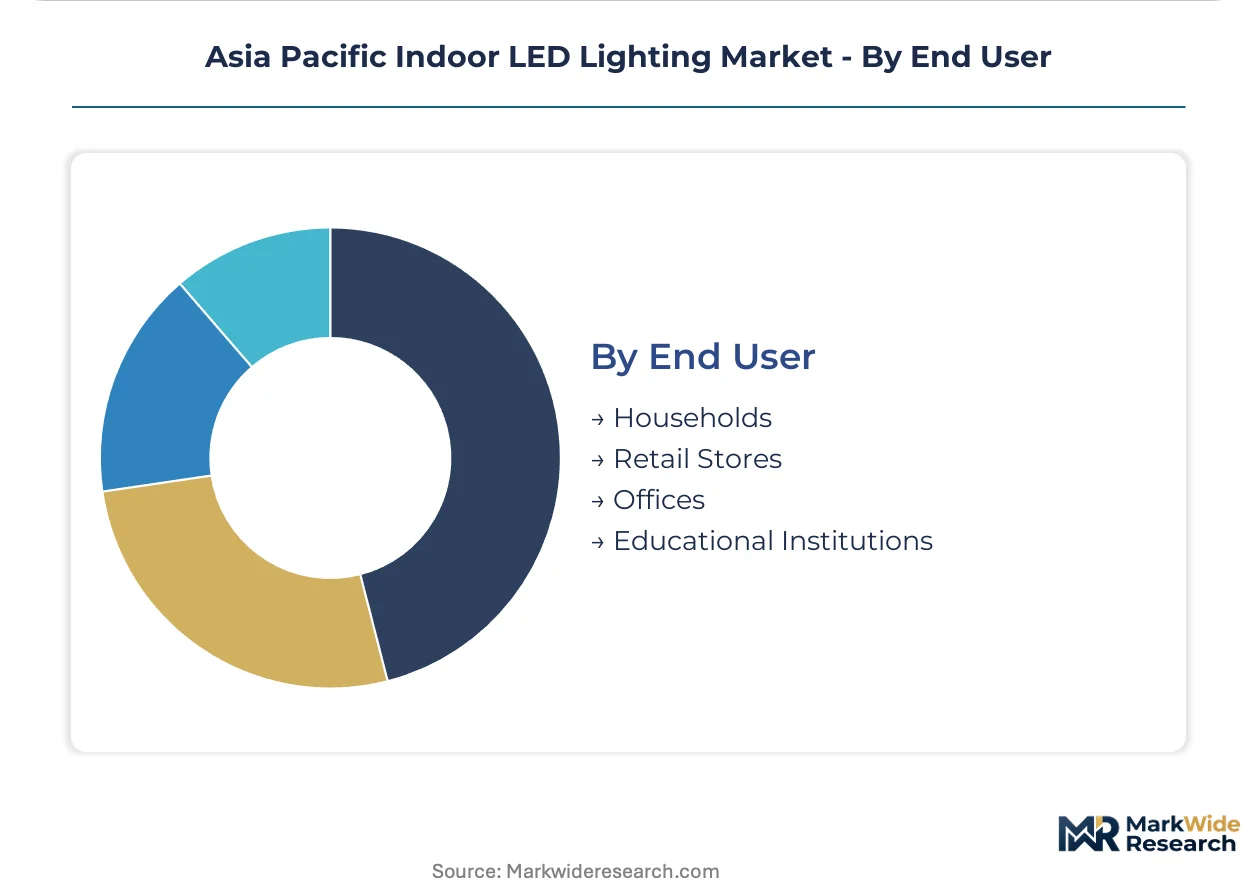
End User:
Supply concentration in driver electronics and phosphor-converted LED sourcing creates divergent risk profiles across end-user segments with varying tolerance for lead time volatility.
- Households:Individual consumers purchasing through retail and e-commerce channels, price-sensitive and influenced by energy efficiency labeling. China's domestic project channel is consolidating around manufacturers with captive component supply and GB standards pre-certification.
- Retail Stores:Merchandising environments requiring high color rendering and beam control for product presentation. Mumbai-Pune corridor retail developments are specifying LED panels with CRI90+ performance to meet lease certification requirements.
- Offices:Corporate and government workplace environments prioritizing glare control, uniformity, and integration with building automation systems.
- Educational Institutions:Schools and universities adopting tunable white systems for circadian rhythm support in classrooms and study spaces.
Offices represent the largest addressable base; educational institutions are expanding most quickly as pedagogical research drives procurement specifications toward biologically optimized illumination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports LED driver ICs and phosphor-converted chips to assembly plants across Vietnam and Thailand, establishing a component trade corridor that feeds fixture manufacturing for Australia's healthcare and commercial retrofit markets.
China
Commercial office retrofits in Shanghai and Shenzhen are replacing fluorescent troffers with high-efficacy LED panels ahead of SAMR's GB standards enforcement deadlines. The national regulator is phasing out non-compliant legacy fixtures through mandatory efficiency labeling. Manufacturing clusters in the Pearl River Delta are consolidating procurement around domestic suppliers with captive testing laboratory relationships.
India
BIS certification mandates are redirecting import sourcing toward certified domestic manufacturers in Mumbai and Delhi-NCR. The national standards body is tightening safety testing requirements for LED assemblies entering through metropolitan commercial corridors. Channel consolidation is displacing unorganized sector imports as certified products capture volume in tier-one and tier-two cities.
Japan
METI's JIS-aligned quality benchmarks are elevating documentation requirements for phosphor degradation curves in large-scale Tokyo and Osaka developments. The ministry mandates extended lumen maintenance testing for commercial procurement above specified project thresholds. Tier-one property developers now require JIS certification as a gatekeeping criterion, compressing qualified supplier pools.
Australia
Sydney and Melbourne healthcare precincts are unbundling lighting maintenance from capital equipment procurement through long-term service contracts. Facility management firms contract directly with manufacturers for multi-site smart lighting rollouts with guaranteed efficacy performance. This purchasing pattern is displacing traditional distributor relationships in the commercial retrofit channel.
Vietnam
Northern Vietnam industrial zones offer underdeveloped LED fixture assembly capacity for suppliers diversifying beyond China-centric production. The government is attracting foreign direct investment through industrial zone incentives and streamlined licensing. Bac Ninh and Hai Phong are emerging as alternative assembly locations for exporters serving ASEAN markets.
Asia Pacific Indoor LED Lighting Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct tiers: multinational electronics conglomerates with captive semiconductor supply, specialized lighting manufacturers with integrated project channels, and regional assemblers competing on manufacturing scale. Strategic archetypes include technology licensors leveraging phosphor and packaging IP, systems integrators anchoring smart building ecosystems, and cost-optimized fabricators serving domestic retrofit volume. Dominant competitive moves center on backward integration into driver electronics and geographic diversification of final assembly beyond China.
Within the multinational tier, Nichia Corporation and Signify N.V. exemplify divergent positioning strategies. The former occupies a position anchored in premium phosphor-converted white LED technology for color-critical applications. The latter represents the systems-integration archetype through building management system compatibility and connected platform deployment. Among Asia-Pacific specialists, Opple Lighting Co., Ltd. sits within the scale-driven domestic channel, while Foshan Electrical and Lighting Co., Ltd. exemplifies the integrated manufacturer serving project-led demand through captive distribution.
| Leading Market Players |
|---|
| Foshan Electrical and Lighting Co., Ltd. (FSL) |
| Everlight Electronics Co., Ltd. |
| Nichia Corporation |
| LG Electronics |
| Panasonic Corporation |
| Signify N.V. |
| Opple Lighting Co., Ltd. |
| MLS Co., Ltd. (Forest Lighting) |
| Samsung Electronics |
| Others |
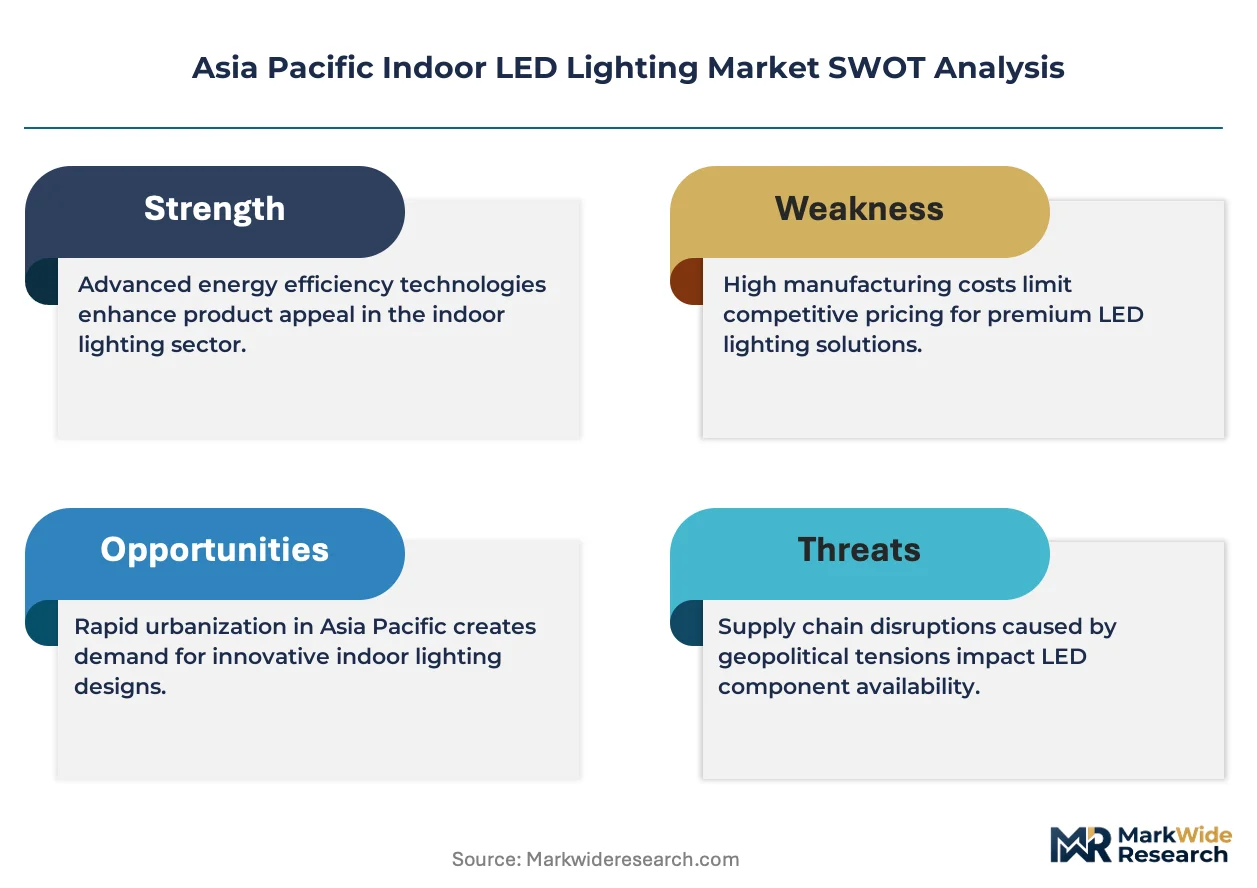
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor's freight rate volatility feeds directly into landed cost spreads between Chinese-manufactured panels and Vietnam-assembled alternatives, compressing margin pools for distributors serving Australia's healthcare retrofit channel while amplifying price differentiation across certification tiers.
Pricing Analysis
Technology-generation pricing gaps separate legacy fluorescent-replacement panels from COB-LED downlights and emerging tunable-white smart systems. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification status and thermal management specifications. Pricing pressure stems from aluminum heat sink cost volatility and driver IC import concentration. Residential retrofit buyers in India's tier-two cities exhibit highest price sensitivity, while Tokyo commercial developers prioritize lumen maintenance warranties over unit cost.
Supply Chain Analysis
Extended payment terms from Taiwanese driver IC suppliers and supply-chain finance facilities anchored in Hong Kong trade credit are restructuring working capital requirements for fixture assemblers. Component sourcing concentrates in China for phosphor-converted LEDs, Taiwan for AC grid-compatible driver electronics, and South Korea for high-CRI chip-on-board arrays. Raw material dependencies span aluminum extrusions for thermal management, rare-earth phosphors for color rendering, and copper winding stock for magnetic components. Single-source vulnerability in Taiwan semiconductor supply creates exposure during regional logistics disruptions. Distribution runs through project-channel integrators in China's Pearl River Delta and electrical distributors in India's metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific indoor LED lighting sits in early-cycle expansion as GB standards enforcement and BIS certification mandates accelerate fixture replacement across commercial real estate portfolios ahead of regulatory deadlines.
For Market Incumbents: Pre-empt margin compression in residential retrofit segments by securing captive aluminum heat sink supply through backward integration into extrusion facilities in Guangdong province. Defend against emerging Vietnamese assemblers by deepening JIS and BIS certification relationships with Tokyo and Delhi-NCR testing laboratories. Channel control through integrated project management services represents the critical defensive lever. For New Entrants and Emerging Players: Build out assembly capacity in Bac Ninh and Hai Phong industrial zones to capture first-mover positioning for ASEAN export markets. Human-centric lighting specifications in Australia's Sydney and Melbourne healthcare precincts offer the most penetrable white-space as facility management firms unbundle maintenance from capital procurement. Direct manufacturer-to-operator service contracting provides the essential go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with underutilized LED fixture divisions and stranded project-channel assets. Long-term viability over the coming decade hinges on regulatory compliance infrastructure and smart platform integration capabilities. Watch for inflection signals in India PLI scheme extension announcements redirecting capital toward domestic chip-on-board packaging.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive AC grid-compatible IC supply reduces Taiwan sourcing vulnerability for high-volume panel manufacturers. |
| JIS Certification Investment | Tokyo and Osaka developer gatekeeping criteria compress qualified supplier pools to certified incumbents. |
| Vietnam Assembly Footprint Expansion | Bac Ninh industrial zone incentives enable diversification beyond China-centric production for ASEAN markets. |
| Human-Centric Lighting Platform Launch | Circadian rhythm tuning with IoT occupancy sensing penetrates healthcare and senior living specifications. |
| Long-Term Service Contracting Model | Sydney healthcare precinct unbundling of maintenance displaces traditional distributor relationships. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with facility managers at Tokyo commercial developments, procurement leads at Mumbai-Pune corridor retail operators, and thermal engineering directors at Pearl River Delta fixture manufacturers. Secondary validation drew from SAMR GB standards filings, BIS certification registries, METI JIS documentation requirements, and customs trade data for LED driver IC imports. Bottom-up shipment estimates by fixture category triangulated against top-down construction spend projections across the analysis window.
Calibration against historical replacement cycles and regulatory enforcement timelines shaped the projection framework. Segmentation dimensions modeled include fixture type, application vertical, technology tier, and end-user category alongside regional regulatory cluster. CAGRs were derived from installed base turnover rates and new-build specification trends. Forecast inputs incorporated aluminum price indices, Taiwan semiconductor foundry utilization rates, and commercial real estate vacancy data.
Stress conditions across raw material cost spikes, Taiwan logistics disruptions, and India PLI scheme implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
UK LED Lighting Market
LED
China LED Market
LED
Mini LED Market
LED
France LED Lighting Market
LED
Bi-Color LED Ring Light Market
LED
Biometrics Infrared LED Market
LED
Pixel Pitch LED Market
LED
Architectural LED Products Market
LED
LED Lamp Market
LED
High Power LED Market
LED
Philippines LED Market
LED
UV-C LED Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
LED High Bay Drivers Market