
 Industrial Transceivers Market | 2026-2036
Industrial Transceivers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Transceivers Market Analysis
Modular form-factor bundling with pre-integrated protocol stacks is consolidating buyer preference away from standalone hardware configurations. Cisco Systems, Inc. leverages its channel dominance in industrial Ethernet to anchor large manufacturing accounts. Infineon Technologies AG specializes in RF transceiver silicon for automotive radar backhaul. Sumitomo Electric Industries, Ltd. controls premium fiber optic module supply for harsh-environment deployments.
Industrial transceivers are bidirectional communication devices that convert electrical signals to optical or RF carriers and back, typically operating across -40°C to +85°C temperature ranges with hermetic sealing against dust and moisture ingress. Their primary purpose is enabling deterministic data exchange between programmable logic controllers, sensors, and actuators in electrically noisy factory floors. Fiber optic product types command the deepest margin pools where link distances exceed two kilometers, while Ethernet variants absorb the highest absolute volume in greenfield smart manufacturing installations. PLC technology segments retain entrenched positions in brownfield process industries, whereas optical technology segments capture accelerated replacement cycles as wavelength-division multiplexing penetrates industrial backbones.
IEC 61000 electromagnetic compatibility standards and IEEE 802.3 Ethernet physical layer specifications govern signal integrity and interoperability certification for industrial transceivers entering European and North American markets. ECHA REACH substance restrictions additionally constrain solder alloys and encapsulant chemistries in modules sold across EU member states. China's GB standards and NMPA-equivalent equipment certification procedures create separate compliance pathways for vendors accessing domestic automation projects. Stakeholders must monitor protocol convergence timelines between Time-Sensitive Networking and existing fieldbus ecosystems to time capacity investments and qualification spending.
Market Dynamics
Deterministic control requirements in automotive and chemical manufacturing are compressing transceiver replacement cycles as wavelength-division multiplexing penetrates industrial backbones. IEEE 802.3 standards evolution and IEC 61000 electromagnetic compatibility mandates are reshaping procurement specifications across factory automation networks.
Growth Catalysts
- Single-mode fiber deployment:Automotive plants in Germany's Ruhr industrial cluster are installing long-haul optical links for deterministic PLC-to-sensor communication. This retrofit wave is displacing legacy serial infrastructure.
- Time-Sensitive Networking convergence:Manufacturing automation networks are migrating from fieldbus ecosystems toward Ethernet-based deterministic protocols. IEC 61000 compliance requirements are accelerating this protocol stack consolidation.
- Harsh-environment certification demand:Chemical processing facilities require hermetically sealed transceivers operating across extended temperature ranges. Dust and moisture ingress protection specifications are tightening procurement criteria.
Market Restraints
- RF silicon supply concentration:Automotive radar backhaul transceivers depend on concentrated RF semiconductor foundry capacity. Geographic concentration in East Asian wafer fabrication creates vulnerability.
- REACH substance compliance costs:ECHA restrictions on solder alloys and encapsulant chemistries constrain module designs for EU markets. Reformulation cycles extend qualification timelines.
- Copper Ethernet substitution:Short-distance factory floor applications under two kilometers increasingly favor unshielded twisted-pair over fiber optic links. This compresses margin pools in volume segments.
Strategic Opportunities
- Modular protocol bundling:Pre-integrated software stacks combined with hardware modules are creating preference shifts away from standalone configurations. Channel partners are capturing value through solution packaging.
- China domestic automation:GB standards certification and NMPA-equivalent equipment procedures create separate vendor pathways for accessing state-sponsored smart manufacturing projects.
- Wavelength-division multiplexing penetration:Industrial backbone upgrades are enabling multi-channel optical transmission. This technology convergence is opening premium module opportunities in brownfield process industries.
Industry Challenges
- Legacy system integration complexity:Brownfield PLC environments require protocol translation layers that increase deployment cost and commissioning time. Retrofit projects face extended validation cycles.
- Electromagnetic compatibility certification bottlenecks:IEC 61000 testing for signal integrity across noisy factory floors demands specialized lab capacity. Qualification queue delays are extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Transceivers Market |
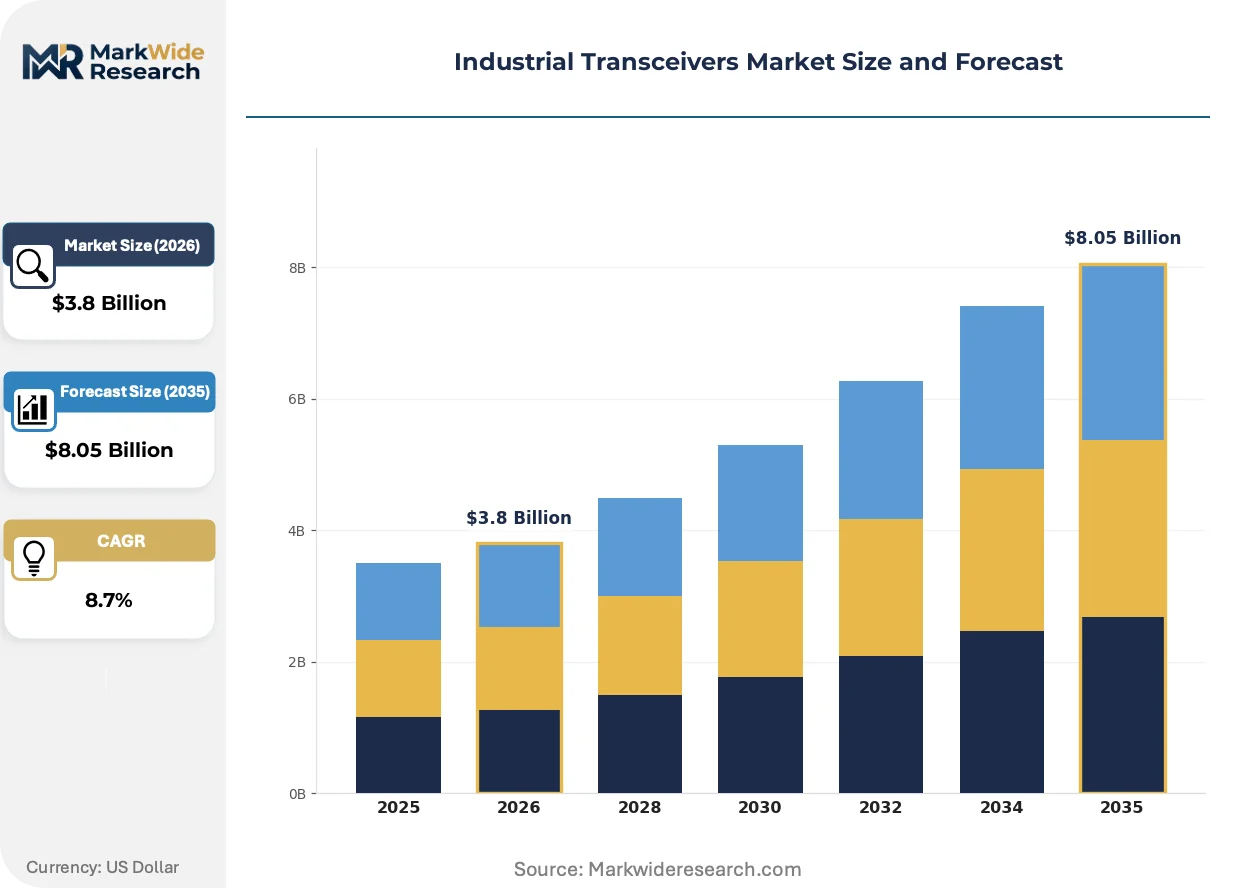
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethernet, Serial, Fiber Optic, Wi-Fi Technology: PLC, RF, Optical, Digital End User: Manufacturing, Automotive, Aerospace, Oil & Gas Form Factor: Modular, Rack-mounted, Compact, Standalone |
| Companies Covered | Cisco Systems, Inc., Analog Devices, Inc., Renesas Electronics Corporation, Infineon Technologies AG, Fujitsu Limited, Eaton Corporation PLC, Accelink Technology Co. Ltd., Sumitomo Electric Industries, Ltd., Coherent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Transceivers Market Emerging Trajectories
Industrial transceiver architecture is bifurcating between hardened fiber modules for deterministic backbones and cost-optimized Ethernet variants for greenfield smart manufacturing installations. This divergence is forcing vendors to specialize rather than span both tiers.
Co-packaged optics is electrifying transceiver density in programmable logic controller backplanes. Automotive and chemical manufacturers in Germany are piloting these integrated photonic assemblies for sub-microsecond latency control loops. The technology is compressing form-factor requirements while multiplying port counts per rack unit.
EU F-Gas Regulation phase-down schedules are constraining refrigerant-dependent thermal management in outdoor-rated transceiver housings. Module vendors are redesigning passive cooling architectures for base stations and remote terminal units. Chemical plants in the Ruhr cluster are specifying these fluorinated-gas-free alternatives to preempt compliance deadlines.
Specification-driven procurement now dominates large manufacturing accounts as channel partners bundle pre-qualified hardware with protocol stacks. System integrators are displacing direct OEM relationships in automotive verticals. Germany's automotive sector exhibits the most pronounced shift toward solution-based contracting with multi-year service attachments.
Industrial Transceivers Market Segmentation
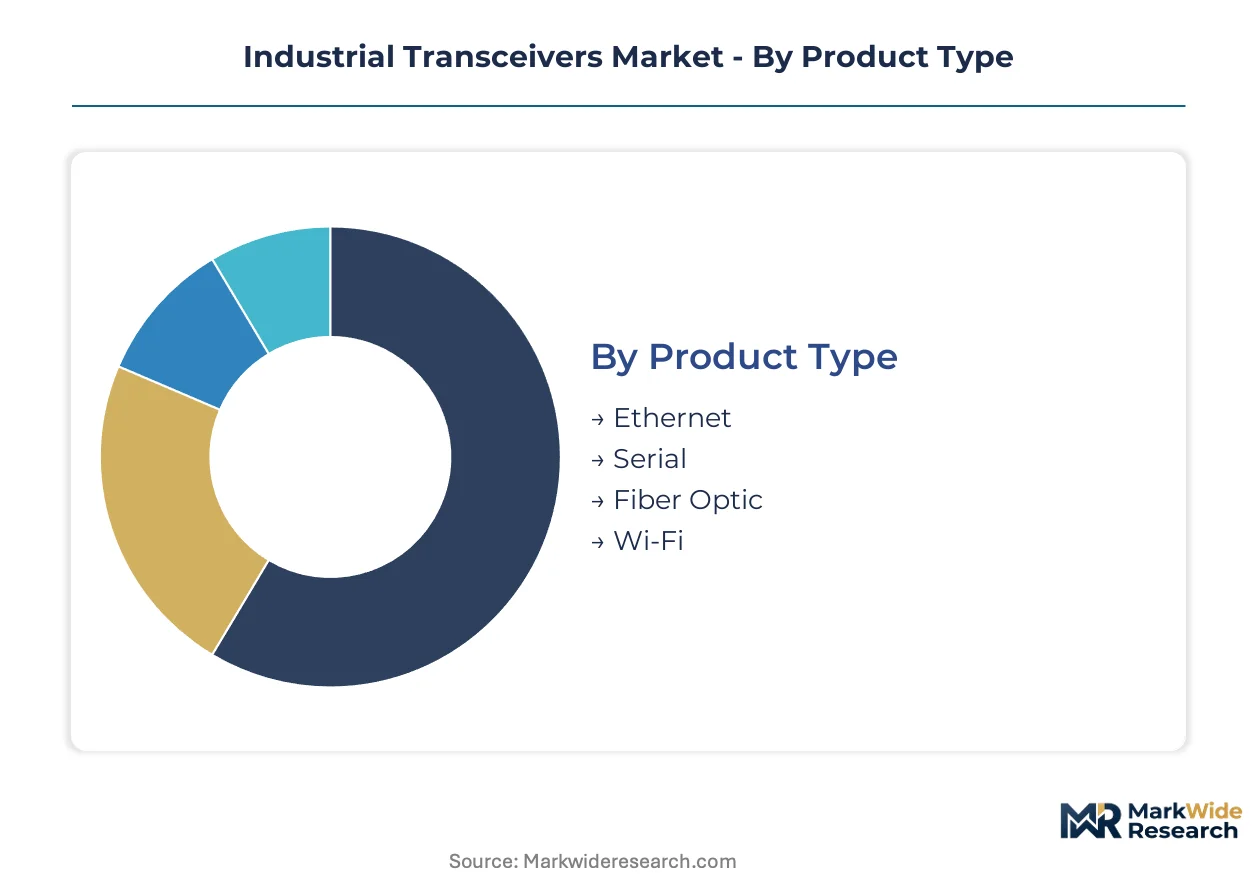
Industrial transceiver procurement patterns diverge sharply across product architectures, with fiber optic modules commanding premium positioning in deterministic backbones while Ethernet variants absorb volume in greenfield installations. Technology maturity and end-use environmental requirements create distinct margin tiers that reshape vendor specialization strategies.
Product Type:
Buyers differentiate primarily by link distance requirements and electromagnetic immunity thresholds, with harsh-environment specifications driving fiber adoption and cost-sensitive factory floors favoring copper alternatives.
- Fiber Optic:Single-mode and multi-mode modules convert electrical signals to optical carriers across hermetically sealed enclosures rated for -40°C to +85°C operation. Demand concentrates in Germany's Ruhr industrial cluster, where automotive and chemical plants deploy wavelength-division multiplexing for deterministic PLC-to-sensor communication exceeding two kilometers.
- Ethernet:Copper-based transceivers implementing IEEE 802.3 physical layer specifications dominate greenfield smart manufacturing installations with sub-kilometer link distances. Unshielded twisted-pair configurations are displacing legacy fieldbus infrastructure in brownfield retrofits where electromagnetic compatibility certification timelines compress procurement decisions.
- Serial:Legacy RS-232/RS-485 converters maintain entrenched positions in process industries with extended equipment replacement cycles.
- Wi-Fi:Industrial wireless transceivers enable mobile equipment connectivity in warehouse automation and portable diagnostic applications.
Volume sits with Ethernet; growth tilts toward fiber optic modules as wavelength-division multiplexing penetrates industrial backbones.
Technology:
Technology selection tracks the divergence between electromechanical reliability requirements in process industries and solid-state integration imperatives in discrete manufacturing.
- Optical:Photonic assemblies leveraging wavelength-division multiplexing enable multi-channel transmission across single fiber strands. Co-packaged optics in PLC backplanes are compressing form factors while multiplying port density per rack unit in German automotive pilot programs.
- RF:Radio frequency transceivers for automotive radar backhaul depend on concentrated semiconductor foundry capacity in East Asian wafer fabrication hubs. Supply concentration creates procurement vulnerability for deterministic control applications.
- PLC:Programmable logic controller-integrated transceivers retain entrenched positions in chemical processing and continuous flow manufacturing with decade-long equipment lifecycles.
- Digital:Software-defined transceiver architectures enable protocol reconfiguration without hardware replacement in mixed-fieldbus environments.
Maturity concentrates in PLC; expansion tilts most steeply toward optical as industrial backbone upgrades accelerate.
End User:
End-use verticals separate by environmental severity, with outdoor exposure and explosive atmosphere certifications creating distinct procurement qualification pathways.
- Automotive:Vehicle assembly plants and component suppliers demand deterministic latency below one millisecond for robotic welding and paint application cells. Germany's automotive sector exhibits pronounced shifts toward solution-based contracting with multi-year service attachments.
- Manufacturing:Discrete and process manufacturing operations span the widest specification range, from dust-tight IP67 modules in food processing to explosion-proof housings in pharmaceutical batch operations.
- Oil & Gas:Upstream and downstream facilities require IEC 61000 electromagnetic compatibility certification combined with salt spray and vibration resistance for offshore platform deployment.
- Aerospace:MRO facilities and assembly operations specify extended temperature ranges and conformal coating for avionics test bench integration.
Procurement volume clusters in manufacturing; specification complexity peaks in oil and gas applications.
Form Factor:
Physical packaging preferences reflect the tension between rack density optimization in centralized control rooms and distributed I/O architectures at the network edge.
- Modular:Hot-swappable transceiver modules with pre-integrated protocol stacks are consolidating buyer preference away from standalone hardware configurations. Channel partners capture value through solution packaging that bundles pre-qualified hardware with software stacks.
- Compact:Miniaturized transceivers for distributed I/O nodes enable cabinet-free installation directly on production machinery, reducing cable runs in space-constrained automotive body shops.
- Rack-mounted:Standardized 19-inch chassis configurations dominate centralized control room deployments with managed power and cooling infrastructure.
- Standalone:Enclosed units with integrated power supplies persist in retrofit applications where existing cabinet infrastructure cannot accommodate blade server architectures.
Deployment scale favors modular designs; edge computing architectures are accelerating compact form factor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial cluster anchors transceiver demand through automotive and chemical plant automation retrofits. China's Yangtze River Delta special economic zones concentrate smart manufacturing investments requiring deterministic fiber links. Japan's Kanto region drives precision electronics applications with sub-microsecond latency requirements.
United States
Automotive assembly plants in Michigan and Tennessee deploy single-mode fiber transceivers for robotic welding cell synchronization. FCC Part 15 emissions standards govern industrial wireless configurations in factory automation networks. Houston's petrochemical corridor specifies IEC 61000-certified modules for explosion-proof environments in downstream processing facilities.
Germany
Chemical manufacturers in North Rhine-Westphalia replace legacy serial infrastructure with wavelength-division multiplexing backbones. EU F-Gas Regulation phase-down schedules accelerate passive cooling redesigns for outdoor-rated transceiver housings. Stuttgart's automotive engineering cluster pilots co-packaged optics in PLC backplanes for paint application deterministic control.
China
State-sponsored smart manufacturing projects in Shenzhen and Shanghai mandate GB standards-certified transceivers for domestic automation procurement. MIIT equipment certification procedures create separate vendor qualification pathways from Western markets. Yangtze River Delta electronics assemblers absorb the highest Ethernet transceiver volumes in greenfield installations.
Japan
Precision machinery builders in Nagoya specify hermetically sealed fiber modules for dust-tight semiconductor cleanroom environments. METI industrial digitization incentives compress replacement cycles in brownfield process industries. Osaka-based automotive component suppliers demand sub-microsecond latency transceivers for robotic quality inspection cells.
South Korea
Memory and display panel fabrication plants in Gyeonggi Province require electromagnetic immunity-rated transceivers for electrically noisy cleanroom floors. MFDS-equivalent equipment certification aligns with IEC standards for export-oriented manufacturing. Busan's shipbuilding cluster deploys salt-spray-resistant modules for offshore platform communication backhaul.
Industrial Transceivers Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base stratifies between channel-dominant networking equipment providers, semiconductor fabricators with captive RF silicon capacity, and premium fiber module specialists serving harsh-environment deployments. Three archetypes dominate: diversified industrial electronics conglomerates leveraging cross-selling, RF semiconductor specialists controlling foundry-dependent automotive radar backhaul, and optical component houses with hermetic sealing expertise. Competitive moves concentrate on modular protocol bundling partnerships and qualification acceleration for regional certification pathways.
Among networking equipment providers, Cisco Systems, Inc. anchors channel relationships with large manufacturing accounts through pre-integrated solution packaging. RF semiconductor specialists include Infineon Technologies AG, which occupies a position within automotive radar transceiver silicon supply. Optical component houses exemplified by Sumitomo Electric Industries, Ltd. represent premium fiber module supply for extended temperature range deployments. These three companies illustrate the technology specialization divergence forcing vendor portfolio choices between fiber backbone and Ethernet edge architectures.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Analog Devices, Inc. |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Fujitsu Limited |
| Eaton Corporation PLC |
| Accelink Technology Co. Ltd. |
| Sumitomo Electric Industries, Ltd. |
| Coherent, Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Japan and Germany anchor premium fiber module supply, disciplining pricing through hermetic sealing expertise while channel-dominant conglomerates absorb margin compression in Ethernet volume tiers. This ownership fragmentation creates divergent pricing power between harsh-environment certification holders and commodity hardware assemblers.
Pricing Analysis
Margin tightening in Ethernet transceivers reflects copper substitution pressure for sub-kilometer factory floor links. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61000-certified modules from industrial-grade and commercial-temperature alternatives. Price differentiation hinges on hermetic sealing grade and REACH compliance certification. Automotive buyers in Germany's Ruhr cluster exhibit lowest price sensitivity due to deterministic control requirements, while greenfield smart manufacturing installations in China absorb highest volume at compressed margins.
Supply Chain Analysis
Photonic chip supply rests on Japanese specialty component producers and Taiwanese optical foundry capacity. RF silicon draws from concentrated East Asian wafer fabrication hubs in Taiwan, South Korea, and Japan. Raw material dependencies include indium phosphide substrates, hermetic sealing alloys, and fluorinated-gas-free thermal management compounds. Single-source vulnerability concentrates in automotive radar backhaul transceiver foundry allocation. Distribution runs through system integrators and industrial Ethernet channel partners with pre-integrated protocol stack bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol stack consolidation and certification cost escalation are forcing weaker hardware-only vendors toward exit or acquisition, consolidating viable competitors around solution-architecture capabilities.
For Market Incumbents: Hedge RF silicon supply exposure through captive foundry partnerships or dual-source qualification in Taiwan and South Korea. Deepen backward integration into optical component supply for wavelength-division multiplexing modules to defend margin position against pure-play fiber specialists. Accelerate IEC 61000 pre-certification investments to compress qualification queue delays for automotive accounts. For New Entrants and Emerging Players: Direct-to-system-integrator digital channels bypass entrenched OEM relationships in Germany's automotive retrofit wave. Target China's Yangtze River Delta greenfield installations where GB standards certification creates separate vendor pathways from Western incumbents. White-space exists in fluorinated-gas-free thermal management modules for EU F-Gas Regulation compliance deadlines. For Investors and Strategic Acquirers: Distressed-cycle entries favor hermetic sealing specialists with automotive certification portfolios in Germany and Japan. Long-term viability centers on protocol convergence timing between Time-Sensitive Networking and fieldbus ecosystems. Watch co-packaged optics adoption curves in PLC backplanes as inflection signal for premium module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Component Supply | Captive indium phosphide sourcing secures margin pools in wavelength-division multiplexing modules for Ruhr chemical plants. |
| Dual-Source RF Foundry Qualification | Geographic diversification of automotive radar backhaul silicon mitigates East Asian wafer concentration risk. |
| Pre-Integrated Protocol Stack Bundling | Channel partners capture solution value by combining IEEE 802.3 hardware with Time-Sensitive Networking software layers. |
| Passive Cooling Architecture Redesign | Fluorinated-gas-free thermal management modules preempt EU F-Gas Regulation phase-down deadlines for outdoor-rated deployments. |
| GB Standards Certification Investment | MIIT equipment procedures unlock state-sponsored smart manufacturing procurement in Shenzhen and Shanghai special economic zones. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial transceivers analysis. Primary interviews with plant engineers, OEM procurement teams, system integration specialists, and aftermarket service heads combined with IEC standards documentation, IEEE 802.3 specification releases, and ECHA REACH substance restriction updates. Bottom-up transceiver shipment tallies triangulated against top-down manufacturing automation capital expenditure estimates across automotive, chemical, and discrete manufacturing verticals.
Data-stream reconciliation across product type, technology segment, end-use vertical, and form factor dimensions shaped projection outputs over the analysis window. CAGRs derived from replacement cycle compression rates, wavelength-division multiplexing penetration curves, and protocol migration timelines between fieldbus and Time-Sensitive Networking ecosystems. Forecast inputs incorporated automotive production schedules, chemical processing capacity additions, and smart manufacturing policy disbursement patterns.
Inputs from plant-level automation directors and channel partner inventory systems were available through the study window; gaps in brownfield PLC retrofit project pipelines introduce uncertainty bands. Forecasts reflect documented assumptions regarding protocol convergence velocity and certification queue durations. Supply concentration in East Asian wafer fabrication and REACH substance restriction reformulation cycles warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
Asia Pacific Enterprise Routers Market
Telecom Hardware
Repeaters Market
Telecom Hardware
OTN Hardware Market
Telecom Hardware
Global Virtualized Evolved Packet Core (VEPC) Market
Telecom Hardware
Parabolic Antenna Market
Telecom Hardware
Europe Zero-Touch Provisioning Market
Telecom Hardware
Digital TV Soc Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Base Station Market
Telecom Hardware
Subscriber Identity Module (SIM) Market
Telecom Hardware
Voice Communication Equipment Market
Telecom Hardware
5G BTS Antenna Market
Telecom Hardware
Africa Small Cell Market
Telecom Hardware
Microwave Antenna Market
Telecom Hardware
5G Temperature-Compensated Crystal Oscillator (TCXO) Market
Telecom Hardware
5G Radio Unit Market