
 Zigbee Enabled Devices Market | 2026-2036
Zigbee Enabled Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Zigbee Enabled Devices Market Outlook
Utility and telecom buyer concentration is hardening across the Zigbee enabled devices landscape as smart metering and broadband service providers consolidate vendor lists for home area network deployments. Amazon leverages its Alexa ecosystem to anchor consumer-facing device interoperability across lighting and security categories. Texas Instruments Incorporated sustains technology leadership through dedicated Zigbee radio frequency system-on-chip portfolios optimized for mesh network density. Silicon Laboratories Inc. competes on protocol stack integration, offering combined Zigbee and Thread silicon that reduces original equipment manufacturer design cycles.
Zigbee enabled devices are low-power wireless hardware operating on IEEE 802.15.4 physical radio layers at 2.4 GHz with data rates up to 250 kbps, purpose-built for mesh network topologies where each node relays packets across multi-hop paths for home automation, industrial sensing, and energy management applications. Smart lighting dominates product type revenue as retrofit LED demand couples with utility rebate programs, while home automation accelerates fastest through thermostat and lock integration with voice platforms. Mesh networking technology anchors infrastructure-grade deployments where self-healing topology requirements exceed point-to-point wireless reliability.
The Zigbee Alliance's certification program interoperates with Ecodesign standby power regulations from the European Commission and FCC Part 15 unlicensed device rules in the United States, creating compliance thresholds that filter out uncertified module suppliers. China's MIIT radio transmission equipment type approval adds a third certification layer for manufacturers targeting the country's utility smart grid procurement. Stakeholders must monitor protocol evolution toward Zigbee Direct and Matter convergence to determine whether silicon investments require multi-protocol stack support or dedicated legacy optimization.
Market Dynamics
Mesh network density requirements from utility smart grid deployments are forcing silicon vendors to optimize radio frequency system-on-chips for multi-hop reliability rather than point-to-point cost minimization.
Growth Catalysts
- EU Ecodesign standby power limits:The European Commission's frameworks mandate maximum standby consumption that favors ultra-low-power Zigbee implementations over Wi-Fi alternatives in lighting and sensor hardware.
- Utility demand response programs:Germany, China, and the United States operate procurement corridors where smart meter rollouts create captive demand for home area network devices with certified interoperability.
- Matter protocol convergence:The Zigbee Alliance's certification program now interoperates with Matter specifications, enabling single-module designs that reduce original equipment manufacturer qualification cycles.
Market Restraints
- Silicon supply concentration:Dedicated Zigbee radio frequency system-on-chip production concentrates among a limited vendor base, creating allocation risk during foundry capacity constraints.
- MIIT type approval timelines:China's radio transmission equipment certification adds six to nine months to product launch schedules for manufacturers targeting utility procurement windows.
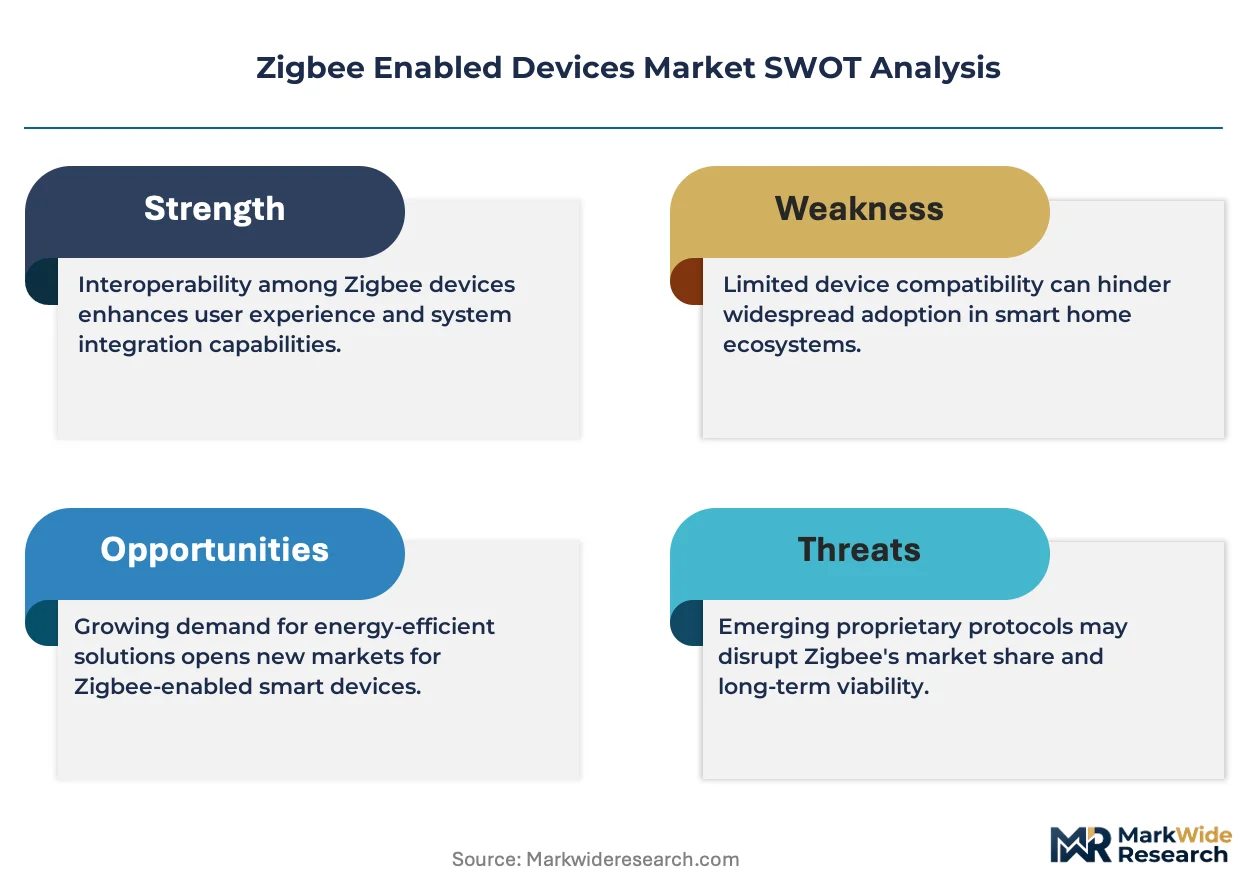
- Thread protocol substitution:Silicon Laboratories and competitors now bundle Thread stack support with Zigbee, enabling buyers to migrate mesh infrastructure to IP-native alternatives without hardware replacement.
Strategic Opportunities
- Industrial sensing white space:Manufacturing facilities in Germany and the United States remain underpenetrated for predictive maintenance sensor networks using IEEE 802.15.4 physical layers.
- Zigbee Direct specification:The Alliance's phone-to-device communication standard eliminates hub dependency, opening retail channels where consumers previously rejected bridge hardware costs.
- FCC Part 15 unlicensed rules:Recent clarifications on 2.4 GHz power spectral density enable higher-range outdoor applications for agricultural monitoring and campus energy management.
Industry Challenges
- Multi-protocol stack engineering scarcity:Firmware developers capable of optimizing concurrent Zigbee, Thread, and Bluetooth Low Energy operation command premium compensation and extended recruitment timelines.
- Certification queue congestion:The Zigbee Alliance's testing backlog stretches to fourteen weeks for complex mesh router implementations, compressing product launch windows against seasonal procurement cycles.
- Legacy hub integration friction:First-generation home automation controllers lack over-the-air update capability, fragmenting the installed base and complicating unified application development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zigbee Enabled Devices Market |
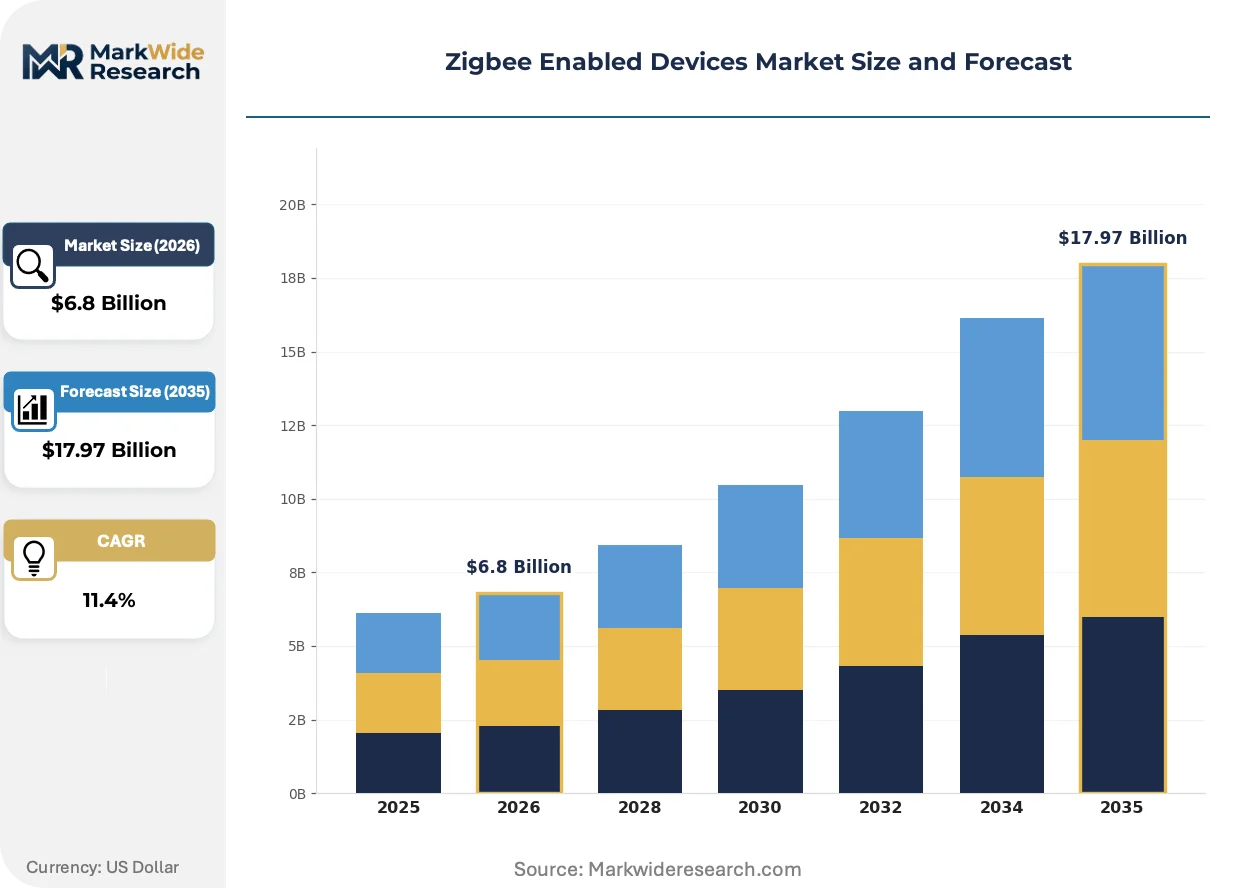
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Home Automation, Industrial Monitoring, Healthcare Devices Application: Energy Management, Home Security, Environmental Monitoring, Asset Tracking Technology: Mesh Networking, Low Power Consumption, Device Interoperability, Wireless Sensor Networks End User: Residential, Commercial, Industrial, Healthcare |
| Companies Covered | Microchip Technology Inc., Philips Lighting (Signify), Silicon Laboratories Inc., Amazon, Samsung Electronics, Texas Instruments Incorporated, Digi International Inc., STMicroelectronics, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zigbee Enabled Devices Market Strategic Shifts
Protocol convergence and regulatory energy mandates are compressing hardware design cycles while expanding the addressable device categories beyond traditional home automation into infrastructure-grade sensing.
Multi-protocol silicon is expanding into utility metering and industrial monitoring applications where single-radio designs previously dominated procurement specifications. Water and gas utilities in Germany and the United States now specify combined Zigbee and Thread module support to future-proof fifteen-year deployment horizons. This technology expansion is compressing vendor margins for dedicated Zigbee-only offerings while rewarding stack integration investments.
REACH substance restrictions and RoHS amendments are phasing out specific solder alloys and flame retardants used in legacy module substrates. European original equipment manufacturers must qualify alternative materials by 2026 to maintain CE marking eligibility for lighting and thermostat products. The industrial sensing segment faces the steepest reformulation burden due to outdoor temperature cycling requirements that stress new material interfaces.
Voice platform integration now dictates hardware certification priorities rather than standalone hub compatibility. Amazon's Alexa ecosystem and competing platforms bundle Zigbee radios directly into smart speakers, displacing separate bridge purchases for lighting and lock categories. This channel consolidation concentrates procurement leverage among platform operators in the United States and Germany, forcing module vendors to prioritize their interoperability test suites over independent certification paths.
Zigbee Enabled Devices Market Segmentation
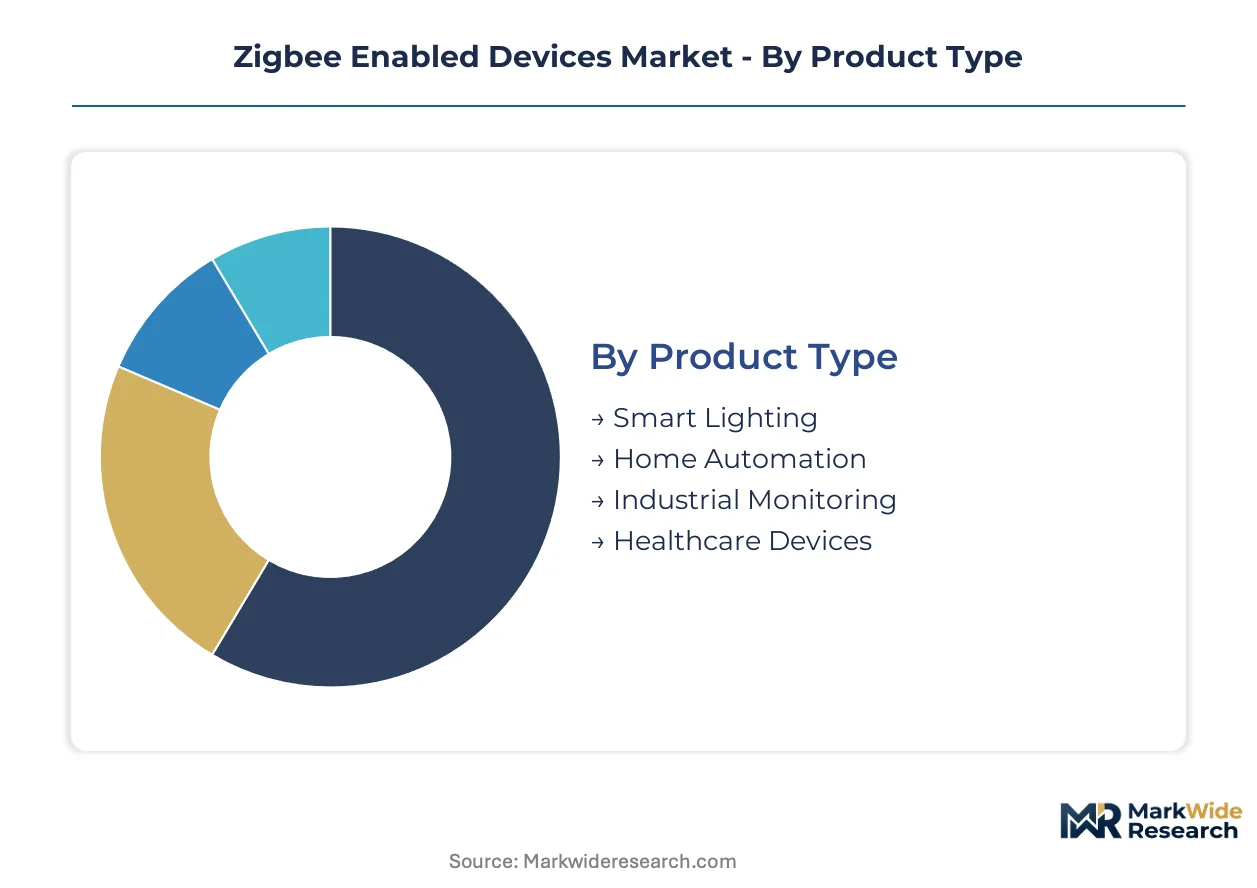
Segmentation in the Zigbee enabled devices market reveals how protocol specifications, power budgets, and interoperability requirements fragment procurement across utility, consumer, and industrial channels. Buyers prioritize different performance thresholds—mesh density for smart grid operators, standby power for residential retrofits, and sensor range for agricultural deployments.
Product Type:
Standardization dominates lighting modules while home automation demands configurable firmware stacks for platform-specific integration.
- Smart Lighting:Retrofit LED controllers and connected luminaires operate on IEEE 802.15.4 physical layers with sub-50mW standby draw. Procurement concentrates in Germany and the United States where utility rebate programs subsidize mesh-enabled bulb replacements. Ecodesign standby power limits from the European Commission filter out Wi-Fi alternatives in volume tenders.
- Home Automation:Thermostats, smart locks, and motorized shades require Zigbee 3.0 stack certification for voice platform interoperability. Amazon's Alexa ecosystem and competing smart speakers bundle radios directly, displacing separate bridge hardware in residential channels. FCC Part 15 unlicensed device rules govern 2.4 GHz transmission power for these consumer-facing deployments.
- Industrial Monitoring:Predictive maintenance sensor networks use IEEE 802.15.4 for vibration and temperature telemetry in manufacturing facilities.
- Healthcare Devices:Patient monitoring and asset tracking hardware prioritizes ultra-low power consumption for multi-year battery life in clinical settings.
Most installed capacity flows through Smart Lighting. Expansion is steepest in Home Automation.
Application:
Volume scales with utility procurement cycles while margin concentrates in security integrations requiring certification queue prioritization.
- Energy Management:Smart meter home area network interfaces and demand response load controllers form the procurement backbone for utility-led deployments. Germany, China, and the United States operate captive demand corridors where certified interoperability gates vendor selection. China's MIIT radio transmission equipment type approval adds six to nine months to product launch schedules for manufacturers targeting these windows.
- Home Security:Door and window sensors, motion detectors, and connected sirens integrate with professional monitoring services and DIY platforms. Matter protocol convergence enables single-module designs that reduce original equipment manufacturer qualification cycles across lighting and lock categories.
- Environmental Monitoring:Indoor air quality sensors and HVAC optimization hardware serve commercial building automation retrofits.
- Asset Tracking:Warehouse inventory tags and healthcare equipment locators leverage mesh density for campus-wide coverage.
Energy Management absorbs the largest procurement volumes. Home Security climbs the fastest as platform operators consolidate vendor lists.
Technology:
Silicon vendor R&D allocation splits between mesh density optimization for infrastructure and multi-protocol stack integration for future-proofing.
- Mesh Networking:Self-healing multi-hop topologies where each node relays packets across paths up to 30 hops deep anchor utility smart grid and campus energy deployments. Texas Instruments and Silicon Laboratories optimize radio frequency system-on-chips for reliability rather than point-to-point cost minimization. FCC Part 15 clarifications on 2.4 GHz power spectral density enable higher-range outdoor applications.
- Low Power Consumption:Sub-1mA receive current and sub-15mA transmit current specifications enable multi-year battery operation in sensor endpoints. REACH substance restrictions and RoHS amendments are phasing out legacy solder alloys and flame retardants, forcing material requalification by 2026.
- Device Interoperability:Zigbee Alliance certification and Matter specification alignment reduce fragmentation in retail channels.
- Wireless Sensor Networks:Distributed sensing architectures for agricultural monitoring and industrial predictive maintenance.
Mesh Networking carries the heaviest infrastructure deployment. Device Interoperability is gaining share fastest through protocol convergence mandates.
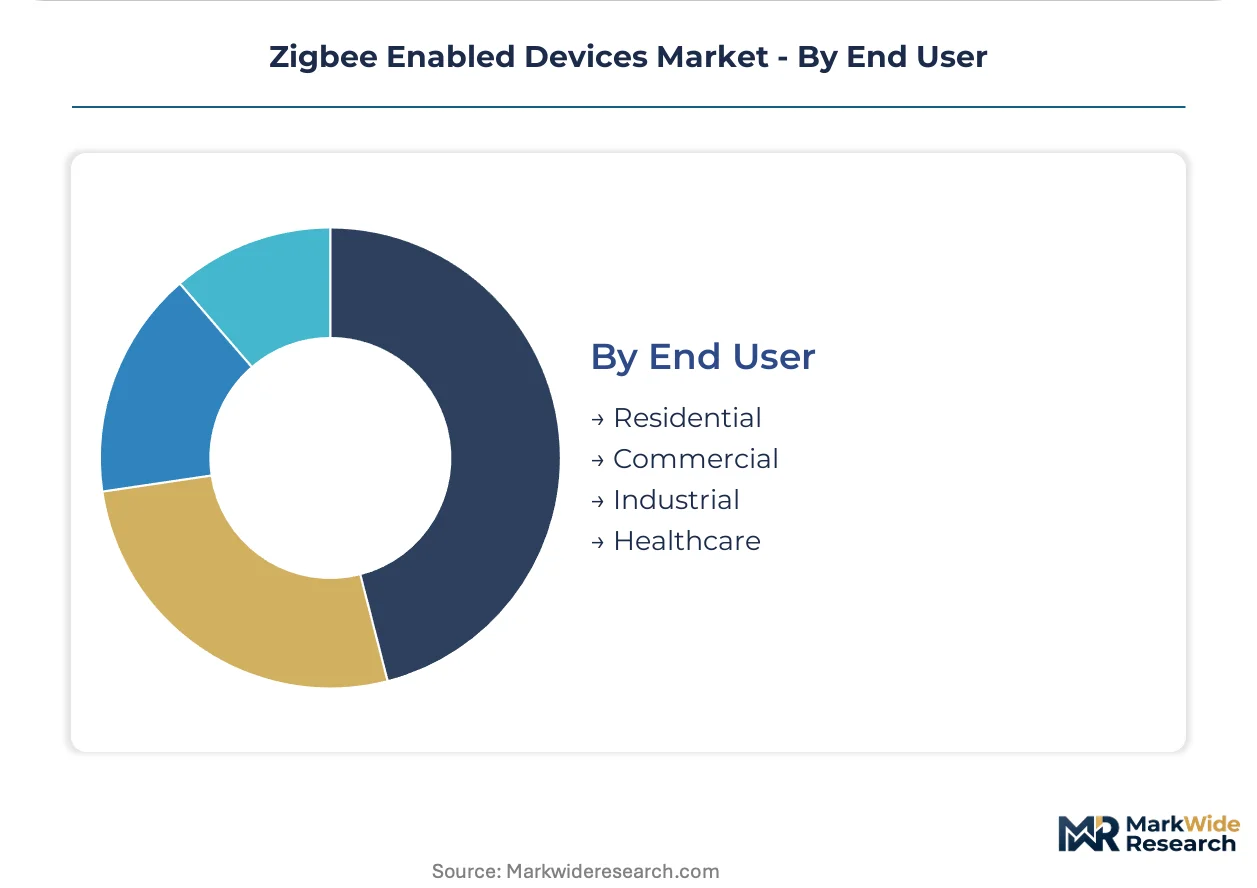
End User:
Customer procurement authority ranges from individual consumers through platform operators to centralized utility purchasing departments.
- Residential:Individual consumers and property managers purchase through retail channels and smart home platform bundles. Voice platform integration now dictates hardware certification priorities rather than standalone hub compatibility. Zigbee Direct specification eliminates bridge dependency, opening segments where consumers previously rejected hardware costs.
- Commercial:Facility managers and building automation integrators specify lighting and environmental monitoring for office and retail footprints. Germany and the United States show underpenetration for predictive maintenance sensor networks using IEEE 802.15.4 physical layers.
- Industrial:Manufacturing operations and utility infrastructure operators mandate fifteen-year deployment horizons with multi-protocol module support.
- Healthcare:Hospital systems and aged care facilities deploy patient monitoring and equipment tracking with stringent reliability requirements.
Residential channels move the highest unit volumes. Industrial segments show the steepest expansion trajectory through utility smart grid procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's utility-led smart meter corridors contrast with China's MIIT certification timelines, revealing how regulatory velocity shapes deployment windows across major demand centers.
United States
Utility demand response programs in California and Texas drive home area network procurement through FERC-enabled grid modernization mandates. FCC Part 15 unlicensed device rules govern 2.4 GHz transmission power for consumer-facing deployments. The Pacific Northwest cluster concentrates smart lighting manufacturing serving rebate-program channels.
Germany
Ecodesign standby power limits from the European Commission filter out Wi-Fi alternatives in volume tenders for retrofit LED controllers. REACH substance restrictions phase out legacy solder alloys by 2026, forcing material requalification. Bavaria's industrial automation corridor shows underpenetration for predictive maintenance sensor networks.
China
MIIT radio transmission equipment type approval adds six to nine months to product launch schedules for manufacturers targeting utility procurement windows. Dual carbon goals accelerate smart grid investments in provincial deployments. The Yangtze River Delta concentrates module fabrication serving domestic and export demand.
Japan
METI standards harmonization enables cross-border certification with European frameworks, reducing OEM qualification cycles. Building energy management retrofits in commercial real estate create demand for environmental monitoring hardware. The Kanto region anchors platform operator procurement for voice-integrated home automation.
United Kingdom
Ofcom spectrum management aligns with EU Ecodesign frameworks post-transition, maintaining standby power compliance pathways. Smart meter rollout delays have compressed vendor selection windows for home area network suppliers. London's property management sector drives commercial building automation specifications.
Zigbee Enabled Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Zigbee enabled devices landscape, creating tiered pressure on module pricing and certification prioritization. Texas Instruments and Silicon Laboratories anchor the semiconductor layer with dedicated radio frequency system-on-chip portfolios. Strategic moves concentrate on multi-protocol stack integration and Matter specification alignment to reduce OEM design cycles.
Among diversified technology conglomerates, Amazon and Samsung Electronics exemplify platform-operator archetypes that bundle Zigbee radios directly into smart speakers and home appliances, displacing separate bridge hardware in residential channels. STMicroelectronics and NXP Semiconductors N.V. occupy positions within the European semiconductor tier, leveraging existing microcontroller customer relationships to cross-sell wireless connectivity solutions.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Philips Lighting (Signify) |
| Silicon Laboratories Inc. |
| Amazon |
| Samsung Electronics |
| Texas Instruments Incorporated |
| Digi International Inc. |
| STMicroelectronics |
| NXP Semiconductors N.V. |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions and RoHS amendments are gating qualified module substrate supply while segmenting pricing tiers between CE-marked premium hardware and uncertified economy alternatives. Manufacturers face material requalification costs by 2026 that filter out smaller module vendors from utility procurement corridors in Germany and the United States.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for IEEE 802.15.4 radio frequency system-on-chips. Three-tier pricing structure across premium, standard, and economy levels separates Zigbee Alliance-certified mesh routers from uncertified endpoints and multi-protocol silicon bundles. Cost compression in standard-tier modules is intensifying because Silicon Laboratories and competitors now bundle Thread stack support without hardware premiums. Utility procurement departments in Germany show lowest price sensitivity while residential retail channels in the United States absorb the steepest discount pressure.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific to European distribution hubs is compressing margins for module vendors without captive assembly capacity. Semiconductor fabrication concentrates in Taiwan, South Korea, and China while final module assembly clusters in the Yangtze River Delta and Shenzhen corridor. Raw material dependencies span gallium arsenide substrates, 2.4 GHz RF front-end components, and halogen-free PCB laminates. Single-source vulnerability in Zigbee-certified radio frequency system-on-chip supply creates allocation risk during foundry capacity constraints. Distribution runs through original equipment manufacturer direct procurement for utility volumes and electronics distributors for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's MIIT certification timelines and Germany's Ecodesign compliance windows creates cost and timing differentials for manufacturers with dual-qualification capabilities.
For Market Incumbents: Deploy multi-protocol stack integration as the primary defensive lever against Thread protocol substitution threats from Silicon Laboratories and competing silicon vendors. Texas Instruments should accelerate Zigbee Direct specification support to neutralize hub-dependency elimination as a channel threat. Backward integration into gallium arsenide substrate supply buffers raw material volatility while captive certification testing capacity compresses fourteen-week Zigbee Alliance queue delays for mesh router implementations. For New Entrants and Emerging Players: Industrial sensing white space in Bavaria's automation corridor offers the most penetrable entry point for predictive maintenance sensor networks using IEEE 802.15.4 physical layers. Water and gas utilities in Germany and the United States specify fifteen-year deployment horizons with multi-protocol module support that legacy vendors underweight. A technology-first wedge through Zigbee Direct-enabled phone-to-device communication eliminates bridge hardware cost objections in residential retail channels. For Investors and Strategic Acquirers: Roll-up economics work for industrial sensing specialists because manufacturing facilities in Germany and the United States remain underpenetrated for mesh-enabled predictive maintenance networks. Long-term viability across the analysis window hinges on protocol convergence positioning toward Matter specification alignment. Acquisition targets should demonstrate Zigbee Alliance certification queue prioritization relationships and multi-protocol firmware engineering teams. The signal to watch is FCC Part 15 clarifications on 2.4 GHz power spectral density enabling outdoor agricultural monitoring applications.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Silicon Integration | Silicon Laboratories bundles Thread with Zigbee to reduce OEM design cycles for utility metering. |
| Zigbee Direct Specification Adoption | Phone-to-device communication eliminates hub dependency, opening retail channels previously closed by bridge costs. |
| Matter Certification Alignment | Single-module designs reduce qualification cycles across lighting and lock categories for Amazon Alexa ecosystem integration. |
| Industrial Sensing White Space Expansion | Predictive maintenance networks in Bavaria and US manufacturing corridors offer underpenetrated deployment opportunities. |
| REACH/RoHS Material Requalification | Alternative solder alloy and flame retardant qualification by 2026 maintains CE marking eligibility for European lighting tenders. |
Study Parameters
Bottom-up utility and smart home platform modeling reconciled against top-down silicon vendor shipment tracking forms the analytical core. Primary interviews with smart grid procurement officers, OEM product managers, Zigbee Alliance certification engineers, and electronics distribution channel heads combined with secondary validation from FCC Part 15 equipment authorization databases, MIIT radio transmission equipment type approval records, Ecodesign directive implementation reports, and SEC filings from Texas Instruments and Silicon Laboratories.
Input-output matrices map IEEE 802.15.4 module shipments through product type, application, technology, and end-user segments across the projection horizon. Segmentation dimensions include mesh networking density requirements, standby power consumption tiers, and protocol stack configuration. CAGRs derive from utility smart meter rollout schedules, voice platform integration penetration curves, and industrial sensing adoption patterns in manufacturing facilities.
The model holds under stable regulatory certification timelines; deviation in MIIT approval durations or REACH substance restriction enforcement would shift launch windows and procurement viability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market