
 APAC Semiconductor Device in Communication Industry Market | 2026-2036
APAC Semiconductor Device in Communication Industry Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Semiconductor Device in Communication Industry Market Insights
Enterprise equipment manufacturers are rotating away from legacy telecom vendors toward vertically integrated chipset suppliers. Samsung Electronics Co. Ltd leverages captive foundry capacity to anchor supply security for 5G infrastructure buyers. Qualcomm Incorporated differentiates through modem-RF system integration that sustains design-win momentum across APAC original equipment manufacturers. Nvidia Corporation competes in data-center interconnect silicon where AI training clusters demand terabit-scale optical transceivers.
APAC semiconductor devices in communication encompass transistors, diodes, integrated circuits, and resistors engineered for signal processing, amplification, and switching in radio-frequency and millimeter-wave bands, typically fabricated on 300mm silicon wafers using FinFET or planar GaN-on-SiC processes to achieve noise figures below 2dB at sub-6GHz frequencies. These components enable base stations, smartphones, and satellite terminals to transmit and receive electromagnetic signals with minimal distortion and power loss. Integrated circuits dominate value capture in mobile communication applications where baseband processors and RF front-end modules absorb the largest share of bill-of-materials costs. Gallium nitride technology is displacing silicon LDMOS in cellular network power amplifiers due to superior power-added efficiency at frequencies above 3.5GHz, creating concentrated margin pools for compound semiconductor foundries.
China's MIIT enforces GB standards for domestic 5G base station procurement that favor local sourcing of power amplifiers and baseband processors, while South Korea's MSIT funds K-Chips Act subsidies for advanced logic capacity expansion. Japan's METI coordinates supply chain resilience consortia that restrict technology transfer to qualified domestic partners, reshaping equipment manufacturer vendor qualification processes. Stakeholders must monitor how export control alignment between Washington and Tokyo affects lithography equipment access for Chinese memory and logic fabs serving communication device demand.
Market Dynamics
Supply chain concentration around South Korea's Pyeongtaek and Yongin foundry clusters is redrawing procurement geography for 5G baseband chipsets, forcing equipment manufacturers to requalify vendors against Japan's METI resilience criteria and China's MIIT domestic sourcing mandates.
Growth Catalysts
- MIIT Domestic Sourcing Mandates:China's GB standards for 5G base station procurement require local power amplifier and baseband processor content, redirecting foundry capacity toward indigenous design houses.
- K-Chips Act Subsidies:South Korea's MSIT funding for advanced logic expansion is pulling EUV lithography investment into Yongin, concentrating leading-edge FinFET supply for regional telecom infrastructure buyers.
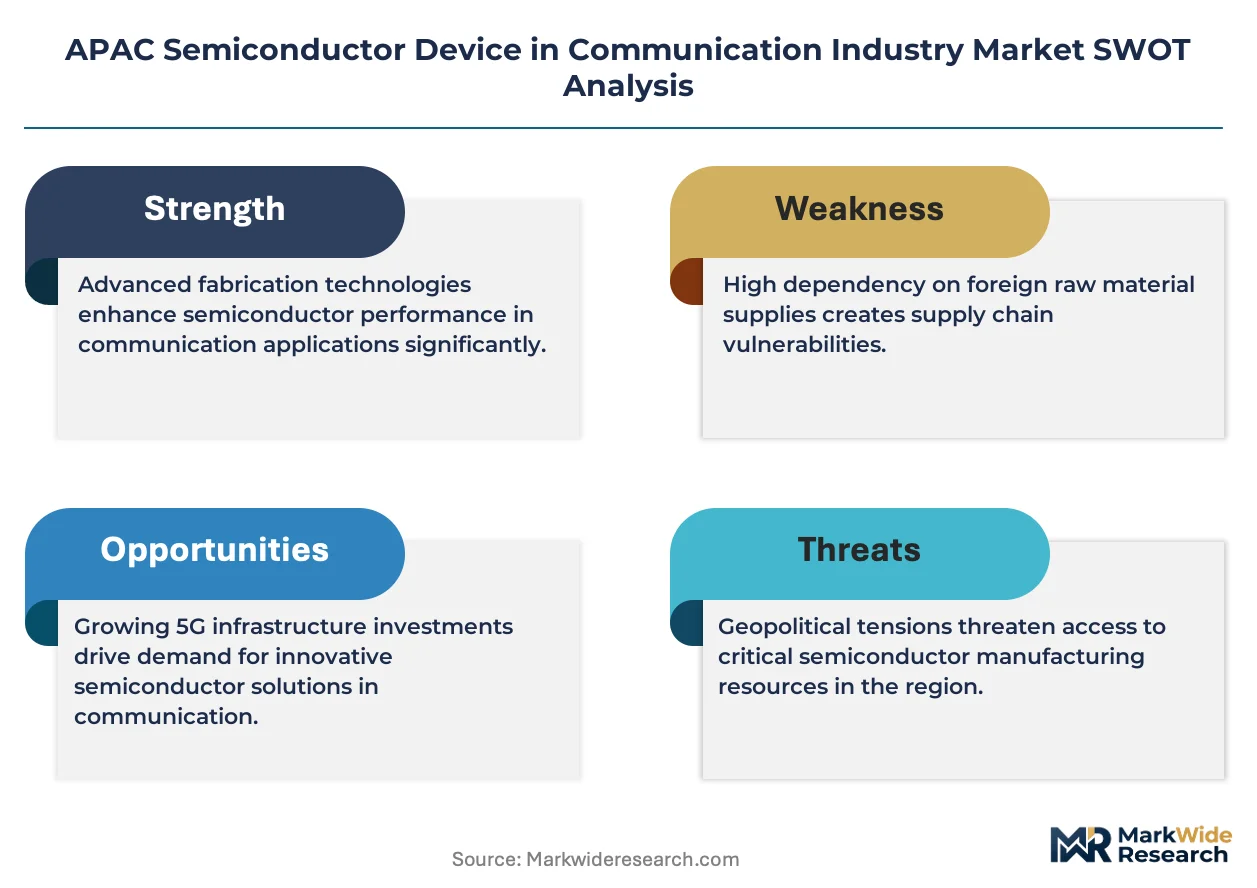
- GaN-on-SiC Process Maturation:Compound semiconductor foundries are capturing margin pools as gallium nitride displaces silicon LDMOS in cellular power amplifiers above 3.5GHz.
Market Restraints
- EUV Equipment Access Friction:Washington-Tokyo export control alignment restricts lithography tool shipments to Chinese memory and logic fabs, capping domestic wafer start expansion.
- Raw Wafer Supply Concentration:300mm silicon substrate production concentrates among Japanese and Taiwanese suppliers, exposing foundry margins to polysilicon price volatility and currency fluctuation.
- Heat Dissipation Physics:Millimeter-wave power amplifiers face thermal management ceilings that limit output power density in sub-6GHz massive MIMO arrays.
Strategic Opportunities
- Vietnam Assembly Test Expansion:Underpenetrated back-end capacity outside China offers tariff-advantaged final test and packaging for RF front-end modules serving ASEAN telecom operators.
- Optical Interconnect Convergence:AI training cluster demand for terabit-scale transceivers is pulling silicon photonics and DSP co-packaging into data-center interconnect silicon.
- METI Supply Chain Consortia:Japan's technology transfer restrictions to qualified domestic partners create captive qualification pathways for equipment vendors seeking resilient second sourcing.
Industry Challenges
- Compound Semiconductor Talent Scarcity:GaN HEMT process engineering expertise concentrates among a narrow cohort of foundry veterans, constraining yield ramp at new 6-inch RF-capable facilities.
- Multi-Die Integration Complexity:Modem-RF system-in-package architectures require heterogeneous integration of CMOS baseband, SOI switches, and BAW filters with tight thermal co-design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Semiconductor Device in Communication Industry Market |
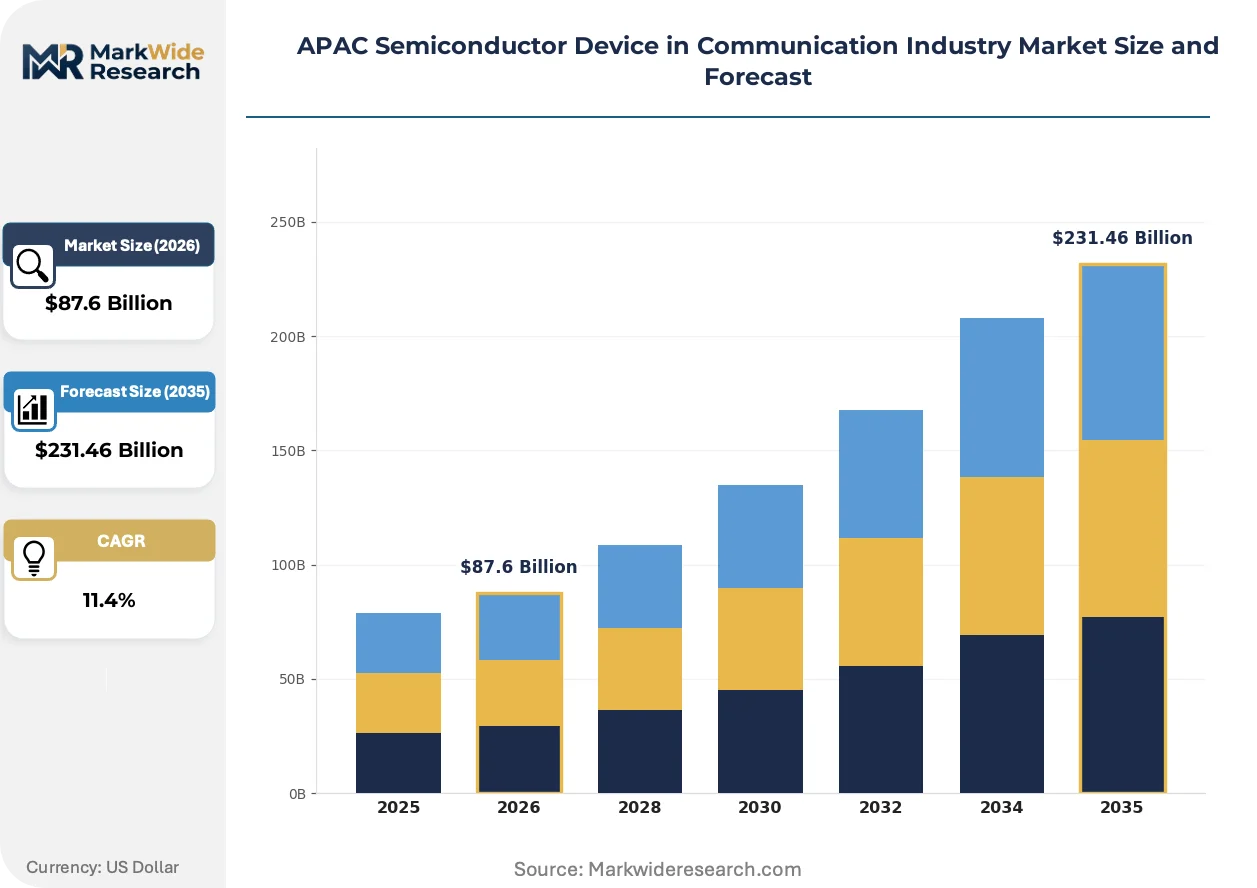
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Transistors, Diodes, Integrated Circuits, Resistors Application: Mobile Communication, Cellular Network, Satellite Communication, IoT Devices Technology: Silicon, Gallium Nitride, Silicon Carbide, AIGaN End User: Telecom Operators, Equipment Manufacturers, Service Providers, Others |
| Companies Covered | Samsung Electronics Co. Ltd, Intel Corporation, NXP Semiconductors NV, Infineon Technologies AG, STMicroelectronics NV, Qualcomm Incorporated, Nvidia Corporation, Toshiba Corporation, Texas Instruments Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Semiconductor Device in Communication Industry Market Trends and Innovations
Radio-frequency semiconductor architecture is compressing toward system-in-package integration where modem, transceiver, and front-end functions share substrate real estate, while regulatory sourcing mandates and procurement model fragmentation reshape competitive access.
Silicon germanium BiCMOS technology for millimeter-wave beamformer ICs is miniaturizing phased-array antenna footprints in 5G base stations. Japanese and South Korean telecom operators are adopting these chipsets for 28GHz small cell densification. The technology is miniaturizing radio unit form factors, enabling street-level deployment without structural reinforcement of existing towers.
China's MIIT enforcement of GB standards for domestic 5G procurement is redirecting foundry loadings toward indigenous power amplifier and baseband processor designs. Equipment manufacturers must requalify supply chains around local sourcing quotas or face exclusion from state-owned operator tenders. Base station OEMs serving the China market are absorbing the highest compliance friction, with some redirecting assembly to joint-venture facilities.
Enterprise equipment manufacturers are rotating vendor relationships away from legacy telecom subsystem suppliers toward vertically integrated chipset houses with captive foundry access. Direct procurement of modem-RF platforms from semiconductor vendors is compressing the traditional RF front-end distributor channel. South Korean and Japanese network equipment makers exhibit the fastest rotation toward direct chipset engagement.
APAC Semiconductor Device in Communication Industry Market Segmentation
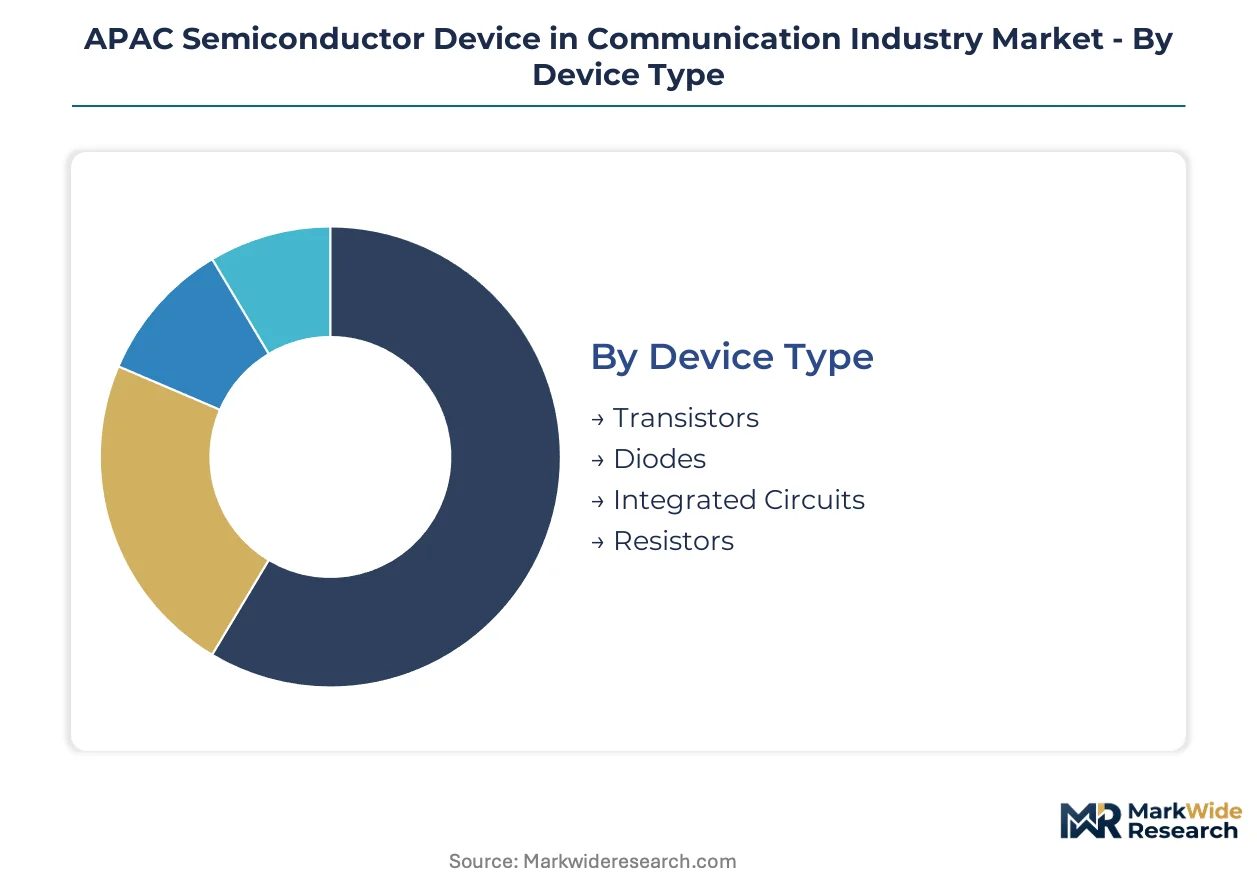
Segmentation reveals how regulatory mandates and supply chain geography fragment procurement patterns across the APAC communication semiconductor landscape. Device type and technology choices increasingly correlate with national sourcing requirements rather than pure performance optimization.
Device Type:
MIIT's GB standards for domestic 5G base station procurement create divergent qualification pathways for each device category, with local content thresholds varying by component complexity.
- Integrated Circuits:Baseband processors and RF front-end modules absorb the largest share of bill-of-materials costs in mobile communication applications. South Korea's Pyeongtaek and Yongin foundry clusters concentrate leading-edge FinFET capacity for these components, while China's indigenous design houses redirect loadings toward domestic fabs under MIIT mandates.
- Transistors:Power amplification functions in cellular base stations rely on discrete transistor architectures fabricated through GaN-on-SiC processes to achieve noise figures below 2dB at sub-6GHz frequencies. Japan's METI supply chain resilience consortia restrict technology transfer for these devices to qualified domestic partners, reshaping vendor qualification processes for equipment manufacturers.
- Diodes:Signal rectification and protection functions in RF front-end modules employ silicon and compound semiconductor junction devices.
- Resistors:Passive termination and impedance matching elements complete signal conditioning chains in radio-frequency subsystems.
Established volume favors Integrated Circuits; emerging adoption favors Transistors as GaN technology penetrates cellular infrastructure.
Application:
End-use concentration patterns reflect divergent deployment timelines across national 5G spectrum allocation schedules and satellite constellation licensing frameworks.
- Mobile Communication:Smartphone baseband processors and modem-RF platforms drive the steepest expansion trajectory as direct procurement from semiconductor vendors compresses traditional distributor channels. South Korean and Japanese network equipment makers exhibit the fastest rotation toward chipset house engagement for these applications.
- Cellular Network:Base station power amplifiers and massive MIMO radio units demand millimeter-wave capable components with stringent thermal management specifications. China's state-owned operator tenders enforce local sourcing quotas that force equipment OEMs to requalify supply chains around indigenous content.
- Satellite Communication:Phased-array terminals and ground station equipment require radiation-hardened components for LEO constellation connectivity.
- IoT Devices:Low-power wide-area network modules integrate simplified RF architectures for sensor connectivity and asset tracking applications.
Procurement scale concentrates in Cellular Network; margin expansion concentrates in Satellite Communication as constellation deployments accelerate.
Technology:
Material platform selection determines access to export-controlled fabrication equipment and foundry partner qualification status under Washington-Tokyo alignment protocols.
- Gallium Nitride:Compound semiconductor foundries capture concentrated margin pools as GaN displaces silicon LDMOS in cellular power amplifiers above 3.5GHz. Process engineering expertise for GaN HEMT fabrication concentrates among a narrow cohort of foundry veterans, constraining yield ramp at new 6-inch RF-capable facilities.
- Silicon:Mature CMOS and BiCMOS processes anchor cost-optimized production for baseband digital logic and millimeter-wave beamformer ICs. Japanese and South Korean telecom operators adopt silicon germanium BiCMOS chipsets for 28GHz small cell densification, miniaturizing radio unit form factors for street-level deployment.
- Silicon Carbide:Substrate material for high-power RF applications and thermal management in base station amplifiers.
- AIGaN:Aluminum indium gallium nitride heterostructures enable advanced HEMT performance for defense and satellite communication frequencies.
Cost structure favors Silicon; performance differentiation favors Gallium Nitride as frequency requirements escalate.
End User:
Customer procurement models fragment between state-mandated domestic sourcing and vertically integrated supply security strategies.
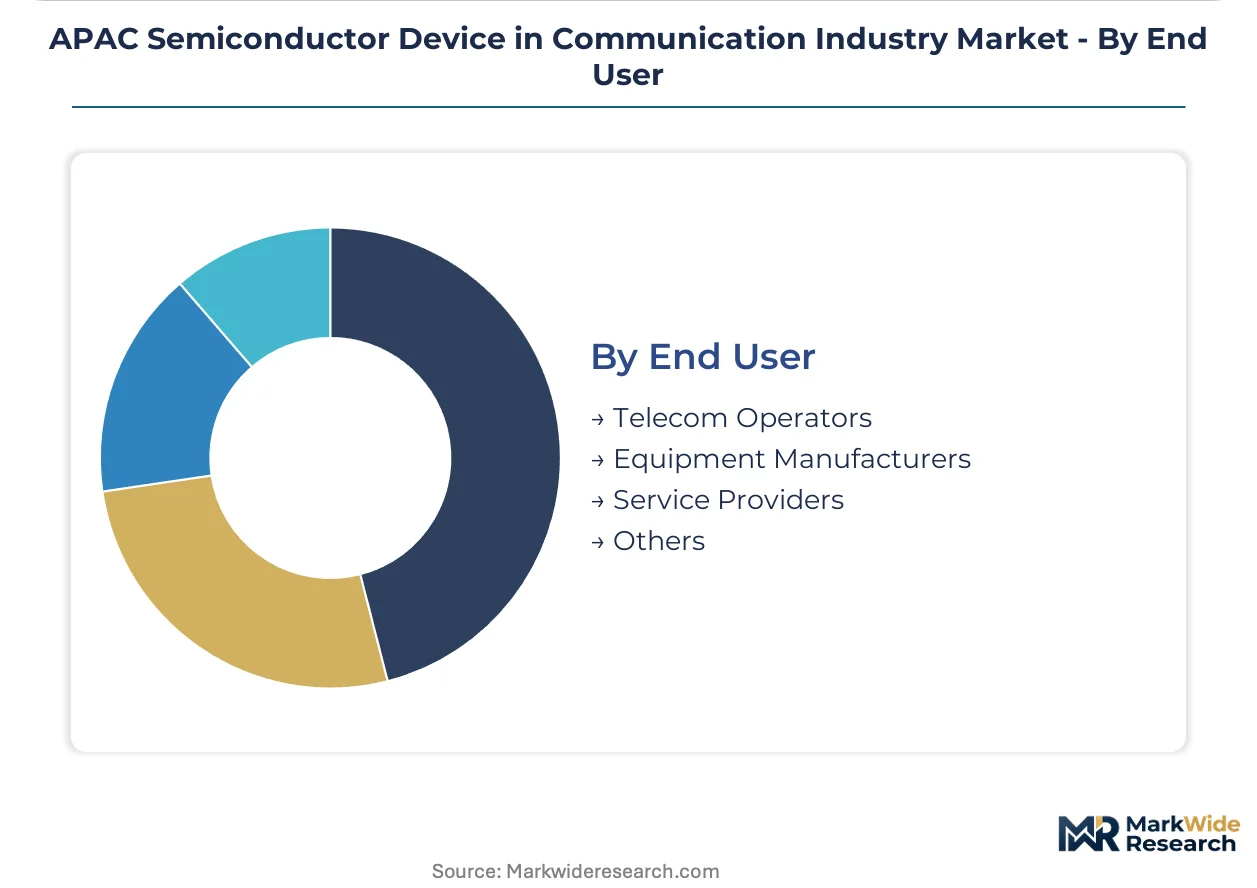
- Telecom Operators:State-owned carriers in China enforce GB standard compliance through tender specifications that exclude non-compliant equipment vendors. Procurement teams rotate vendor relationships away from legacy subsystem suppliers toward vertically integrated chipset houses with captive foundry access.
- Equipment Manufacturers:Base station OEMs absorb the highest compliance friction from MIIT mandates, with some redirecting assembly to joint-venture facilities to maintain market access. Samsung Electronics leverages captive foundry capacity to anchor supply security for 5G infrastructure buyers across the region.
- Service Providers:Network managed services and system integration firms specify component tiers based on deployment geography and regulatory jurisdiction.
- Others:Research institutions and defense contractors operate under separate technology transfer restrictions and export control classifications.
Volume concentration sits with Telecom Operators; supply chain flexibility demands concentrate with Equipment Manufacturers navigating multi-jurisdictional qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors semiconductor logistics across Northeast Asia, handling specialized wafer and lithography equipment flows that underpin foundry expansion timelines. Submarine cable landings at Songdo and Tanah Merah direct data-center silicon demand toward specific coastal manufacturing zones. Regional procurement patterns fragment along national technology sovereignty programs.
China
State-owned carrier tenders for 5G base stations enforce GB standard compliance that redirects foundry loadings toward indigenous power amplifier and baseband processor designs. MIIT domestic sourcing mandates require local content thresholds that exclude non-compliant equipment vendors from procurement pools. Yangtze River Delta fabs around Shanghai and Wuxi absorb the highest compliance friction as OEMs requalify supply chains.
South Korea
MSIT K-Chips Act subsidies pull EUV lithography investment into Yongin, concentrating leading-edge FinFET capacity for regional telecom infrastructure buyers. Pyeongtaek foundry clusters anchor supply security negotiations with equipment manufacturers seeking captive wafer starts. Samsung Electronics leverages this captive capacity to secure design wins across APAC 5G infrastructure deployments.
Japan
METI supply chain resilience consortia restrict technology transfer for GaN HEMT and RF-capable devices to qualified domestic partners, reshaping vendor qualification processes. Kanto region foundries around Tokyo and Yokohama specialize in silicon germanium BiCMOS for millimeter-wave beamformer ICs. Telecom operators adopt these chipsets for 28GHz small cell densification without structural tower reinforcement.
Vietnam
Underpenetrated back-end assembly and test capacity outside China offers tariff-advantaged final processing for RF front-end modules serving ASEAN telecom operators. Northern industrial zones around Bac Ninh and Hai Phong attract packaging investments from firms diversifying beyond Chinese manufacturing. Regulatory alignment with regional trade frameworks accelerates qualification timelines for Vietnam-origin components.
India
PLI scheme incentives for telecom equipment manufacturing create downstream demand for imported baseband and RF components pending domestic fab maturation. Design-linked incentive programs redirect fabless design activity toward Bengaluru and Hyderabad clusters. State-owned operator 5G rollout schedules concentrate procurement windows that favor vendors with established Indian assembly partnerships.
APAC Semiconductor Device in Communication Industry Market Competitive Landscape
Listed leaders compete with private specialists across foundry access and government subsidy capture. Market structure concentrates around vertically integrated conglomerates with captive wafer capacity, tiered specialists in compound semiconductor processes, and fabless design houses dependent on external fabrication. Three archetypes dominate: conglomerate captives securing supply security, GaN foundries capturing margin pools above 3.5GHz, and modem-RF platform vendors compressing distributor channels. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure lithography tool access and requalify vendor relationships.
Among Korea-based conglomerates, Samsung Electronics Co. Ltd occupies a position exemplifying captive foundry leverage for infrastructure supply security. Qualcomm Incorporated and Nvidia Corporation represent the fabless platform tier, with the former anchoring modem-RF system integration and the latter sitting within data-center interconnect silicon where AI training clusters drive terabit-scale optical transceiver demand. These three names illustrate how vendor relationships rotate toward direct chipset engagement and away from legacy telecom subsystem channels.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd |
| Intel Corporation |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| STMicroelectronics NV |
| Qualcomm Incorporated |
| Nvidia Corporation |
| Toshiba Corporation |
| Texas Instruments Inc |
| Others |
Pricing and Supply Chain Analysis
MIIT domestic sourcing mandates for 5G base station procurement gate both supply qualification and price differentiation simultaneously, forcing equipment manufacturers to absorb compliance premiums for local content thresholds while compound semiconductor foundries capture margin pools unavailable to silicon-only vendors.
Pricing Analysis
Volume-discount tiering structures separate telecom operators placing wafer-start commitments above ten-thousand-unit thresholds from mid-tier equipment manufacturers purchasing through distributor channels. Price differentiation hinges on GaN-on-SiC process certification under Japan's METI resilience criteria and captive foundry access secured through Samsung Electronics' Pyeongtaek cluster. Cost compression in standard silicon LDMOS power amplifiers intensifies as gallium nitride displaces legacy technology above 3.5GHz. State-owned carriers exhibit lowest price sensitivity due to procurement quota requirements, while ASEAN telecom operators demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese equipment manufacturers responding to METI supply chain resilience consortia, while South Korean foundry customers maintain just-in-time wafer starts enabled by Yongin cluster proximity. Geographic supply concentration centers on South Korea, Japan, and Taiwan for 300mm silicon substrates and EUV lithography equipment. Raw material dependencies draw from polysilicon feedstock, high-purity quartz crucibles, and photoresist chemicals. Single-source vulnerability concentrates in Japanese and Taiwanese 300mm wafer suppliers. Distribution runs through specialized semiconductor logistics providers handling lithography equipment and wafer shipments from the Port of Busan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G baseband chipset demand inflects on K-Chips Act subsidy disbursement timelines, creating a high-growth disruption window as EUV lithography investment concentrates leading-edge FinFET capacity in Yongin.
For Market Incumbents: Consolidate captive foundry access through long-term wafer start agreements with Pyeongtaek cluster operators, and deepen backward integration into GaN-on-SiC epitaxy to defend against compound semiconductor foundry margin capture. Threat vectors include MIIT domestic sourcing mandates redirecting China-bound loadings toward indigenous design houses. Priority levers center on METI consortium qualification for Japanese telecom infrastructure tenders. For New Entrants and Emerging Players: RF front-end module assembly gaps in Vietnam's northern industrial zones offer tariff-advantaged final test capacity underserved by incumbent packaging houses. Most penetrable segment concentrates in ASEAN telecom operator procurement for sub-6GHz massive MIMO arrays. Go-to-market angle leverages regulatory alignment with regional trade frameworks accelerating Vietnam-origin component qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GaN HEMT process engineering capabilities as yield ramp constraints at new 6-inch RF-capable facilities extend payback periods. Long-term viability favors acquisition targets with established compound semiconductor foundry veteran teams and existing METI or MIIT qualification pathways. Signal to watch: Washington-Tokyo export control alignment friction affecting EUV equipment access for Chinese logic fabs serving communication device demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Secures wafer start priority for 5G infrastructure buyers amid Pyeongtaek cluster concentration. |
| GaN-on-SiC Process Qualification | Captures margin pools in cellular power amplifiers above 3.5GHz frequencies. |
| MIIT Consortium Partnership | Enables access to China state-owned operator tenders under GB standard compliance. |
| Vietnam Assembly Test Investment | Exploits tariff-advantaged back-end capacity for ASEAN telecom RF module demand. |
| Modem-RF Platform Integration | Compresses traditional distributor channels through direct semiconductor vendor engagement. |
Research Methodology
A spread of perspectives from foundry operations executives, telecom equipment procurement directors, compound semiconductor process engineers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT subsidy disbursement records, METI supply chain resilience consortium filings, and K-Chips Act funding announcements. Trade data from Korea Customs Service and Japan External Trade Organization anchored volume triangulation. Bottom-up wafer start estimates and top-down equipment manufacturer procurement forecasts were reconciled through iterative stakeholder feedback.
Segmentation dimensions modeled span device type, application, technology platform, and end-user procurement archetype across the analysis window. Analytical framework approaches derived CAGRs through regression of historical foundry capacity expansion against telecom infrastructure deployment schedules. Industry-specific forecast inputs incorporated EUV lithography tool delivery timelines and GaN HEMT yield ramp curves at new 6-inch RF-capable facilities.
Underlying assumptions cover sustained K-Chips Act subsidy disbursement and stable Washington-Tokyo export control alignment, with deviation risk concentrated in EUV equipment access restrictions for Chinese fabs and polysilicon price volatility affecting 300mm wafer substrate costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market