
 Automotive Thermostat Market | 2026-2036
Automotive Thermostat Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thermostat Market Analysis
The EU F-Gas Regulation is rebalancing the competitive landscape for thermal management component suppliers. Mahle GmbH leverages its integrated powertrain thermal systems portfolio to sustain engineering relationships with European OEMs. BorgWarner Inc anchors its position through electrification-focused thermal solutions that compete across hybrid and battery-electric platforms. Robert Bosch GmbH differentiates via sensor-integrated smart thermostat architectures that dominate precision temperature control segments.
An automotive thermostat is a temperature-sensitive valve, typically incorporating a wax-filled thermal element or electronic sensor, that modulates coolant flow between the engine block and radiator to maintain optimal operating temperature. The device prevents engine overheating while enabling rapid warm-up to reduce friction, emissions, and fuel consumption. Electronic and smart thermostats command premium positioning as OEMs phase out mechanical units in favor of digitally actuated systems with real-time thermal mapping capabilities. Aftermarket channels occupy a mature volume tier serving aging vehicle parc replacement cycles, while factory-installed smart variants capture the fastest growth trajectory tied to electrified powertrain thermal complexity.
The EPA tailpipe emission standards and NHTSA fuel economy mandates in the United States, alongside EMA and REACH frameworks in Europe, collectively tighten thermal efficiency requirements that thermostat designs must satisfy. China's MIIT and GB standards add a third compliance layer for suppliers serving domestic OEMs and joint ventures. Stakeholders must monitor how emerging battery thermal runaway protocols and solid-state battery cooling architectures reshape thermostat functional specifications and qualification timelines.
Market Dynamics
The automotive thermostat sector faces a structural pivot as electrification redefines thermal management requirements across powertrain architectures. Internal combustion engine cooling demands now coexist with battery pack thermal regulation, forcing suppliers to engineer dual-capability systems.
Growth Catalysts
- Electrification mandates:China's MIIT dual carbon goals and the EU Green Deal accelerate EV platform rollouts that require sophisticated multi-zone thermal control systems.
- Emission tightening:Euro 7 standards and EPA tailpipe rules demand precise engine temperature windows to minimize cold-start emissions and optimize catalytic converter efficiency.
- Thermal runaway protocols:Emerging battery safety regulations in passenger electric vehicles mandate redundant cooling circuits that expand thermostat functional specifications.
Market Restraints
- Wax element supply concentration:Thermal actuator production clusters in German and Japanese specialty chemical suppliers, creating single-source vulnerability for mechanical thermostat variants.
- Electronic component cost volatility:MEMS sensor and microcontroller pricing fluctuates with semiconductor foundry capacity constraints, compressing margins on smart thermostat SKUs.
- Mechanical thermostat substitution:Digitally actuated systems displace wax-filled units in new vehicle platforms, stranding capacity at legacy mechanical-focused manufacturers.
Strategic Opportunities
- Commercial vehicle electrification:Battery-electric bus and truck segments in Germany and California present unserved demand for heavy-duty thermal management systems.
- Solid-state battery cooling:Next-generation cell chemistries from Toyota and QuantumScape require novel thermal architectures that reset supplier qualification timelines.
- Aftermarket sensor retrofit kits:Independent repair channels in the United States seek plug-and-play electronic thermostat upgrades for aging hybrid parc.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety compliance for thermostat control algorithms extends development cycles and requires specialized automotive firmware engineers.
- Legacy system integration:Smart thermostats must interface with 1990s-era coolant circuit designs in vehicle refurbishment markets without full architecture replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thermostat Market |
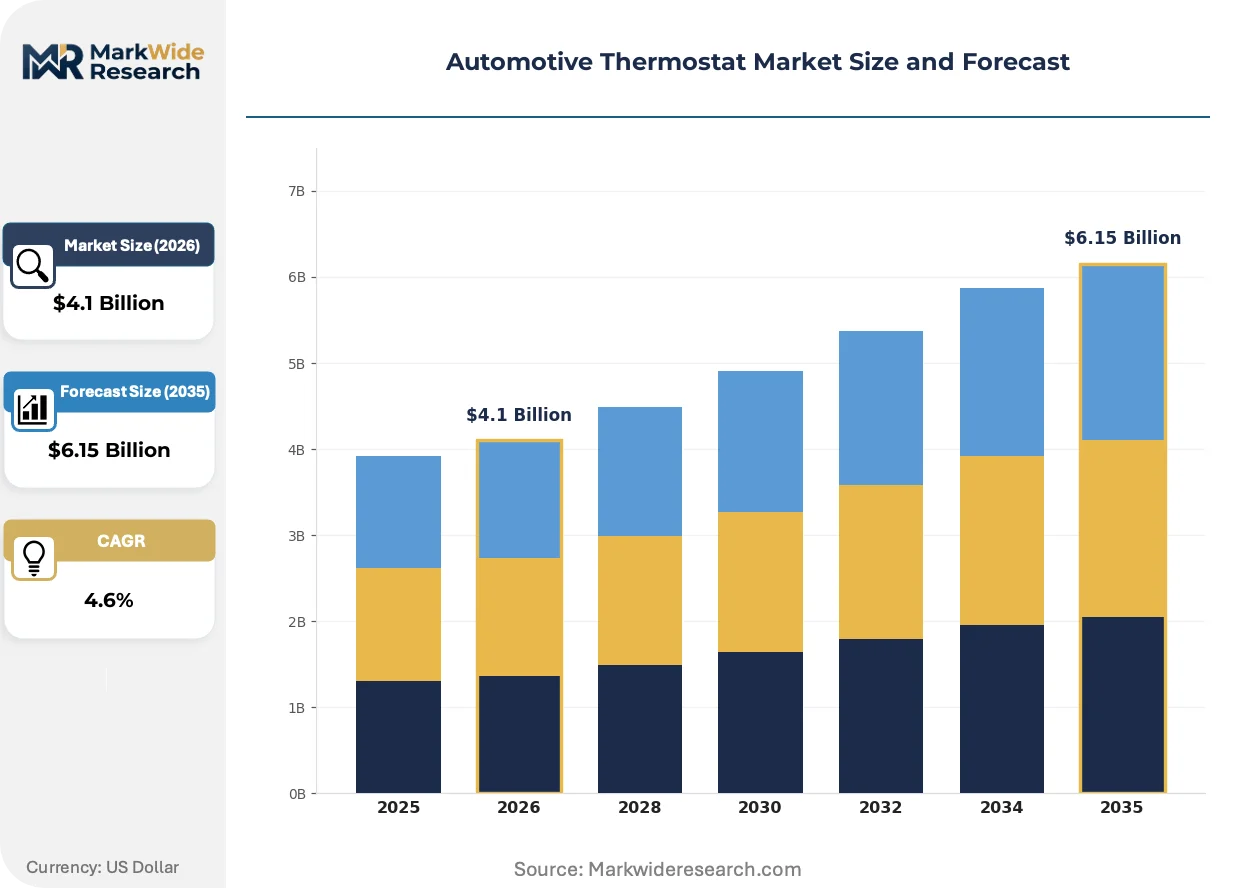
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Smart, Thermomechanical End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Factory-installed, Aftermarket, Retrofitted, Custom-installed Temperature Range: Low, Medium, High, Extreme |
| Companies Covered | Gates Corporation, Stant Corporation, Mahle GmbH, Nippon Thermostat Co. Ltd., HELLA, BorgWarner Inc, Vernet SAS, Fishman Thermo Technologies Ltd, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thermostat Market Emerging Trajectories
Automotive thermal management is converging with powertrain electrification and predictive vehicle systems. Component suppliers now engineer for multi-physics environments where combustion cooling, battery conditioning, and cabin climate control share control logic and hardware.
Predictive thermal mapping software is integrating with electronic thermostat actuators to anticipate load conditions before they materialize. Tier 1 suppliers embed machine learning models that preprocess GPS route data, ambient temperature forecasts, and driver behavior patterns. This convergence compresses the boundary between thermal hardware and vehicle intelligence layers.
REACH chemical restrictions and the EU F-Gas Regulation are reshaping material specifications for thermal actuator fills and seal compounds. Manufacturers reformulate wax-based elements to eliminate restricted substances while maintaining response curves within OEM tolerance bands. German and French regulators now audit supply chain chemical compliance with expanded substance screening protocols.
Fleet operators and leasing companies now specify thermal component durability metrics in procurement tenders rather than accepting standard OEM catalog offerings. Large commercial buyers in California and Texas negotiate extended warranty terms and predictive maintenance data access. This behavioral shift pressures suppliers to unbundle hardware from service analytics and restructure pricing around operational outcomes.
Automotive Thermostat Market Segmentation
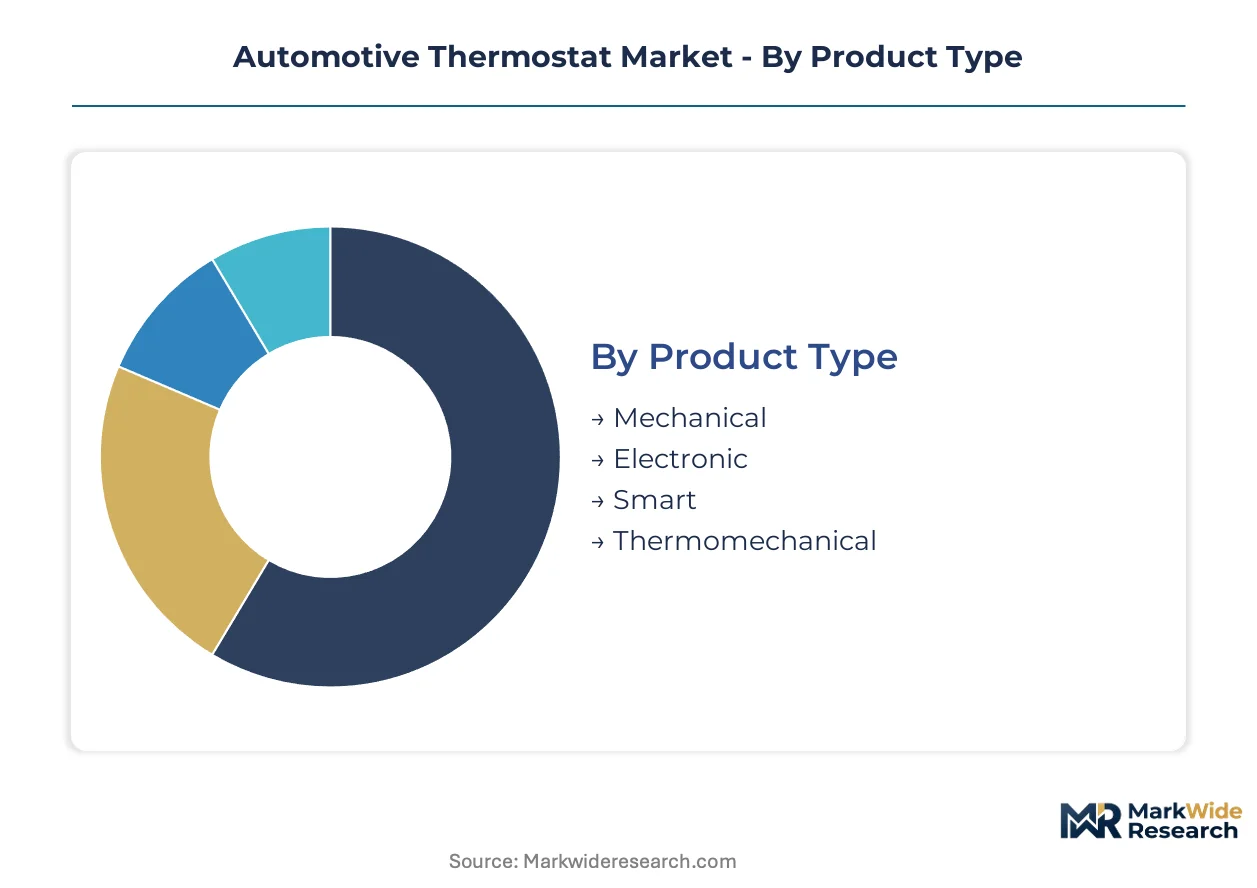
Thermostat segmentation reflects divergent engineering requirements across combustion, hybrid, and battery-electric platforms. Suppliers configure production lines around distinct actuator technologies and thermal control specifications demanded by powertrain type.
Product Type:
Supply concentration clusters around electronic and smart variants as OEM procurement shifts toward digitally actuated thermal management systems.
- Mechanical:Wax-filled thermal elements trigger valve actuation through phase-change expansion. German and Japanese specialty chemical suppliers dominate wax compound formulation, creating single-source vulnerability for legacy internal combustion engine cooling circuits.
- Electronic:Sensor-integrated architectures with MEMS temperature detection and microcontroller-driven valve positioning enable real-time thermal mapping. MIIT dual carbon goals and EU Green Deal electrification mandates concentrate demand in China and Germany for battery-electric and hybrid vehicle platforms.
- Smart:Predictive algorithms preprocess GPS route data and ambient conditions to anticipate thermal loads before they materialize.
- Thermomechanical:Hybrid designs combine wax actuation with electronic override capabilities for transitional powertrain architectures.
Mechanical variants absorb the bulk of installed capacity across aging vehicle parc replacement cycles; smart thermostats are expanding most quickly through factory-installed electrified platform specifications.
End User:
Cost tier differentiation separates premium engineering relationships from volume procurement arrangements across the customer base.
- OEMs:Direct vehicle manufacturer specifications demand ISO 26262 functional safety certification and predictive thermal mapping software integration. EPA tailpipe standards and Euro 7 emission regulations in the United States and Germany mandate precise temperature control windows that only electronic architectures satisfy.
- Aftermarket Providers:Independent repair channels service mechanical thermostat replacement demand in 1990s-era vehicle refurbishment markets without full coolant circuit architecture replacement.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging EV brands require rapid qualification timelines for multi-zone thermal control systems.
- Tier-1 Suppliers:Integrated powertrain thermal system bundling positions thermostat procurement within broader HVAC and battery conditioning contracts.
OEMs absorb the bulk of installed capacity through captive supply arrangements; Tier-1 suppliers are climbing the fastest as electrification consolidates thermal management procurement.
Installation Type:
Application context determines warranty liability, software certification requirements, and service data access terms.
- Factory-installed:Embedded at vehicle assembly with full powertrain control network integration and over-the-air update capability.
- Aftermarket:Plug-and-play mechanical replacements dominate independent repair channels in the United States aging hybrid parc.
- Retrofitted:Electronic thermostat upgrades for legacy coolant circuits require ISO 26262 algorithm validation and specialized automotive firmware engineering.
- Custom-installed:Fleet operator specifications in California and Texas negotiate extended warranty terms and predictive maintenance data access separate from standard OEM catalog offerings.
Factory-installed variants absorb the bulk of installed capacity; custom-installed applications are gaining share fastest through commercial fleet procurement restructuring.
Temperature Range:
Margin structure varies with thermal specification stringency and qualification testing duration for extreme environments.
- Low:Battery conditioning circuits for temperate climate electric vehicle deployment.
- Medium:Standard internal combustion engine operating windows dominate volume production.
- High:Performance combustion applications and fast-charging battery thermal management require advanced seal compounds reformulated under REACH chemical restrictions.
- Extreme:Solid-state battery cooling architectures from Toyota and QuantumScape reset supplier qualification timelines with novel thermal actuator specifications.
Medium-range specifications absorb the bulk of installed capacity; extreme-range applications are expanding most quickly through next-generation cell chemistry development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and the United States concentrate the bulk of OEM procurement for advanced thermostat technologies, with each market driven by distinct regulatory frameworks and electrification timelines. National emission mandates and battery thermal safety protocols are reshaping supplier qualification requirements across these demand centers.
China
MIIT dual carbon goals and GB standards are accelerating EV platform rollouts that require multi-zone thermal control systems. The ministry's battery thermal runaway protocols mandate redundant cooling circuits, expanding thermostat functional specifications for domestic OEMs and joint ventures. Shanghai and Guangdong province host concentrated supplier engineering centers serving BYD, NIO, and CATL battery conditioning programs.
Germany
Euro 7 emission standards and KBA enforcement are mandating tighter engine temperature control windows for precise catalytic converter efficiency. The EU F-Gas Regulation and REACH chemical restrictions are forcing wax compound reformulation for thermal actuator fills. Stuttgart and Munich anchor development clusters where Mahle GmbH and Robert Bosch GmbH maintain integrated powertrain thermal system relationships with Volkswagen, BMW, and Mercedes-Benz.
United States
EPA tailpipe emission standards and NHTSA fuel economy mandates are tightening thermal efficiency requirements for combustion platforms alongside California's Advanced Clean Cars II rules. The Inflation Reduction Act's domestic content provisions are incentivizing localized thermostat production for electrified vehicle supply chains. Michigan and Ohio retain engineering density for Detroit Three thermal management procurement, while Texas fleet operators negotiate extended warranty terms for commercial vehicle electrification.
Japan
METI carbon neutrality roadmaps and JIS standards are driving solid-state battery development programs that reset thermal architecture specifications. Nippon Thermostat Co. Ltd. anchors domestic supply relationships with Toyota's next-generation cell chemistry timelines. Aichi prefecture and Tokyo metropolitan manufacturing corridors concentrate precision actuator production for hybrid and battery-electric platform exports.
South Korea
MFDS automotive component safety frameworks and Ministry of Environment emission rules are converging with Hyundai-Kia's accelerated EV platform launches. Seoul Capital Area engineering centers are qualifying smart thermostat architectures for E-GMP platform battery conditioning. Busan-Ulsan industrial complexes support export-oriented production for European and North American OEM thermal system contracts.
Automotive Thermostat Market Vendor Landscape
German producers anchor one tier through integrated powertrain thermal systems; Japanese specialists hold precision actuator expertise for hybrid transitions. The vendor base stratifies across three tiers: multinational diversified suppliers with electrification portfolios, regional mechanical-focused manufacturers serving aftermarket replacement cycles, and emerging Chinese fabricators capturing domestic EV procurement. Competitive moves center on sensor-integrated smart architecture development and backward integration into MEMS temperature detection components.
Within the diversified multinational tier, Mahle GmbH, BorgWarner Inc, and Robert Bosch GmbH exemplify distinct strategic positioning archetypes. Mahle GmbH occupies a position emphasizing integrated thermal system bundling across combustion and electrified platforms. BorgWarner Inc represents the electrification-focused vector competing across hybrid and battery-electric architectures. Robert Bosch GmbH anchors the precision control segment through sensor-integrated smart thermostat development. These three entities collectively illustrate how European and US-based suppliers are restructuring engineering relationships around OEM electrification procurement consolidation.
| Leading Market Players |
|---|
| Gates Corporation |
| Stant Corporation |
| Mahle GmbH |
| Nippon Thermostat Co. Ltd. |
| HELLA |
| BorgWarner Inc |
| Vernet SAS |
| Fishman Thermo Technologies Ltd |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Detroit Three and German premium OEM procurement concentration anchors contract-based long-term offtake pricing for electronic thermostat architectures, while spot-market mechanical units serve fragmented aftermarket channels with compressed margins. Wax compound suppliers in Germany and Japan leverage single-source positioning to extract premium pricing for thermal actuator fills, even as digitization displaces mechanical demand.
Pricing Analysis
Short lead-time premiums of 15-25% apply to smart thermostat SKUs required for EV platform launches with accelerated qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified predictive thermal mapping systems from basic electronic actuators and legacy wax-filled units. Cost compression in mechanical tiers is intensifying because semiconductor foundry constraints inflate MEMS sensor and microcontroller inputs for smart variants. Aftermarket distributors exhibit highest price sensitivity, while OEM platform engineering teams prioritize certification-grade performance over unit economics.
Supply Chain Analysis
ISO 26262 functional safety certification and IATF 16949 quality management credentials gate supplier access to OEM direct procurement, extending qualification cycles. Manufacturing concentrates in Germany, China, and Japan, with Aichi prefecture and Stuttgart anchoring precision actuator production for hybrid platform exports. Wax thermal element formulation draws from German and Japanese specialty chemical suppliers, creating single-source vulnerability for mechanical thermostat production. Tariff exposure on semiconductor components sourced from Taiwan and South Korea threatens margin stability for smart thermostat SKUs. Distribution runs through Tier 1 thermal system integrators bundling thermostat procurement within broader HVAC and battery conditioning contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive thermostat sector sits in a technology-transition phase where electronically actuated and predictive thermal mapping architectures displace wax-filled mechanical units across new vehicle platforms.
For Market Incumbents: To counter stranded capacity at mechanical-focused production lines, accelerate backward integration into MEMS temperature detection components and captive wax compound formulation capabilities. Prioritize ISO 26262 software certification investments to defend OEM platform engineering relationships against emerging sensor-integrated competitors. For New Entrants and Emerging Players: Fleet operator procurement channels in California and Texas present the most penetrable entry point, with extended warranty and predictive maintenance data access terms unbundled from standard OEM catalog offerings. Target commercial vehicle electrification segments in Germany and California with heavy-duty thermal management systems engineered for battery-electric bus and truck platforms. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with embedded software capabilities and established Tier 2 supplier relationships awaiting OEM qualification. Long-term viability hinges on positioning for solid-state battery cooling architecture resets from Toyota and QuantumScape development programs. Monitor battery thermal runaway protocol adoption across MIIT, EPA, and KBA jurisdictions as the inflection signal for multi-zone thermal control system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering validation burden across Volkswagen, BMW, and Mercedes-Benz electrified architectures. |
| Battery Supply Agreement | Secures thermal management component allocation for CATL and BYD cell conditioning programs in China. |
| Software-Defined Vehicle Investment | Enables predictive thermal mapping integration with GPS route preprocessing and ambient condition forecasting. |
| Geographic Manufacturing Footprint | Aligns localized production with Inflation Reduction Act domestic content provisions for US electrified supply chains. |
| Charging Infrastructure Partnership | Positions thermal system suppliers for fast-charging battery thermal management specifications in extreme temperature ranges. |
Methodological Framework
Document review covered IHS Markit vehicle production databases, EPA and KBA emission certification filings, and MIIT GB standard updates, complemented by interviews with Tier 1 supplier procurement directors, OEM platform thermal engineers, aftermarket distribution channel managers, and German specialty chemical wax compound formulators. Secondary validation drew from SEC 10-K thermal segment disclosures, EU F-Gas Regulation implementation audits, and REACH chemical restriction compliance protocols. Bottom-up unit volume modeling and top-down OEM thermal system spending estimates were triangulated to anchor market sizing.
Historical production volumes for mechanical, electronic, smart, and thermomechanical thermostat variants were cross-referenced against panel input from OEM platform engineering teams regarding electrification procurement timelines. Segmentation modeling spanned propulsion architecture, actuator technology tier, installation context, and regional regulatory cluster across the projection horizon. CAGRs were derived from OEM platform rollout schedules weighted against aftermarket replacement cycle analysis and battery thermal runaway protocol adoption curves.
Caveats apply where solid-state battery commercialization timelines, semiconductor foundry capacity constraints, or Euro 7 enforcement delays could materially shift the outlook for smart thermostat demand trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Thailand Automotive Lubricants Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Transfer Case Market
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
Cylinder Head Cover Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Leaf Spring Market