
 Railway Control Stands Market | 2026-2036
Railway Control Stands Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Control Stands Market Analytics
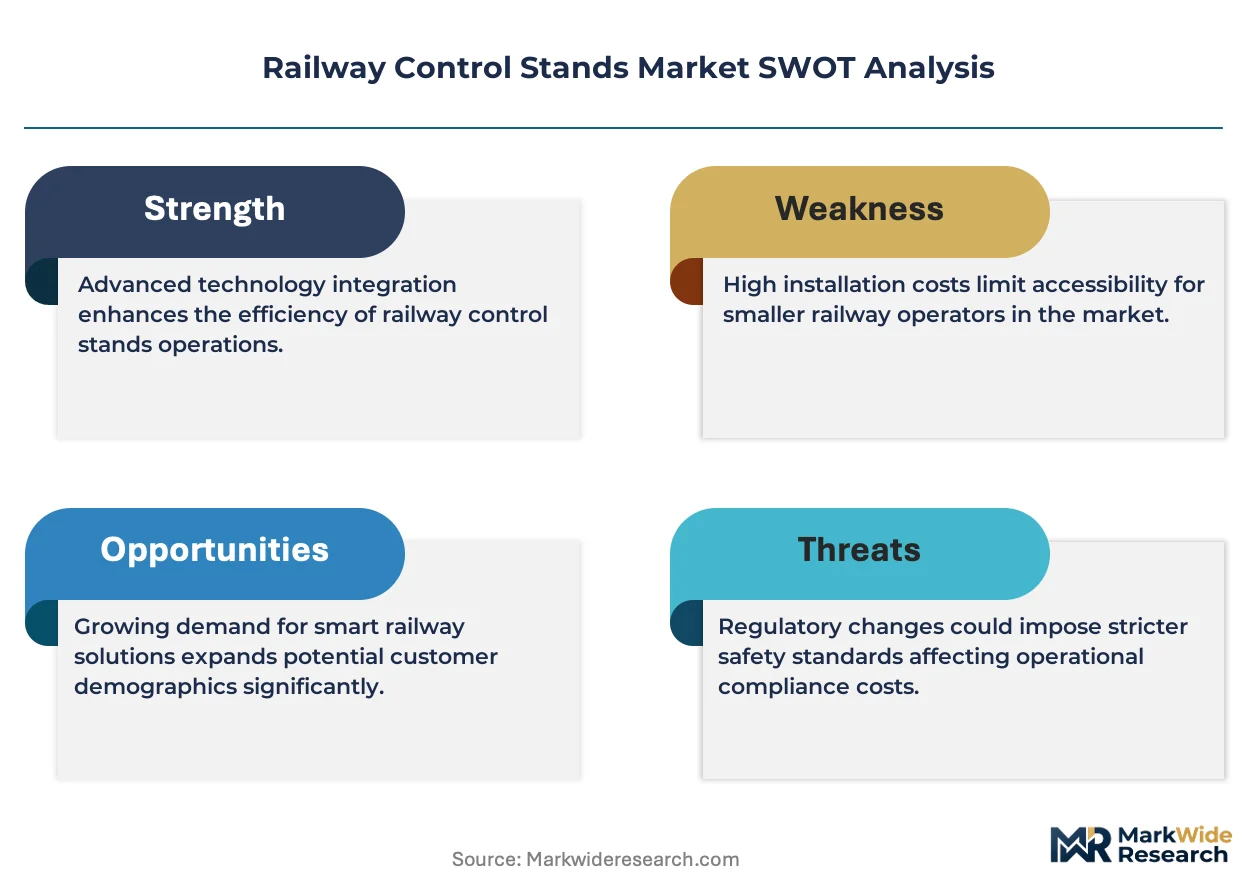
The capital-intensity divergence between full-system integrators and component specialists is bifurcating competitive dynamics in railway control stands. Siemens Mobility leverages deep vertical integration in electromechanical control architectures to dominate European mainline retrofit contracts. CRRC Corporation anchors its position through captive manufacturing scale and state-backed procurement channels across China's expanding high-speed network. Alstom competes by specializing in ERTMS-compatible electronic control platforms for cross-border freight corridors.
Railway control stands constitute the operator-facing interface assemblies that translate human commands into braking, traction, and signaling inputs through electromechanical linkages or electronic actuation circuits, typically engineered to SIL-2 or SIL-3 safety integrity levels depending on application criticality. These assemblies serve as the final control element in train cabs, determining operational responsiveness across freight haulage, passenger transit, and shunting maneuvers. Electronic control stands are capturing disproportionate investment as railway operators phase out manual lever systems in favor of integrated digital interfaces that consolidate braking, traction, and diagnostic functions. Hydraulic systems retain residual dominance in heavy-haul freight applications where force multiplication requirements exceed electromechanical actuator capacities. Maintenance contractors represent an expanding end-user segment as outsourced lifecycle service models displace in-house overhaul programs among cost-constrained operators.
The European Union Agency for Railways enforces interoperability standards through ERTMS specifications that mandate control stand compatibility with centralized traffic management systems, effectively conditioning market access on certification compliance. China's National Railway Administration implements GB standards that align domestic control stand designs with indigenous signaling protocols, creating regulatory segmentation between export-oriented and domestically focused suppliers. India's Ministry of Railways prescribes RDSO specifications that govern control stand procurement for its electrification and dedicated freight corridor investments. Stakeholders must monitor divergence between regional certification regimes as interoperability mandates fragment across Europe's ERTMS rollout, China's CTCS evolution, and India's emerging automatic train protection requirements.
Market Dynamics
The European Union's F-Gas Regulation is forcing accelerated replacement cycles for hydraulic control systems across mainline fleets, compressing supplier lead times while expanding the addressable base for electronic actuator platforms.
Growth Catalysts
- ERTMS Baseline 3 Mandates:The EU Agency for Railways mandates centralized traffic management compatibility across cross-border corridors, requiring control stand retrofits in Germany, France, and Poland.
- Urban Transit Fleet Modernization:Metro operators in China and India are phasing out manual lever systems in favor of integrated digital interfaces for braking and traction consolidation.
- Freight Electrification Programs:India's Ministry of Railways is expanding dedicated freight corridor investments that specify RDSO-compliant electronic control architectures.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries control critical IGBT and microcontroller supply for electronic control stands, exposing European integrators to single-source risk.
- Legacy Fleet Longevity:Heavy-haul freight operators in North America extend hydraulic system service lives beyond 25 years through component-level refurbishment, delaying electronic conversion.
- Certification Cost Burden:SIL-3 validation requirements under IEC 61508 impose multi-year testing timelines that freeze smaller suppliers from tender participation.
Strategic Opportunities
- Maintenance Contractor Channel Expansion:Outsourced lifecycle service models among cost-constrained operators in Brazil and Mexico are creating captive demand for control stand overhaul specialists.
- CTCS-4 Signaling Convergence:China's National Railway Administration is aligning next-generation control stands with indigenous automatic train protection protocols for high-speed export markets.
- Retrofit-as-a-Service Models:German regional operators are piloting subscription-based control stand upgrades that bundle hardware, installation, and predictive maintenance under unified contracts.
Industry Challenges
- SIL Certification Talent Scarcity:Functional safety engineering expertise concentrates among aging specialists in Stuttgart and Munich, constraining supplier scaling capacity.
- Legacy System Integration Complexity:Electromechanical control stands must interface with 40-year-old braking architectures in Eastern European fleets without full cab reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Control Stands Market |
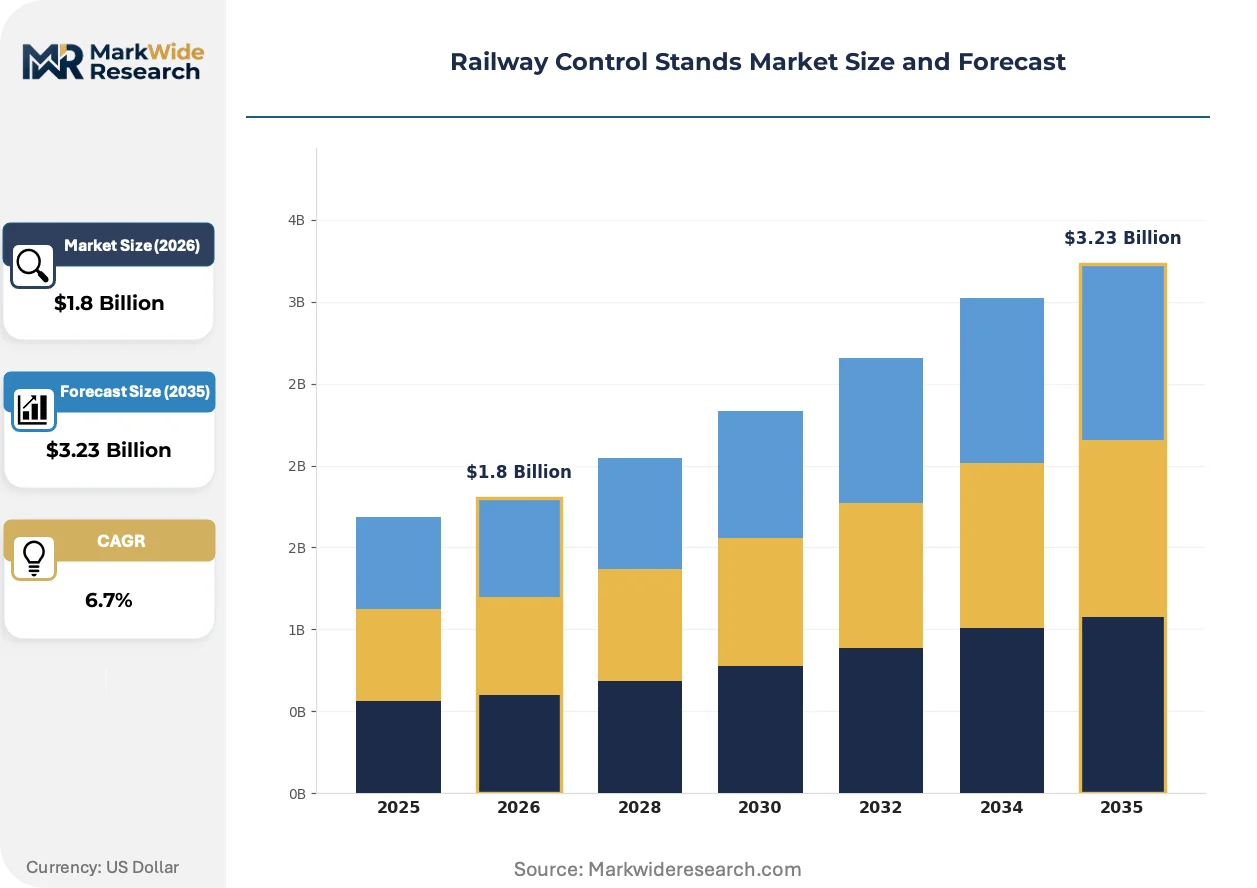
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Control Stands, Electronic Control Stands, Semi-Automatic Control Stands, Multi-Functional Control Stands Application: Freight Transport, Passenger Transport, Shunting Operations, Maintenance Services End User: Railway Operators, Freight Companies, Urban Transit Providers, Maintenance Contractors Technology: Electromechanical Systems, Hydraulic Systems, Pneumatic Systems, Integrated Control Solutions |
| Companies Covered | ABB, Alstom, Siemens Mobility, Hitachi Rail, Toshiba, Thales Group, Knorr-Bremse, CRRC Corporation, Bombardier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Control Stands Market Evolving Landscape
Electronic actuation architectures are fragmenting the supplier base, compressing margins for hydraulic specialists while enabling software-defined control platforms that consolidate multiple safety functions.
Brushless DC motor drives with integrated position feedback are decomposing the traditional separation between human-machine interfaces and braking actuation circuits. European commuter rail operators are adopting these platforms for metro and regional services. This convergence is decomposing the historical tiering between full-system integrators and component suppliers, forcing mid-tier manufacturers to choose between software competency or hardware commoditization.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbon-based hydraulic fluids is accelerating material substitution in control stand damping systems. Industrial consequence includes forced redesign of seal compatibility and fluid viscosity specifications for cold-climate operations. Nordic freight operators are responding by pre-ordering synthetic ester-based alternatives ahead of 2030 compliance deadlines.
Third-party maintenance contractors are capturing control stand overhaul volumes previously retained in-house by state railways. Specialist service providers in Poland and the Czech Republic are displacing original equipment manufacturer service networks through faster turnaround guarantees. This channel shift is most visible in Germany's regional passenger sector, where DB Regio has unbundled lifecycle service contracts from initial procurement.
Railway Control Stands Market Segmentation
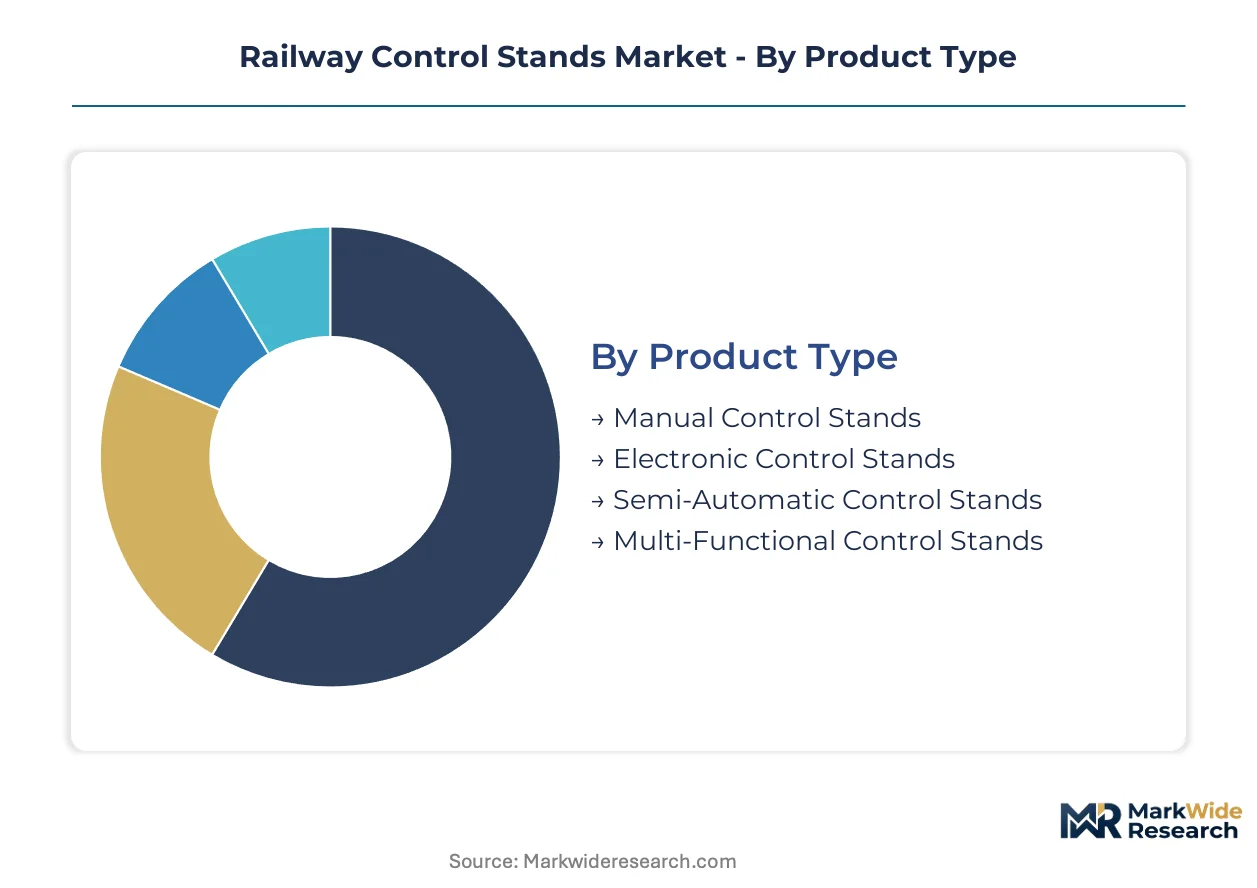
Control stand procurement patterns diverge sharply across safety-criticality tiers and operational duty cycles. Railway operators segment investments by interoperability mandates, fleet age profiles, and outsourcing depth rather than uniform technology preferences.
Product Type:
ERTMS Baseline 3 and China's CTCS-3 standards are segmenting demand between legacy-compatible mechanical platforms and digitally integrated architectures. European regulators enforce centralized traffic management compatibility, while China's GB standards prioritize indigenous protocol alignment.
- Manual Control Stands:Lever-based mechanical assemblies with direct linkage to braking and traction circuits. Demand concentrates in India's freight corridors and Eastern European retrofit programs where RDSO and legacy TSI standards permit extended service intervals. Operators defer replacement where full cab reconstruction costs exceed modernization budgets.
- Electronic Control Stands:Microprocessor-driven interfaces consolidating braking, traction, and diagnostic feedback through SIL-2 or SIL-3 validated architectures. Germany's regional operators and China's high-speed network are absorbing capacity as ERTMS and CTCS mandates accelerate replacement cycles. Brushless DC motor integration is compressing the traditional separation between human-machine interfaces and actuation circuits.
- Semi-Automatic Control Stands:Hybrid architectures retaining mechanical backup for electronic primary control. Poland and Czech Republic maintenance contractors favor these for interoperability flexibility during transitional signaling upgrades.
- Multi-Functional Control Stands:Integrated platforms embedding predictive maintenance interfaces and energy management displays. Urban transit providers in India and Brazil are piloting these for fleet-wide telemetry consolidation.
Electronic control stands handle the majority of new procurement throughput; multi-functional variants are climbing the fastest on share as predictive maintenance contracts expand.
Application:
Operational duty intensity determines safety integrity requirements and replacement frequency. Heavy-haul freight cycles stress hydraulic damping components, while high-frequency passenger services prioritize electronic responsiveness.
- Freight Transport:High-force braking demands favor hydraulic retention in North American and Australian heavy-haul corridors. India's dedicated freight corridors are mandating electronic conversion under RDSO specifications, compressing supplier lead times for compliant actuators.
- Passenger Transport:Metro and regional operators in Germany, France, and China are standardizing on electronic platforms with integrated ERTMS or CTCS driver-machine interfaces. Passenger safety regulations enforce SIL-3 validation for emergency braking circuits.
- Shunting Operations:Low-speed maneuvering requirements sustain demand for robust mechanical stands with simplified maintenance protocols. Polish and Romanian yards specify these for interoperability with aging locomotive fleets.
- Maintenance Services:Third-party overhaul specialists in the Czech Republic and Mexico are capturing volumes previously retained in-house, creating demand for modular stand architectures with standardized component replacement.
Freight transport absorbs the largest equipment volume; maintenance services are expanding most quickly as outsourced lifecycle models displace operator-owned overhaul capacity.
End User:
Procurement centralization varies by ownership structure. State-backed operators leverage volume consolidation, while privatized freight companies prioritize total-cost-of-ownership metrics over initial capital outlay.
- Railway Operators:State monopolies in China and India dominate procurement through centralized tendering aligned with GB and RDSO standards. Deutsche Bahn's unbundling of regional service contracts is fragmenting demand across German Länder-level purchasers.
- Freight Companies:Privatized operators in North America and Australia extend hydraulic system life cycles through component refurbishment, delaying electronic conversion. Cost pressure is forcing maintenance outsourcing to Polish and Mexican contractors.
- Urban Transit Providers:Metro operators in São Paulo, Mumbai, and Shenzhen are modernizing fleets with integrated digital interfaces. These entities specify CTCS-4 or ERTMS compatibility for future-proofing against signaling evolution.
- Maintenance Contractors:Specialist service providers are displacing OEM networks through faster turnaround guarantees. Brazilian and Mexican operators are piloting subscription-based upgrade models bundling hardware and predictive maintenance.
Railway operators command the dominant procurement volume; maintenance contractors are gaining share fastest as lifecycle service unbundling accelerates.
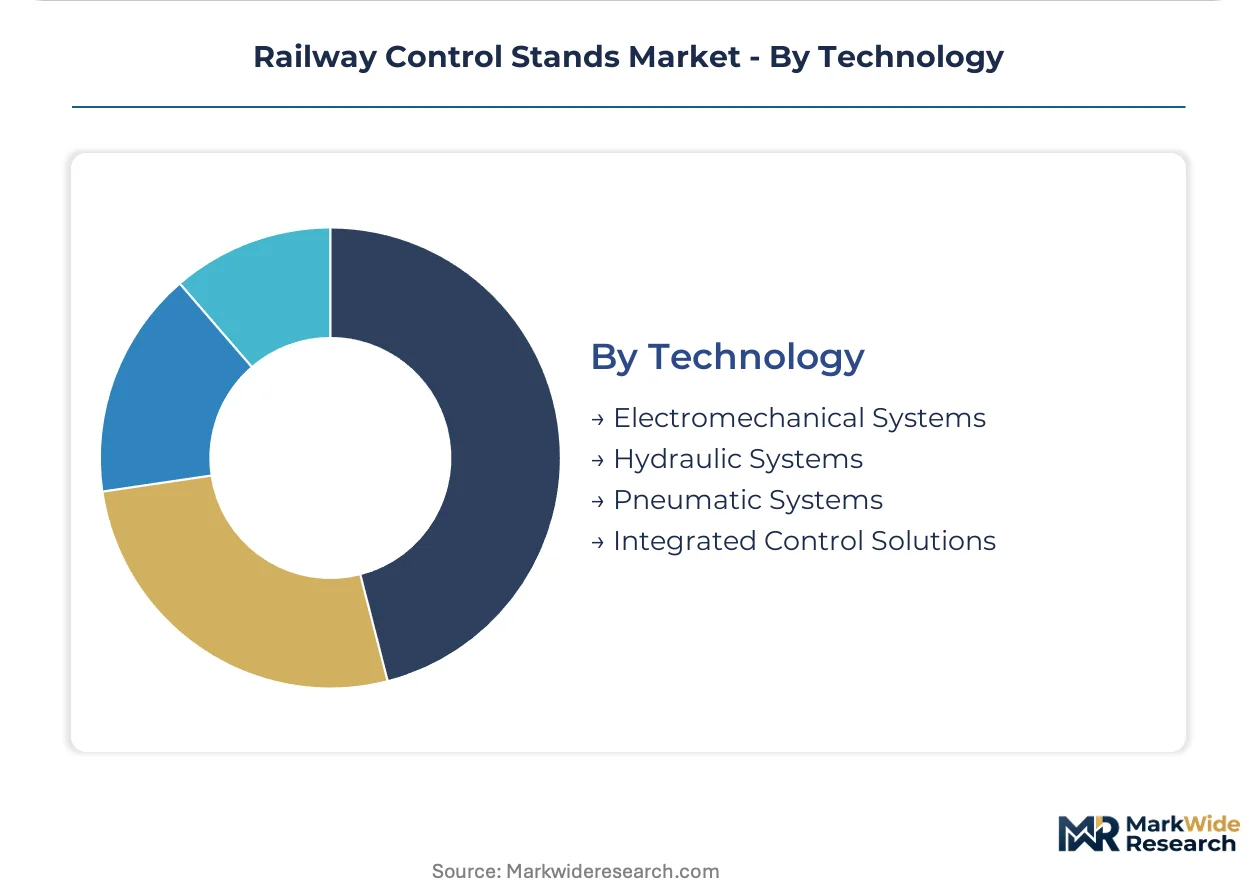
Technology:
Actuation physics and regulatory chemistry are restructuring competitive positioning. The EU F-Gas Regulation's hydrofluorocarbon phasedown is forcing hydraulic fluid substitution, while semiconductor supply concentration constrains electronic scaling.
- Electromechanical Systems:Brushless DC motor drives with integrated position feedback are consolidating braking and traction control into unified electronic architectures. European commuter rail adoption is decomposing historical tiering between full-system integrators and component suppliers.
- Hydraulic Systems:Force multiplication for heavy-haul applications relies on synthetic ester fluid formulations replacing hydrofluorocarbon bases under F-Gas compliance deadlines. Nordic freight operators are pre-ordering cold-climate viscosity specifications ahead of 2030 mandates.
- Pneumatic Systems:Compressed air actuation retains niche deployment in legacy Eastern European fleets requiring minimal electronic infrastructure. These systems interface with 40-year-old braking architectures without full cab reconstruction.
- Integrated Control Solutions:Software-defined platforms embedding diagnostic telemetry and energy optimization are capturing investment from urban transit providers. China's CTCS-4 alignment is conditioning export market access on indigenous protocol compatibility.
Electromechanical systems anchor current procurement volume; integrated control solutions are expanding at the steepest trajectory as software-defined functionality consolidates multiple safety systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in railway control stands favor manufacturing economies with captive domestic demand. China and Germany run structural surpluses in electronic control architectures. India and Brazil remain net importers of SIL-certified assemblies.
China
High-speed rail expansion absorbs the majority of domestic electronic control stand production. The National Railway Administration's GB standards align indigenous designs with CTCS signaling protocols. CRRC Corporation anchors manufacturing in Changzhou and Qingdao, supplying both domestic corridors and export markets across Southeast Asia.
Germany
ERTMS Baseline 3 mandates are compressing replacement cycles for legacy electromechanical systems across Deutsche Bahn's regional networks. The EU F-Gas Regulation accelerates hydraulic fluid substitution deadlines. Siemens Mobility maintains engineering concentration in Munich and Erlangen, dominating retrofit contracts for cross-border freight corridors.
India
Dedicated freight corridor investments under the Ministry of Railways are specifying RDSO-compliant electronic control architectures. Electrification programs across the Eastern and Western Dedicated Freight Corridors are mandating SIL-2 validated platforms. Manufacturing clusters in Chennai and Pune are scaling assembly capacity for domestic procurement.
United States
Heavy-haul freight operators extend hydraulic system service lives through component-level refurbishment, delaying electronic conversion. The Federal Railroad Administration maintains prescriptive braking standards that slow ERTMS-style harmonization. Chicago and Omaha serve as maintenance hubs where third-party contractors capture overhaul volumes from Class I railroads.
Brazil
Urban transit providers in São Paulo and Rio de Janeiro are modernizing metro fleets with integrated digital interfaces. ANVISA-equivalent rail safety protocols are converging toward international SIL standards. Maintenance contractors in the ABC Paulista industrial zone are piloting subscription-based control stand upgrade models.
Railway Control Stands Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing captive rail divisions. The supplier base fragments between full-system integrators with signaling expertise and component specialists focused on actuation hardware. Three archetypes dominate: vertically integrated mobility conglomerates, state-backed rolling stock manufacturers, and brake-system specialists extending into cab controls. Competitive dynamics center on certification speed and aftermarket service bundling rather than price alone.
Among European-based integrators, Alstom and Siemens Mobility exemplify the diversified mobility conglomerate archetype, combining signaling expertise with control stand manufacturing. CRRC Corporation represents the state-backed manufacturer model, leveraging domestic procurement scale. These three anchors occupy positions that condition market access through certification relationships and installed base leverage.
| Leading Market Players |
|---|
| ABB |
| Alstom |
| Siemens Mobility |
| Hitachi Rail |
| Toshiba |
| Thales Group |
| Knorr-Bremse |
| CRRC Corporation |
| Bombardier |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Deutsche Bahn and Siemens Mobility lock in multi-year supply access for ERTMS-compatible electronic control stands while fixing price visibility against raw material volatility. These contracts bundle hardware procurement with predictive maintenance subscriptions, transferring lifecycle cost risk from operator to supplier.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade premiums for SIL-3 validated architectures serving Germany's high-speed corridors, while standard tiers target RDSO-compliant volumes for India's freight electrification. Price differentiation stems from safety integrity validation depth and after-sales service bundling. Cost compression in economy tiers is intensifying because Chinese state-backed manufacturers leverage captive domestic scale. Freight companies in North America exhibit highest price sensitivity, deferring electronic conversion through component refurbishment cycles.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites critical IGBT and microcontroller supply for electronic control stand production. Manufacturing concentrates in Germany, China, and India, with Changzhou and Qingdao feeding CRRC's domestic high-speed expansion while Munich and Erlangen anchor Siemens Mobility's European retrofit capacity. Raw material dependencies span rare-earth magnets for brushless DC motors, synthetic ester hydraulic fluids for F-Gas compliance, and specialized seal polymers for cold-climate damping. Single-source vulnerability concentrates in Taiwan-based foundry capacity. Distribution runs through OEM-direct channels for state railway tenders and third-party maintenance contractor networks for aftermarket overhaul volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions are expanding faster than hardware sales as Brazilian and Mexican operators pilot bundled upgrade models. Service-attach revenue layers now determine supplier profitability more than initial equipment margins.
For Market Incumbents: Consolidate aftermarket service networks against Polish and Czech specialist contractors displacing OEM channels through faster turnaround guarantees. Acquire SIL certification engineering capacity in Stuttgart and Munich to offset aging specialist scarcity. Backward integration into brushless DC motor production reduces exposure to Taiwan semiconductor supply concentration.
For New Entrants and Emerging Players: Predictive maintenance software gaps where incumbents under-serve create entry points for cloud-native diagnostic platforms. Target maintenance contractor channels in Brazil's ABC Paulista industrial zone and Mexico's privatized freight corridors. Lead with retrofit-as-a-Service subscription models bundling hardware installation and remote monitoring under unified contracts.
For Investors and Strategic Acquirers: Brake-system specialists extending into cab controls represent the most defensible acquisition archetype for signaling-convergence exposure. Long-term viability hinges on ERTMS and CTCS protocol alignment across the analysis window. Monitor divergence between regional certification regimes as inflection indicator for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Drives | Captive brushless DC production insulates Siemens Mobility from Taiwan foundry bottlenecks. |
| Retrofit-as-a-Service Launch | German regional operators pilot subscription bundles consolidating hardware and predictive maintenance. |
| SIL-3 Certification Investment | Multi-year IEC 61508 validation timelines freeze smaller competitors from tender participation. |
| Maintenance Contractor Channel Expansion | Polish and Czech specialists displace OEM networks through faster turnaround guarantees. |
| Synthetic Ester Fluid Pre-Ordering | Nordic freight operators secure cold-climate viscosity specifications ahead of F-Gas deadlines. |
Research Methodology
A standing panel of railway procurement directors, maintenance contractor operations heads, SIL validation engineers, and signaling system integrators provided ongoing calibration across primary interview cycles. Secondary validation drew from EU Agency for Railways ERTMS deployment databases, China's National Railway Administration GB standard filings, Indian Ministry of Railways RDSO specifications, and IEC 61508 certification registries. Bottom-up equipment procurement tracking triangulated against top-down infrastructure investment forecasts from national railway authorities.
Consistency checks validated volume and value outputs against external benchmarks including rolling stock delivery schedules, electrification program announcements, and maintenance outsourcing contract disclosures across the analysis window. Segmentation modeling incorporated product architecture type, operational application intensity, end-user procurement centralization, and actuation technology physics. CAGRs derived from equipment replacement cycle compression under regulatory mandate timelines, weighted by fleet age profiles and interoperability compliance deadlines.
Underlying assumptions cover ERTMS Baseline 3 rollout pacing, CTCS-4 protocol finalization, and F-Gas Regulation phasedown adherence, with deviation risk concentrated in semiconductor supply continuity and SIL engineering talent availability. Practitioners should keep alternative scenarios live as regional certification regime divergence and state-backed procurement channel preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Point Machine Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Train Transformer Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railway Sliding Bearing Market