
 Exhaust Hanger Material Market | 2026-2036
Exhaust Hanger Material Market Size, Share, and Industry Trends Forecast 2026-2036
Exhaust Hanger Material Market Analytics
Supplier consolidation from single-source to multi-source arrangements is shifting procurement risk profiles across the exhaust hanger material value chain. Tenneco Inc. leverages its captive rubber compounding capacity to control raw material quality from polymer through finished hanger. Faurecia anchors European OEM supply through integrated exhaust system platforms that bundle hanger modules with aftertreatment hardware. Bosal International competes on geographic reach, sustaining foundry-to-assembly operations across multiple manufacturing zones.
Exhaust hanger materials comprise elastomeric and metallic compounds engineered to suspend exhaust system components while isolating vibration, with rubber formulations typically specifying durometer hardness between 50 and 70 Shore A for optimal damping across temperature extremes from minus forty to two hundred degrees Celsius. Polyurethane and rubber material types dominate current volume, with polyurethane capturing margin pools in performance automotive applications requiring superior oil and ozone resistance. Steel retains structural share in heavy-duty form factors where load-bearing capacity exceeds polymer limits, though lightweight variants are gaining specification in aerospace and marine applications seeking mass reduction.
The EPA enforces tailpipe emission durability standards that extend hanger service life requirements to fifteen years or one hundred fifty thousand miles, compelling material upgrades in US-bound platforms. EMA and REACH frameworks in Europe restrict certain plasticizer chemistries in rubber compounds, redirecting formulation investment toward bio-based curatives and low-Vulcanization systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant certification cycles and stranded inventory positions.
Market Dynamics
Automotive OEMs are consolidating supplier bases while simultaneously demanding material performance upgrades that exceed legacy rubber specifications, compressing margins for compounders caught between volume concentration and R&D escalation.
Growth Catalysts
- Euro 7 emission durability mandates:Extended service life requirements for exhaust hardware are compelling material upgrades to advanced polyurethane formulations that withstand thermal cycling stress.
- Electric vehicle platform differentiation:Battery thermal management systems require vibration isolation components with broader temperature operating windows than conventional internal combustion applications.
- German premium automotive cluster:Stuttgart and Munich production corridors specify certification-grade polyurethane hangers for performance vehicle segments with stringent NVH targets.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs swing with crude oil derivatives, compressing formulation margins for non-integrated compounders.
- REACH plasticizer restrictions:ECHA phased bans on phthalate-based curatives force reformulation investments that strand existing compound inventories.
- Steel substitution ceiling:Heavy-duty commercial vehicle load requirements exceed polymer tensile limits above 500 kilograms per hanger point.
Strategic Opportunities
- Marine propulsion electrification:Yacht and commercial vessel builders seek lightweight exhaust suspension for hybrid powertrain retrofits in Mediterranean and Gulf Coast shipyards.
- Bio-based curative convergence:Castor oil-derived polyols combined with low-Vulcanization chemistry open premium positioning for sustainability-certified automotive platforms.
- Aftermarket channel digitization:Direct-to-installer platforms bypass traditional distributor tiers, capturing margin pools in North American independent repair networks.
Industry Challenges
- Polymer rheology expertise scarcity:Compound formulation for minus forty to two hundred degree Celsius damping requires specialized material science talent concentrated at Tier 1 automotive suppliers.
- Dual certification timeline compression:Simultaneous EPA fifteen-year durability validation and ECHA substance registration create parallel testing burdens for US-European platform suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhaust Hanger Material Market |
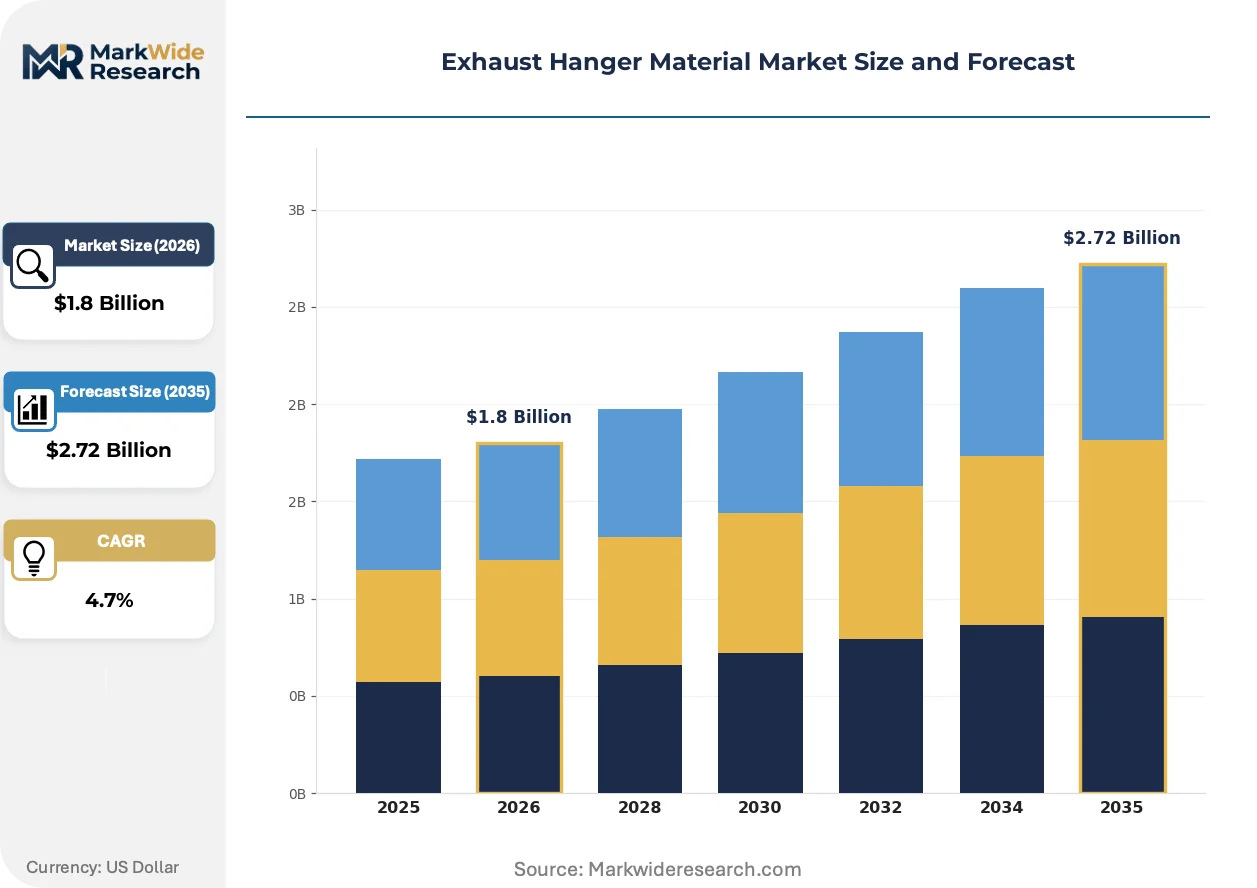
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber, Polyurethane, Nylon, Steel Application: Automotive, Marine, Industrial, Aerospace End User: Manufacturers, Aftermarket, OEMs, Distributors Form Factor: Standard, Custom, Heavy-Duty, Lightweight |
| Companies Covered | Tenneco Inc., Faurecia, Bosal International, Walker Exhaust Systems, HJS Emission Technology, Magna International Inc., Yutaka Giken Co., Ltd., AP Exhaust Technologies, Dinex Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhaust Hanger Material Market Evolving Landscape
Material science advances are converging with regulatory durability mandates to reshape specification hierarchies across automotive, marine, and aerospace exhaust suspension applications.
Self-healing polyurethane formulations are integrating microcapsule-based repair chemistry that autonomously seals microcracks from thermal fatigue. Tier 1 suppliers in Germany and Japan are qualifying these compounds for premium vehicle platforms with fifteen-year corrosion warranties. The technology is integrating predictive maintenance data streams from connected vehicle architectures, enabling condition-based replacement scheduling rather than fixed-interval service.
EPA tailpipe emission durability rules now extend hanger service life verification to one hundred fifty thousand miles, forcing compounders to accelerate thermal aging test protocols. The regulation compresses development cycles for new platform introductions while elevating documentation burdens for material traceability. US-bound vehicle programs are responding by locking specifications earlier in design phases, reducing late-stage formulation flexibility.
Fleet operators and commercial vehicle lessors are unbundling exhaust system maintenance from powertrain service contracts, creating discrete procurement categories for hanger replacement components. Independent repair networks in Texas and California are capturing this volume through specialized exhaust service bays with rapid polyurethane-to-steel specification cross-reference capabilities. The pattern concentrates in regions with high commercial vehicle registration density and stringent roadside emission inspection enforcement.
Exhaust Hanger Material Market Segmentation
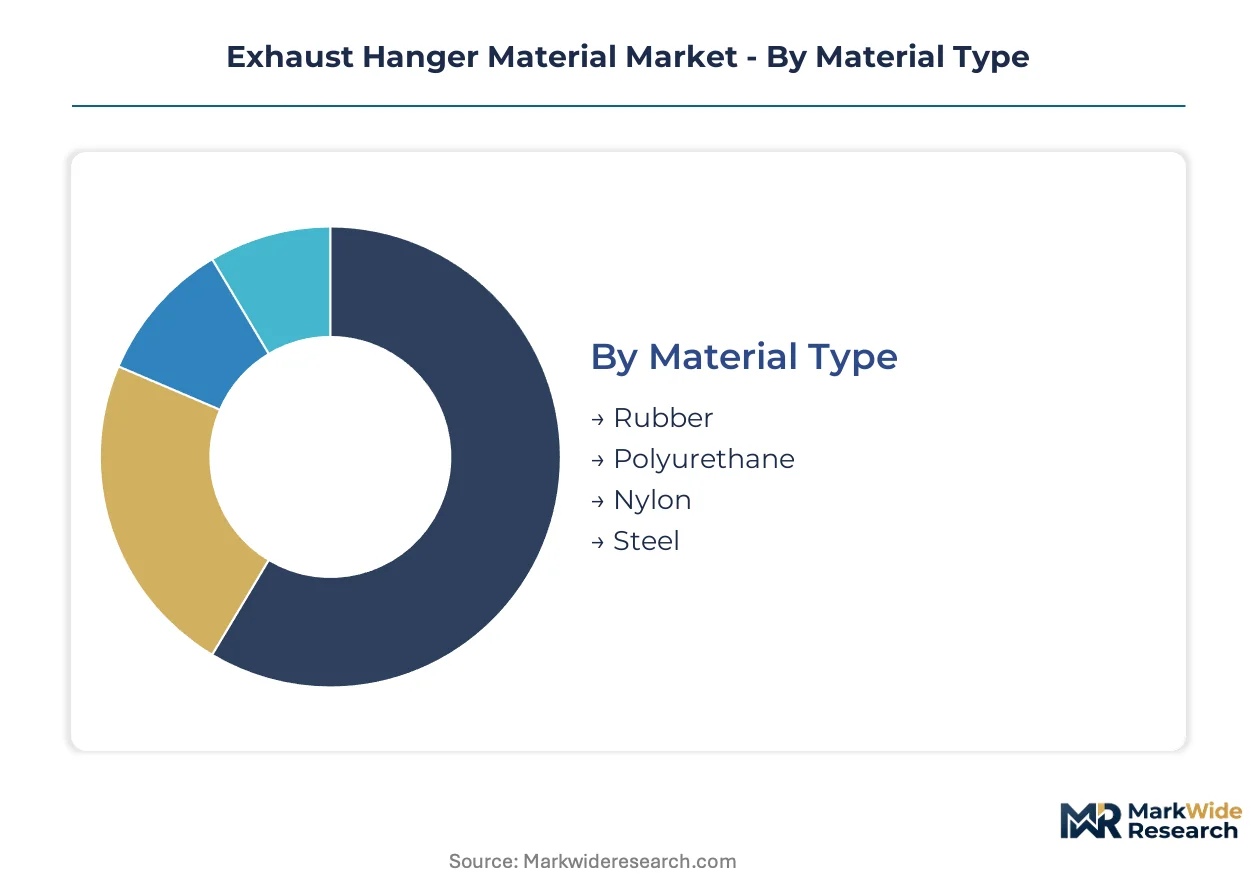
Material specification tiers in exhaust hanger procurement map directly to thermal cycling demands and load-bearing requirements across vehicle platforms. Upgrade cycles from conventional rubber to advanced polymer compounds are shortening as emission durability mandates extend service life verification periods.
Material Type:
Replacement-cycle acceleration is compressing compound qualification timelines, with thermal aging protocols now spanning fifteen-year equivalent testing before platform approval.
- Rubber:Formulations specify durometer hardness between 50 and 70 Shore A, balancing vibration damping with temperature resilience from minus forty to two hundred degrees Celsius. German premium automotive clusters in Stuttgart and Munich specify certification-grade rubber hangers for NVH-sensitive performance vehicle segments.
- Polyurethane:Superior oil and ozone resistance characteristics position this compound for thermal cycling stress under Euro 7 emission durability mandates. Demand concentrates in specification-grade automotive applications where extended service life requirements exceed legacy rubber performance envelopes.
- Nylon:Engineering thermoplastic variants serve cost-optimized platforms with moderate temperature exposure profiles.
- Steel:Structural metal retains specification in heavy-duty form factors where load-bearing capacity exceeds 500 kilograms per hanger point.
Volume placements concentrate in rubber formulations; the faster expansion belongs to polyurethane.
Application:
End-use diversification is fragmenting procurement specifications, with each vertical imposing distinct thermal and mechanical performance thresholds.
- Automotive:Internal combustion platforms drive baseline volume, while battery thermal management systems in electric vehicles require vibration isolation across broader temperature operating windows. EPA fifteen-year durability validation and ECHA substance registration create parallel testing burdens for US-European platform suppliers.
- Marine:Yacht and commercial vessel builders seek lightweight exhaust suspension for hybrid powertrain retrofits in Mediterranean and Gulf Coast shipyards. Castor oil-derived polyols combined with low-Vulcanization chemistry open sustainability-certified positioning.
- Industrial:Heavy equipment manufacturers specify steel-dominant hangers for load-bearing applications exceeding polymer tensile limits.
- Aerospace:Mass reduction priorities in aircraft systems are gaining specification for lightweight polymer variants.
Automotive captures the largest placement base; marine applications are climbing the fastest.
End User:
Channel structure is bifurcating between captive OEM supply and independent aftermarket procurement with diverging specification requirements.
- OEMs:Integrated exhaust system platforms bundle hanger modules with aftertreatment hardware, locking specifications early in design phases. Tenneco Inc. leverages captive rubber compounding capacity to control raw material quality from polymer through finished hanger.
- Aftermarket:Direct-to-installer platforms bypass traditional distributor tiers, capturing margin pools in North American independent repair networks. Fleet operators in Texas and California are unbundling exhaust system maintenance from powertrain service contracts.
- Manufacturers:Tier 1 suppliers concentrate polymer rheology expertise for minus forty to two hundred degree Celsius damping formulations.
- Distributors:Traditional wholesale tiers face compression as digitized procurement channels disintermediate inventory positions.
OEM placements dominate value capture; aftermarket channels are gaining share fastest.
Form Factor:
Load specification tiers are stratifying procurement around weight-bearing thresholds and thermal exposure profiles.
- Heavy-Duty:Exceeds 500 kilograms per hanger point, mandating steel construction for commercial vehicle and industrial equipment applications.
- Standard:Baseline rubber and polyurethane formulations serve mass-market automotive platforms with moderate thermal cycling demands.
- Lightweight:Advanced polymer compounds address aerospace and marine mass reduction priorities where every kilogram translates to fuel efficiency.
- Custom:Application-specific geometries accommodate non-standard exhaust routing in performance vehicle and specialty equipment builds.
Standard form factors anchor volume; lightweight specifications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock corridors in the US Gulf Coast and polymer compounding clusters in Germany's Rhine-Ruhr region anchor raw material availability for advanced exhaust hanger formulations. These localities shape procurement patterns across automotive, marine, and aerospace verticals.
United States
EPA fifteen-year durability mandates and heavy-duty fleet electrification drive specification-grade polyurethane demand. The agency's tailpipe emission standards extend hanger service life verification to one hundred fifty thousand miles. Houston polymer compounders supply Gulf Coast automotive assembly plants with thermal-cycling-resistant formulations.
Germany
Premium vehicle production corridors in Stuttgart and Munich specify certification-grade polyurethane hangers for NVH-sensitive platforms. ECHA REACH plasticizer restrictions redirect formulation investment toward bio-based curatives. Stuttgart-based Tier 1 suppliers integrate captive rubber compounding from polymer through finished hanger.
China
Domestic EV platform proliferation and marine propulsion electrification expand vibration isolation component procurement. MEE emission durability frameworks align with Euro 7 thermal cycling standards. Yangtze River Delta shipyards specify lightweight exhaust suspension for hybrid powertrain retrofits.
Japan
Automotive OEM consolidation and aerospace mass reduction priorities elevate advanced polymer specifications. METI industrial standards govern material traceability for export-bound platforms. Nagoya production corridors concentrate polymer rheology expertise for minus forty to two hundred degree Celsius damping formulations.
India
Commercial vehicle fleet expansion and aftermarket channel digitization fragment procurement specifications. BIS automotive component standards intersect with state-level roadside emission enforcement. Tamil Nadu automotive clusters source rubber and polyurethane compounds for cost-optimized domestic platforms.
Exhaust Hanger Material Market Competitive Landscape
Global majors compete with regional champions across integrated exhaust system platforms and captive material compounding capabilities. Supplier consolidation from single-source to multi-source arrangements shifts procurement risk profiles across the value chain. Three archetypes dominate: integrated system bundlers, captive compounders, and geographic reach specialists. M&A activity concentrates around aftertreatment hardware integration, while capacity expansion targets marine and aerospace diversification.
Within the integrated system tier, Tenneco Inc. and Faurecia occupy positions exemplifying captive material control and platform bundling strategies respectively. Bosal International represents the geographic reach archetype, sustaining foundry-to-assembly operations across multiple manufacturing zones. These three entities anchor competitive dynamics around raw material quality assurance, early design-phase specification locking, and multi-zone production flexibility.
| Leading Market Players |
|---|
| Tenneco Inc. |
| Faurecia |
| Bosal International |
| Walker Exhaust Systems |
| HJS Emission Technology |
| Magna International Inc. |
| Yutaka Giken Co., Ltd. |
| AP Exhaust Technologies |
| Dinex Group |
| Others |
Value Network & Pricing Analysis
German premium automotive OEM procurement concentration in Stuttgart and Munich corridors anchors contract-based long-term offtake pricing for certification-grade polyurethane hangers. EPA fifteen-year durability mandates and ECHA REACH plasticizer restrictions compress formulation flexibility while locking specifications early in platform design phases.
Pricing Analysis
Warranty bundling with exhaust system platforms separates OEM captive supply from unbundled aftermarket procurement. Three-tier pricing structure across certification-grade polyurethane, standard rubber formulations, and economy nylon compounds reflects thermal cycling performance and load-bearing thresholds. Cost compression in standard rubber tiers intensifies because REACH plasticizer bans force stranded inventory write-downs. Fleet operators in Texas and California demonstrate highest price sensitivity through unbundled maintenance contracts, while German premium OEMs exhibit lowest sensitivity due to NVH warranty integration.
Supply Chain Analysis
Single-source vulnerability sits with polyol and isocyanate feedstock concentration in US Gulf Coast petrochemical corridors. Manufacturing gravity centers on Germany, China, and Japan for polymer compounding and finished hanger assembly. Raw material dependencies draw from crude oil derivatives, castor oil bio-feedstocks, and steel foundry outputs. Tariff exposure on cross-border polyurethane precursor shipments elevates landed cost volatility. Distribution runs through integrated exhaust system platform bundlers for OEM channels and digitized direct-to-installer networks for aftermarket capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where Tier 1 captive compounding capabilities and dual-certification burdens force non-integrated compounders toward exit or acquisition.
For Market Incumbents: Hedge against REACH plasticizer restriction cascades by accelerating bio-based curative qualification in captive Rhine-Ruhr compounding facilities. Secure early-design-phase specification locks with Stuttgart and Munich OEM platform engineers before EPA-ECHA regulatory divergence widens. Backward integration into castor oil polyol supply chains insulates margin compression from petrochemical feedstock volatility. For New Entrants and Emerging Players: Launch via direct-to-installer digital platforms targeting Texas and California fleet unbundling trends in aftermarket exhaust maintenance. Marine propulsion electrification in Mediterranean and Gulf Coast shipyards offers penetrable white-space with lower certification barriers than automotive OEM supply. Position on castor oil-derived polyurethane sustainability credentials for yacht builder procurement committees seeking green retrofit positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap compounders with stranded phthalate-based inventory in Germany and US Midwest manufacturing zones. Five-to-ten-year viability hinges on dual EPA-ECHA certification completion and captive thermal aging test protocol investment. Watch for Tier 1 supplier M&A announcements targeting aftertreatment hardware integration as inflection signal for hanger module bundling acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyol Supply | Castor oil sourcing secures REACH-compliant formulation pathways ahead of ECHA phased bans. |
| Dual-Certification Test Protocol Investment | Parallel EPA fifteen-year durability and ECHA substance registration accelerates platform approval timelines. |
| Marine Application Diversification | Mediterranean and Gulf Coast shipyard penetration captures hybrid powertrain retrofit demand outside automotive consolidation. |
| Direct-to-Installer Channel Digitization | Bypassing wholesale distributor tiers captures margin pools in North American independent repair networks. |
| Self-Healing Polyurethane Formulation Launch | Microcapsule-based repair chemistry qualifies for German premium vehicle fifteen-year corrosion warranty coverage. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and polymer compounding technical directors underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EPA emission durability filings, ECHA REACH substance registrations, vehicle production databases, and customs trade records on polyol and isocyanate imports. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates across material type, application, and end-user channels.
Rate-of-change decomposition isolates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span material specification tier, vehicle propulsion architecture, OEM versus aftermarket channel, and regional regulatory cluster alignment. CAGRs derive from weighted average of platform introduction timelines, replacement cycle acceleration, and thermal cycling durability mandate phase-ins. Industry-specific forecast inputs incorporate EPA fifteen-year service life verification protocols and Euro 7 emission durability alignment with MEE frameworks in China.
The model assumes a particular technology adoption path; alternative pathways for self-healing polyurethane or steel-polymer hybrid form factors would alter the outlook. Forecasts reflect documented assumptions on regulatory timeline adherence, feedstock cost trajectories, and OEM supplier consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Car Rack Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Global Automotive Dynamic Chassis Control System Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Automotive Propeller Shaft Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Motorcycle Battery Chargers Market