
 Tire Repair Patch Market | 2026-2036
Tire Repair Patch Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Repair Patch Market Analytics
Wholesale distributor networks are reshaping how tire repair patches reach end users across fragmented automotive aftermarket channels. ITW Global Tire Repair leverages direct-to-fleet contracts to sustain volume commitments in North America. REMA TIP TOP anchors European supply through specialized rubber compounding expertise. Hangzhou Xinyousheng competes on manufacturing scale, serving Asia-Pacific markets with cost-optimized patch production.
A tire repair patch is a vulcanized rubber or synthetic compound membrane, typically reinforced with fabric cord layers and activated by chemical cement or heat-cure bonding, designed to seal punctures and restore structural integrity to pneumatic tires. The primary commercial purpose is to extend tire service life and reduce replacement frequency in high-mileage vehicle operations. Pre-cured patches dominate professional repair channels due to consistent adhesion performance under workshop conditions, while self-adhesive variants are gaining traction among DIY consumers seeking tool-free application. Tubeless patches command margin premiums in passenger and light truck segments where radial construction demands precise injury mapping.
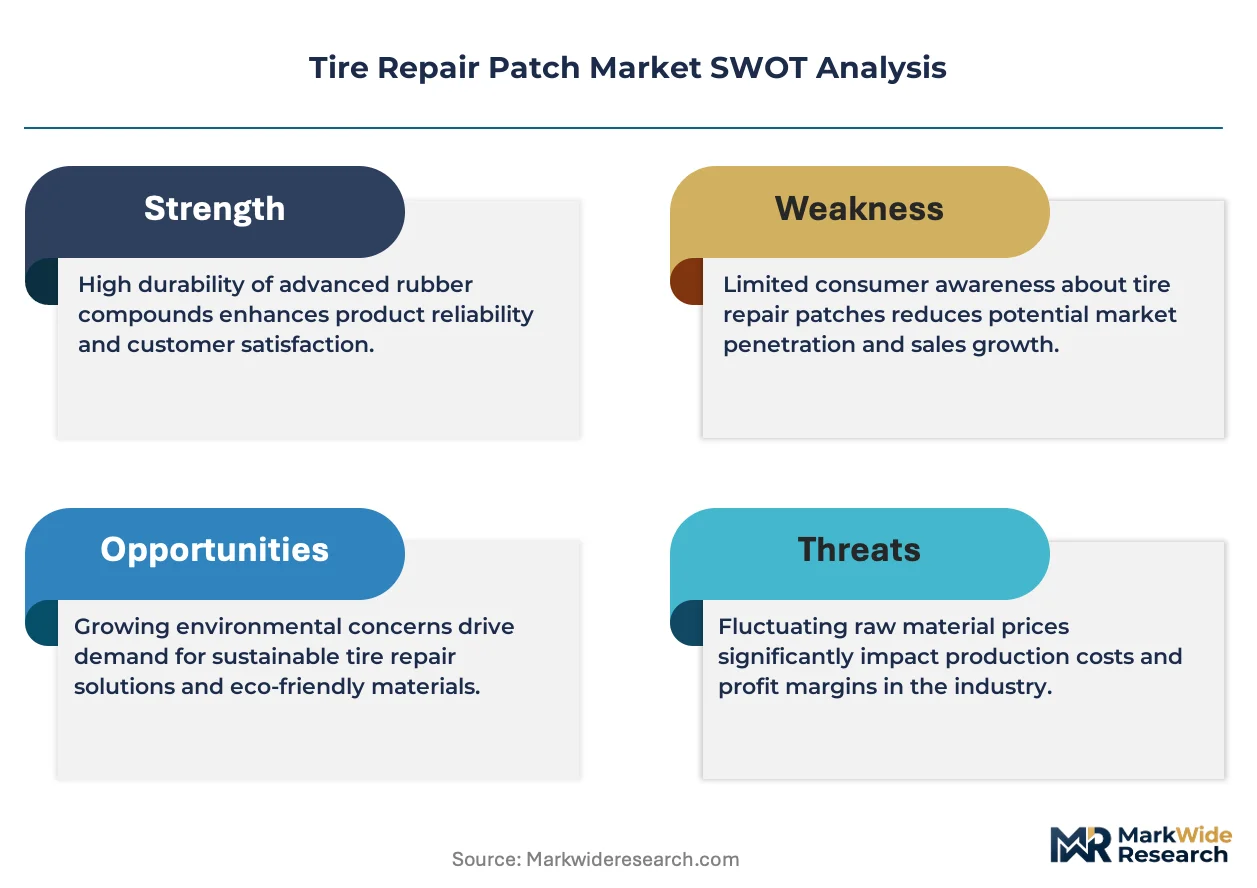
FDA oversight of rubber chemical constituents, EPA guidelines on volatile organic compounds in tire repair cements, and REACH substance restrictions collectively determine which adhesive formulations and patch materials gain market access in regulated economies. NHTSA tire safety standards indirectly shape repair patch specifications by defining acceptable injury dimensions and repair zone parameters for highway-speed vehicles. Stakeholders must monitor evolving chemical disclosure requirements and regional certification protocols to maintain product registration and avoid supply exclusion.
Market Dynamics
REACH chemical restrictions in Europe are forcing reformulation of adhesive cements across the tire repair patch supply base, compressing margins for manufacturers dependent on legacy rubber compound recipes while creating first-mover advantages for compliant producers.
Growth Catalysts
- Commercial Fleet Expansion:Long-haul trucking operators in the United States are standardizing patch protocols to extend tire replacement cycles amid rising rubber input costs. Fleet maintenance contracts now specify pre-cured patch systems for radial tire repairs.
- China Manufacturing Scale:Domestic production capacity for vulcanized rubber membranes is concentrating in Zhejiang and Shandong provinces, reducing unit costs for Asia-Pacific aftermarket distributors.
- Tubeless Radial Adoption:Passenger vehicle OEM specifications for tubeless construction are expanding the addressable injury zone for professional-grade patches, displacing plug-only repairs in light truck segments.
Market Restraints
- Raw Material Volatility:Synthetic rubber and fabric cord prices fluctuate with crude oil derivatives, squeezing gross margins for patch manufacturers without backward integration into compound production.
- Supply Concentration Risk:Chemical cement activators and specialty adhesives rely on a narrow base of European and Chinese specialty chemical suppliers, exposing the value chain to export licensing delays.
- Technical Limitation:Self-adhesive patch variants fail to achieve vulcanized bond strength, restricting their use to temporary repairs and capping price realization in professional channels.
Strategic Opportunities
- India Aftermarket Penetration:Commercial vehicle density on national highways is rising faster than organized service network expansion, creating whitespace for branded patch distribution through tire dealer chains.
- E-Mobility Tire Specifications:Electric vehicle weight distribution and torque profiles are accelerating wear patterns in specific tread zones, opening demand for reinforced patches in high-stress injury locations.
- CE Marking Harmonization:Unified EU certification for tire repair materials is reducing country-by-country registration burdens, enabling faster market access for compliant Asian manufacturers.
Industry Challenges
- Vulcanization Skill Shortage:Professional repair channels face shrinking technician pools trained in heat-cure bonding techniques, forcing investment in automated curing equipment.
- Certification Timeline Compression:Evolving NHTSA repair zone parameters and ECHA substance evaluations are shortening product registration windows, requiring accelerated reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Repair Patch Market |
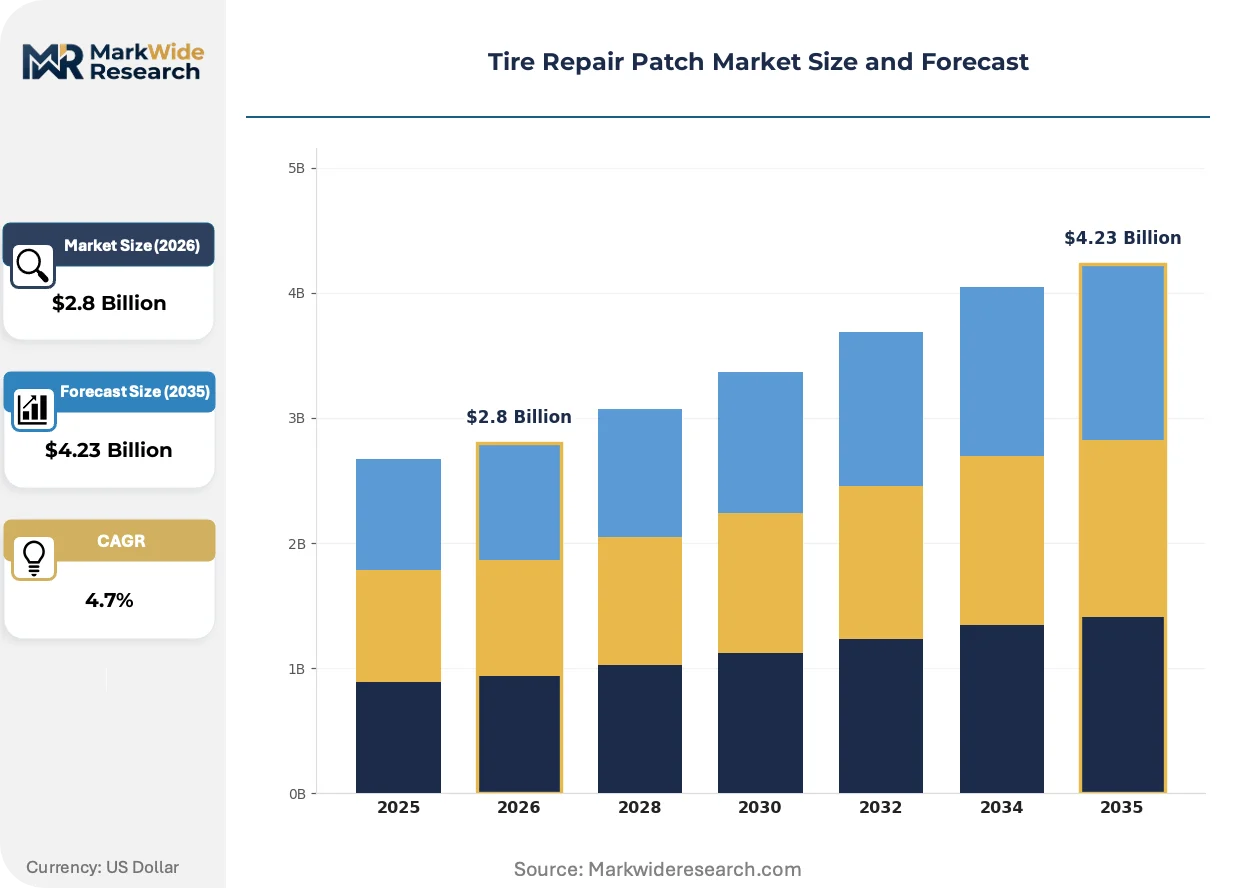
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Patches, Self-Adhesive Patches, Tubeless Patches, Pre-Cured Patches Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Equipment End User: Automotive Repair Shops, DIY Consumers, Fleet Operators, Tire Retailers Distribution Channel: Online Stores, Retail Outlets, Wholesale Distributors, Auto Parts Stores |
| Companies Covered | REMA TIP TOP, Mahant Industries, ITW Global Tire Repair, Hangzhou Xinyousheng (Sford) Rubber Products Co., Ltd, Shangyu EXX Tire Parts Co., Ltd, TECH Tire Repair, Unipatch Rubber Limited, Optimus Enterprise Private Limited, Lotus Rubber Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Repair Patch Market Evolving Landscape
Digital inventory management and predictive tire monitoring systems are reshaping how repair patches are procured and deployed across commercial fleets, shifting procurement from reactive spot-buying to integrated maintenance planning.
RFID-enabled patch tracking is digitizing warranty verification and repair history documentation for fleet operators. Large logistics companies in Germany and the United States are embedding patch application data into centralized tire asset management platforms. This connectivity is digitizing compliance audit trails and compressing dispute resolution cycles between repair shops and fleet procurement departments.
REACH substance restrictions on aromatic solvents in chemical cements are mandating reformulation of activation compounds across European supply chains. Manufacturers are substituting bio-based adhesion promoters for traditional petroleum-derived alternatives. Professional repair shops in France and Italy are absorbing higher material costs while awaiting certification clarity from ECHA on acceptable compound thresholds.
Fleet procurement departments are consolidating vendor relationships through multi-year supply agreements that bundle patch materials with mounting and balancing services. Tire service chains in Brazil and Mexico are displacing independent repair shops through integrated maintenance subscriptions. This concentration is most visible in long-haul trucking corridors where route density supports dedicated service lane contracts.
Tire Repair Patch Market Segmentation
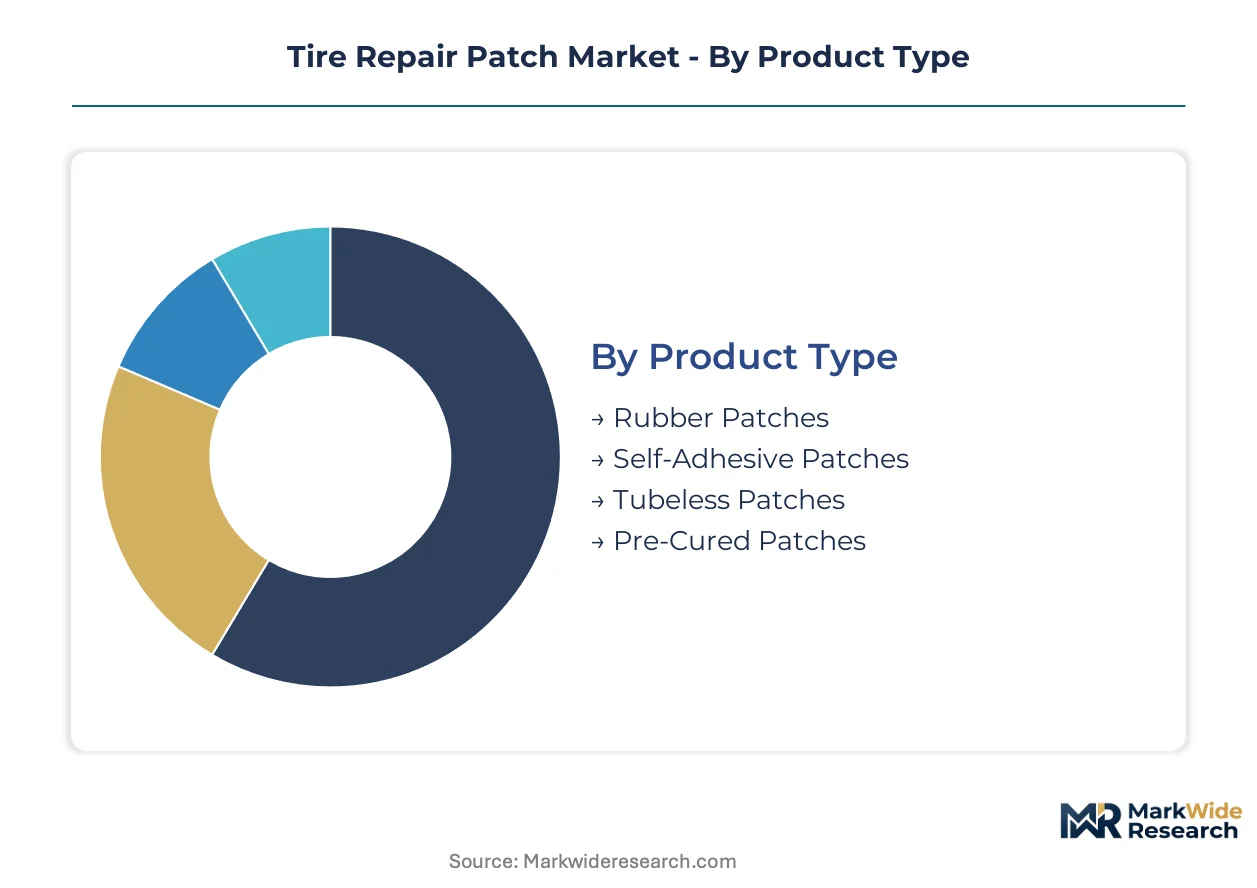
Tire repair patch segmentation reveals distinct service intensity profiles across customer channels. Fleet operators demand vulcanized solutions with documented repair histories, while DIY consumers prioritize tool-free application speed over bond durability.
Product Type:
After-sales service intensity varies sharply across patch technologies, with professional channels requiring heat-cure equipment and technician certification while consumer segments favor instant-adhesion formats.
- Pre-Cured Patches:These vulcanized rubber membranes arrive factory-cured with fabric reinforcement layers, activated by chemical cement during installation. Long-haul trucking fleets in the United States specify pre-cured systems under standardized maintenance protocols to maximize radial tire replacement cycles amid volatile natural rubber prices.
- Tubeless Patches:Engineered for radial construction injuries, these patches feature reinforced shoulder designs that accommodate flex stress in belted tire architectures. Passenger vehicle specifications for tubeless OEM fitments in Germany and Japan are expanding the addressable repair zone, displacing plug-only repairs in light truck service bays.
- Rubber Patches:Conventional vulcanized compounds requiring heat-cure activation dominate emerging market repair shops with lower equipment investment thresholds.
- Self-Adhesive Patches:Pressure-activated synthetic membranes serve temporary repair scenarios where curing equipment is unavailable, limiting price realization in professional channels due to bond strength constraints.
By volume, rubber patches lead. By growth pace, pre-cured patches are climbing the fastest.
Application:
Vehicle duty cycles determine patch performance specifications, with commercial applications demanding reinforced constructions that withstand sustained load stress.
- Commercial Vehicles:Radial truck tires operating at sustained highway speeds require patches rated for dynamic load deformation. Brazilian long-haul corridors and Mexican freight routes are standardizing professional repair protocols as fleet management contracts consolidate vendor relationships.
- Passenger Vehicles:Tubeless radial specifications dominate OEM fitments, creating demand for precision-mapped injury repairs in shoulder and crown zones. Japanese and German automaker tire specifications indirectly shape acceptable patch dimensions through warranty compliance requirements.
- Two-Wheelers:Bias-ply construction and lower speed ratings permit simpler patch geometries, with roadside repair networks in India and Southeast Asia driving volume through high-frequency, low-margin transactions.
- Heavy Equipment:Off-the-road tires for mining and construction utilize specialized patch compounds resistant to cut-and-chip damage in abrasive operating environments.
Commercial vehicles generate the highest revenue per repair event. Two-wheelers are expanding most quickly in absolute transaction count.
End User:
Procurement authority concentration distinguishes institutional buyers from fragmented consumer decision-making, reshaping distribution economics.
- Fleet Operators:Centralized procurement departments negotiate multi-year supply agreements bundling patch materials with mounting and balancing services. Large logistics companies in Germany embed repair documentation into tire asset management platforms, digitizing compliance audit trails.
- Automotive Repair Shops:Independent service bays face shrinking technician pools trained in heat-cure bonding, accelerating investment in automated curing equipment to maintain throughput.
- Tire Retailers:Service chains in Brazil and Mexico are displacing independent repair shops through integrated maintenance subscriptions tied to route-density corridors.
- DIY Consumers:Tool-free application preferences drive self-adhesive patch demand, though bond strength limitations restrict use to temporary repairs.
Fleet operators command the steepest volume discounts. Tire retailers are gaining share fastest through subscription bundling.
Distribution Channel:
Channel structure reflects the technical assistance intensity required for proper patch selection and application.
- Wholesale Distributors:These intermediaries aggregate fragmented automotive aftermarket demand, maintaining inventory buffers that absorb raw material price volatility for downstream repair shops.
- Auto Parts Stores:Counter staff technical knowledge influences patch specification accuracy, with NAPA and similar chains in the United States investing in repair protocol training.
- Retail Outlets:Big-box automotive sections serve DIY consumers with limited product education, favoring self-adhesive formats with prominent packaging instructions.
- Online Stores:E-commerce penetration remains constrained by the need for real-time injury assessment, though fleet procurement departments utilize digital platforms for standardized material replenishment.
Wholesale distributors handle the greatest transaction volume. Online stores are expanding most quickly among fleet procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fleet operators command premium pricing for vulcanized repair systems, while Chinese manufacturers extract cost advantages through Zhejiang and Shandong production clusters. This asymmetry shapes procurement patterns across commercial channels.
United States
Long-haul trucking fleets operating I-80 and I-95 corridors standardize pre-cured patch protocols under NHTSA tire safety guidelines. EPA volatile organic compound regulations constrain adhesive cement formulations, favoring domestic compounders with reformulation capabilities. Texas and Ohio maintenance hubs concentrate vendor relationships through multi-year supply agreements bundling patch materials with mounting services.
Germany
Commercial vehicle density on Autobahn freight routes sustains demand for heat-cure bonding systems with documented repair histories. REACH substance restrictions through ECHA mandate bio-based adhesion promoters, compressing margins for legacy compound recipes. Bavaria and North Rhine-Westphalia host specialized rubber compounding facilities serving fleet operators with integrated tire asset management platforms.
China
Domestic manufacturing scales in Zhejiang and Shandong provinces reduce unit costs for vulcanized rubber membranes serving Asia-Pacific aftermarket distributors. MIIT industrial standards and dual carbon goals tighten emission controls on rubber processing facilities. Hangzhou and Qingdao clusters deepen production capacity for export-oriented patch fabricators competing on cost-optimized output.
India
Commercial vehicle density on national highways rises faster than organized service network expansion, creating whitespace for branded patch distribution through tire dealer chains. BIS certification requirements for automotive rubber products filter substandard imports from unregulated sources. Maharashtra and Gujarat industrial corridors attract patch manufacturers seeking proximity to freight corridor maintenance demand.
Brazil
Long-haul trucking corridors through São Paulo and Minas Gerais states consolidate vendor relationships through integrated maintenance subscriptions displacing independent repair shops. ANVISA oversight of rubber chemical constituents parallels FDA frameworks, though enforcement capacity varies regionally. Southeastern service chains bundle patch procurement with route-density corridor contracts, compressing independent shop market share.
Tire Repair Patch Market Competitive Landscape
Multinational compound specialists and regional scale fabricators split the market along technical certification and cost optimization vectors. Consolidation pressure concentrates among European and North American channels where REACH and EPA compliance costs filter smaller compounders. Three archetypes dominate: integrated rubber compounders with backward integration into adhesive production, specialized patch fabricators serving single geographies, and diversified automotive aftermarket suppliers leveraging existing distribution. Capacity expansion in Asian manufacturing clusters and strategic partnerships linking compound technology with fleet procurement platforms represent the dominant competitive moves reshaping supply relationships.
Among diversified automotive aftermarket suppliers, ITW Global Tire Repair exemplifies the direct-to-fleet contracting archetype in North American channels. REMA TIP TOP anchors European supply positioning through specialized rubber compounding expertise. Hangzhou Xinyousheng occupies the scale-driven manufacturing tier serving Asia-Pacific markets with cost-optimized production. These three entities represent distinct strategic postures: fleet-facing contract structures, technical certification leadership, and volume-centric fabrication respectively.
| Leading Market Players |
|---|
| REMA TIP TOP |
| Mahant Industries |
| ITW Global Tire Repair |
| Hangzhou Xinyousheng (Sford) Rubber Products Co., Ltd |
| Shangyu EXX Tire Parts Co., Ltd |
| TECH Tire Repair |
| Unipatch Rubber Limited |
| Optimus Enterprise Private Limited |
| Lotus Rubber Industries |
| Others |
Value Network & Pricing Analysis
Overcapacity in Shandong province vulcanized rubber membrane production is compressing export pricing power while forcing Zhejiang fabricators toward domestic aftermarket absorption, reshaping how Asian manufacturers calibrate volume commitments against margin preservation.
Pricing Analysis
Configured-to-order pricing for fleet-certified pre-cured patches commands spreads of 40-60% above standard catalog SKUs. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales documentation intensity. Cost compression in economy-grade self-adhesive formats is intensifying because REACH-compliant bio-based cement reformulations add 15-25% to raw material burdens. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while independent repair shops in emerging markets face acute margin pressure from input volatility.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for vulcanized membrane exporters. Production gravity centers on Zhejiang and Shandong provinces in China, with secondary concentrations in Maharashtra and Gujarat industrial corridors in India. Synthetic rubber feedstock and fabric cord reinforcement draw from crude oil derivatives and polyester textile streams, respectively. Single-source vulnerability concentrates in European specialty chemical suppliers of cement activators. Distribution runs through wholesale distributor networks that aggregate fragmented automotive aftermarket demand across multi-country territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across North American and European long-haul corridors is shifting buyer power toward volume aggregators, compressing vendor margins and privileging contract structures with embedded service bundling.
For Market Incumbents: Pre-empt margin erosion by securing backward integration into rubber compounding facilities in Zhejiang or Shandong, insulating against synthetic rubber price volatility. Accelerate REACH-compliant adhesive certification ahead of ECHA threshold clarifications to lock in European fleet contracts before reformulation costs fully transmit. Channel control through direct-to-fleet digital platforms represents the priority defensive lever against wholesale distributor disintermediation. For New Entrants and Emerging Players: Establish a beachhead in India's unorganized tire dealer chains serving national highway freight corridors, where commercial vehicle density outpaces branded service network expansion. Target two-wheeler roadside repair networks in Southeast Asia with simplified rubber patch SKUs requiring minimal curing equipment investment. A go-to-market angle anchored to BIS certification compliance filters substandard import competition and builds credibility with domestic distributor gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated vulcanization equipment sub-segments, enabling mid-scale entrants to achieve viable throughput without legacy fixed-asset burdens. Acquisition targets should profile specialized rubber compounders with ECHA pre-certification and captive adhesive formulation capabilities. The signal to watch is fleet procurement department migration toward integrated tire asset management platforms, which will concentrate vendor selection authority and accelerate contract renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive synthetic rubber supply insulates ITW Global Tire Repair and REMA TIP TOP from petrochemical price volatility. |
| REACH-Compliant Adhesive Certification | ECHA-aligned bio-based cement formulations unlock European fleet procurement channels ahead of regulatory enforcement. |
| Direct-to-Fleet Digital Platform Deployment | ITW Global Tire Repair's centralized procurement portals compress distributor margins while embedding multi-year volume commitments. |
| Automated Vulcanization Equipment Investment | Heat-cure bonding automation addresses technician skill shortages in German and United States repair shops. |
| India Tire Dealer Chain Distribution Partnerships | Branded patch penetration through Maharashtra and Gujarat dealer networks captures whitespace from unorganized service expansion. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, aftermarket service chain operators, rubber compounding plant managers, and tire dealer network owners; and secondary validation through customs trade databases, MIIT industrial standard filings, ECHA substance restriction updates, and SEC 10-K disclosures from diversified automotive aftermarket suppliers. Bottom-up patch volume estimates by vehicle class and application were triangulated against top-down tire replacement cycle data and regional commercial vehicle density metrics.
Forecast inputs span product type segmentation across pre-cured, tubeless, rubber, and self-adhesive patch technologies; application dimensions including commercial vehicles, passenger vehicles, two-wheelers, and heavy equipment; and end-user procurement patterns distinguishing fleet operators from independent repair shops and DIY consumers. CAGRs were derived from regression analysis of historical replacement frequency trends, fleet expansion trajectories, and regulatory compliance cost pass-through assumptions across the projection horizon. Industry-specific forecast inputs incorporate REACH substance evaluation timelines and NHTSA repair zone parameter evolution.
Sensitivities concentrate around ECHA cement reformulation thresholds, synthetic rubber price volatility transmission, and fleet procurement platform consolidation velocity. Forecasts reflect documented assumptions regarding technician skill availability and regional certification harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Wheel Spacers and Adapters Market
Tires and Wheels
North America Alloy Wheels Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
EV Tire Market
Tires and Wheels
North America Tire Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
Rechargeable Tires Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Bus Radial Tire Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Tire Carousel Market