
 Italy Automotive Hydraulic Actuators Market | 2026-2036
Italy Automotive Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Hydraulic Actuators Market Foresight
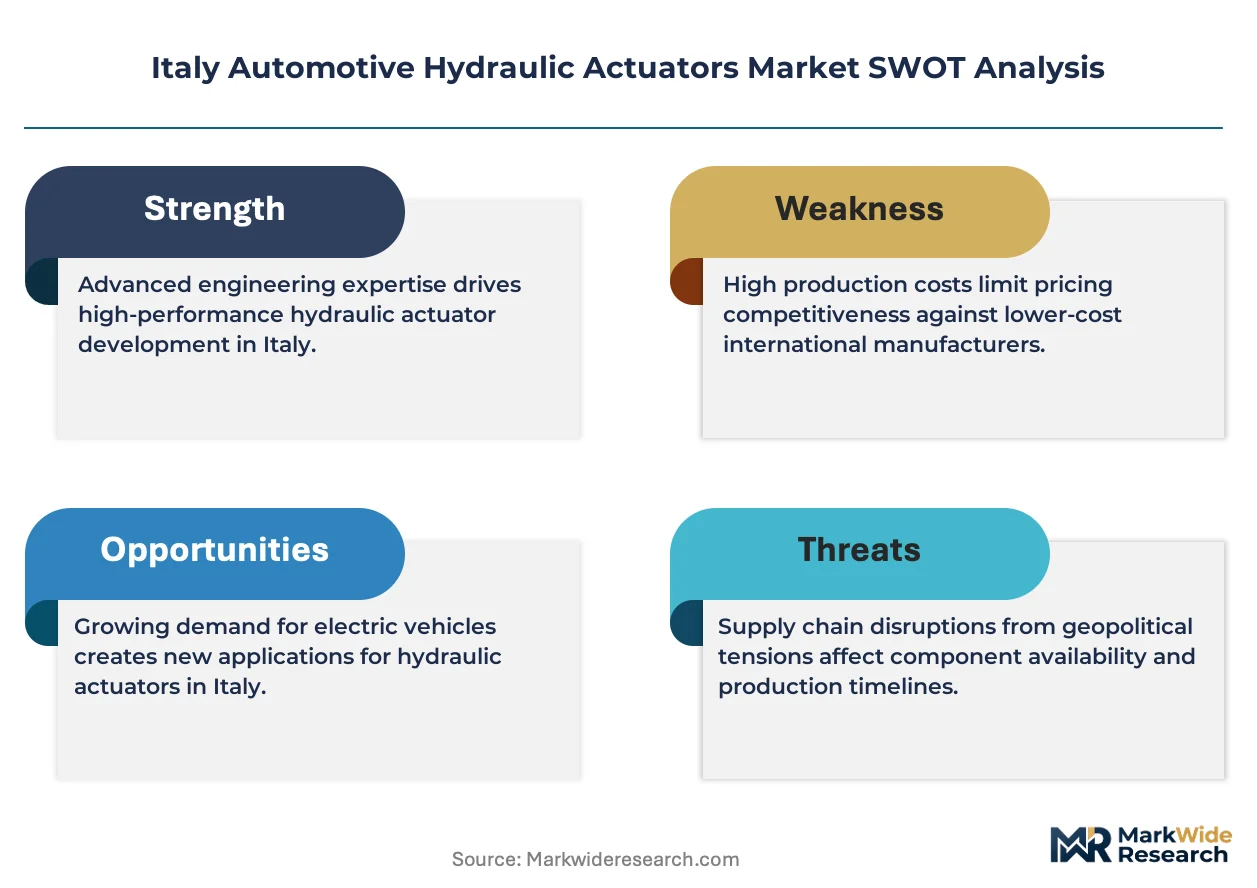
ISO 26262 functional safety certification is reorganizing the competitive landscape for hydraulic actuator suppliers serving Italian automakers. Robert Bosch GmbH leverages its embedded electronics heritage to integrate safety-compliant valve control modules. Continental AG sustains long-standing supply relationships with Turin-based OEM assembly plants through localized production footprints. BorgWarner Inc specializes in transmission actuation architectures that meet the stringent fault-tolerance thresholds now mandatory for platform approval.
Automotive hydraulic actuators are fluid-powered mechanical devices that convert pressurized oil flow into linear or rotary motion, typically operating at system pressures between 100 and 350 bar to manage clutch engagement, brake force distribution, and suspension damping in vehicles. Their primary commercial purpose is to deliver high force density and rapid response in powertrain and chassis systems where electromagnetic alternatives prove inadequate. Linear actuators dominate the product mix due to their ubiquity in brake and clutch applications, while electric-hydraulic actuators represent the fastest-growing category as electrified architectures demand seamless blending of hydraulic force with electronic modulation. OEMs capture the largest end-user value pool, though aftermarket providers are gaining structural importance as extended vehicle lifespans in Italy drive replacement demand for wearable actuator seals and cylinders.
EU type-approval frameworks administered by the European Commission, supplemented by Italy's Ministry of Infrastructure and Transport (MIT) homologation requirements, mandate electromagnetic compatibility and environmental durability testing for all chassis-integrated actuators. The EU Green Deal's embedded carbon reporting obligations, enforced through the Carbon Border Adjustment Mechanism, are pressuring suppliers to document lifecycle emissions from aluminum and steel forging processes. Stakeholders must monitor how Euro 7 brake particle emission limits reshape hydraulic brake actuator specifications and determine whether piezoelectric precision control warrants premium positioning against conventional solenoid architectures.
Market Dynamics
Brake-by-wire migration and Euro 7 emission readiness are compressing supplier qualification timelines across Italian OEM assembly networks. Tier-one hydraulic actuator manufacturers must now embed ISO 26262 functional safety modules into valve control architectures before securing platform approval from Stellantis and Ferrari engineering teams.
Growth Catalysts
- Emission Compliance Mandates:Euro 7 brake particle emission limits are forcing OEMs to upgrade hydraulic brake actuator precision control. Tier suppliers embedding piezoelectric modulation modules capture expanded specification scope.
- Electrification Architecture Demand:Hybrid and battery-electric powertrains require electric-hydraulic actuators for seamless torque blending. Northern Italian manufacturing clusters in Turin and Emilia-Romagna anchor this demand concentration.
- Extended Vehicle Lifecycles:Italian passenger vehicle fleet aging is accelerating aftermarket replacement cycles for wearable actuator seals and cylinders. Independent service providers are building dedicated hydraulic component distribution networks.
Market Restraints
- Aluminum and Steel Input Volatility:Forged cylinder bodies and valve housings depend on primary aluminum and specialty steel grades. Carbon Border Adjustment Mechanism reporting obligations add compliance cost layers without direct price recovery mechanisms.
- Supplier Concentration Risk:High-pressure hydraulic component forging capacity concentrates among a limited set of European tier-two suppliers. Disruption at any single forging facility cascades through Italian OEM just-in-sequence assembly schedules.
- Electromechanical Substitution Threat:Pure electromechanical brake actuators are advancing through ISO 26262 certification pathways. Long-term platform architecture decisions may marginalize hydraulic solutions in entry-segment vehicle categories.
Strategic Opportunities
- Carbon Footprint Documentation Services:EU Green Deal embedded carbon reporting creates white space for suppliers offering lifecycle emissions verification for aluminum forging processes. Early movers capture premium positioning in OEM sustainability scorecards.
- Remanufacturing Channel Development:Circular economy frameworks are legitimizing remanufactured hydraulic actuators for aftermarket replacement. Italian independent distributors are establishing certified remanufacturing partnerships with core suppliers.
- Suspension Actuator Electrification:Active chassis control systems are converging hydraulic damping with electronic valve modulation. Tier suppliers integrating sensor feedback loops into hydraulic architectures access expanding specification scope in premium vehicle segments.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:ISO 26262 ASIL-D certification requirements demand specialized embedded software and systems engineering capabilities. Italian automotive engineering programs are not producing sufficient safety-certified graduates to match supplier hiring needs.
- Legacy Platform Integration Complexity:Brake-by-wire migration requires hydraulic actuator suppliers to maintain dual-architecture production capability. Parallel manufacturing of conventional and electronically integrated actuators strains capital allocation and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Hydraulic Actuators Market |
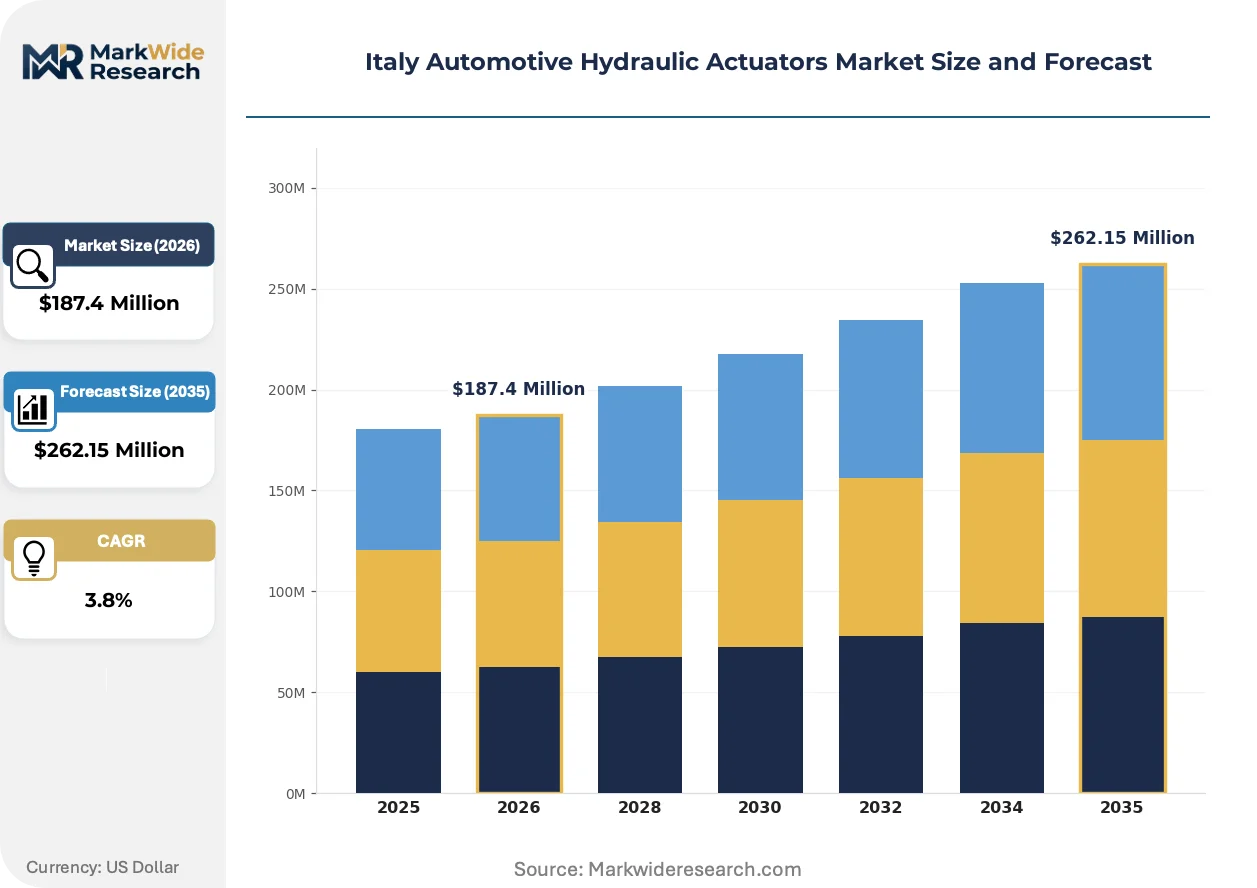
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Electric-Hydraulic Actuators, Pneumatic Actuators End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: On-Road Vehicles, Off-Road Vehicles, Commercial Vehicles, Specialty Vehicles Technology: Hydraulic Technology, Electronic Control, Piezoelectric Technology, Variable Displacement Technology |
| Companies Covered | Wabco Holdings Inc., BorgWarner Inc, Continental AG, Johnson Electric, Denso Corporation, Robert Bosch GmbH, Sonceboz SA, CTS Corporation, Hella KGaA Hueck & Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Hydraulic Actuators Market Shifts & Advancements
Electrification of chassis and powertrain systems is dissolving traditional boundaries between hydraulic force generation and electronic control. Italian OEMs now specify actuators as integrated mechatronic modules rather than discrete hydraulic components.
Piezoelectric valve control is fragmenting the precision actuation landscape. These ceramic-based positioning elements enable microsecond-level flow modulation for brake force distribution. Stellantis and Ferrari engineering teams are qualifying piezoelectric architectures for next-generation platform releases. The technology is fragmenting supplier tier structures by forcing electronics specialists into hydraulic component supply chains.
EU Green Deal carbon reporting obligations are reshaping supplier documentation requirements. The European Commission's Carbon Border Adjustment Mechanism mandates embedded emissions disclosure for aluminum and steel inputs. Hydraulic actuator manufacturers serving Italian OEMs are deploying blockchain-tracked supply chain auditing to satisfy homologation prerequisites. Component suppliers with verified low-carbon forging partnerships are securing preferential qualification status.
Aftermarket procurement is consolidating around certified remanufacturing networks. Italian independent distributors are displacing traditional spare parts wholesalers with remanufactured actuator offerings carrying OEM-equivalent warranty terms. Fleet operators and leasing companies in Lombardy and Veneto are adopting remanufactured components to meet corporate sustainability targets. This channel shift is compressing margins for conventional new-part distribution while opening service revenue pools for technical refurbishment providers.
Italy Automotive Hydraulic Actuators Market Segmentation
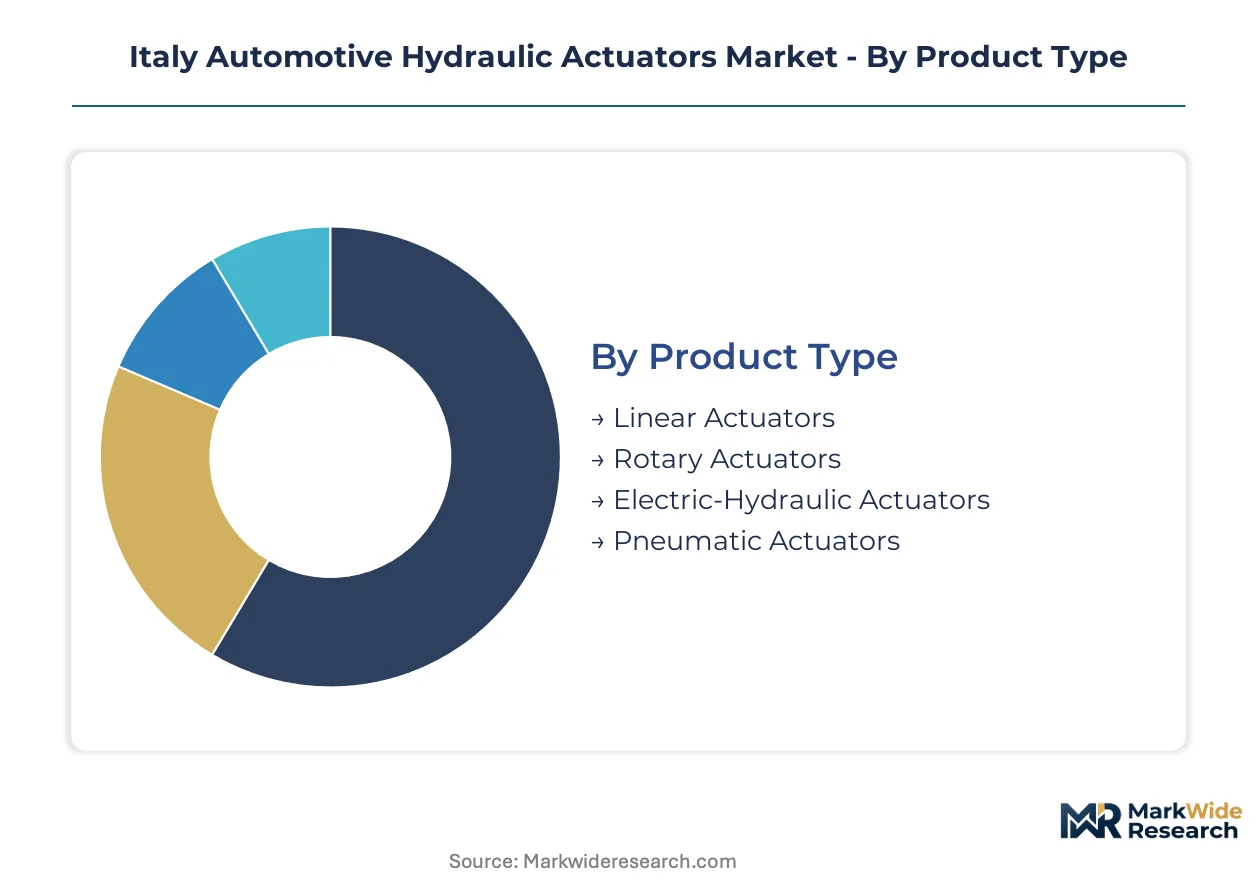
Segmentation reveals how hydraulic actuator demand fragments across procurement channels in Italy's automotive manufacturing ecosystem. Product architecture and end-user concentration determine which suppliers capture value in brake-by-wire and transmission actuation applications.
Product Type:
Channel distribution varies sharply by actuator mechanism, with OEM direct procurement favoring integrated electronic-hydraulic units while aftermarket channels handle simpler linear replacements.
- Linear Actuators:Cylindrical piston mechanisms convert pressurized fluid into straight-line motion for clutch and brake caliper applications. Turin-based Stellantis assembly plants specify these for high-volume platform lines where proven reliability outweighs electronic complexity. Brake-by-wire migration is forcing upgrades to sensor-integrated variants.
- Electric-Hydraulic Actuators:Hybrid architectures blend hydraulic force density with electronic valve modulation for seamless torque blending in electrified powertrains. Emilia-Romagna's Ferrari engineering teams specify these for active chassis control where millisecond response matters. Hybrid and battery-electric architectures are accelerating qualification timelines.
- Rotary Actuators:Vane and gear mechanisms deliver torque output for transmission selector and steering assist applications.
- Pneumatic Actuators:Compressed air systems serve niche commercial vehicle auxiliary functions where hydraulic infrastructure is absent.
By volume, Linear Actuators leads. By growth pace, Electric-Hydraulic Actuators is climbing the fastest.
End User:
Cost tiers separate integrated module procurement from component supply, with safety-certified systems commanding premium positioning against standard hydraulic replacements.
- OEMs:Vehicle manufacturers in Turin and Maranello specify complete actuator modules with embedded ISO 26262 functional safety compliance. Direct procurement contracts lock in multi-year supply agreements with forged component traceability requirements.
- Tier-1 Suppliers:Bosch and Continental integrate hydraulic actuators into brake and transmission subsystems before delivering to assembly plants. These suppliers bear homologation responsibility for electromagnetic compatibility and environmental durability testing.
- Aftermarket Providers:Independent distributors in Lombardy and Veneto supply replacement seals and cylinders for Italy's aging passenger vehicle fleet.
- Vehicle Assemblers:Contract manufacturers performing final assembly operations procure pre-validated actuator assemblies from approved supplier lists.
OEMs dominate value capture. Aftermarket Providers are gaining structural importance as fleet aging accelerates replacement cycles.
Installation:
Application context determines pressure rating specifications and environmental sealing requirements across Italy's vehicle production mix.
- On-Road Vehicles:Passenger cars and light commercial vehicles subject to Euro 7 brake particle emission limits. Hydraulic brake actuators in this segment require piezoelectric precision control modules to meet tightening regulatory thresholds.
- Commercial Vehicles:Heavy-duty trucks and buses operating at higher system pressures demand reinforced cylinder bodies and enhanced thermal management.
- Off-Road Vehicles:Agricultural and construction equipment exposed to contamination and vibration extremes.
- Specialty Vehicles:Racing and limited-production applications with custom hydraulic architectures.
On-Road Vehicles generates the highest unit volumes. Commercial Vehicles shows the steepest specification upgrade trajectory as emission compliance tightens.
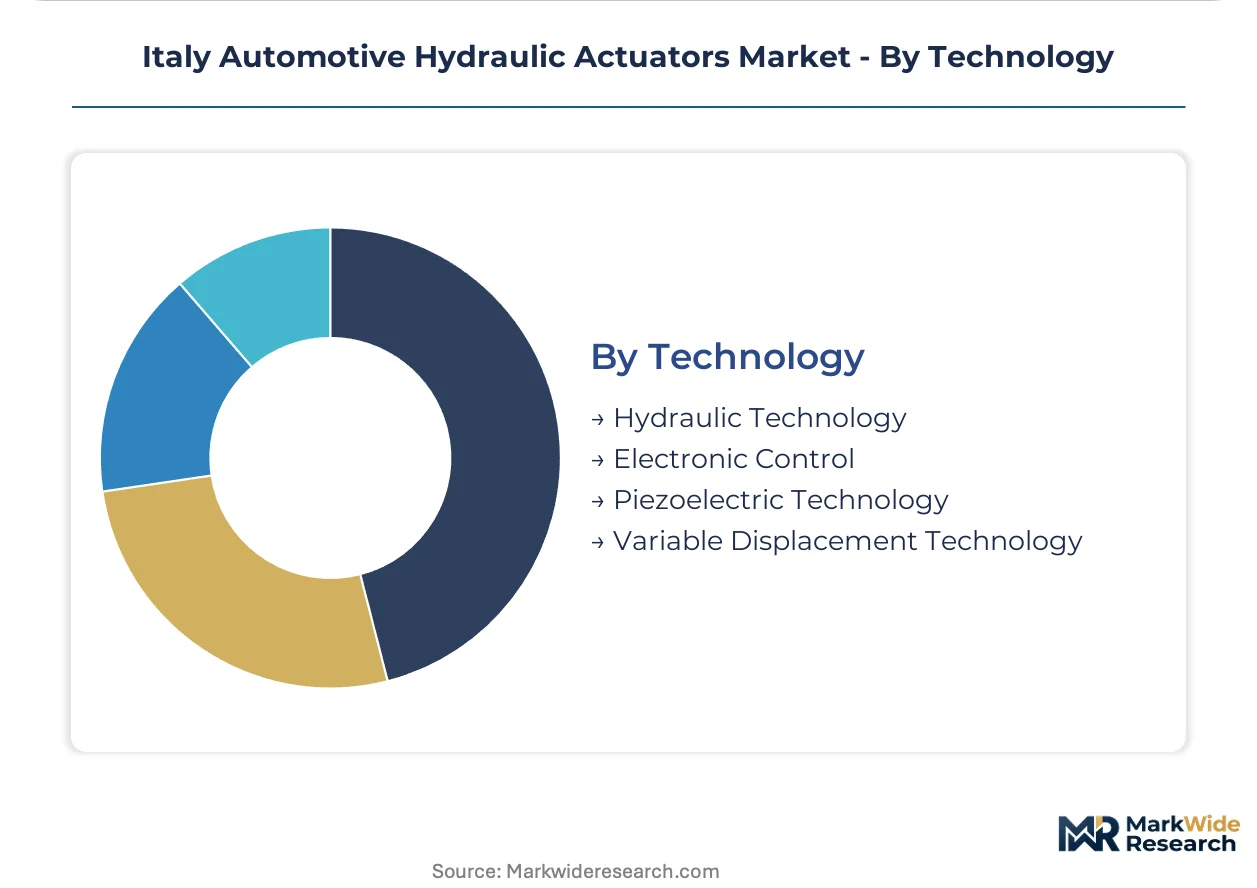
Technology:
Supply concentration in forging and electronics capabilities is fragmenting the supplier landscape as mechatronic integration demands expand.
- Hydraulic Technology:Conventional fluid power systems with mechanical valve control dominate legacy platform production. Northern Italian manufacturing clusters maintain substantial installed base of forging capacity for cylinder bodies.
- Electronic Control:Embedded sensor and processor modules enable real-time flow modulation for brake-by-wire architectures. Stellantis engineering specifications now mandate ASIL-D safety certification for these integrated systems.
- Piezoelectric Technology:Ceramic-based positioning elements deliver microsecond-level precision for brake force distribution.
- Variable Displacement Technology:Adaptive pump and motor configurations optimize energy efficiency in hybrid powertrains.
Hydraulic Technology retains volume leadership. Electronic Control is expanding most quickly as platform architectures electrify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal embedded carbon reporting obligations are reshaping supplier qualification requirements across Italian automotive manufacturing clusters. The European Commission's Carbon Border Adjustment Mechanism mandates lifecycle emissions documentation for aluminum and steel forging inputs. Regional demand concentrates in northern industrial corridors where Stellantis and Ferrari anchor vehicle assembly ecosystems.
Piedmont
Turin-based Stellantis assembly plants drive brake-by-wire actuator demand for high-volume platform lines. Italy's Ministry of Infrastructure and Transport enforces homologation requirements for electromagnetic compatibility testing. The Turin metropolitan corridor hosts concentrated forging capacity for hydraulic cylinder bodies serving OEM direct procurement contracts.
Emilia-Romagna
Ferrari engineering teams in Maranello specify electric-hydraulic actuators for active chassis control systems. Euro 7 brake particle emission limits are accelerating piezoelectric valve control qualification timelines. The Modena-Reggio Emilia automotive belt anchors premium vehicle actuator development with embedded ISO 26262 functional safety modules.
Lombardy
Milan-centered aftermarket distribution networks supply replacement seals for Italy's aging passenger vehicle fleet. The EU Green Deal circular economy frameworks legitimize remanufactured hydraulic components carrying OEM-equivalent warranty terms. Independent service providers in Brescia and Bergamo provinces are building certified remanufacturing partnerships with core suppliers.
Veneto
Vicenza and Verona provinces host specialized hydraulic component distributors serving commercial vehicle operators. Extended vehicle lifecycles in northern Italian fleet markets accelerate replacement cycles for wearable actuator cylinders. Regional distributors are displacing traditional spare parts wholesalers with sustainability-certified remanufactured offerings.
Italy Automotive Hydraulic Actuators Market Competitive Landscape
Player mix skews toward diversified automotive systems conglomerates with embedded electronics capabilities. The supplier base concentrates among tier-one integrators capable of delivering ISO 26262-certified mechatronic modules rather than discrete hydraulic component fabricators. Three strategic archetypes dominate: electronics-integrated systems specialists, forged component manufacturers with safety certification pathways, and aftermarket remanufacturing operators. Competitive dynamics center on vertical integration into valve control electronics and geographic proximity to Turin-Emilia assembly corridors.
Within the diversified systems tier, Continental AG and Robert Bosch GmbH represent archetypal positions combining hydraulic component heritage with embedded safety electronics. BorgWarner Inc exemplifies the transmission actuation specialization vector. These entities anchor supplier qualification frameworks that Stellantis and Ferrari engineering teams mandate for platform approval, occupying positions where functional safety certification and carbon footprint documentation converge as non-negotiable entry requirements.
| Leading Market Players |
|---|
| Wabco Holdings Inc. |
| BorgWarner Inc |
| Continental AG |
| Johnson Electric |
| Denso Corporation |
| Robert Bosch GmbH |
| Sonceboz SA |
| CTS Corporation |
| Hella KGaA Hueck & Co. |
| Others |
Supply & Pricing Matrix
Forging capacity utilization rates above eighty-five percent across northern Italian tier-two suppliers create pricing power asymmetries between integrated mechatronic module producers and discrete hydraulic component fabricators. This scale concentration elevates price floors for ISO 26262-certified actuator assemblies while compressing margins for standard linear replacements lacking embedded electronics.
Pricing Analysis
Certification level creates the primary spread between ASIL-D safety-compliant electric-hydraulic modules and conventional mechanical valve actuators. Three-tier pricing structure separates premium mechatronic units with piezoelectric control from standard solenoid architectures and economy-grade aftermarket seals. Cost compression in entry-segment brake actuators is intensifying because pure electromechanical substitutes advance through homologation pathways. Tier-1 suppliers exhibit lowest price sensitivity due to locked multi-year OEM contracts, while independent aftermarket distributors face acute margin pressure from remanufactured alternatives.
Supply Chain Analysis
Germany and China anchor high-pressure hydraulic component forging capacity serving Italian OEM assembly networks. Cylinder bodies and valve housings draw from primary aluminum smelters and specialty steel mills subject to EU Carbon Border Adjustment Mechanism disclosure requirements. Single-source vulnerability concentrates at European forging facilities qualified for Stellantis platform approval. Distribution runs through just-in-sequence logistics corridors linking Turin and Emilia-Romagna assembly plants with tier-one integrator warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brake-by-wire migration fragments supplier tier structures by forcing electronics specialists into hydraulic component supply chains, creating acquisition and partnership niches for players with cross-domain capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into piezoelectric valve control electronics and captive forging partnerships in Piedmont. Electromechanical brake actuator certification by Continental and Bosch threatens long-term platform share for pure hydraulic suppliers. Prioritize ASIL-D safety module development to maintain OEM direct procurement status. For New Entrants and Emerging Players: ISO 26262 certification fast-tracks for aftermarket remanufacturing networks offer the most penetrable entry vector. Target Lombardy and Veneto independent distributors seeking sustainability-certified hydraulic component suppliers. Lead with blockchain-tracked carbon footprint documentation to differentiate against incumbent forging networks. For Investors and Strategic Acquirers: Forged component manufacturers with safety certification pathways represent the highest-conviction acquisition archetype. Long-term viability hinges on electrification architecture convergence rather than legacy hydraulic volume. Watch piezoelectric valve control qualification timelines at Stellantis and Ferrari as inflection indicators for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectronics | Captures valve control margin pools as Stellantis mandates microsecond-level brake modulation. |
| Carbon Border Adjustment Compliance Program | Secures preferential qualification status under EU Green Deal embedded emissions frameworks. |
| Remanufacturing Channel Partnership | Accesses circular economy revenue pools as Lombardy fleet operators adopt sustainability-certified components. |
| ASIL-D Safety Certification Investment | Unblocks platform approval pathways for brake-by-wire architectures at Turin assembly plants. |
| Just-in-Sequence Logistics Footprint | Reduces inventory carrying costs across Emilia-Romagna premium vehicle production clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, and EU regulatory filings. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads informed demand-side assumptions. Customs records and MIT homologation documentation provided supply-side validation. Bottom-up actuator volume estimates triangulated against top-down automotive production forecasts.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the projection horizon. CAGRs derived from regression analysis of historical platform adoption curves and electrification roadmap disclosures. Forecast inputs incorporate Euro 7 brake particle emission limit implementation schedules and piezoelectric valve control qualification timelines.
Underlying assumptions cover emission compliance trajectory, forging capacity expansion rates, and electromechanical substitution velocity, with deviation risk concentrated in regulatory delay or accelerated brake-by-wire platform decisions. Recalibration cycles align with material shifts in EU Green Deal carbon reporting enforcement and OEM platform architecture announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Electric Drivetrain Components Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
Steel Cords for Radial Tyres Market