
 Splined Sleeves Market | 2026-2036
Splined Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Splined Sleeves Market Analytics
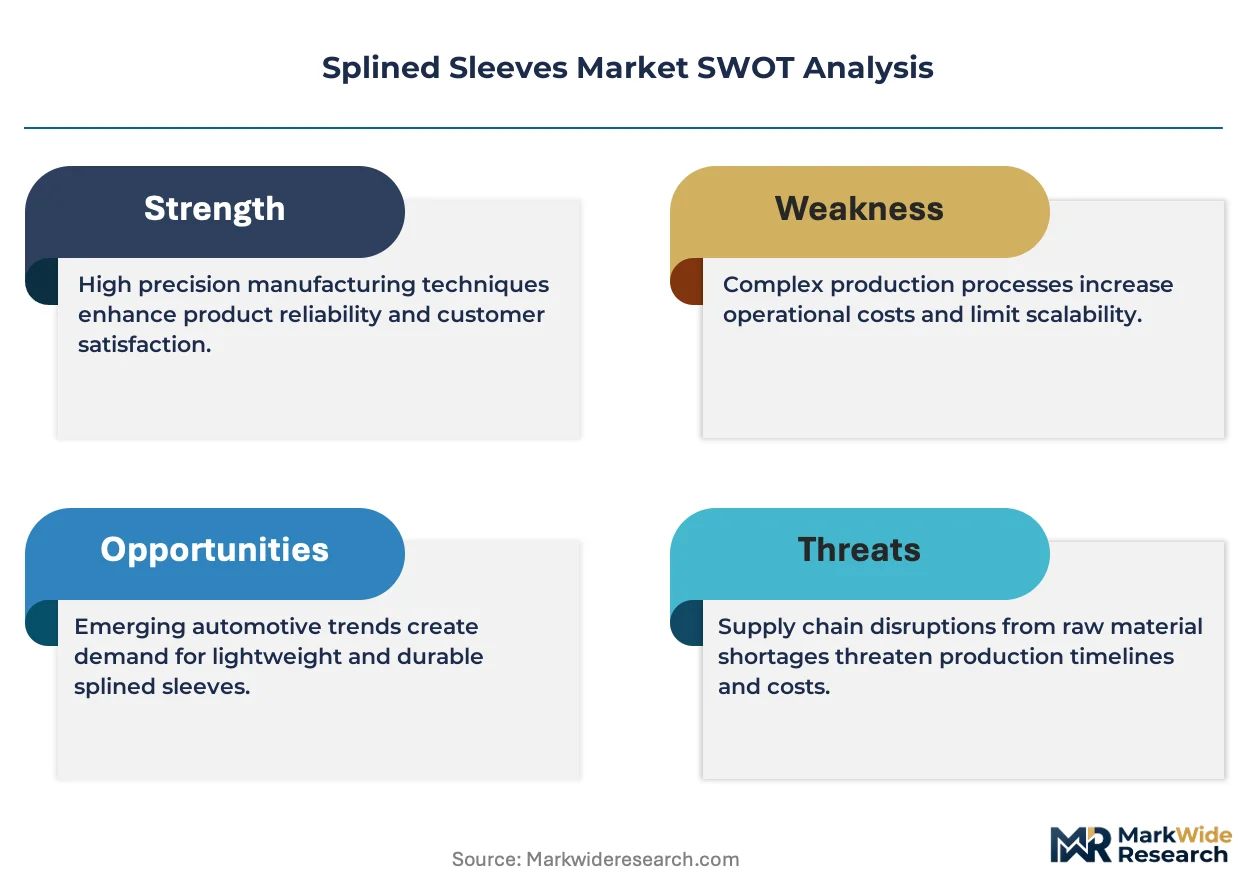
Preventive maintenance contracts and software-enabled torque monitoring is restructuring how splined sleeve suppliers capture lifetime value from industrial customers. NTN Corporation leverages its bearing technology heritage to dominate precision sleeve supply for robotics OEMs in East Asia. Grob Inc. anchors North American demand through its cold-forming expertise in automotive drivetrain components. MISUMI competes on catalog breadth and same-day fulfillment velocity for maintenance procurement across Japanese factory networks.
Splined sleeves are cylindrical mechanical couplings with axial grooves machined along their inner or outer diameter surfaces, typically produced through hobbing, broaching, or cold-forming processes to achieve precise tooth geometry for torque transmission. Internal splined sleeves command premium positioning in aerospace actuator systems where concentricity tolerances below five micrometers prevent backlash failure. Steel formulations sustain the largest material share due to fatigue resistance requirements in heavy industrial machinery, while aluminum variants gain traction in robotics where payload reduction directly improves cycle speed. The automotive application segment carries concentrated margin pools as EV platform standardization drives multi-year supply agreements.
ISO 9001 quality management and IATF 16949 automotive sector standards govern supplier qualification across major procurement channels, with REACH substance restrictions in Europe and EPA reporting obligations in the United States adding compliance layers to material sourcing decisions. Japan's METI circular economy guidelines increasingly influence design-for-disassembly requirements in precision mechanical components. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading impact on steel procurement economics.
Market Dynamics
Automotive powertrain electrification is consolidating procurement around precision splined sleeves as EV platforms standardize drivetrain architectures, forcing suppliers to reconfigure capacity for high-volume, tight-tolerance production runs.
Growth Catalysts
- REACH material traceability mandates:European suppliers are certifying low-carbon steel grades to maintain access to Germany's automotive supplier corridor around Stuttgart and Wolfsburg.
- Electric drivetrain assemblies:Powertrain manufacturers are expanding procurement of precision splined sleeves for torque transmission in battery-electric vehicle platforms.
- Cold-forming process advancement:Near-net-shape manufacturing is reducing material waste in high-volume automotive sleeve production.
Market Restraints
- Specialized alloy cost volatility:Nickel and molybdenum price swings in specialty steel formulations compress margin predictability for precision component suppliers.
- Supplier concentration in East Asia:Bearing heritage manufacturers dominate robotics-grade sleeve supply, creating single-source vulnerability for Western OEMs.
- Broaching equipment lead times:Extended delivery cycles for precision hobbing machinery constrain capacity expansion timelines.
Strategic Opportunities
- EU Green Deal carbon border adjustments:Certified low-carbon steel sourcing creates qualification barriers that favor early-adopter suppliers with verified supply chains.
- Robotics payload optimization:Aluminum spline variants are penetrating collaborative robot joint assemblies where cycle speed improvements justify material switching costs.
- Preventive maintenance digitization:Torque monitoring software integration enables lifetime value capture through predictive replacement contracts.
Industry Challenges
- Concentricity tolerance capability:Aerospace actuator specifications below five micrometers require capital-intensive metrology infrastructure that smaller suppliers struggle to fund.
- IATF 16949 certification timelines:Automotive sector quality management audits extend supplier qualification cycles, delaying revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Splined Sleeves Market |
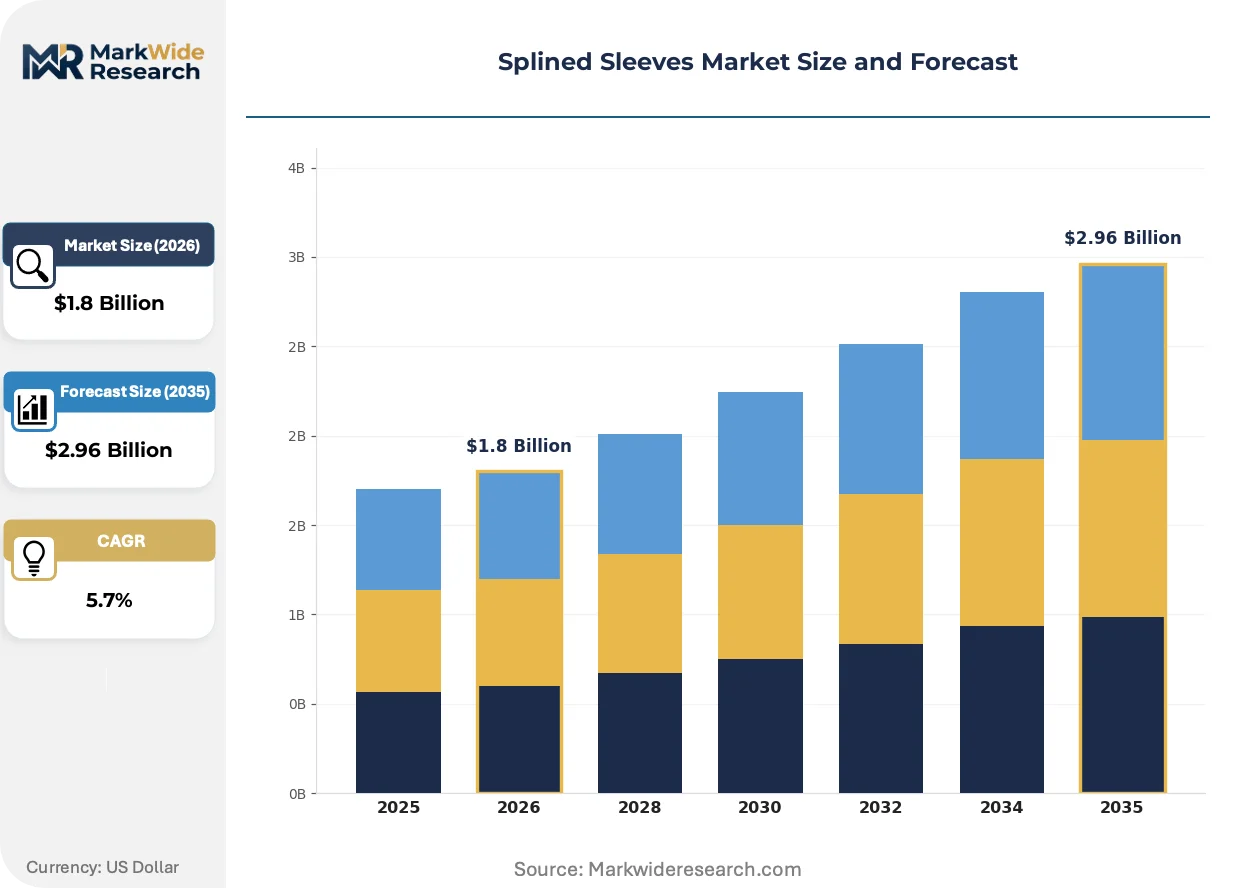
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Splined Sleeves, External Splined Sleeves, Keyed Sleeves, Custom Splined Sleeves Material: Steel, Aluminum, Plastic, Composite Application: Automotive, Aerospace, Industrial Machinery, Robotics End User: Manufacturers, Repair Shops, OEMs, DIY Enthusiasts |
| Companies Covered | NTN Corporation, Grob Inc., MISUMI, Weasler, THK Co., Ltd., Jerpbak-Bayless Company, AmTech OEM, Arrow Gear Co., Tracey Gear & Precision Shaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Splined Sleeves Market Evolving Landscape
Digital thread integration across manufacturing and maintenance operations is redefining how splined sleeve suppliers capture value beyond the initial component sale.
Additive manufacturing of near-net-shape preforms is electrifying traditional subtractive finishing workflows in precision spline production. Medical device and aerospace buyers are qualifying electron-beam-melted titanium blanks that reduce machining time by sixty percent on complex internal geometries. This convergence is compressing lead times for low-volume, high-mix orders that previously required extensive setup.
Japan's METI circular economy guidelines are mandating design-for-disassembly in precision mechanical components sold into domestic factory automation networks. Manufacturers must now document material composition and end-of-life recyclability to maintain preferred supplier status with major electronics assemblers. Component suppliers are responding by standardizing sleeve geometries that accommodate automated sorting and remelting.
Automotive buyers are consolidating supplier panels around multi-year platform agreements that bundle design engineering with volume production commitments. Tier-one drivetrain integrators are displacing spot-market purchasing with captive sourcing arrangements that lock in capacity and pricing. This concentration is most visible in Germany's supplier corridor, where Wolfsburg-based procurement teams are reducing qualified vendor lists from twelve to three per component family.
Splined Sleeves Market Segmentation
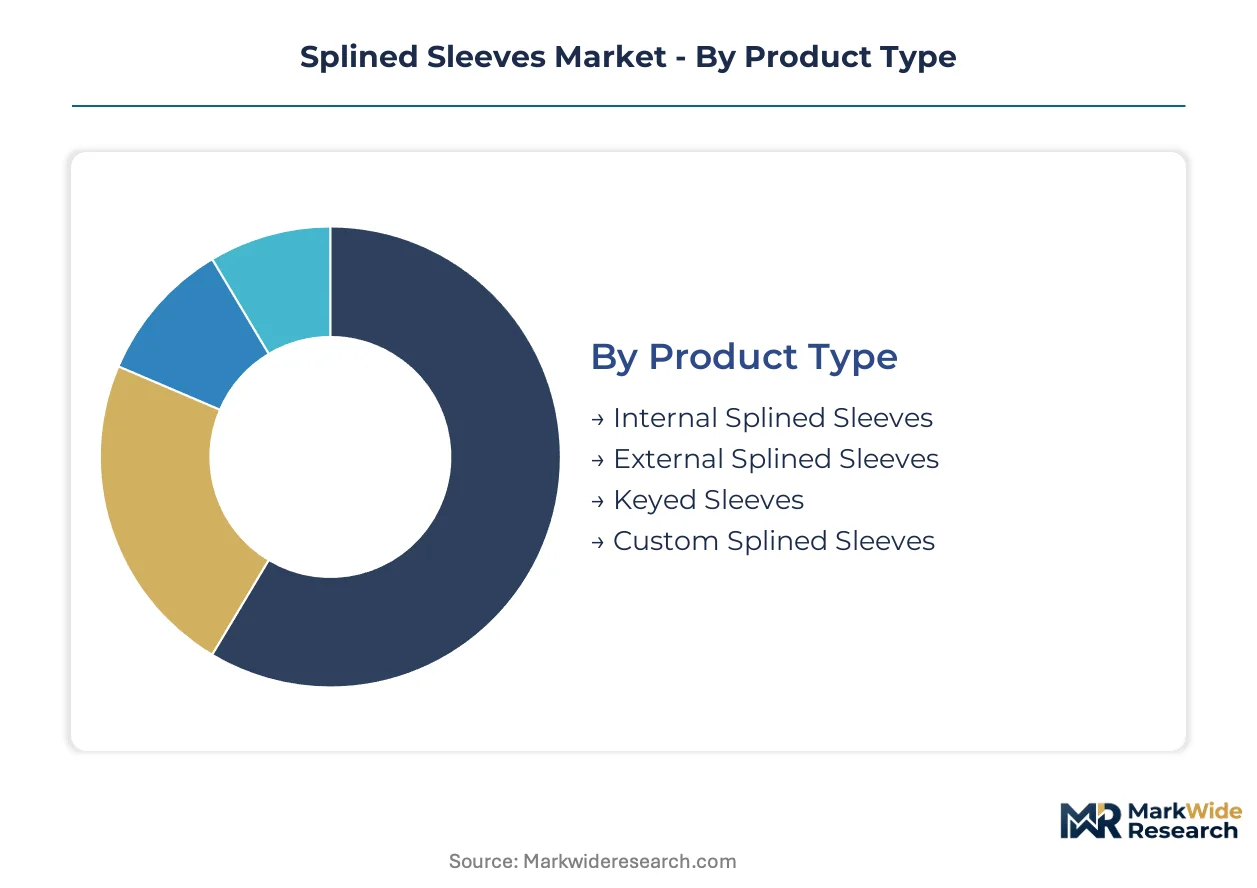
Splined sleeve procurement decisions pivot on torque load requirements, environmental exposure, and lifecycle cost calculations. Segmentation reveals how specification granularity determines supplier qualification barriers and margin capture potential across mechanical power transmission applications.
Product Type:
Buyers select sleeve geometry based on assembly space constraints and backlash tolerance thresholds in the final drivetrain or actuator configuration.
- Internal Splined Sleeves:These components feature axial grooves machined along inner diameters to mate with external shaft profiles. Aerospace actuator systems in Germany's Stuttgart corridor specify concentricity below five micrometers to prevent backlash failure in flight control mechanisms. REACH-certified suppliers command premium positioning here.
- External Splined Sleeves:Grooves formed on outer surfaces engage internal hubs or couplings. Automotive powertrain manufacturers around Wolfsburg consolidate procurement of these variants for standardized EV drivetrain architectures requiring high-volume, tight-tolerance production runs.
- Keyed Sleeves:Simplified axial slot designs transmit torque through single-key engagement rather than full circumferential splining.
- Custom Splined Sleeves:Application-specific geometries address non-standard shaft configurations or legacy equipment retrofit requirements.
Volume sits with External Splined Sleeves; growth tilts toward Internal Splined Sleeves.
Material:
Material selection traces directly to fatigue resistance requirements versus weight reduction priorities in the target machinery category.
- Steel:Alloy and carbon steel formulations dominate heavy industrial machinery applications where cyclic loading demands superior fatigue resistance. European suppliers are certifying low-carbon grades under EU Green Deal frameworks to maintain access to Germany's automotive supplier corridor.
- Aluminum:Lightweight variants penetrate robotics joint assemblies where payload reduction improves cycle speed. Collaborative robot OEMs in Japan's factory automation networks specify these for rotational inertia optimization.
- Plastic:Polymer formulations serve corrosive environments and electrical isolation requirements in select industrial settings.
- Composite:Fiber-reinforced materials address extreme strength-to-weight ratios in aerospace secondary structures.
Steel captures current volume dominance; aluminum gains share fastest in robotics payload optimization.
Application:
End-use sector determines certification burden, volume predictability, and the balance between spot purchasing versus captive supply arrangements.
- Automotive:Powertrain electrification consolidates procurement around precision sleeves as EV platforms standardize drivetrain architectures. Tier-one integrators are displacing spot-market purchasing with multi-year platform agreements that bundle design engineering with volume commitments.
- Aerospace:Actuator systems demand concentricity tolerances below five micrometers, requiring capital-intensive metrology infrastructure that filters supplier participation. IATF 16949 and AS9100 certifications govern qualification timelines.
- Industrial Machinery:Preventive maintenance contracts and torque monitoring software integration enable lifetime value capture through predictive replacement scheduling.
- Robotics:Payload optimization drives aluminum spline adoption in collaborative robot joint assemblies where cycle speed improvements justify material switching costs.
Automotive anchors procurement volume; robotics represents the fastest-growing trajectory.
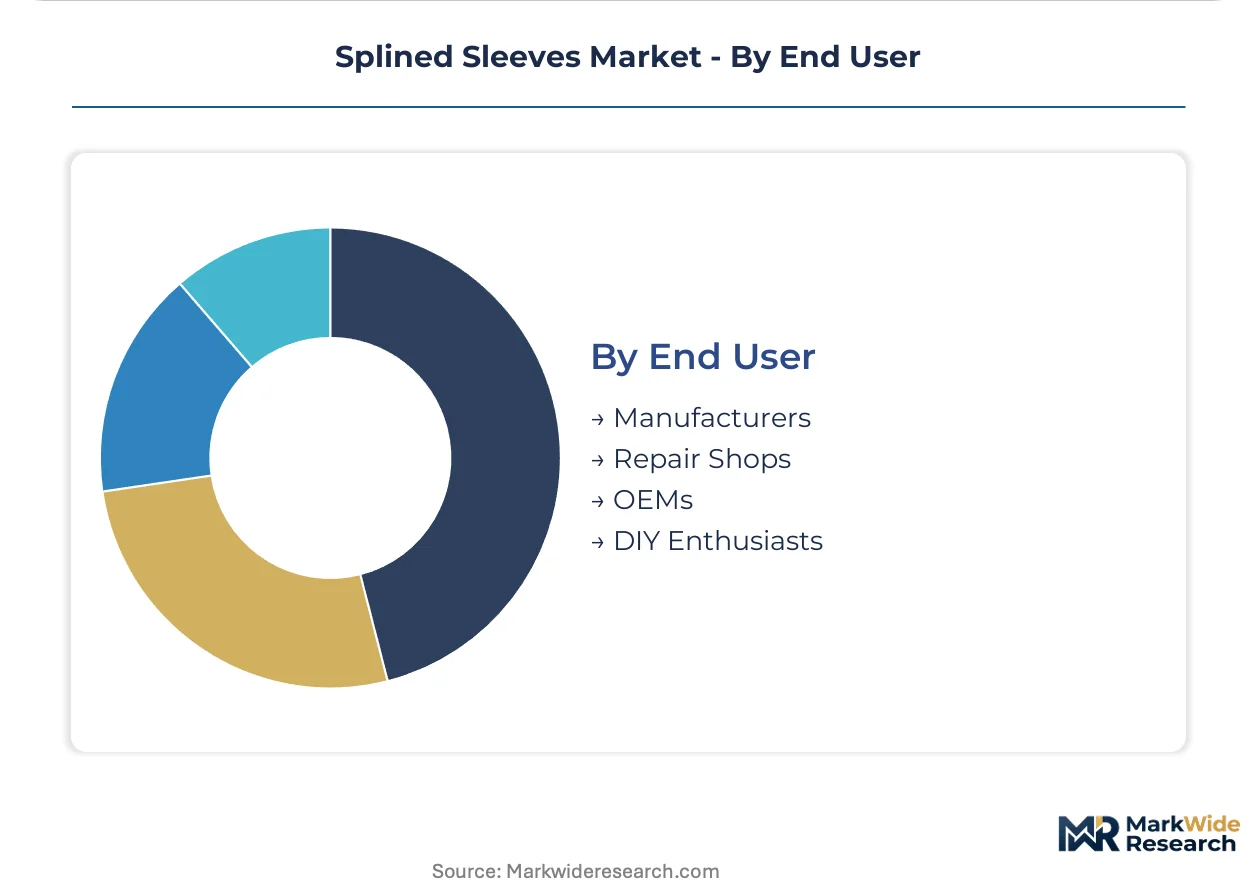
End User:
Customer type shapes fulfillment velocity requirements, technical support intensity, and the viability of catalog versus custom manufacturing business models.
- Manufacturers:Production-scale buyers negotiate multi-year supply agreements with design engineering bundled into platform partnerships. Germany's automotive supplier corridor exemplifies this concentration around Wolfsburg-based procurement teams.
- OEMs:Original equipment manufacturers qualify suppliers through extended IATF 16949 audit cycles, delaying revenue recognition for new market entrants but locking in capacity and pricing.
- Repair Shops:Maintenance procurement demands same-day fulfillment velocity and catalog breadth rather than custom engineering.
- DIY Enthusiasts:Small-volume purchasers access standardized geometries through distributor channels with minimal technical support requirements.
Manufacturers hold procurement volume concentration; OEMs drive specification evolution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asia and Germany, while consumption spreads across automotive manufacturing corridors in multiple continents. Steel procurement economics and carbon border regulations are redrawing supplier qualification maps faster than capacity can relocate.
Germany
Stuttgart and Wolfsburg anchor European demand for precision splined sleeves as EV platform standardization accelerates. REACH substance restrictions and EU Green Deal carbon border adjustments push suppliers toward certified low-carbon steel grades. The automotive supplier corridor around these cities is consolidating vendor panels from twelve to three per component family.
China
Domestic robotics OEMs and industrial machinery builders drive consumption of aluminum spline variants for payload optimization. MIIT dual carbon goals and GB standards for mechanical components tighten material traceability requirements. Yangtze River Delta manufacturing clusters are absorbing capacity expansions from cold-forming equipment investments.
United States
Automotive powertrain electrification and aerospace actuator demand split procurement between high-volume EV drivetrain sleeves and micrometer-tolerance flight control components. EPA reporting obligations add compliance layers to specialty alloy sourcing decisions. Midwest industrial corridors and Southern automotive assembly zones concentrate buyer activity.
Japan
Collaborative robot manufacturers in factory automation networks specify aluminum splines for rotational inertia optimization. METI circular economy guidelines mandate design-for-disassembly documentation to maintain preferred supplier status. Kanto and Kansai industrial basins host torque monitoring software integration pilots for predictive maintenance contracts.
South Korea
Automotive and robotics OEMs drive precision sleeve procurement as EV drivetrain localization accelerates. MFDS and national industrial standards govern quality certification for mechanical power transmission components. Seoul Capital Area and Busan-Ulsan manufacturing zones concentrate tier-one supplier relationships.
Splined Sleeves Market Competitive Landscape
Top-tier vendors anchor precision aerospace and automotive supply, while mid-tier fabricators compete on catalog breadth and fulfillment velocity. Bearing heritage manufacturers dominate robotics-grade sleeve supply in East Asia, creating single-source vulnerability for Western OEMs. Cold-forming specialists and broaching equipment operators represent distinct strategic archetypes. Competitive moves concentrate on multi-year platform agreements bundling design engineering with volume commitments, plus capacity expansion for high-volume tight-tolerance production runs.
Within the bearing-heritage tier, NTN Corporation exemplifies precision sleeve supply integration for robotics OEMs. Grob Inc. anchors North American positioning through its cold-forming expertise in automotive drivetrain components. MISUMI occupies a position defined by catalog breadth and same-day fulfillment velocity for maintenance procurement across Japanese factory networks.
| Leading Market Players |
|---|
| NTN Corporation |
| Grob Inc. |
| MISUMI |
| Weasler |
| THK Co., Ltd. |
| Jerpbak-Bayless Company |
| AmTech OEM |
| Arrow Gear Co. |
| Tracey Gear & Precision Shaft |
| Others |
Value Network & Pricing Analysis
Tier-one automotive procurement teams in Germany's Stuttgart-Wolfsburg corridor command pricing leverage through multi-year platform agreements that bundle design engineering with volume commitments, compressing spot-market premiums and favoring suppliers with captive capacity arrangements.
Pricing Analysis
Margin tightening in precision aerospace grades reflects capital-intensive metrology infrastructure requirements that filter supplier participation. Three-tier pricing structure across certified low-carbon steel, standard alloy formulations, and economy-grade alternatives segments buyer access. Cost-down pressure on external splined sleeves accelerates as EV drivetrain standardization consolidates procurement panels. Maintenance procurement through distributor channels exhibits highest price sensitivity; aerospace actuator specifications tolerate premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with East Asian bearing-heritage manufacturers dominating robotics-grade sleeve supply for Western OEMs. Production gravity centers on Germany, China, and Japan for precision cold-forming and broaching capacity. Specialty steel formulations draw from nickel and molybdenum supply chains exposed to commodity price volatility. Distribution runs through tier-one drivetrain integrators consolidating vendor panels from twelve to three per component family.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards upstream control over certified low-carbon steel sourcing and downstream integration into torque-monitoring software platforms as suppliers race to capture lifetime value beyond component sales.
For Market Incumbents: Deploy multi-year platform agreements bundling design engineering with volume commitments to lock in capacity before new entrants qualify under IATF 16949 timelines. Deepen backward integration into REACH-certified low-carbon steel grades to defend margin position against carbon border adjustment mechanisms. Cold-forming equipment operators should expand metrology infrastructure to capture aerospace actuator specifications below five micrometers. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Germany open a window for early-adopter suppliers with verified low-carbon supply chains to penetrate the automotive supplier corridor. Aluminum spline variants for collaborative robotics present the most penetrable white-space target given payload optimization trends. Pursue preventive maintenance digitization partnerships to establish torque monitoring software integration as a go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors cold-forming specialists with automotive heritage and broaching equipment operators possessing aerospace certification infrastructure. Long-term viability hinges on suppliers capturing recurring revenue through predictive replacement contracts rather than transactional component sales. Watch for consolidation signals as tier-one integrators reduce qualified vendor lists from twelve to three per component family.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Steel Sourcing | EU Green Deal carbon border adjustments favor suppliers with verified low-carbon supply chains in Germany. |
| Metrology Infrastructure Expansion | Five-micrometer concentricity capability filters supplier participation in aerospace actuator specifications. |
| Torque Monitoring Software Integration | Predictive replacement contracts enable lifetime value capture from industrial maintenance procurement. |
| Multi-Year Platform Agreement Structuring | EV drivetrain standardization consolidates procurement around bundled design engineering commitments. |
| Aluminum Spline Variant Development | Collaborative robot OEMs in Japan specify lightweight variants for rotational inertia optimization. |
Research Methodology
Multi-period observation of procurement panel consolidation patterns, certification timeline extensions, and carbon border adjustment implementation anchored the trend analysis, supplemented by interviews with tier-one drivetrain procurement managers, aerospace actuator engineering leads, cold-forming equipment operators, and maintenance contract specialists. Secondary validation drew from IATF 16949 audit disclosure patterns, REACH certification registries, EU Green Deal regulatory filings, and automotive production database trajectories. Bottom-up volume modeling and top-down value triangulation cross-checked segment-level outputs.
Input-output matrices mapped splined sleeve demand across product type, material grade, application sector, and end-user archetype dimensions throughout the forecast period. CAGRs derived from regression analysis against automotive electrification deployment curves, robotics installation trajectories, and industrial machinery maintenance cycle frequencies. Industry-specific forecast inputs included EV platform standardization roadmaps and METI circular economy guideline implementation schedules.
Caveats apply where nickel and molybdenum price volatility, extended broaching equipment lead times, or accelerated carbon border adjustment phase-ins could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline trajectories and procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Wind Shield Washer Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Automotive Brake Wheel Cylinder Market