
 Electronically Commutated Motors Market | 2026-2036
Electronically Commutated Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Electronically Commutated Motors Market Analysis
OEM-direct procurement channels for electronically commutated motors is fragmenting as smaller system integrators gain digital purchasing access alongside traditional distributor relationships. Nidec Corporation dominates high-volume brushless motor supply for HVAC compressors through captive manufacturing networks in Asia. Siemens AG leverages its automation portfolio to bundle EC motor solutions with industrial drive systems, creating stickier enterprise accounts. ABB Ltd. competes on energy efficiency certification depth, sustaining premium positioning across European retrofit markets.
Electronically commutated motors integrate permanent magnet rotors with electronic inverter drives to achieve variable-speed operation without mechanical commutation losses, typically delivering efficiency ratings above IE4 standards through precise torque control algorithms. The primary commercial purpose centers on reducing energy consumption in continuous-duty applications such as fans, pumps, and compressors where partial-load operation dominates runtime. Brushless motor types anchor the installed base across HVAC systems and home appliances, while permanent magnet configurations represent the fastest-expanding category as rare-earth magnet costs stabilize and sensorless control technology matures. Field oriented control technology commands the highest margin pool due to firmware complexity and calibration service attach rates, whereas proportional control occupies cost-sensitive appliance segments.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that effectively phase out single-speed induction motors in commercial equipment, directly expanding EC motor addressable markets. REACH compliance in Europe restricts certain insulation material chemistries, compelling manufacturers to reformulate stator winding systems and recertify product families. China's GB 18613 efficiency standard tiers and MIIT industrial energy conservation directives pressure domestic motor fleets toward premium efficiency classes. Stakeholders must monitor rare-earth supply chain concentration and regional efficiency standard convergence to anticipate which product architectures will carry cross-border certification advantages.
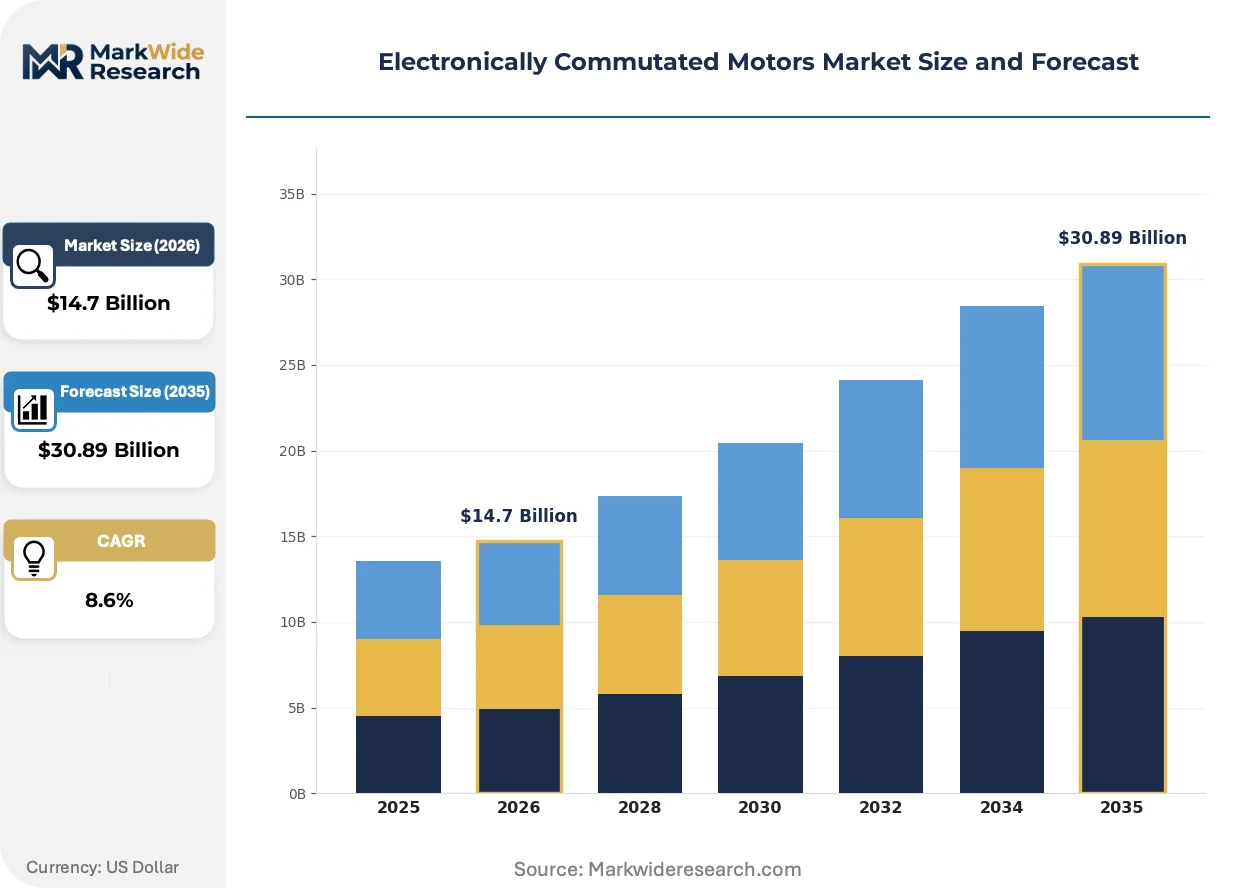
Market Dynamics
Permanent magnet rotor architectures and sensorless field-oriented control firmware are compressing cost differentials against induction motors, while efficiency mandates from Beijing to Brussels accelerate replacement timelines in continuous-duty equipment.
Growth Catalysts
- US DOE 10 CFR 431 standards:Minimum efficiency thresholds for commercial equipment phase out single-speed induction motors, directly expanding EC motor substitution opportunities in rooftop units and chilled water systems.
- China's MIIT industrial modernization directives:State-backed retrofit programs for motor fleets in steel, cement, and chemical plants generate concentrated volume demand for IE4-class permanent magnet units.
- Rare-earth magnet cost stabilization:Neodymium-iron-boron price normalization after supply chain volatility enables OEMs to specify permanent magnet configurations without hedging premiums.
Market Restraints
- Neodymium supply concentration:Rare-earth oxide refining capacity clusters in China's Inner Mongolia and Jiangxi provinces, creating single-source vulnerability for magnet-dependent motor architectures.
- REACH insulation reformulation costs:ECHA restrictions on specific winding varnish chemistries force manufacturers to redesign stator systems and recertify entire product families.
- Induction motor residual stock:Decades of installed base in commercial HVAC and pumping infrastructure delays replacement cycles even where payback periods justify upgrades.
Strategic Opportunities
- India's BIS efficiency labeling expansion:Mandatory star ratings for industrial motors create regulatory tailwind for EC technology penetration in a market historically dominated by low-cost induction units.
- Data center cooling retrofits:Hyperscale facilities in Northern Virginia and Frankfurt seek variable-speed fan arrays to optimize partial-load efficiency, opening premium specification channels.
- Sensorless control algorithm licensing:Firmware IP monetization through per-unit royalties offers recurring revenue streams beyond hardware margins.
Industry Challenges
- Power electronics integration complexity:Embedding inverter drives into motor housings requires thermal management and electromagnetic compatibility expertise that strains traditional motor manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and CCC approvals for new product families extend time-to-revenue by months.
- Legacy building automation protocol fragmentation:BACnet, Modbus, and proprietary HVAC control systems demand customized communication interfaces that complicate standard product strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronically Commutated Motors Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless, Synchronous, Asynchronous, Permanent Magnet Application: HVAC Systems, Automotive Drives, Industrial Automation, Home Appliances End User: Manufacturing, Healthcare, Aerospace, Electronics Technology: Sensorless Control, Proportional Control, Field Oriented Control, Direct Torque Control |
| Companies Covered | Regal Beloit Corporation, Delta Electronics, Inc., Nidec Corporation, Mitsubishi Electric Corporation, Siemens AG, ABB Ltd., Johnson Electric Holdings Limited, Bühler Motor GmbH, ebm-papst Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronically Commutated Motors Market Emerging Trajectories
Digital commissioning tools and AI-driven predictive maintenance are redefining how motor performance is validated and monetized across equipment lifecycles.
GaN-based inverter power stages are collapsing thermal management requirements and switching losses in compact EC motor drives. Data center cooling OEMs in Northern Virginia and Singapore specify these topologies for kilowatt-scale fan arrays. The technology is collapsing the physical envelope and cost floor for integrated motor-drive units.
REACH restrictions on halogenated flame retardants in stator insulation systems are compelling reformulation of winding varnishes and slot liners. European motor manufacturers face eighteen-month recertification cycles for existing product families. HVAC compressor suppliers serving the German market accelerate qualification of bio-based epoxy alternatives to maintain CE marking continuity.
Digital direct procurement platforms are fragmenting traditional distributor relationships in the EC motor channel. Smaller system integrators in Texas and Bavaria now access manufacturer pricing through self-service portals previously reserved for volume OEM accounts. This pattern concentrates in commercial building retrofit segments where project-scale procurement historically favored regional electrical distributors.
Electronically Commutated Motors Market Segmentation
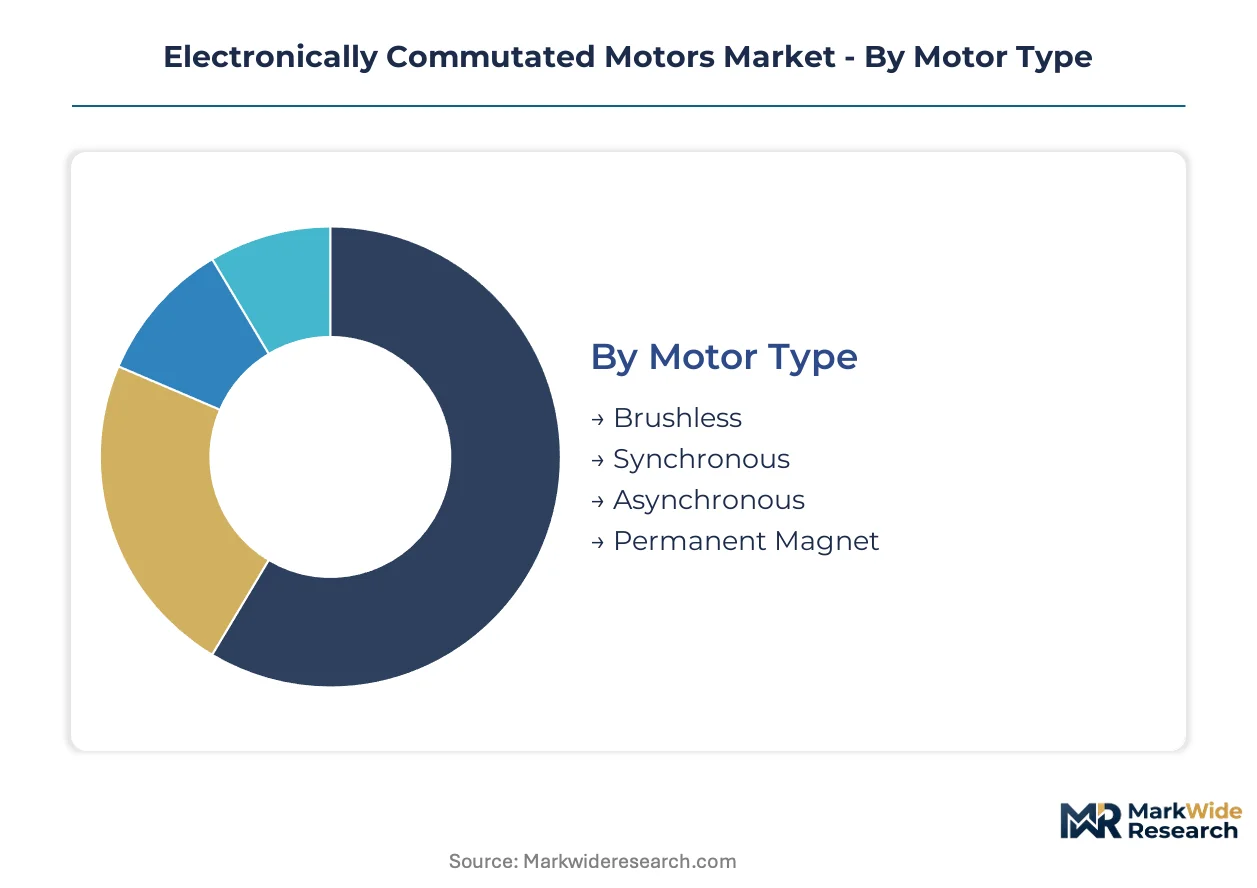
Segmentation in electronically commutated motors reveals how efficiency mandates and application-specific torque requirements reshape procurement patterns across equipment categories. Motor architecture choices cascade through system design decisions, from thermal management in HVAC compressors to precision positioning in factory automation.
Motor Type:
Cost tier differentiation separates legacy-compatible designs from premium permanent magnet architectures targeting efficiency-centric specifications.
- Brushless:Eliminates mechanical commutation through electronic switching of stator windings, achieving 15-20 percentage point efficiency gains over brushed equivalents. Demand concentrates in HVAC fan arrays and refrigeration compressors where continuous-duty runtime maximizes energy savings payback. US DOE 10 CFR 431 standards accelerate substitution timelines in commercial rooftop units.
- Permanent Magnet:Employs neodymium-iron-boron or ferrite rotors to generate magnetic flux without excitation losses, delivering IE4+ efficiency ratings in compact footprints. China's MIIT industrial modernization programs drive concentrated volume demand for steel mill and cement plant retrofits. Rare-earth magnet cost normalization removes hedging premiums from OEM specifications.
- Synchronous:Locks rotor speed to supply frequency through DC excitation or reluctance torque, serving grid-tied pumping infrastructure.
- Asynchronous:Relies on slip between rotating magnetic field and rotor for torque generation, persisting in cost-sensitive appliance segments.
Brushless holds installed capacity. Permanent magnet is rotating up the share rankings.
Application:
Application segmentation tracks where variable-speed operation delivers measurable energy reduction against fixed-speed legacy equipment.
- HVAC Systems:Variable-speed compressors and fan arrays modulate capacity to match thermal loads rather than cycling on-off, cutting energy consumption 30-50% in partial-load conditions. Demand concentrates in commercial building retrofits across Germany and the United States where Ecodesign and DOE standards mandate minimum efficiency thresholds. Chiller plants and rooftop units represent the highest-value specification channels.
- Industrial Automation:Precision torque control enables servo positioning and coordinated motion in packaging machinery and material handling systems. China's factory automation upgrade programs and Germany's Industrie 4.0 investments drive specification volume for field-oriented control architectures.
- Automotive Drives:Electric power steering and thermal management pumps specify compact EC motors for weight-sensitive underhood packaging.
- Home Appliances:Washing machine drums and refrigerator compressors adopt sensorless control to hit energy labeling thresholds at mass-market price points.
HVAC Systems dominates current revenue. Industrial Automation is gaining share fastest.
End User:
Customer type segmentation captures divergent procurement sophistication, from tender-driven manufacturing fleets to specification-engineered aerospace programs.
- Manufacturing:Steel, cement, and chemical plants operate motor fleets exceeding thousands of units, creating concentrated retrofit opportunities under China's MIIT energy conservation directives. Procurement evaluates total cost of ownership over 10-15 year horizons, favoring IE4-class permanent magnet units despite 40-60% first-cost premiums.
- Healthcare:Medical imaging equipment and HVAC isolation systems demand electromagnetic compatibility certification and vibration isolation that command 25-35% price premiums over industrial equivalents.
- Aerospace:Cabin pressurization and fuel pump applications specify MIL-STD qualified motors with extended temperature ranges.
- Electronics:Semiconductor fabrication tools require cleanroom-compatible motor housings and minimal particulate generation.
Manufacturing anchors volume demand. Healthcare is climbing the fastest.
Technology:
Control methodology segmentation determines firmware complexity, calibration service attach rates, and margin structure across the product hierarchy.
- Field Oriented Control:Decomposes stator current into torque and flux components through coordinate transformation, enabling precise dynamic response for servo applications. Demand concentrates in German automotive production lines and Japanese robotics installations where trajectory accuracy determines equipment value. Firmware licensing models generate recurring revenue streams beyond hardware margins.
- Sensorless Control:Estimates rotor position through back-EMF detection or observer algorithms, eliminating encoder cost and reliability concerns. China's home appliance manufacturers and India's BIS-labeled industrial motor programs drive volume adoption where cost compression outweighs precision requirements.
- Proportional Control:Simple voltage-frequency scaling serves cost-sensitive fan and pump applications with limited speed range requirements.
- Direct Torque Control:Switches inverter states based on flux and torque hysteresis bands, offering fast transient response for traction applications.
Field Oriented Control commands margin concentration. Sensorless Control is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Department of Energy efficiency mandates under 10 CFR 431 and China's MIIT industrial modernization directives are reshaping procurement patterns across major motor markets. Regulatory pressure is compressing replacement timelines for continuous-duty equipment.
United States
Commercial building retrofits and data center cooling expansions drive specification volume for variable-speed fan arrays. DOE 10 CFR 431 standards phase out single-speed induction motors in rooftop units and chilled water systems. Northern Virginia's hyperscale facility cluster demands premium EC motor configurations for partial-load optimization.
Germany
Industrie 4.0 investments and HVAC system upgrades anchor demand for field-oriented control architectures. Ecodesign requirements and REACH compliance restrict insulation chemistries, forcing stator winding reformulation. The Ruhr industrial corridor and Bavarian manufacturing belt concentrate retrofit activity for IE4-class permanent magnet units.
China
State-backed motor fleet modernization in steel, cement, and chemical plants generates concentrated volume demand. MIIT energy conservation directives and GB 18613 efficiency tiers pressure domestic fleets toward premium efficiency classes. Inner Mongolia and Jiangxi provinces host rare-earth oxide refining capacity that supplies magnet-dependent architectures.
India
BIS efficiency labeling expansion for industrial motors creates regulatory tailwind for EC technology penetration. Mandatory star ratings challenge historically low-cost induction motor dominance. Gujarat and Maharashtra manufacturing corridors see accelerating specification of sensorless control systems for textile and pharmaceutical processing equipment.
Japan
Factory automation upgrade cycles and precision robotics installations sustain demand for high-dynamic-response motor systems. METI energy efficiency guidelines and JIS standards shape product certification requirements. The Chubu region around Nagoya anchors automotive production line retrofits requiring precise torque control.
Electronically Commutated Motors Market Vendor Landscape
On the supply side, the industry is consolidating around integrated motor-drive specialists with captive magnet supply chains and firmware development capabilities. Tiered competition separates premium efficiency certifiers from cost-optimized appliance suppliers. Three archetypes dominate: Asian volume manufacturers with vertical magnet integration, European automation conglomerates bundling EC solutions with drive systems, and mid-scale specialists targeting retrofit channels. Competitive moves center on sensorless control algorithm licensing and multi-jurisdiction certification acceleration.
Among Asia-Pacific volume leaders, Nidec Corporation and Delta Electronics, Inc. exemplify the magnet-integrated manufacturing archetype. Siemens AG anchors European positioning through automation portfolio bundling. These three occupy distinct competitive vectors—magnet supply security, industrial system integration, and efficiency certification depth—without direct overlap in core customer segments.
| Leading Market Players |
|---|
| Regal Beloit Corporation |
| Delta Electronics, Inc. |
| Nidec Corporation |
| Mitsubishi Electric Corporation |
| Siemens AG |
| ABB Ltd. |
| Johnson Electric Holdings Limited |
| Bühler Motor GmbH |
| ebm-papst Group |
| Others |
Supply Flow & Price Mechanics
Rare-earth oxide refining capacity in China's Inner Mongolia and Jiangxi provinces anchors magnet cost structures for permanent magnet rotor architectures, concentrating margin capture upstream while OEMs compete on firmware differentiation and certification depth downstream. This geographic tethering of critical inputs shapes where pricing power accumulates across motor tiers and how supply security premiums translate into contract structures.
Pricing Analysis
Volume-discount tiering structures stratify procurement economics across OEM-direct, distributor, and digital platform channels. Pricing separates IE4-certified permanent magnet units with field-oriented control firmware from sensorless brushless configurations and basic proportional control variants. Cost compression in sensorless appliance-grade segments is intensifying because Chinese manufacturers are scaling output for domestic MIIT retrofit programs. Manufacturing fleet buyers with 10-15 year total cost of ownership horizons prove least price-sensitive, while small commercial retrofit contractors purchasing through digital direct platforms exhibit highest sensitivity to first-cost differentials.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk planning for magnet-dependent motor architectures. Neodymium-iron-boron magnet production draws from Chinese rare-earth refining, Japanese magnet fabrication, and German winding wire supply. Single-source vulnerability concentrates in rare-earth oxide processing capacity. Distribution runs through captive manufacturing networks for high-volume HVAC compressor supply, regional electrical distributors for commercial retrofit projects, and emerging self-service digital portals for smaller system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronically commutated motors market sits in early-cycle expansion as efficiency mandates from Beijing to Brussels force replacement timelines that outpace natural equipment wear. Regulatory tailwinds in industrial motor fleets and commercial HVAC retrofits justify capacity positioning ahead of demand inflection.
For Market Incumbents: Insulate permanent magnet supply security through backward integration into rare-earth sourcing partnerships or long-term offtake agreements with Jiangxi and Inner Mongolia refiners. Defend firmware margin pools by accelerating sensorless control algorithm patent filings before Chinese appliance OEMs achieve parity. Prioritize multi-jurisdiction certification investment to compress time-to-revenue for new product families across UL, CE, and CCC pathways. For New Entrants and Emerging Players: India's BIS efficiency labeling expansion offers the most penetrable geographic entry point, where mandatory star ratings disrupt historically low-cost induction motor dominance. Target sensorless control system specifications for Gujarat and Maharashtra textile and pharmaceutical processing equipment. Pursue licensing-based go-to-market models that monetize firmware IP through per-unit royalties rather than competing on hardware manufacturing scale. For Investors and Strategic Acquirers: Capital is best deployed toward integrated motor-drive specialists with captive magnet supply chains and established field-oriented control calibration service attach rates. The 5-10 year viability window favors acquisition targets with demonstrated multi-jurisdiction certification velocity and digital commissioning tool capabilities. Monitor rare-earth price volatility indices and REACH insulation reformulation compliance timelines as early signals of which product architectures will carry cross-border certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Supply | Secures magnet cost predictability for permanent magnet rotor architectures against Jiangxi province concentration risk. |
| Sensorless Control Algorithm Licensing | Generates recurring royalty streams beyond hardware margins from Chinese appliance OEM volume adoption. |
| Multi-Jurisdiction Certification Acceleration | Compresses UL, CE, and CCC approval timelines to capture DOE 10 CFR 431 substitution windows. |
| Digital Direct Procurement Platform Launch | Fragments traditional distributor relationships by enabling self-service access for Texas and Bavaria system integrators. |
| GaN-Based Inverter Power Stage Development | Collapses thermal management requirements for Northern Virginia hyperscale data center cooling specifications. |
Methodological Framework
A spread of perspectives from HVAC equipment procurement managers, industrial motor fleet maintenance directors, rare-earth supply chain specialists, and automation system integrators converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with these stakeholder categories against secondary validation from US DOE efficiency standard filings, MIIT industrial energy conservation directive documentation, ECHA REACH restriction updates, and customs trade data on rare-earth oxide flows. Bottom-up equipment shipment modeling and top-down energy efficiency mandate penetration rates were triangulated to establish market sizing boundaries.
Demand-supply-balance framing anchored the forecast framework across the projection horizon, with segmentation dimensions spanning motor architecture type, control methodology sophistication, application equipment category, and regional regulatory cluster. CAGRs were derived from replacement cycle compression under efficiency mandates and technology cost curve trajectories for permanent magnet configurations. Industry-specific forecast inputs included MIIT industrial modernization program implementation schedules and BIS efficiency labeling phase-in timelines for the Indian market.
Practitioners should monitor rare-earth price volatility, REACH insulation reformulation compliance deadlines, and multi-jurisdiction certification backlog durations for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
North America Electric Motor Market
Electric Motor
Electric Traction Motor Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Frameless Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Global Automotive Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Motors for Robot Body and Robot Wheels Market