
 Global Automotive Door Hinges Market | 2026-2036
Global Automotive Door Hinges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Door Hinges Market Intelligence
The increasing production of light commercial vehicles alongside traditional passenger cars is broadening the product mix requirements for hinge manufacturers. Magna International Inc. leverages its scale in stamping and assembly to supply major OEMs across North America and Europe. Gestamp Automoción, S.A. specializes in complex metal body-in-white components, including integrated hinge systems, while Edscha Holding GmbH focuses on advanced kinematic systems for doors and tailgates.
Automotive door hinges are mechanical bearings connecting a vehicle door to its body frame, facilitating a controlled swinging motion. These components are engineered from materials like high-strength steel or aluminum to withstand specific load cycles and ensure door alignment during impact events. While steel continues to dominate due to cost, aluminum and composite hinges are seeing greater adoption, driven by vehicle lightweighting initiatives. Passenger vehicles constitute the largest application by volume, but light commercial vehicles offer higher margin opportunities for specialized hinge designs.
Component performance is governed by stringent safety standards, including side-impact crashworthiness tests mandated by the US NHTSA and similar European vehicle type-approval processes. In China, hinge durability and material composition must comply with national GB standards for all new vehicles. OEM procurement patterns are shifting toward suppliers who can deliver integrated, pre-aligned hinge and latch modules that reduce assembly line complexity.
Market Dynamics
The imperative for vehicle lightweighting, driven by stringent global emissions regulations and fuel economy standards, is the central structural force in the automotive door hinge market. This pressure compels a move away from traditional steel towards advanced materials like aluminum and composites, altering cost structures and manufacturing processes.
Growth Catalysts
- Electric Vehicle Expansion:The rapid growth of the electric SUV segment, with its typically heavier doors due to battery placement and structural reinforcement, necessitates the development of stronger, more durable hinge systems.
- Regulatory Mandates:Emissions targets under the EU Green Deal and fuel economy standards from the US EPA directly incentivize the use of lightweight aluminum and composite hinges to reduce overall vehicle mass.
- Manufacturing Consolidation:The concentration of automotive production in clusters within China and Mexico creates localized, high-volume demand, allowing hinge suppliers to achieve economies of scale by co-locating with major OEMs.
Market Restraints
- Material Cost Premium:The higher procurement and processing costs associated with aluminum and composite materials compared to high-strength steel remain a significant barrier to adoption, particularly in economy vehicle segments.
- Substitution from Steel:Advanced high-strength steels (AHSS) offer a cost-effective alternative to aluminum, providing comparable strength-to-weight ratios that can meet lightweighting goals without the significant cost penalty.
- Technical Integration Hurdles:The complexity of designing and validating advanced kinematic hinges for gull-wing or scissor doors creates a technical barrier, limiting their application to low-volume, high-end supercars.
Strategic Opportunities
- Light Commercial Vehicles:Developing specialized, high-load hinges for light commercial vehicle side and rear cargo doors presents a high-margin opportunity beyond the saturated passenger car segment.
- Integrated Mechatronics:There is a clear opportunity to embed sensors and actuators directly into hinge systems for features like soft-close, power assist, and digital keyless entry, creating new value propositions.
- Aftermarket and Repair:Supplying certified, high-quality replacement hinges to the independent aftermarket and collision repair industry offers a stable revenue stream, especially for older vehicle models with high failure rates.
Industry Challenges
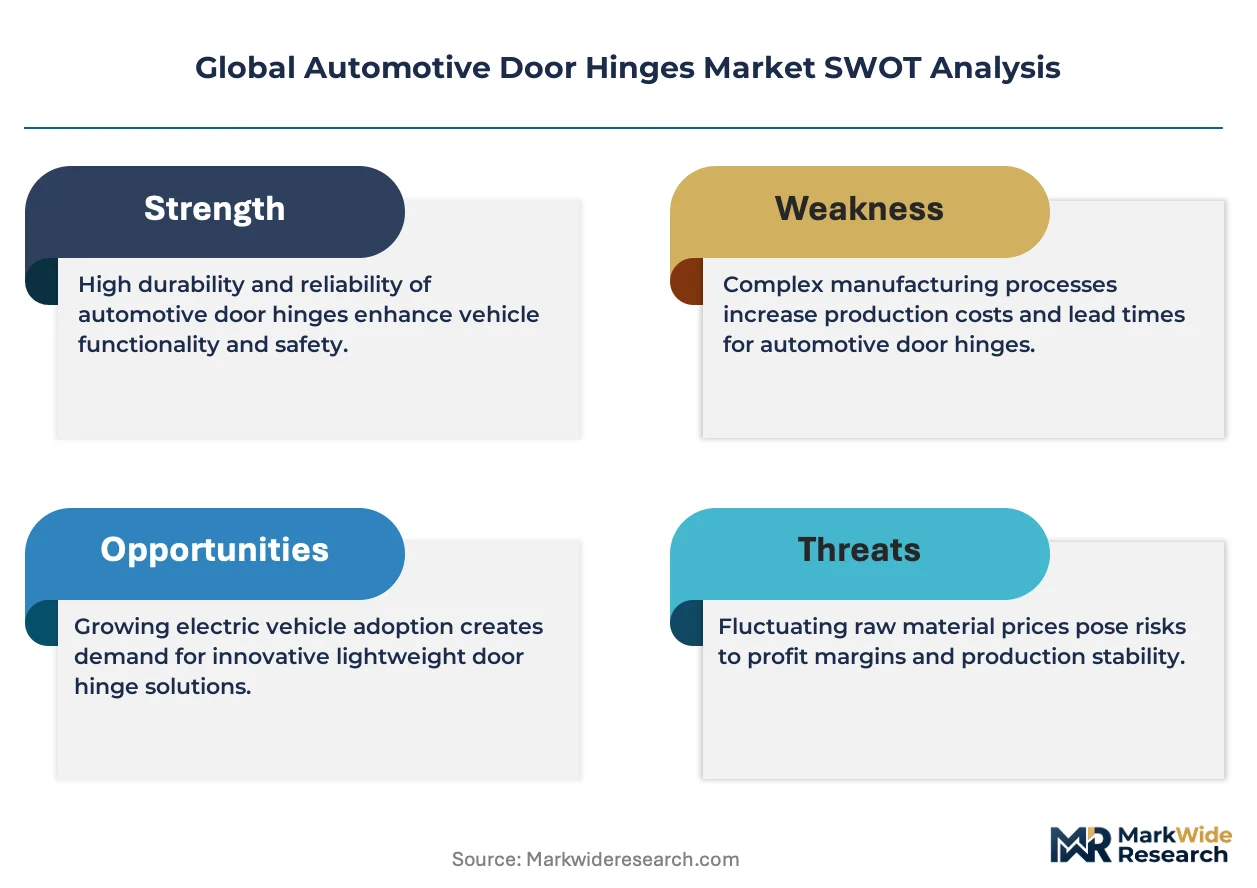
- Compliance Cycle Time:The lengthy and expensive process of durability and crashworthiness testing to meet standards from the US NHTSA and for European vehicle type-approval delays the introduction of new hinge designs.
- Supply Chain Complexity:Managing a global supply chain for raw materials like aluminum and high-strength steel exposes manufacturers to significant price volatility and geopolitical risks, complicating cost forecasting.
- Assembly Line Integration:Ensuring that integrated hinge and latch modules are fully compatible with the diverse and highly automated assembly line systems of different global OEMs is a persistent engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Door Hinges Market |
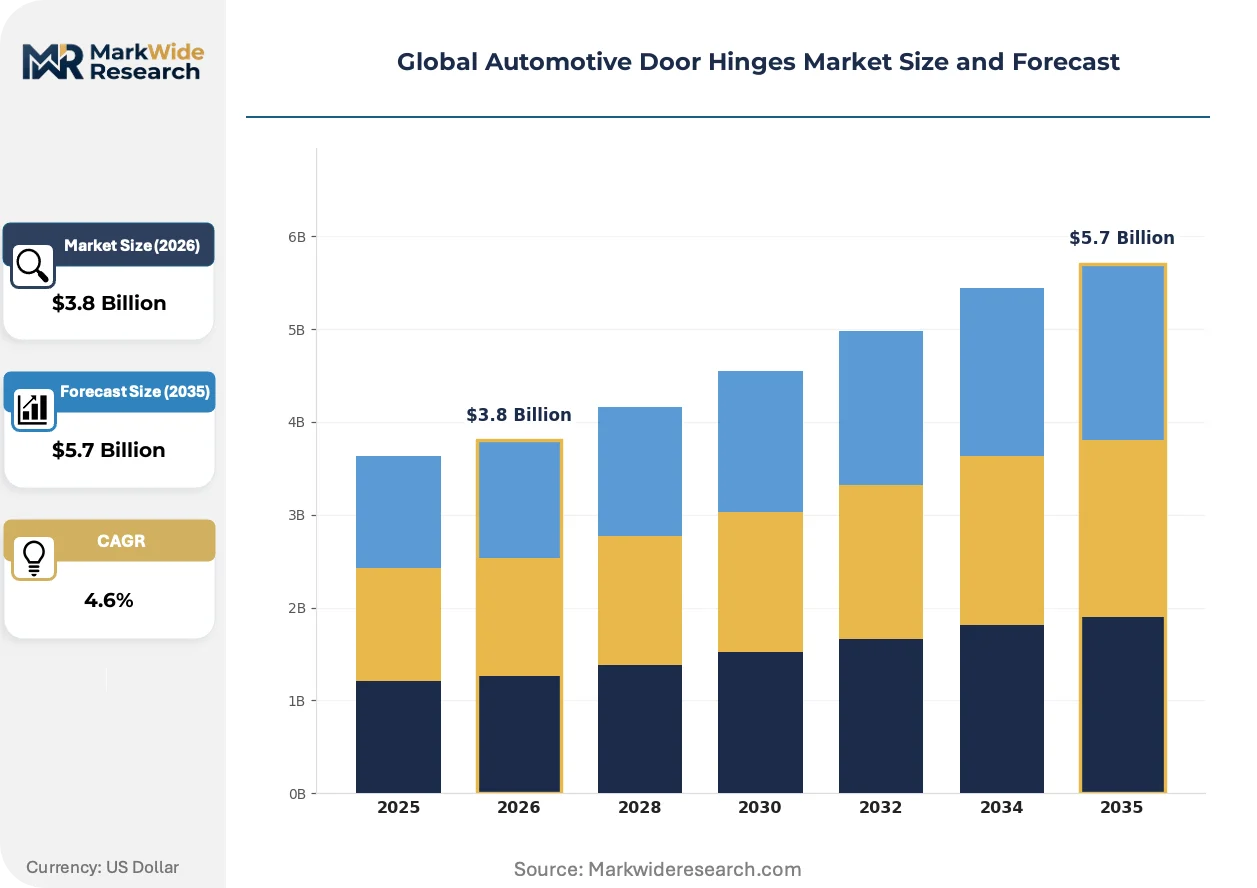
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butt Hinges, Continuous Hinges, Ball Bearing Hinges, Pivot Hinges, Strap Hinges Material: Steel, Aluminum, Stainless Steel, Brass, Composite End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Duty Trucks, Specialty Vehicles |
| Companies Covered | Aisin Seiki Co., Ltd, Magna International Inc., Multimatic Inc., Gestamp Automoción, S.A., Dura Automotive Systems, Brano Group, ER Wagner, Midlake Products & Mfg. Co., Inc., Edscha Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Door Hinges Market Strategic Shifts & Innovations
Innovation in the automotive door hinge market is defined by the convergence of mechanical engineering with advanced electronics and material science. This evolution is a direct response to OEM demands for reduced vehicle weight, enhanced safety, and improved user convenience, pushing hinge design far beyond its traditional role.
Smart hinge technology integrates sensors and micro-actuators to provide advanced functionality. The luxury and premium electric vehicle segments are the earliest adopters of these systems for features like power-assisted opening and soft-closing doors. The core mechanical function of the hinge is converging with the vehicle's central electronic control unit architecture, transforming a simple pivot into a complex mechatronic component.
European regulations, particularly the EU's Corporate Sustainability Reporting Directive (CSRD), are influencing material selection and sourcing. This directive compels suppliers to provide transparent data on the carbon footprint of their products, including the energy used to produce steel and aluminum. Hinge manufacturers supplying European OEMs are now required to document and validate the environmental impact across their entire supply chain.
A notable behavioral change among OEMs is the move toward sourcing complete, pre-aligned door modules rather than individual components. This approach favors large, vertically integrated suppliers who can deliver a sub-assembly that includes the hinge, latch, check arm, and wiring harness. This trend is most pronounced in high-volume vehicle platforms in North America and China, where minimizing assembly line complexity and time is a critical priority.
Global Automotive Door Hinges Market Segmentation
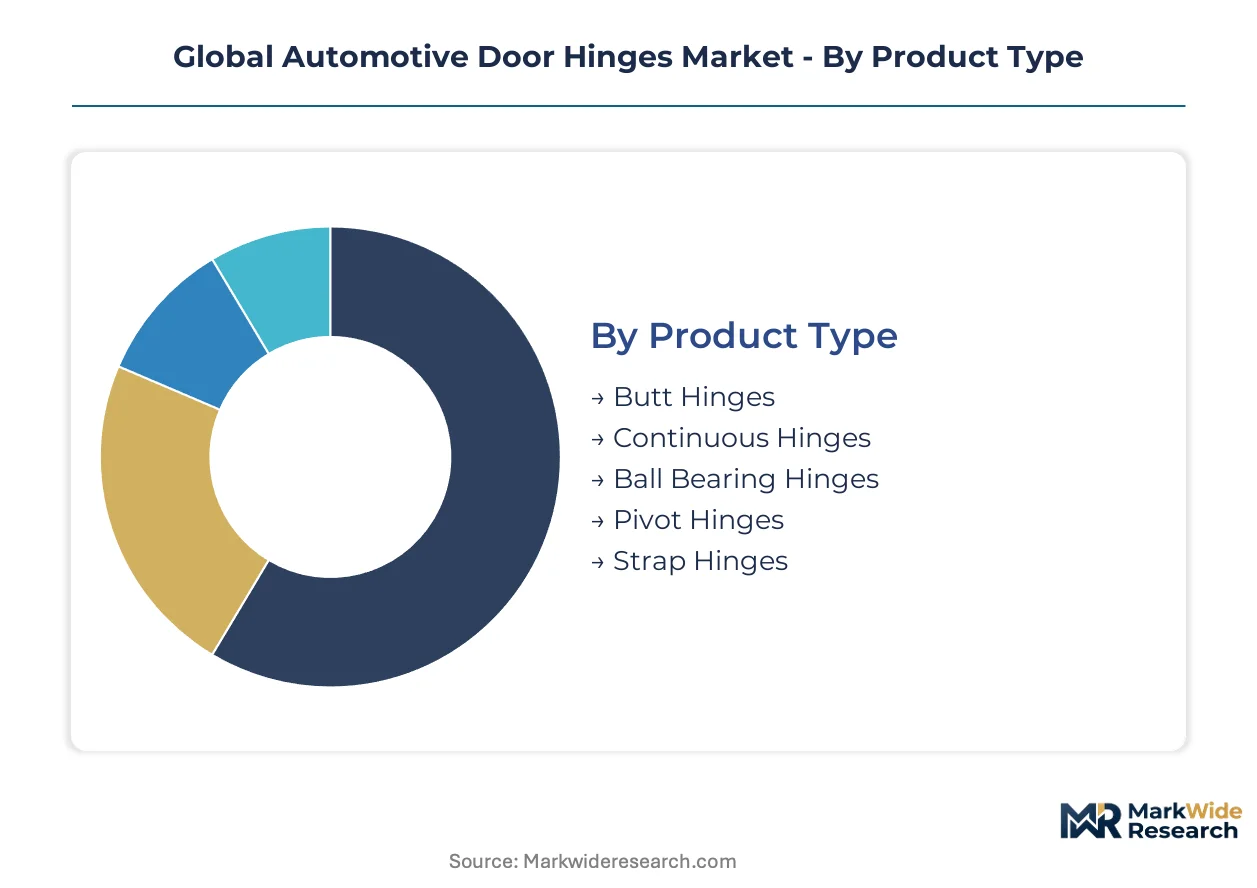
The segmentation of the automotive door hinges market provides a granular understanding of product variations, material demands, and end-user requirements. This detailed breakdown highlights specific opportunities and challenges across different vehicle types and supply chain participants.
Product Type:
The product type segmentation highlights the varying levels of mechanical complexity and integration required for different vehicle door designs.
- Butt Hinges:These are the most common type, consisting of two leaves joined by a pin, offering a simple pivot point for door movement. Demand for butt hinges is concentrated in standard passenger vehicles across Asian manufacturing hubs due to their cost-effectiveness and proven reliability.
- Ball Bearing Hinges:Incorporating ball bearings between the hinge knuckles, these provide smoother operation and enhanced durability, particularly for heavier doors. The electric SUV segment in North America and Europe drives demand for these more robust hinge systems due to increased door weight and higher usage cycles.
- Continuous Hinges:Also known as piano hinges, these run the full length of the door, distributing weight evenly and offering high strength.
- Pivot Hinges:Designed to allow a door to pivot from a single point at the top and bottom, these are often used in specialty or custom vehicle applications.
- Strap Hinges:Characterized by long leaves that extend across the door and frame, strap hinges provide strong support, commonly found in commercial and utility vehicles.
Butt Hinges lead volumes today; Ball Bearing Hinges are gaining share fastest.
Material:
Material choices directly influence hinge performance, cost, and weight, presenting distinct trade-offs for automotive manufacturers.
- Steel:High-strength steel remains the dominant material due to its excellent mechanical properties, cost-effectiveness, and ease of manufacturing. OEMs in China and Mexico extensively utilize steel hinges for their high-volume, economy vehicle platforms.
- Aluminum:Lightweight aluminum alloys are increasingly adopted for their mass-saving benefits, directly contributing to improved fuel economy and reduced emissions. European vehicle manufacturers prioritize aluminum hinges to meet stringent EU Green Deal emission targets.
- Stainless Steel:Offering superior corrosion resistance and aesthetic appeal, stainless steel is typically reserved for niche applications or high-end vehicle models where durability in harsh environments is critical.
- Brass:Brass hinges are less common in modern automotive applications but are sometimes used for aesthetic purposes in luxury or vintage vehicle restorations.
- Composite:Advanced composite materials offer significant weight reduction potential, though their higher cost and complex manufacturing processes limit current adoption to specialized, low-volume applications.
Steel remains the predominant material choice, while aluminum is experiencing the steepest expansion trajectory driven by lightweighting mandates.
End User:
End-user categories reflect distinct procurement patterns and demand for varying levels of integration and customization within the automotive supply chain.
- OEMs:Original Equipment Manufacturers directly integrate hinges into new vehicle designs, demanding high volumes, precise specifications, and often customized solutions. Major OEMs like General Motors and Volkswagen source integrated hinge modules to streamline their assembly lines.
- Aftermarket Providers:These entities supply replacement hinges for vehicle repair and maintenance, catering to a diverse range of vehicle models and ages. The aftermarket segment provides a stable revenue stream for suppliers, particularly for older vehicle models requiring component replacement.
- Tier-1 Suppliers:These companies often receive raw materials or sub-components and assemble them into complete hinge systems before supplying them to OEMs. Suppliers like Magna International Inc. leverage their scale to provide integrated solutions.
- Vehicle Assemblers:Specialized vehicle assemblers, often for commercial or specialty vehicles, purchase hinges directly for their production lines, requiring specific designs for unique door configurations.
OEMs represent the largest volume segment, with aftermarket providers ensuring long-term product lifecycle support.
Application:
Application segments delineate demand based on vehicle type, each presenting unique engineering challenges and volume requirements for door hinge systems.
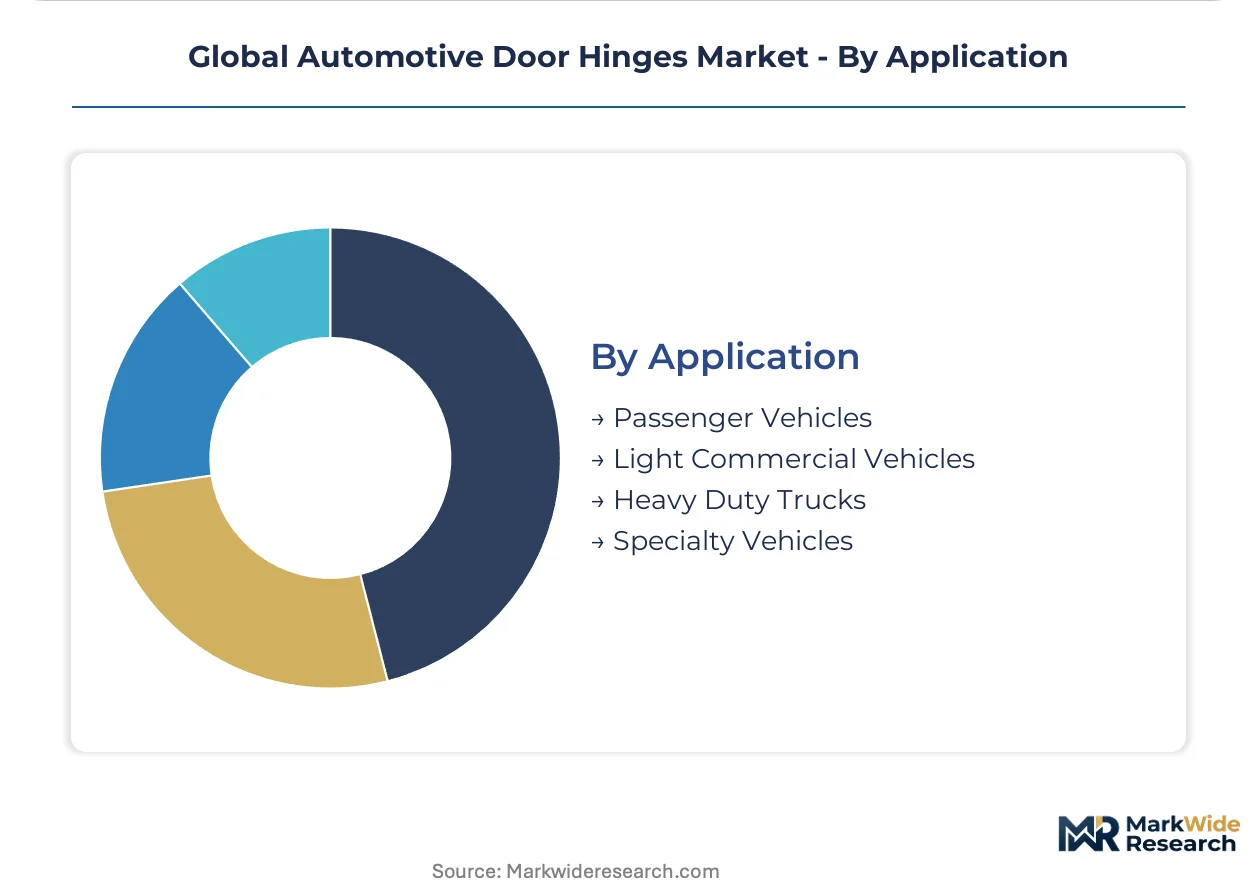
- Passenger Vehicles:This segment includes sedans, hatchbacks, and SUVs, representing the largest volume demand for door hinges globally. The focus here is on cost-effective, durable, and aesthetically integrated designs for mass-market appeal.
- Light Commercial Vehicles:Vans, pickup trucks, and smaller delivery vehicles fall into this category, requiring robust hinges for frequently used cargo doors and higher load capacities. This segment offers higher margin opportunities for specialized hinge designs.
- Heavy Duty Trucks:These vehicles demand extremely durable and heavy-duty hinges capable of withstanding significant stress and harsh operating conditions.
- Specialty Vehicles:This segment encompasses a wide range of vehicles, including emergency vehicles, recreational vehicles, and armored cars, often requiring custom-engineered hinge solutions for unique door mechanisms.
Passenger vehicles consume the highest volume of hinges, but light commercial vehicles offer specialized design opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives shifts in automotive door hinge production, as manufacturers seek lower compliance costs and favorable operating environments. This dynamic influences investment decisions and supply chain configurations across different regions. Global demand for automotive door hinges is concentrating in specific manufacturing hubs.
China
Demand for hinges stems from its massive domestic passenger vehicle market and electric SUV expansion. Chinese GB standards mandate specific durability and material compositions for all new vehicles. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta drive high-volume production.
Mexico
Nearshoring initiatives and established trade agreements with the United States fuel demand for automotive hinges. The country's automotive industry benefits from favorable trade policies like USMCA. Major assembly plants in cities like Puebla and Saltillo create significant localized demand for suppliers.
United States
The push for lightweighting in electric SUVs creates demand for advanced aluminum and composite hinge systems. US EPA fuel economy standards and NHTSA crashworthiness tests influence material selection and design. Automotive manufacturing in the Midwest, particularly around Detroit, remains a core hub for hinge procurement.
Germany
European OEMs require lightweight hinge solutions to meet stringent EU Green Deal emission targets. The country's vehicle type-approval processes demand rigorous testing for new hinge designs. Bavaria and Baden-Württemberg host major automotive component suppliers and assembly operations.
Japan
The sophisticated Japanese automotive market demands high-quality, durable hinge systems for both domestic and export vehicles. METI promotes sustainable manufacturing practices, influencing material choices like aluminum. Production facilities in Aichi Prefecture, home to major OEMs, drive consistent demand for advanced components.
Global Automotive Door Hinges Market Key Industry Players
Capacity expansion dominates the current landscape, as manufacturers seek to meet rising demand from electric vehicle production and lightweighting initiatives. The market structure is tiered, featuring large, integrated suppliers alongside specialized component manufacturers. Strategic archetypes include global Tier-1 integrators and regional niche players. Competitive moves focus on geographic expansion and technology licensing to secure long-term OEM contracts.
Scale-driven manufacturers like Magna International Inc. exemplify the capabilities of vertically integrated suppliers, leveraging extensive stamping and assembly expertise. Gestamp Automoción, S.A. occupies a position among specialists in complex metal body-in-white components, including integrated hinge systems. Edscha Holding GmbH represents manufacturers focused on advanced kinematic systems for doors and tailgates, catering to specialized vehicle requirements. These companies anchor the supply of critical hinge modules to major global OEMs.
| Leading Market Players |
|---|
| Aisin Seiki Co., Ltd |
| Magna International Inc. |
| Multimatic Inc. |
| Gestamp Automoción, S.A. |
| Dura Automotive Systems |
| Brano Group |
| ER Wagner |
| Midlake Products & Mfg. Co., Inc. |
| Edscha Holding GmbH |
| Others |
Cost & Logistics Intelligence
Raw material costs for steel and aluminum hinges flow from global commodity markets, influencing manufacturing expenses and ultimately impacting OEM procurement prices in major automotive hubs.
Pricing Analysis
Direct-to-OEM discounts establish the baseline pricing in the automotive door hinge market, where contract-based long-term offtake agreements are the dominant pricing model. Price differentiation stems from quality grade and customization level, particularly for advanced kinematic systems. Pricing pressure stems from cost compression in high-volume economy vehicle segments, driven by intense competition among suppliers. OEMs represent the most price-sensitive buyers, while aftermarket providers exhibit lower sensitivity due to replacement demand.
Supply Chain Analysis
Returns and refurbishment processes for automotive door hinges remain nascent, with most components moving through a linear supply chain from production to vehicle assembly. Geographic supply concentration centers in China, Mexico, and Germany, leveraging established automotive manufacturing ecosystems. The supply chain depends on raw material inputs like high-strength steel and aluminum alloys, exposing manufacturers to commodity price volatility. Single-source vulnerability for specialized hinge components presents a structural risk for some OEMs. Distribution runs through Tier-1 suppliers directly to vehicle assembly plants globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal, with its stringent emission targets, frames the automotive door hinge market as a regulatory compounder, driving demand for lightweight material innovation.
For Market Incumbents: Anchor existing OEM relationships by investing in pre-aligned hinge and latch module development for high-volume platforms. Expand capacity in key manufacturing clusters like China and Mexico, mitigating supply chain complexity. The material cost premium for aluminum poses a named threat to margins in economy segments. Certification investment in advanced crashworthiness standards provides a crucial lever against emerging competitors.
For New Entrants and Emerging Players: US EPA fuel economy standards in the United States open a window for specialized suppliers of lightweight composite hinge systems. Target high-load hinges for light commercial vehicle cargo doors, representing a high-margin opportunity. The electric SUV segment in North America offers the most penetrable application for durable ball bearing hinge systems. A go-to-market angle focused on integrated mechatronic solutions for power-assisted doors offers clear differentiation.
For Investors and Strategic Acquirers: Consolidation pressure builds where OEMs demand integrated hinge and latch modules, favoring large Tier-1 suppliers. The market's long-term viability spans a 5-10 year window, driven by sustained vehicle production and lightweighting mandates. Acquisition target archetypes include specialized manufacturers of advanced kinematic or composite hinge technologies. Smart hinge adoption in mid-range electric vehicles signals broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mexico | Expanding production in Mexico leverages USMCA trade agreements for North American OEM supply. |
| Advanced Material R&D | Investing in composite material research addresses EU Green Deal lightweighting mandates for European vehicles. |
| Mechatronic Hinge Development | Developing smart hinge systems captures premium value in luxury and electric vehicle segments. |
| Aftermarket Channel Partnership | Securing partnerships with aftermarket providers ensures stable revenue streams for older vehicle models. |
| Integrated Module Certification | Achieving NHTSA and European type-approval for complete modules reduces OEM assembly line complexity. |
Research Approach
Direct dialogue with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations provided qualitative grounding. This primary research was combined with secondary validation from vehicle production databases, IHS Markit registration data, and customs trade reports. A bottom-up estimation of market size was triangulated with top-down validation against overall automotive component spending.
The analytical framework produced volume and value outputs, projecting market trends across the analysis window. Segmentation dimensions modeled included product type, material, end user, application, and regional production clusters. Compound annual growth rates were derived from historical performance and future market drivers. Vehicle production volumes and material costs served as key industry-specific forecast inputs.
Revisions become necessary when significant geopolitical risks or shifts in regulatory enforcement materialize. Forecasts reflect assumptions regarding raw material price stability and sustained global vehicle production. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brake Pad Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Automotive Power Window Regulator Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Friction Pads Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Passenger Car Accessories Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Gear Market
Automotive Parts
Leaf Spring Shackle Side Bar Market