
 Nigeria Passenger Vehicles Lubricants Market | 2026-2036
Nigeria Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Passenger Vehicles Lubricants Market Foresight
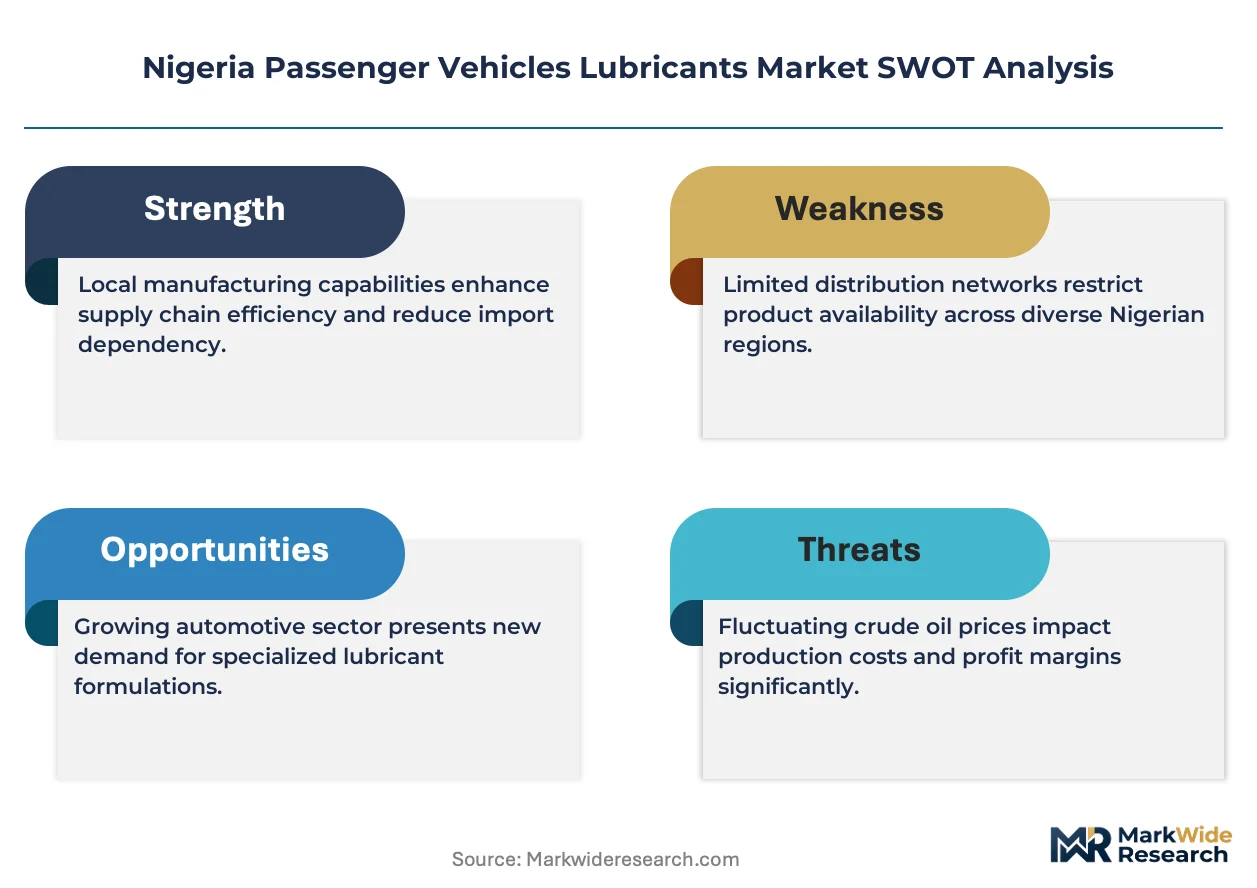
A capital-intensity divergence between integrated refiners and import-dependent blenders is reorganizing competitive dynamics in Nigeria's passenger vehicle lubricants sector. TotalEnergies leverages its downstream infrastructure and coastal storage assets to secure feedstock continuity. Ardova Plc anchors its position through an extensive retail network spanning major Nigerian cities. A-Z Petroleum competes aggressively on price in the informal mechanic segment, where brand loyalty remains thin.
Passenger vehicle lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with viscosity grades typically ranging from SAE 5W-30 to SAE 20W-50 for tropical climates. These formulations incorporate detergent-dispersant packages and anti-wear additives to maintain engine cleanliness under stop-and-go driving conditions common in congested Nigerian cities. Synthetic oil commands premium positioning among fleet operators seeking extended drain intervals, while mineral oil retains volume leadership through mechanic-channel dominance. The workshop distribution channel captures significant margin pools by bundling lubricant sales with labor services, creating sticky customer relationships.
The Standards Organisation of Nigeria (SON) mandates compliance with API and ACEA performance categories for all imported lubricants, effectively filtering out substandard products from Asian gray-market suppliers. Nigeria's Department of Petroleum Resources (DPR) enforces environmental handling standards that increase compliance costs for smaller blenders lacking waste-oil recycling capabilities. Stakeholders must monitor SON's pending adoption of more stringent API SP and ILSAC GF-6 specifications, as these will force reformulation investments and potentially consolidate the supplier base toward technically capable players.
Market Dynamics
API SP and ILSAC GF-6 specification upgrades are forcing wholesale reformulation investments across Nigeria's lubricant supply base, compressing margins for technically deficient blenders while rewarding integrated refiners with captive additive sourcing.
Growth Catalysts
- Fleet operator consolidation:Lagos and Abuja commercial transporters are centralizing procurement through scheduled maintenance contracts, creating volume concentration that favors certified lubricant suppliers.
- SON quality enforcement:The Standards Organisation of Nigeria's API certification mandate is filtering gray-market Asian imports, expanding addressable market for compliant domestic blenders.
- Synthetic base oil adoption:Extended drain interval formulations are penetrating fleet segments as operators calculate total cost of ownership against mineral oil alternatives.
Market Restraints
- Feedstock import dependency:Nigeria lacks domestic Group II/III base oil production, exposing blenders to dollar-denominated input volatility and forex availability constraints.
- Coastal storage concentration:Bulk liquid terminal capacity clusters around Lagos and Port Harcourt, elevating inland logistics costs for northern and eastern distributors.
- Informal mechanic channel stickiness:Unbranded bulk oil repackaging persists in roadside workshops, undermining price integrity for packaged lubricant marketers.
Strategic Opportunities
- Northern corridor expansion:Kano and Kaduna commercial hubs remain underserved by certified lubricant distribution, offering first-mover advantages to organized retail networks.
- Waste oil re-refining integration:DPR environmental handling standards create regulatory permission for vertically integrated players to capture circular economy value pools.
- Digital fleet management convergence:Telematics-enabled predictive maintenance platforms can embed lubricant consumption monitoring, creating data-locked supplier relationships.
Industry Challenges
- Laboratory certification backlog:SON testing capacity constraints delay product approval timelines, freezing working capital in inventory for new formulation launches.
- Mechanic channel education deficit:Synthetic oil benefits remain poorly understood in informal service bays, requiring sustained technical demonstration investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Passenger Vehicles Lubricants Market |
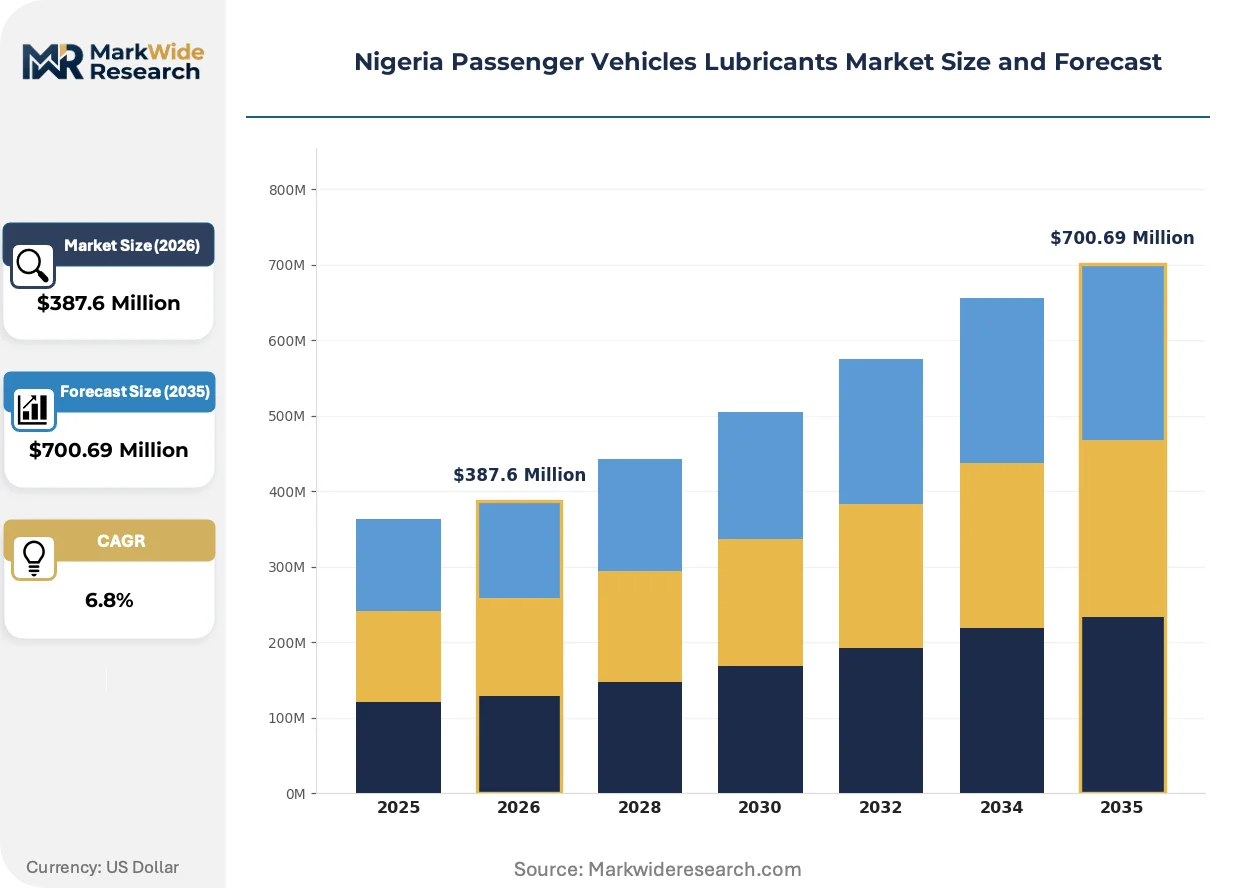
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Mineral Oil, Semi-Synthetic Oil, Bio-Based Oil Application: Engine Lubrication, Transmission Lubrication, Brake System, Cooling System Distribution Channel: Retail Stores, Online Platforms, Workshops, Fleet Services End User: Private Vehicle Owners, Fleet Operators, Repair Shops, Automotive OEMs |
| Companies Covered | 11 Plc, Ardova Plc, BP Plc (Castrol), TotalEnergies, Oando PLC, Conoil Plc, MRS Oil Nigeria PLC, Eterna Plc, A-Z Petroleum, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Passenger Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and distribution channel economics are undergoing simultaneous recalibration across Nigeria's passenger vehicle lubricant sector.
Semi-synthetic lubricant technology is bifurcating the mid-market segment by delivering mineral-oil cost proximity with synthetic performance attributes. Fleet operators in the South-West corridor are adopting these formulations at accelerated rates to bridge drain interval extension with budget constraints. This technology is compressing pure mineral oil margins while restricting full synthetic penetration to premium fleet segments.
SON's pending API SP adoption timeline is accelerating additive package reformulation investments among import-dependent blenders. The specification's enhanced low-speed pre-ignition protection requirements favor suppliers with technical partnerships with major additive houses. Smaller blenders lacking these relationships face consolidation pressure or contract manufacturing dependence.
Workshop channel bundling of lubricant sales with labor services is displacing standalone product transactions in Lagos and Ibadan metropolitan markets. Fleet operators increasingly negotiate all-inclusive service contracts that specify lubricant brand and grade, transferring purchase authority from drivers to procurement departments. This concentration is visible among interstate transport cooperatives operating along the Lagos-Ibadan Expressway corridor.
Nigeria Passenger Vehicles Lubricants Market Segmentation
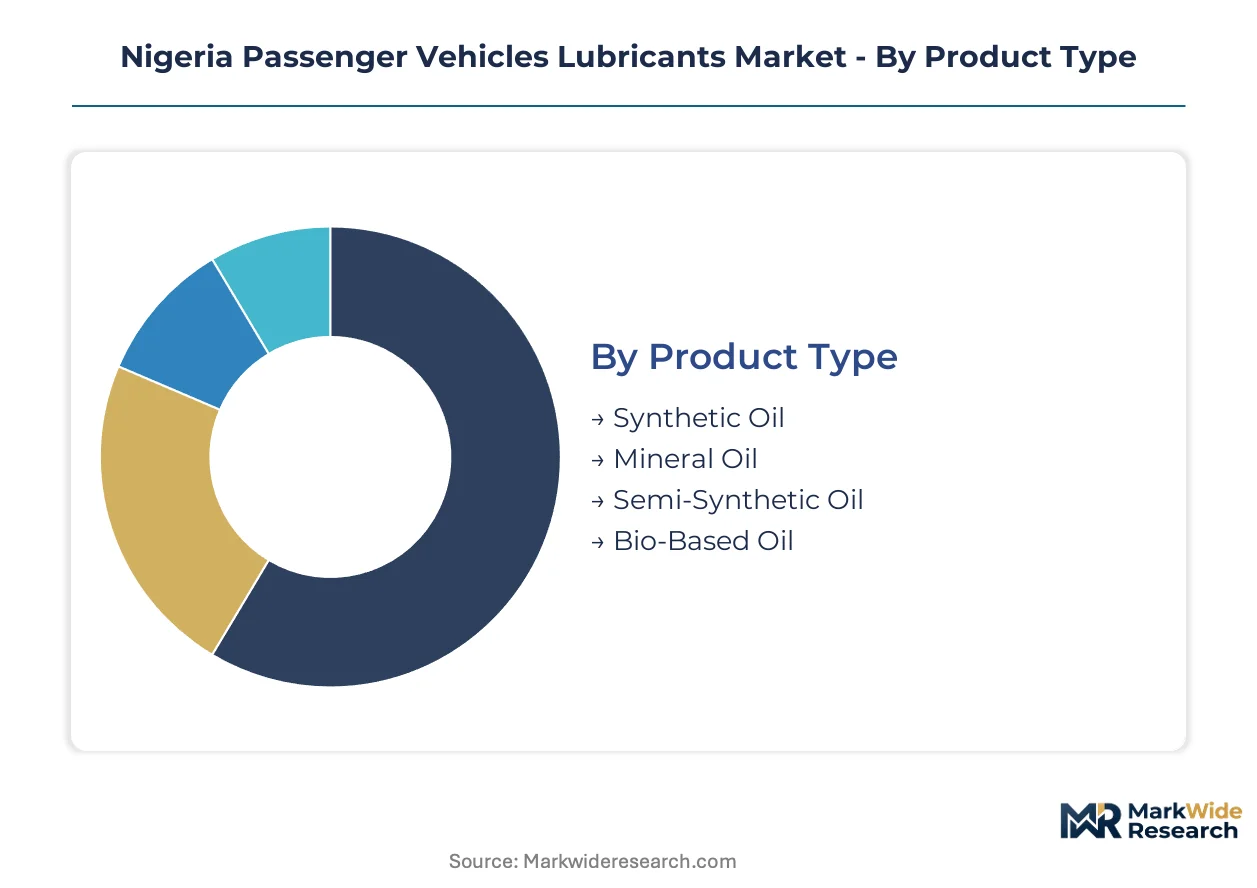
Segmentation in Nigeria's passenger vehicle lubricants market reveals how product specifications, application requirements, and procurement authority distribute across distinct channel economics. Each dimension carries implications for margin capture, working capital intensity, and regulatory exposure.
Product Type:
Workshop mechanics in Lagos and Ibadan push mineral oil volumes through informal bundling with labor services, while fleet procurement departments source synthetics through direct supplier contracts.
- Mineral Oil:Refined petroleum-based formulations dominate roadside mechanic channels across the South-West corridor. Lagos-Ibadan Expressway commercial transporters prioritize unit cost over drain interval extension, sustaining volume leadership despite margin compression.
- Synthetic Oil:Engineered base stocks with uniform molecular structures enable extended drain intervals. Abuja-based fleet operators with centralized maintenance programs calculate total cost of ownership advantages, driving adoption among organized commercial transport cooperatives.
- Semi-Synthetic Oil:Blended formulations bridge price-performance positioning for mid-tier fleet segments in Kano and Kaduna.
- Bio-Based Oil:Vegetable-derived base stocks remain nascent due to SON certification complexity and tropical oxidation stability concerns.
Mineral oil dominates installed base. Synthetic oil is where expansion concentrates.
Application:
Application segmentation tracks where lubricant consumption concentrates by mechanical system, with engine lubrication commanding disproportionate volume share and specification complexity.
- Engine Lubrication:Internal combustion engine oils incorporate detergent-dispersant packages and anti-wear additives formulated for stop-and-go Nigerian driving conditions. API SP specification upgrades are forcing reformulation investments among import-dependent blenders serving Lagos metropolitan demand.
- Transmission Lubrication:Gear oils and automatic transmission fluids protect synchronized manual gearboxes and torque converter systems. Northern corridor commercial transporters operating heavy-duty passenger buses generate concentrated demand for high-viscosity transmission formulations.
- Brake System:Hydraulic fluids maintain pedal response integrity in tropical humidity conditions.
- Cooling System:Antifreeze and coolant formulations prevent overheating in congested urban traffic patterns.
Engine lubrication absorbs the majority of specification investment. Transmission lubrication offers the steepest expansion trajectory as fleet operators extend preventive maintenance intervals.
Distribution Channel:
Channel segmentation determines who controls purchase authority and how margin pools distribute between product and service components.
- Workshops:Mechanic-led service bays bundle lubricant sales with labor, creating sticky relationships through technical recommendation authority. Lagos and Ibadan metropolitan markets show accelerated workshop channel displacement of standalone retail transactions.
- Fleet Services:Direct supplier relationships with commercial transport cooperatives enable volume contracting and scheduled delivery logistics. Interstate operators along the Lagos-Ibadan Expressway corridor negotiate all-inclusive service contracts specifying lubricant brand and grade.
- Retail Stores:Branded packaged lubricants reach private vehicle owners through automotive parts retailers.
- Online Platforms:E-commerce penetration remains limited by mechanic channel trust relationships and counterfeit product concerns.
Workshops control the majority of transaction volume. Fleet services represent the fastest-climbing channel as procurement centralization accelerates.
End User:
End user segmentation separates fragmented individual demand from concentrated organizational procurement with divergent price sensitivity and technical specification requirements.
- Fleet Operators:Commercial transport cooperatives and interstate bus companies centralize lubricant procurement through maintenance departments. SON API certification mandates filter supplier options toward technically capable blenders with laboratory testing partnerships.
- Private Vehicle Owners:Individual motorists rely on mechanic recommendations with limited brand specification authority. Southern Nigeria urban centers generate volume concentration through vehicle density and commuting intensity.
- Repair Shops:Independent service facilities purchase bulk lubricants for resale with labor bundling.
- Automotive OEMs:New vehicle assemblers specify fill-for-life and initial service lubricants for warranty compliance.
Private vehicle owners represent the broadest installed base. Fleet operators concentrate where margin and contract value expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across Nigeria's regional corridors, with the South-West corridor driving premium synthetic adoption while northern and eastern markets remain anchored to mineral oil through informal mechanic channels.
Lagos-Ibadan Corridor
Interstate commercial transport density along the Lagos-Ibadan Expressway sustains elevated lubricant throughput, with fleet operators negotiating centralized procurement contracts. SON's API certification mandate filters supplier options toward technically capable blenders with laboratory testing partnerships. Apapa port proximity enables direct bulk import reception, reducing working capital cycles for coastal storage operators.
Abuja-FCT
Federal government fleet centralization and diplomatic vehicle maintenance standards create concentrated demand for certified synthetic formulations. DPR environmental handling standards elevate compliance costs for smaller blenders lacking waste-oil recycling infrastructure. Garki and Wuse industrial zones host organized service bay networks displacing informal mechanic transactions.
Kano-Kaduna Axis
Northern commercial hubs remain underserved by certified lubricant distribution, with mineral oil dominating through informal bulk repackaging channels. SON testing capacity constraints delay product approval timelines, freezing inventory investment for new market entrants. Kano's Dawanau market cluster sustains traditional trade patterns resistant to packaged brand penetration.
Port Harcourt-Aba Cluster
Petrochemical adjacency and informal manufacturing density create bifurcated demand, with organized fleet services contrasting roadside mechanic bulk oil resale. Coastal storage concentration around Onne and Port Harcourt terminals elevates inland logistics costs for eastern distributors. Aba's spare parts market integrates lubricant sales with mechanical repair bundling.
Onitsha-Enugu Eastern Belt
Commercial transport cooperatives operating interstate routes generate concentrated demand for high-viscosity transmission formulations. Informal mechanic channel stickiness persists in Onitsha's Head Bridge market, undermining price integrity for packaged lubricant marketers. Enugu's organized retail networks represent nascent penetration opportunities for certified supplier expansion.
Nigeria Passenger Vehicles Lubricants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with coastal storage assets and captive additive sourcing distinguishing the upper tier from import-dependent blenders. International majors leverage downstream infrastructure to secure feedstock continuity, while domestic blenders anchor position through retail network density. Two strategic archetypes dominate: integrated refiners with coastal logistics control, and import-dependent blenders competing on price through informal channel penetration. Competitive moves concentrate on retail network expansion and scheduled maintenance contract capture.
Among Nigeria-based operators, 11 Plc and Ardova Plc occupy positions within the domestic blender tier, exemplifying network-driven competitive strategies. TotalEnergies represents the integrated international archetype, leveraging coastal storage and downstream infrastructure. These three companies illustrate the structural divergence between feedstock-integrated and import-dependent market participation models.
| Leading Market Players |
|---|
| 11 Plc |
| Ardova Plc |
| BP Plc (Castrol) |
| TotalEnergies |
| Oando PLC |
| Conoil Plc |
| MRS Oil Nigeria PLC |
| Eterna Plc |
| A-Z Petroleum |
| Others |
Supply & Pricing Matrix
Synthetic base oil substitution for mineral formulations is redrawing procurement geography across Nigeria's lubricant sector, compressing margins for import-dependent blenders while rewarding coastal storage operators with dollar-denominated inventory leverage. This input transition concentrates purchasing power among fleet operators calculating total cost of ownership, forcing price architecture to align with drain interval economics rather than unit volume.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement in Lagos and Abuja, with synthetic formulations commanding premium positioning against spot-market mineral oil transactions at roadside workshops. Price differentiation rests on API certification tier and volume scale, with SON-mandated SP/GF-6 compliance creating a two-tier market. Cost compression in the mineral segment intensifies as gray-market Asian imports undercut packaged brands. Fleet procurement departments show lowest price sensitivity, while informal mechanics and private vehicle owners in the South-West corridor remain highly elastic.
Supply Chain Analysis
Inventory lead times stretch across 8-12 weeks for Group II/III base oils sourced from refineries in the United States, South Korea, and the Netherlands, exposing Nigerian blenders to dollar liquidity constraints. Feedstock draws from Singapore and Rotterdam trading hubs, with additive packages anchored in Germany and the United States. Single-source vulnerability concentrates around Apapa and Onne coastal terminals, where bulk liquid storage capacity clusters. Distribution runs through workshop channel bundling in metropolitan Lagos and Ibadan, with fleet direct contracts bypassing traditional retail layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against electric vehicle powertrain erosion and extended-drain synthetic formulations that collapse mineral oil volume pools. Incumbents must navigate a contracting addressable base for conventional lubricants while capturing premium positioning in fleet telematics-integrated service contracts.
For Market Incumbents: Consolidate coastal storage assets and captive additive sourcing to secure feedstock continuity against forex volatility. Deepen backward integration into waste oil re-refining to capture circular economy value pools under DPR environmental standards. Defend against A-Z Petroleum price aggression in the informal mechanic segment through technical demonstration investments that shift purchase authority from drivers to fleet procurement departments. For New Entrants and Emerging Players: Lead with semi-synthetic formulations targeting Kano and Kaduna commercial hubs, where certified lubricant distribution remains sparse and SON testing backlogs freeze incumbent inventory. Capture first-mover advantage in northern corridor fleet services by negotiating scheduled maintenance contracts with interstate transport cooperatives. Deploy digital fleet management platforms that embed lubricant consumption monitoring, creating data-locked supplier relationships resistant to price-based switching. For Investors and Strategic Acquirers: SON's pending API SP adoption reshapes the acquisition landscape toward technically capable blenders with laboratory testing partnerships and additive house relationships. Target import-dependent mid-cap specialists with coastal logistics access but lacking reformulation capability, as consolidation pressure forces contract manufacturing dependence. Watch mechanic channel education investment levels as the inflection signal separating sustainable margin capture from commodity price erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Storage Expansion | Apapa and Onne terminal capacity secures dollar-denominated feedstock continuity against forex volatility. |
| API SP Certification Investment | SON compliance mandates filter supplier base toward technically capable blenders with additive partnerships. |
| Waste Oil Re-refining Integration | DPR environmental standards create regulatory permission for circular economy value capture. |
| Fleet Telematics Partnership | Predictive maintenance platforms embed lubricant monitoring, locking supplier relationships through data. |
| Northern Corridor Distribution Buildout | Kano and Kaduna commercial hubs offer first-mover advantage in underserved certified lubricant markets. |
Research Methodology
Desk research of customs import records, SON certification registries, and DPR environmental compliance filings preceded structured interviews with fleet procurement managers, roadside workshop operators, coastal storage terminal managers, and lubricant blender technical directors. Primary fieldwork across Lagos, Abuja, Kano, and Port Harcourt validated secondary trade data and pricing intelligence. Bottom-up volume modeling triangulated against top-down macroeconomic indicators to ensure segmentation integrity.
Variance decomposition across product type, application, distribution channel, and end user dimensions anchored the analytical framework, with CAGRs derived from trend extrapolation moderated by regulatory inflection timing. Feedstock import dependency ratios, fleet operator consolidation trajectories, and mechanic channel stickiness indices served as industry-specific forecast inputs throughout the projection horizon.
Forecasts assume regulatory continuity in SON API certification regimes and DPR environmental handling standards; material policy shifts would require re-modeling. Base case projections incorporate stable naira-dollar exchange rate assumptions and no disruptive synthetic base oil supply interruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
Autocatalyst Market
Automotive Parts
VVT Actuators Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Electric Drivetrain Components Market
Automotive Parts
Global Automotive Coolant Reservoir Tank Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Germany Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Global Car Engine Oil Market