
 Automotive Air Conditioning Electric Scroll Compressors Market | 2026-2036
Automotive Air Conditioning Electric Scroll Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Conditioning Electric Scroll Compressors Market Insights
Chinese electric compressor foundry expansion is realigning supply availability for European and North American EV programs. Denso Corporation leverages its inverter scroll integration expertise to anchor thermal system contracts with Toyota and Lexus electrified platforms. Valeo competes through vertically controlled compressor-inverter modules that reduce assembly complexity for OEM customers. BorgWarner, Inc specializes in heat pump-compatible scroll architectures that extend electric range in cold climates.
Automotive air conditioning electric scroll compressors are hermetic positive-displacement devices orbiting a fixed scroll against an orbiting scroll to compress refrigerant, with displacement volumes typically ranging from 20 to 60 cc and operating speeds up to 9,000 rpm in inverter-driven configurations. These units serve as the primary refrigeration prime mover in electric vehicle thermal management systems, replacing belt-driven compressors eliminated by the absence of internal combustion engines. Variable capacity scroll designs now dominate OEM specification sheets as range-conscious automakers prioritize partial-load efficiency over peak cooling output. Inverter technology leads technology segment margins due to semiconductor content and software control integration, while heat pump technology represents the fastest-growing application vector as cold-weather range preservation becomes a consumer purchase criterion. Single-stage architectures retain aftermarket volume but face displacement risk from multi-stage systems in premium EV thermal platforms.
FDA maintains no direct jurisdiction over automotive thermal components, but EPA refrigerant phase-down rules under the AIM Act directly dictate compressor seal compatibility and lubricant chemistry transitions from R-134a to R-1234yf and emerging low-GWP alternatives. NHTSA fuel economy standards indirectly pressure compressor efficiency gains as thermal load reduction contributes to fleet-wide compliance pooling. China's MEE enforces dual carbon alignment disclosures that compressor suppliers must document through lifecycle carbon assessments to qualify for domestic EV platform sourcing. Stakeholders should monitor refrigerant regulatory divergence between EPA, ECHA, and MEE frameworks, as incompatible certification requirements threaten to fragment compressor platform commonality across export markets.
Market Dynamics
Heat pump architecture mandates from Chinese and European regulators are compressing supplier qualification timelines while simultaneously expanding displacement volume requirements for multi-stage scroll systems. This dual pressure is restructuring procurement relationships between compressor foundries and EV platform architects.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology enforces compressor efficiency minimums that disqualify fixed-speed architectures from domestic EV platform sourcing, accelerating inverter scroll adoption.
- Cold-Climate Range Preservation:Consumer purchase criteria in Nordic markets and northern China prioritize heat pump-compatible thermal systems, expanding addressable displacement volumes for multi-stage scroll designs.
- Yangtze River Delta Cluster Concentration:Co-location of domestic foundries and foreign joint ventures near Tesla, BYD, and Volkswagen Group assembly plants reduces logistics friction and compresses supplier response times.
Market Restraints
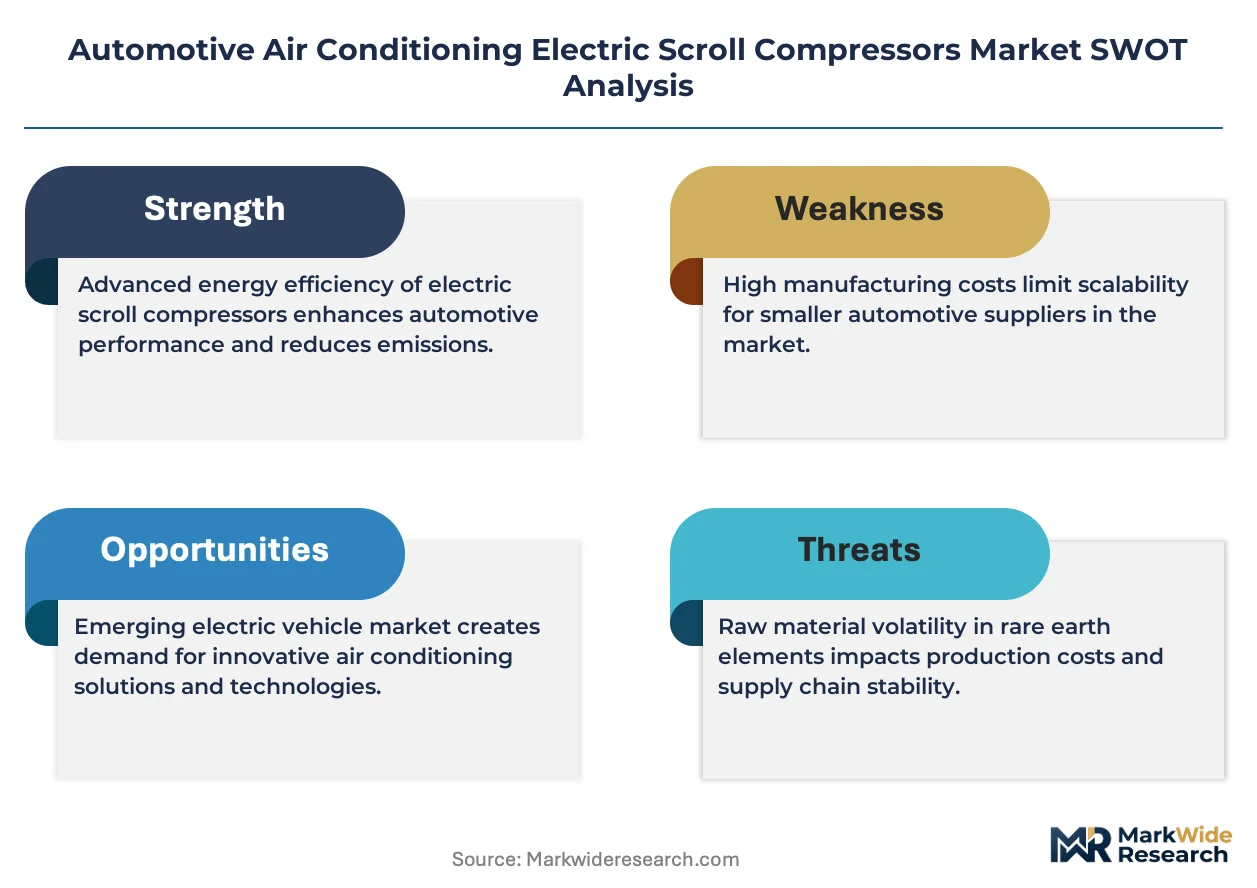
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings embedded in permanent magnet motors create margin compression for inverter scroll manufacturers without long-term offtake agreements.
- Single-Source Semiconductor Dependency:IGBT and SiC inverter module supply concentrates among Taiwanese and German foundries, exposing compressor assemblers to allocation risk during automotive chip shortages.
- R-1234yf Seal Compatibility:EPA refrigerant phase-down timelines under the AIM Act force simultaneous lubricant chemistry transitions that extend validation cycles and delay platform launches.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentive frameworks for automotive components offer tariff advantages for compressor manufacturers establishing local inverter integration capacity.
- Two-Stage Compression Convergence:Marriage of scroll kinematics with vapor injection ports enables heat pump operation at ambient temperatures below minus twenty degrees Celsius, opening Arctic market segments.
- Direct OEM Distribution Channels:Bypass of traditional tiered automotive supplier networks through platform-architect direct contracts captures margin previously allocated to thermal system integrators.
Industry Challenges
- Electromechanical Simulation Talent Scarcity:Compressor housing design now requires coupled thermal-fluid-structural modeling expertise that outstrips available simulation engineering capacity in traditional HVAC recruitment pools.
- Dual Certification Timeline Compression:Simultaneous EPA SNAP approval for refrigerant compatibility and ECHA REACH compliance for lubricant chemistry extends qualification gates by eight to fourteen months.
- Legacy 12V Architecture Integration:High-voltage compressor modules must interface with residual low-voltage control networks in transitional EV platforms, multiplying harness complexity and fault-mode scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Conditioning Electric Scroll Compressors Market |
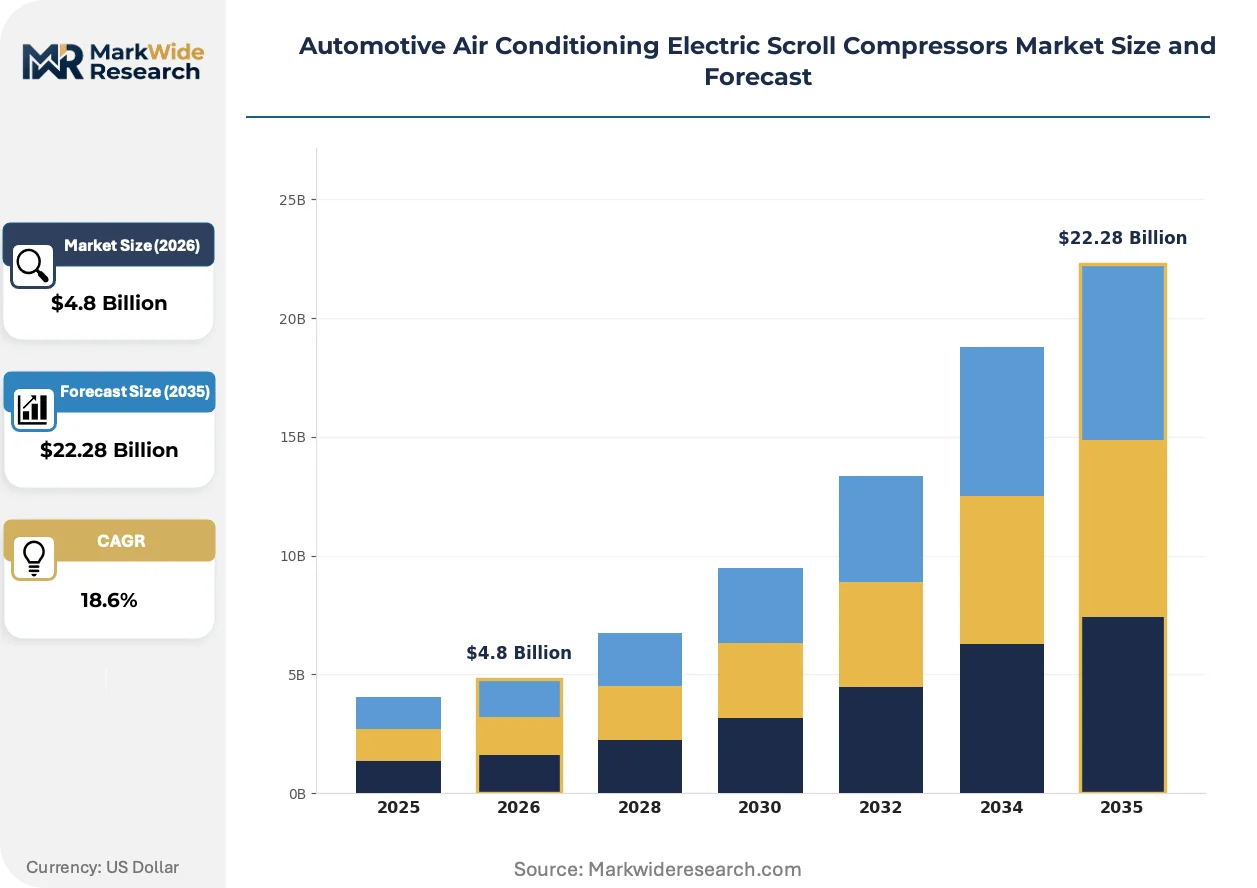
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Multi-Stage, Variable Capacity, Fixed Capacity End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Inverter Technology, Digital Scroll, Conventional Scroll, Heat Pump Technology Installation Type: Integrated Systems, Standalone Units, Retrofit Installations, Custom Installations |
| Companies Covered | Sanden Corporation, Valeo, Denso Corporation, Brose Fahrzeugteile SE & Co. KG, BorgWarner, Inc, MAHLE GmbH, Toyota Industries Corporation, Robert Bosch GmbH, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Conditioning Electric Scroll Compressors Market Trends and Innovations
Scroll compressor architecture is bifurcating between efficiency-optimized single-stage units for temperate climates and multi-stage vapor injection systems for cold-weather markets. This technical divergence is fragmenting supplier R&D allocation and reshaping platform commonality strategies.
Silicon carbide inverter modules are electrifying compressor motor control by enabling switching frequencies above fifteen kilohertz with reduced thermal losses. Tier 1 thermal suppliers are adopting these power electronics for 2026-model-year platforms. This electrification is compressing the efficiency gap between scroll compressors and alternative positive-displacement architectures.
EPA's refrigerant phase-down rules under the AIM Act are forcing lubricant chemistry transitions from polyalkylene glycol to polyolester formulations compatible with R-1234yf and emerging hydrofluoroolefin blends. Compressor seal manufacturers are accelerating fluorocarbon elastomer validation programs. Heat pump-equipped EV platforms face the steepest reformulation timelines due to dual-circuit refrigerant exposure.
Fleet procurement managers are consolidating thermal system sourcing under platform-architect contracts rather than HVAC subsystem tenders. This disintermediation eliminates tiered supplier margins but concentrates volume risk on compressor foundries. Chinese EV manufacturers are pioneering this consolidation, with European OEM procurement divisions now piloting parallel structures.
Automotive Air Conditioning Electric Scroll Compressors Market Segmentation
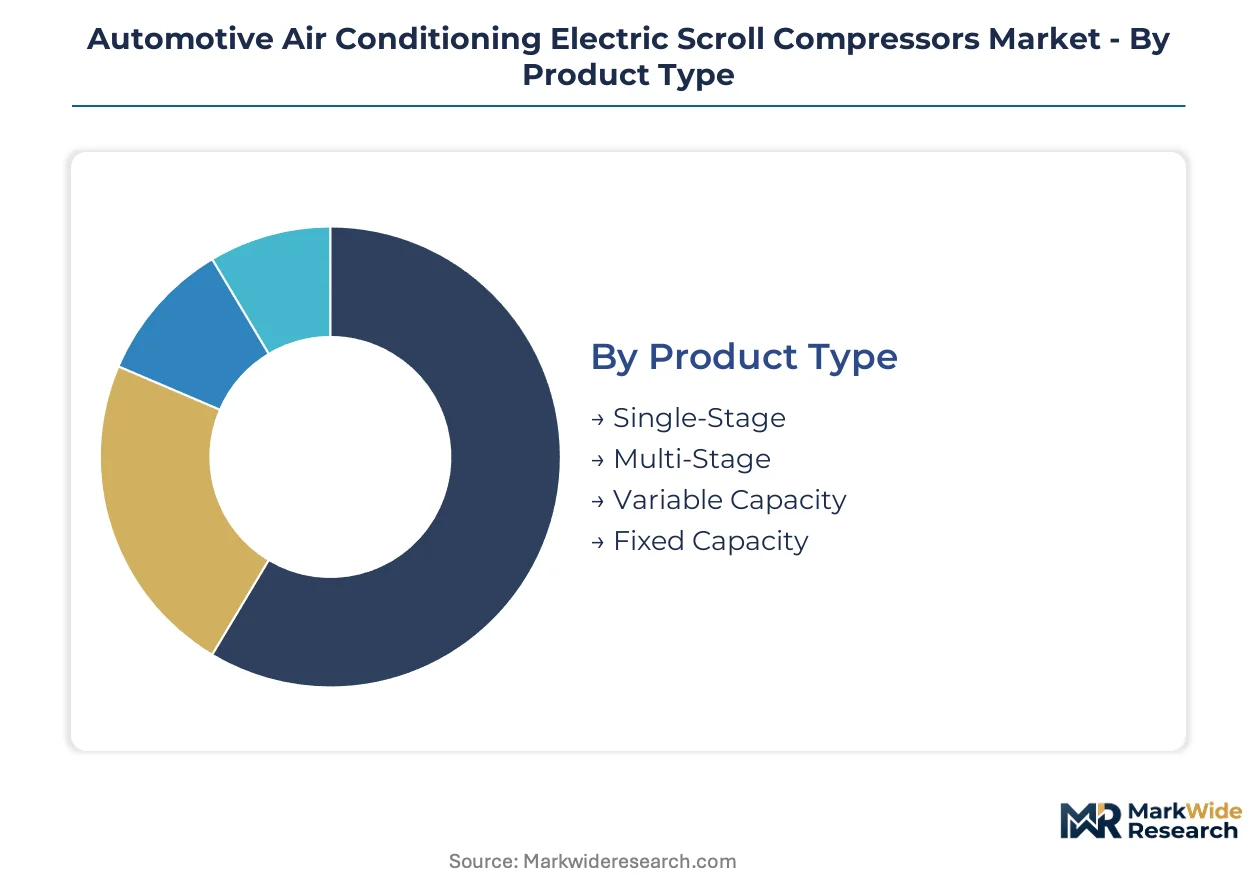
Electric scroll compressor segmentation reflects divergent thermal management architectures across EV platforms. Compressor specification varies sharply between temperate-climate efficiency optimization and cold-weather heat pump deployment. Procurement channels are restructuring as platform architects consolidate sourcing authority previously held by HVAC subsystem integrators.
Product Type:
Compressor foundries concentrate capacity allocation around architectures serving distinct climate zones and platform efficiency targets.
- Variable Capacity:Inverter-driven displacement modulation enables partial-load efficiency optimization critical for range-conscious EV platforms. Denso and Valeo anchor supply contracts with Toyota and European OEMs prioritizing WLTP efficiency metrics over peak cooling output.
- Multi-Stage:Vapor injection scroll designs with inter-stage ports extend heat pump operation to sub-minus-twenty-degree ambient conditions. BorgWarner specializes in these architectures for Nordic markets and northern China where cold-weather range preservation dominates purchase criteria.
- Single-Stage:Fixed displacement units retain aftermarket volume for legacy ICE-to-EV retrofit applications.
- Fixed Capacity:On-off cycling architectures face MIIT efficiency disqualification from domestic Chinese EV sourcing.
Variable capacity absorbs the bulk of installed capacity; multi-stage is expanding most quickly.
End User:
Customer concentration patterns mirror the consolidation of thermal system procurement under platform-architect authority.
- OEMs:Tesla, BYD, and Volkswagen Group now contract compressor foundries directly, bypassing traditional tiered supplier networks. This disintermediation captures margin previously allocated to thermal system integrators but concentrates volume risk on manufacturing capacity.
- Tier-1 Suppliers:Denso, Valeo, and BorgWarner maintain assembler relationships through vertically controlled compressor-inverter modules that reduce harness complexity for OEM customers.
- Vehicle Assemblers:Contract manufacturers in China's Yangtze River Delta cluster source through joint venture structures combining foreign technology with domestic foundry capacity.
- Aftermarket Providers:Service channel demand concentrates on single-stage replacements for early-generation EV thermal systems.
OEM direct procurement commands the dominant share of forward capacity; tier-1 supplier relationships are stabilizing as module integration requirements intensify.
Technology:
Technology margins diverge based on semiconductor content and software control integration depth.
- Inverter Technology:Silicon carbide power modules enable switching frequencies above fifteen kilohertz with reduced thermal losses. IGBT and SiC supply concentrates among Taiwanese and German foundries, exposing compressor assemblers to allocation risk during automotive chip shortages.
- Heat Pump Technology:Dual-circuit architectures face the steepest EPA refrigerant reformulation timelines due to R-1234yf exposure in both cabin and battery thermal loops.
- Digital Scroll:Solenoid-controlled unloading mechanisms offer intermediate efficiency between fixed and fully variable architectures.
- Conventional Scroll:Belt-driven configurations eliminated from EV platforms retain residual demand in hybrid transitional architectures.
Inverter technology anchors value concentration; heat pump configurations are climbing the fastest as cold-climate regulations mandate extended ambient operating ranges.
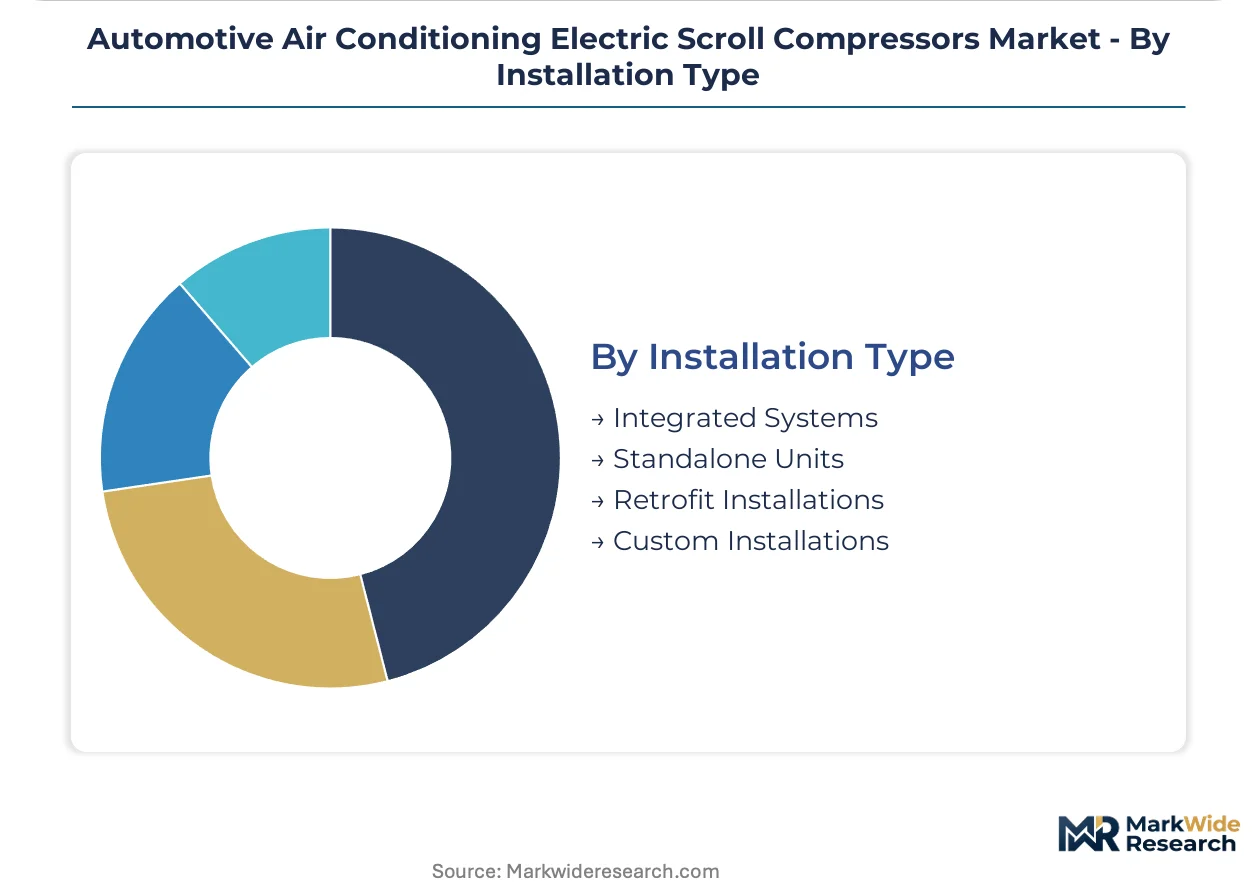
Installation Type:
Integration depth determines harness complexity and platform commonality strategies across EV architectures.
- Integrated Systems:Compressor-inverter modules packaged with refrigerant management valves and sensors reduce assembly line touchpoints. Valeo competes through this vertical control of thermal subsystem integration.
- Standalone Units:Discrete compressor assemblies persist in aftermarket channels and low-volume EV conversions.
- Retrofit Installations:ICE-to-EV thermal system conversions require custom mounting adaptations and high-voltage harness extensions.
- Custom Installations:Commercial vehicle and specialty EV platforms specify displacement volumes and port configurations outside standard passenger car ranges.
Integrated systems dominate new platform allocation; custom installations serve niche volume with higher margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing in Jiangxi Province anchors compressor motor supply chains for electric vehicle thermal systems worldwide. Foundry capacity concentrates near raw material conversion nodes to minimize magnet oxidation during transport. Regulatory divergence across major automotive markets is fragmenting compressor platform commonality.
China
MIIT efficiency mandates disqualify fixed-speed compressor architectures from domestic EV platform sourcing, accelerating inverter scroll adoption. The MEE enforces dual carbon alignment disclosures requiring lifecycle carbon documentation for supplier qualification. Yangtze River Delta automotive clusters host co-located domestic foundries and foreign joint ventures near Tesla, BYD, and Volkswagen Group assembly plants.
Germany
Cold-climate range preservation priorities in Nordic export markets drive heat pump-compatible scroll specification for premium EV platforms. ECHA REACH compliance for lubricant chemistry extends qualification timelines for R-1234yf transition programs. Bavaria and Baden-Württemberg host thermal system development centers supplying Volkswagen Group and BMW electrified architectures.
United States
EPA refrigerant phase-down rules under the AIM Act dictate compressor seal compatibility transitions from R-134a to R-1234yf formulations. NHTSA fuel economy standards indirectly pressure thermal efficiency gains as fleet-wide compliance pooling tightens. Michigan and Ohio automotive corridors concentrate compressor validation facilities serving Detroit Three EV programs.
Japan
METI technology roadmaps prioritize silicon carbide inverter integration for next-generation thermal management efficiency. JIS standards govern compressor durability testing protocols for domestic OEM qualification. Kanto and Chubu industrial regions anchor Denso and Toyota Industries Corporation manufacturing and R&D infrastructure.
India
PLI scheme frameworks for automotive components offer tariff advantages for compressor manufacturers establishing local inverter integration capacity. BIS efficiency labeling requirements are tightening for imported thermal components. Tamil Nadu and Maharashtra automotive corridors attract joint venture investments targeting domestic EV and export markets.
Automotive Air Conditioning Electric Scroll Compressors Market Competitive Landscape
Global majors compete with regional champions across inverter integration depth and thermal system modularity. Market structure tilts toward consolidated tier-1 supplier relationships with direct OEM contracting emerging as a parallel channel. Three archetypes dominate: vertically integrated compressor-inverter module suppliers, heat pump architecture specialists, and scale-focused foundry operators. Competitive moves concentrate on strategic partnerships for semiconductor supply security and geographic expansion into PLI-advantaged manufacturing jurisdictions.
Among Japanese-origin tier-1 suppliers, Denso Corporation and Toyota Industries Corporation occupy positions emphasizing inverter scroll integration and captive thermal system supply. Valeo represents the European module-integration archetype through vertically controlled compressor-inverter packaging. BorgWarner, Inc anchors the heat pump specialization vector with multi-stage scroll architectures for cold-climate markets. Brose Fahrzeugteile SE & Co. KG, MAHLE GmbH, and Robert Bosch GmbH populate the German industrial fabricator tier with diversified thermal portfolio exposure. Sanden Corporation and Hanon Systems exemplify Asia-Pacific foundry-scale positioning with regional market density advantages.
| Leading Market Players |
|---|
| Sanden Corporation |
| Valeo |
| Denso Corporation |
| Brose Fahrzeugteile SE & Co. KG |
| BorgWarner, Inc |
| MAHLE GmbH |
| Toyota Industries Corporation |
| Robert Bosch GmbH |
| Hanon Systems |
| Others |
Pricing and Supply Chain Analysis
Platform-architect procurement consolidation by Tesla, BYD, and Volkswagen Group anchors contract-based long-term offtake pricing for electric scroll compressors. This buyer concentration shifts pricing power toward volume-scaled foundries capable of direct OEM qualification.
Pricing Analysis
Warranty and service bundling separates premium compressor-inverter modules from unbundled standalone units. Pricing stratifies across premium, standard, and economy tiers based on semiconductor content grade and MIIT efficiency certification level. Cost compression in fixed-capacity architectures is intensifying because MIIT mandates disqualify these units from domestic Chinese EV sourcing. Aftermarket providers exhibit the highest price sensitivity, while OEM platform architects prioritize efficiency metrics over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European and North American OEMs mandate multi-supplier qualification for IGBT and SiC inverter modules. Manufacturing concentrates in China, Taiwan, and Germany, with rare earth magnet processing anchored in Jiangxi Province. The chain draws from neodymium-dysprosium permanent magnets, fluorocarbon elastomer seals, and polyolester lubricants. Single-source semiconductor vulnerability from Taiwanese and German foundries exposes assemblers to allocation risk. Distribution runs through platform-architect direct contracts and tier-1 thermal system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into inverter semiconductor sourcing and refrigerant-compatible seal manufacturing is reshaping competitive positioning in electric scroll compressors. Players are racing to secure upstream magnet offtake and downstream platform-architect relationships.
For Market Incumbents: Cement semiconductor supply security through long-term foundry partnerships with Taiwanese and German SiC manufacturers. Expand captive magnet processing capacity in Jiangxi Province to offset rare earth price volatility. Denso and Valeo must defend against emerging Chinese foundries by accelerating heat pump-compatible multi-stage R&D.
For New Entrants and Emerging Players: Launch via direct OEM distribution channels bypassing tiered supplier networks. Target India's PLI-advantaged manufacturing corridors for tariff-competitive inverter integration capacity. White-space exists in two-stage vapor injection architectures for Arctic climate segments and aftermarket retrofit installations for early-generation EV thermal systems.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated compressor-inverter specialists with silicon carbide control expertise. Long-term viability hinges on qualification for Chinese dual carbon disclosure requirements and EPA SNAP refrigerant compatibility. Watch for MIIT efficiency mandate tightening as the inflection signal compressing fixed-speed residual demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Enables switching frequencies above fifteen kilohertz with reduced thermal losses for Denso and Valeo. |
| Rare Earth Magnet Supply Agreement | Secures neodymium-dysprosium offtake from Jiangxi Province processors against price volatility. |
| Heat Pump Architecture Development | Extends multi-stage scroll operation to sub-minus-twenty-degree ambient for Nordic and northern China markets. |
| Platform-Architect Direct Contracting | Bypasses tiered supplier margins and concentrates volume risk on manufacturing capacity. |
| Dual Certification Investment | Accelerates simultaneous EPA SNAP and ECHA REACH compliance to compress qualification timelines. |
Research Methodology
Document review covered SEC filings from compressor manufacturers, MIIT efficiency disclosure databases, and EPA SNAP approval records, complemented by interviews with OEM platform engineers, Tier 1 thermal supplier procurement leads, aftermarket distributors, and semiconductor foundry account managers. Secondary validation drew from IHS Markit vehicle production data, Yangtze River Delta industrial cluster reports, and rare earth trade flow statistics. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Cross-referencing historical inverter adoption curves against expert panel input on heat pump penetration rates structured the analytical framework across the analysis window. Segmentation dimensions modeled include propulsion architecture, compressor capacity type, technology tier, and regional production cluster. CAGRs were derived from coupled thermal management demand projections and EV platform rollout schedules. Silicon carbide cost decline curves and refrigerant phase-down timelines served as key forecast inputs.
Rare earth magnet price spikes, semiconductor allocation disruptions, and refrigerant regulatory divergence between EPA, ECHA, and MEE frameworks are the dominant revision risks. Deviation in MIIT efficiency mandate enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Wiper Systems Market