
 Automotive Steering Shaft Market | 2026-2036
Automotive Steering Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steering Shaft Market Analytics
Carbon fiber-reinforced polymer is expanding its share in high-performance steering shafts as automakers target mass reduction targets without sacrificing torsional rigidity. JTEKT Corporation leverages integrated forging and machining operations to control cost curves across Japanese and North American assembly plants. Nexteer Automotive Group Ltd. anchors its position through electric power steering integration, while ZF Friedrichshafen AG competes via modular platform architectures that span multiple OEM customers.
An automotive steering shaft is a mechanical linkage that transmits torque from the steering wheel to the steering gear, typically manufactured from hollow-drawn steel tubing with yoke joints at each end to accommodate angular misalignment and column collapse during frontal impact. Its primary purpose is to provide precise directional control while meeting occupant safety standards for energy absorption. Collapsible shafts and electronic steering shafts command premium positioning as electrified architectures proliferate, whereas fixed shafts occupy mature, cost-sensitive segments in emerging-market truck applications. Aluminum-intensive designs are capturing margin pools in European and Asian OEM programs where gram-level weight savings translate directly into fleet compliance outcomes.
NHTSA Federal Motor Vehicle Safety Standards and EPA Corporate Average Fuel Economy rules shape material selection and structural design requirements for steering shafts sold into the United States. ECE R12 and ECE R94 regulations in Europe mandate specific collapse-force characteristics and intrusion resistance that differentiate certified products from non-compliant alternatives. Stakeholders must monitor how software-defined vehicle architectures redefine the mechanical interface between driver input and steer-by-wire actuators.
Market Dynamics
Electronic steering shaft architectures are compressing mechanical component counts as steer-by-wire systems eliminate traditional column linkages, forcing suppliers to pivot from forged steel expertise toward sensor integration and software calibration capabilities.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Automakers substitute aluminum and carbon fiber-reinforced polymers for steel to achieve gram-level mass reduction targets that translate directly into fleet compliance credits.
- Electric vehicle platforms:Battery-electric architectures demand collapsible steering shafts with integrated position sensors to support autonomous emergency steering and lane-keeping systems.
- German premium OEM clusters:Stuttgart and Munich anchor tier-1 supply networks where aluminum-intensive designs capture margin pools through gram-level weight savings.
Market Restraints
- Aluminum price volatility:LME aluminum futures create input cost instability for lightweight shaft programs, compressing margins when hedging strategies fail.
- Steer-by-wire substitution threat:Elimination of mechanical steering columns in Level 4 autonomous vehicles threatens demand for traditional shaft assemblies.
- ECE R12 collapse-force certification:European homologation timelines extend 18-24 months for new material formulations, delaying program launches.
Strategic Opportunities
- Software-defined vehicle architectures:Convergence of mechanical shafts with torque sensors and ECU interfaces creates new revenue pools in integrated steering modules.
- Indian commercial vehicle expansion:Domestic truck and bus production growth under the PLI scheme creates demand for cost-optimized fixed shafts in emerging-market applications.
- NHTSA crashworthiness mandates:Updated Federal Motor Vehicle Safety Standards for frontal impact energy absorption drive replacement cycles in North American supplier programs.
Industry Challenges
- Mechatronics talent scarcity:Integration of torque sensors, angle encoders, and ECU calibration requires skill sets concentrated in automotive electronics, not traditional forging operations.
- Legacy platform coexistence:Suppliers must maintain parallel production lines for mechanical shafts serving internal combustion fleets and electronic variants for electrified architectures.
- ISO 26262 functional safety certification:ASIL-D compliance for steer-by-wire interfaces demands capital-intensive testing infrastructure and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Shaft Market |
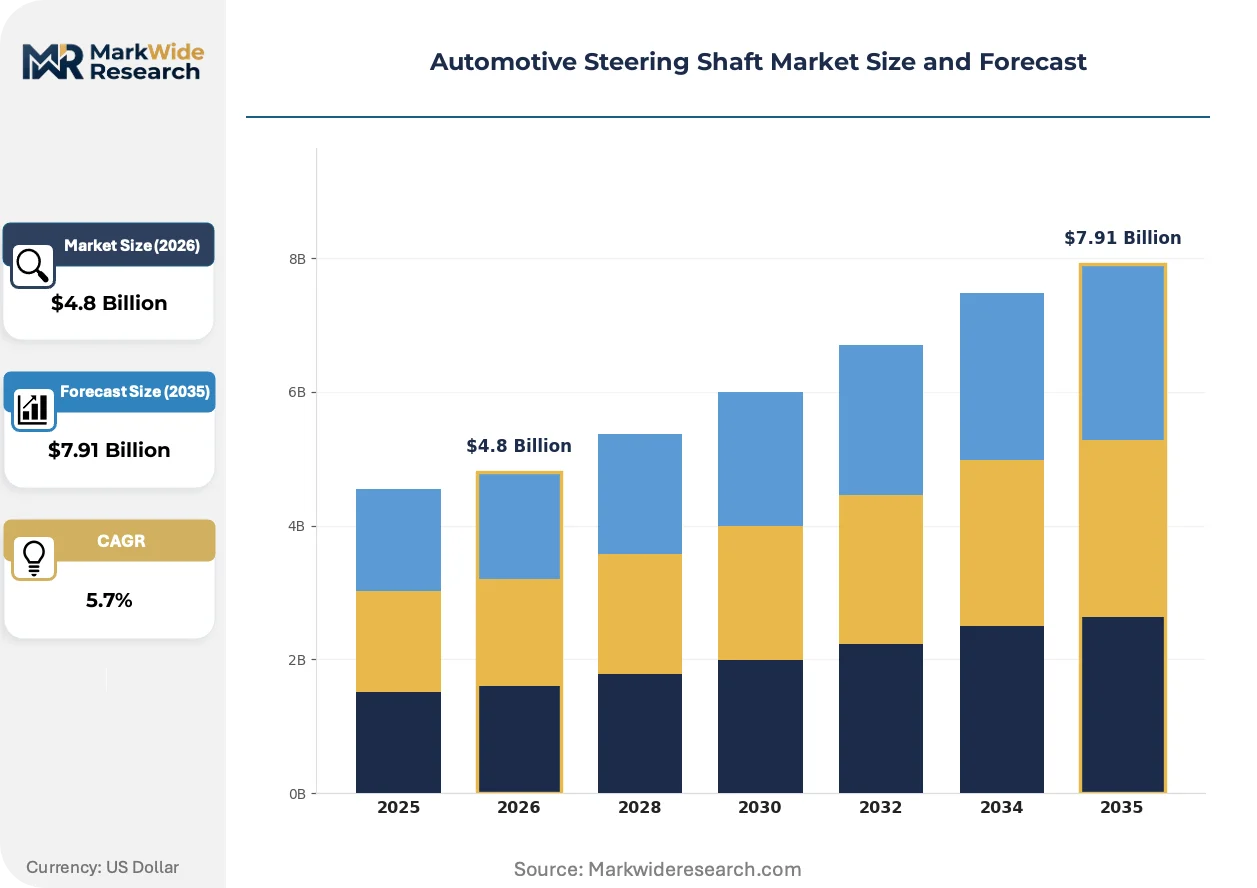
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Shaft, Collapsible Shaft, Rack and Pinion, Electronic Steering Shaft Application: SUVs, Sedans, Trucks, Motorcycles Material: Steel, Aluminum, Composite, Magnesium End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | JTEKT Corporation, Nexteer Automotive Group Ltd., ZF Friedrichshafen AG, Robert Bosch GmbH, NSK Ltd., Showa Corporation, Thyssenkrupp AG, Hyundai Mobis Co., Ltd., Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Shaft Market Evolving Landscape
Material substitution and sensor integration are collapsing the boundary between mechanical hardware and electronic control systems, redefining supplier value propositions around torque transmission.
Carbon fiber-reinforced polymer is unifying mass reduction with torsional rigidity in high-performance steering shafts. European premium OEMs specify these materials for electric sports car platforms where every kilogram affects range certification. This unifying capability is compressing the supplier base toward composites specialists with automotive forging partnerships.
NHTSA Federal Motor Vehicle Safety Standard 203/204 updates are mandating enhanced column collapse characteristics for frontal impact protection. Tier-1 suppliers must redesign yoke joint geometries and tube wall thicknesses to meet revised energy absorption curves. North American truck programs face the steepest compliance costs due to higher steering loads and existing platform architectures.
Fleet procurement departments now specify total cost of ownership metrics rather than unit pricing for steering shaft contracts. Long-haul truck operators in the US Midwest prioritize 10-year corrosion warranties and predictive maintenance telemetry over initial purchase price. This behavioral shift favors suppliers with integrated forging, machining, and sensor calibration capabilities under single-source accountability.
Automotive Steering Shaft Market Segmentation
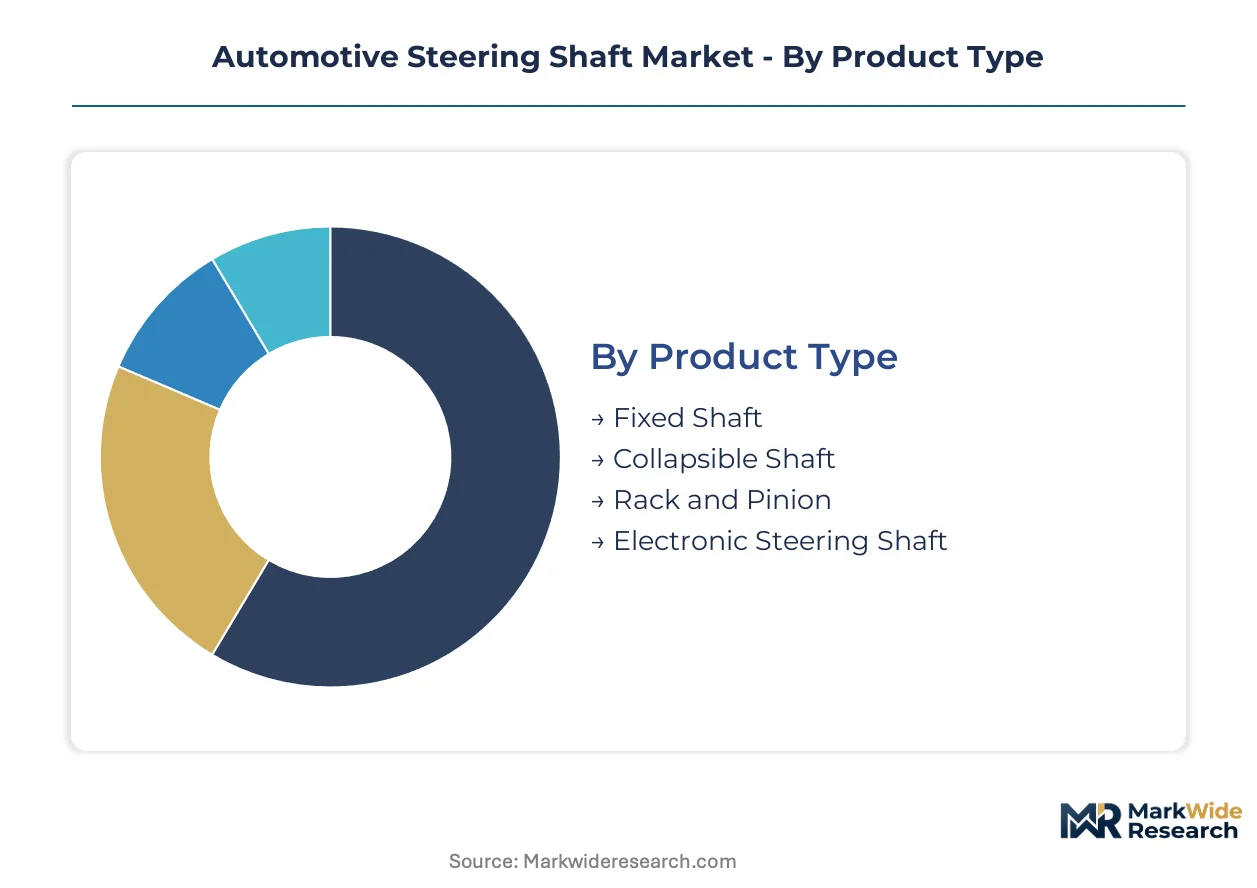
Segmentation in the automotive steering shaft market reveals how certification requirements, material science advances, and vehicle electrification create divergent margin structures across product categories. Suppliers must navigate parallel regulatory pathways while serving internal combustion legacy fleets and next-generation electric architectures simultaneously.
Product Type:
ISO 26262 ASIL-D functional safety certification governs electronic steering shafts, while collapsible variants face NHTSA FMVSS 203/204 and ECE R12 homologation timelines that extend 18-24 months for new formulations. Fixed shafts carry lighter regulatory burdens concentrated in basic crashworthiness standards.
- Collapsible Shaft:Engineered with telescoping tube sections and controlled deformation zones that absorb frontal impact energy while maintaining steering column integrity. Demand concentrates in North American truck platforms where NHTSA mandates drive replacement cycles for enhanced occupant protection. EPA fuel-economy credits accelerate aluminum-intensive variants in German premium OEM programs.
- Electronic Steering Shaft:Integrates torque sensors, angle encoders, and ECU interfaces to enable steer-by-wire architectures and autonomous emergency steering. Battery-electric platforms in Stuttgart and Munich anchor tier-1 procurement as automakers pursue software-defined vehicle capabilities. ASIL-D compliance demands capital-intensive testing infrastructure that filters supplier participation.
- Fixed Shaft:Conventional hollow-drawn steel construction with yoke joints for angular misalignment accommodation in cost-sensitive applications.
- Rack and Pinion:Direct steering gear interface common in compact vehicle platforms with simplified mechanical linkage requirements.
Leading the category by volume: Collapsible Shaft. Growing fastest: Electronic Steering Shaft.
Application:
Cost tier differentiation separates premium electric SUV programs specifying carbon fiber-reinforced polymer shafts from economy sedan procurement favoring steel tubing. Commercial vehicle applications impose durability premiums that reshape supplier margin pools.
- SUVs:Higher steering loads and elevated seating positions demand enhanced torsional rigidity specifications. German electric sports car platforms specify aluminum and composite materials where gram-level weight savings affect range certification.
- Sedans:Volume concentration in mass-market passenger car segments with standardized steel shaft configurations and compressed procurement cycles.
- Trucks:Long-haul operators in the US Midwest prioritize 10-year corrosion warranties and predictive maintenance telemetry over initial purchase price, favoring integrated forging and sensor calibration capabilities.
- Motorcycles:Niche application with specialized lightweight shaft requirements for handlebar steering interfaces.
Trucks command the highest per-unit pricing. SUVs are climbing the fastest as electrification reshapes platform architectures.
Material:
Supply concentration for aluminum and composite feedstocks determines regional cost competitiveness, with LME futures volatility compressing margins for lightweight programs when hedging strategies fail.
- Steel:Dominant hollow-drawn tubing specification with established forging and machining supply chains across Japanese and North American assembly plants. Mature cost curves support emerging-market truck applications in India under PLI scheme incentives.
- Aluminum:Captures margin pools in European and Asian OEM programs where gram-level weight savings translate directly into fleet compliance outcomes. Input cost instability from LME futures creates margin pressure for lightweight shaft programs.
- Composite:Carbon fiber-reinforced polymer unifies mass reduction with torsional rigidity in high-performance applications. European premium OEMs specify these materials for electric sports car platforms.
- Magnesium:Ultra-lightweight specification for specialized weight-critical applications with limited current deployment.
Steel retains volume leadership. Composites are expanding most quickly in premium electric platforms.
End User:
Procurement accountability patterns separate OEM direct sourcing of integrated electronic modules from aftermarket replacement demand concentrated in corrosion-warranty and maintenance-telemetry specifications.
- OEMs:Direct procurement of electronic steering shafts with integrated position sensors for autonomous emergency steering and lane-keeping systems. Software-defined vehicle architectures create new revenue pools in integrated steering modules.
- Tier-1 Suppliers:Modular platform architectures spanning multiple OEM customers with single-source accountability for forging, machining, and sensor calibration capabilities.
- Vehicle Assemblers:Contract manufacturing arrangements with specified material and certification requirements.
- Aftermarket Providers:Replacement cycle demand driven by NHTSA crashworthiness mandate updates and corrosion warranty claims in long-haul truck fleets.
OEMs dominate procurement value. Tier-1 suppliers are gaining share fastest through integrated module capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive steering shafts clusters in Germany, where Stuttgart and Munich anchor tier-1 supply networks for premium vehicle platforms. Procurement patterns diverge sharply between mature markets pursuing lightweight material substitution and emerging economies optimizing cost-sensitive fixed shaft configurations.
United States
NHTSA Federal Motor Vehicle Safety Standard 203/204 updates are mandating enhanced column collapse characteristics for frontal impact protection. Long-haul truck operators in the US Midwest prioritize 10-year corrosion warranties and predictive maintenance telemetry over initial purchase price. Detroit-area suppliers face the steepest compliance costs due to higher steering loads and existing platform architectures serving domestic OEM programs.
Germany
Gram-level weight savings in aluminum-intensive designs translate directly into fleet compliance outcomes for EPA and EU Green Deal targets. ECE R12 and ECE R94 regulations mandate specific collapse-force characteristics that differentiate certified products from non-compliant alternatives. Stuttgart and Munich anchor tier-1 supply networks where ZF Friedrichshafen AG and Robert Bosch GmbH serve premium electric sports car platforms.
Japan
JTEKT Corporation leverages integrated forging and machining operations to control cost curves across domestic and North American assembly plants. METI industrial policy supports lightweight material R&D through collaborative supplier-OEM consortia. Toyota City and Nagoya industrial corridors concentrate precision forging capacity for both domestic consumption and export programs.
China
Domestic battery-electric platform proliferation is accelerating procurement of electronic steering shafts with integrated position sensors. MIIT new energy vehicle mandates and GB standards for steering system safety shape supplier certification requirements. Yangtze River Delta manufacturing clusters concentrate capacity for both domestic OEMs and export-oriented joint ventures.
India
Domestic truck and bus production growth under the PLI scheme creates demand for cost-optimized fixed shafts in emerging-market applications. BIS certification timelines and central government production-linked incentives are reshaping supplier localization strategies. Tamil Nadu and Maharashtra industrial corridors attract forging investments serving commercial vehicle OEMs.
Automotive Steering Shaft Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers pivot from forged steel expertise toward sensor integration capabilities. The vendor base concentrates around three tiers: diversified automotive component conglomerates with integrated electronics divisions, specialized steering system suppliers with captive forging operations, and regional fabricators serving cost-sensitive emerging markets. Two dominant competitive moves are reshaping positioning: M&A activity targeting mechatronics capabilities and geographic expansion into Indian and Southeast Asian commercial vehicle corridors.
Among diversified conglomerates, JTEKT Corporation and ZF Friedrichshafen AG exemplify the integrated electronics-forging hybrid model. Nexteer Automotive Group Ltd. occupies a position within the specialized tier, representing suppliers whose focus on steering-specific expertise enables single-source accountability for OEM programs. These three companies anchor the competitive structure through their respective archetypes rather than through interchangeable commodity positioning.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive Group Ltd. |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| NSK Ltd. |
| Showa Corporation |
| Thyssenkrupp AG |
| Hyundai Mobis Co., Ltd. |
| Mando Corporation |
| Others |
Value Network & Pricing Analysis
Steer-by-wire technology migration is simultaneously compressing mechanical component counts and concentrating supply power among mechatronics-capable suppliers, reshaping both cost structures and procurement accountability across North American and European OEM programs.
Pricing Analysis
Volume concentration in fixed steel shafts for Indian commercial vehicles contrasts with margin capture in electronic steering shafts serving German premium OEMs. Three-tier pricing structure across premium electronic modules, standard collapsible shafts, and economy fixed shafts tracks certification burden and sensor integration density. Cost compression in aluminum-intensive variants is intensifying because LME futures volatility outpaces hedging coverage. Fleet procurement departments in the US Midwest exhibit lowest price sensitivity, prioritizing predictive maintenance telemetry and corrosion warranties over unit economics.
Supply Chain Analysis
ISO 26262 ASIL-D qualification gates filter supplier participation toward electronics-forging hybrid operations, concentrating viable production in Germany, Japan, and China. Raw material flows draw from hollow-drawn steel tubing mills, aluminum smelters tied to LME pricing, and carbon fiber prepreg specialists serving European electric sports car platforms. Single-source vulnerability runs through torque sensor and angle encoder suppliers concentrated in Japanese industrial corridors. Distribution runs through Tier-1 modular platform suppliers with single-source accountability for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic steering shaft architectures are displacing mechanical linkages, creating a technology-transition phase where sensor integration capabilities determine competitive viability.
For Market Incumbents: Anticipate margin compression in forged steel legacy portfolios as steer-by-wire penetration accelerates, prioritizing backward integration into torque sensor calibration and ECU interface development. Certification investment in ASIL-D testing infrastructure anchors defensibility against emerging mechatronics specialists. For New Entrants and Emerging Players: Sensor-first integration capabilities for Indian commercial vehicle fixed shaft programs offer the most penetrable white-space, leveraging PLI scheme localization incentives and BIS certification timelines that favor agile entrants. Direct OEM engagement through integrated forging-machining-sensor module proposals bypasses established Tier-1 gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with electronics-forging hybrid specialists given software-defined vehicle architecture proliferation across premium electric platforms. Five-to-ten year viability hinges on ASIL-D certification completion and OEM module integration contracts. The signal to watch is Tier-1 supplier consolidation announcements targeting sensor calibration capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Torque sensor and angle encoder alliances accelerate ASIL-D certification timelines for electronic shaft programs. |
| Aluminum Supply Agreement | Long-term offtake contracts with LME-hedged smelters stabilize input costs for lightweight shaft architectures. |
| Indian Manufacturing Footprint | Tamil Nadu and Maharashtra forging investments capture PLI-linked commercial vehicle demand under localized BIS compliance. |
| Software-Defined Vehicle Investment | ECU calibration and steer-by-wire interface development aligns with Stuttgart and Munich OEM platform roadmaps. |
| Predictive Maintenance Telemetry Launch | Corrosion monitoring and lifecycle analytics bundles address US Midwest fleet total-cost-of-ownership procurement criteria. |
Research Methodology
Trade databases, automotive production registries, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews across Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers. Bottom-up and top-down triangulation validated segment-level volume and value estimates.
Bottom-up modeling anchored forecasts, with top-down macroeconomic and regulatory scenario checks across the projection horizon. Segmentation dimensions included product type, vehicle class, propulsion architecture, material specification, and regional production cluster. CAGRs derived from fitted growth curves applied to baseline production volumes, with NHTSA mandate timelines and EPA fuel-economy credit valuations as key automotive-specific inputs.
Several conditions sit outside the modeled scope, including unannounced steer-by-wire platform cancellations, extreme aluminum price dislocations, and geopolitical trade restrictions affecting sensor component flows. Forecasts reflect documented assumptions on electrification penetration and regulatory compliance deadlines. A model refresh is warranted upon material change in NHTSA Federal Motor Vehicle Safety Standard implementation schedules or EPA Corporate Average Fuel Economy enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Car Diffuser Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Front Forks Market
Vehicle Components
RV Battery Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Global Tyre Inflators Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Cylindrical Roller Bearings Market