
 UAE Automotive Composites Market | 2026-2036
UAE Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Automotive Composites Market Analytics
MOHAP's vehicle safety and emissions protocols is decoupling legacy steel-intensive designs from new platform architectures across UAE assembly lines. Hexcel Corporation leverages its aerospace-grade carbon fiber heritage to anchor supply relationships with domestic EV startups. Toray Industries Inc competes through vertically integrated precursor-to-prepreg manufacturing that sustains cost discipline for high-volume structural programs. SGL Carbon specializes in thermoplastic composites for battery enclosure applications, occupying a niche where thermal management requirements dominate material selection criteria.
Automotive composites encompass engineered material systems combining polymer matrices with reinforcing fibers to achieve strength-to-weight ratios exceeding conventional metals, typically manufactured through resin transfer molding or automated fiber placement with fiber volume fractions between 50-65%. Their primary purpose centers on mass reduction for fuel efficiency gains and electric vehicle range extension without sacrificing crashworthiness. Carbon fiber commands premium positioning in structural parts where load-bearing performance justifies material cost, while glass fiber dominates exterior panels through cost-optimized compression molding cycles. Injection molding technology leads interior components volume due to cycle time advantages and geometric complexity tolerance.
The UAE's central automotive regulator MOHAP enforces conformity assessment procedures aligned with GCC Standardization Organization technical regulations, while the Emirates Authority for Standardization and Metrology (ESMA) governs material flammability and recyclability benchmarks for vehicle interior applications. These frameworks shape supplier qualification timelines and compel Tier-1 participants to maintain dual certification pathways. Stakeholders must monitor how Abu Dhabi's industrial free zone incentives interact with evolving carbon border adjustment mechanisms to determine optimal manufacturing footprint decisions.
Market Dynamics
MOHAP's tightening vehicle emissions framework is decoupling legacy steel-intensive architectures from new EV platform designs across UAE assembly lines. This regulatory pivot compresses supplier qualification timelines while elevating thermal management and crashworthiness standards for structural composites.
Growth Catalysts
- Abu Dhabi aerospace corridor:Composite engineering talent pools from adjacent aviation programs now overlap with automotive manufacturing, accelerating technology transfer into EV structural applications.
- ESMA interior flammability benchmarks:Updated material recyclability requirements for vehicle cabin applications are pulling thermoplastic composites into mainstream seating and dashboard programs.
- Resin transfer molding automation:Cycle time improvements in high-pressure RTM systems are reducing per-part costs for carbon fiber structural components below hand-layup thresholds.
Market Restraints
- Acrylonitrile price volatility:Precursor chemical costs for carbon fiber production fluctuate with global petrochemical feedstock markets, squeezing margin predictability for domestic converters.
- Prepreg import concentration:UAE manufacturers rely on narrow supply channels from European and Asian precursor suppliers, exposing production schedules to shipping lane disruptions.
- Thermoplastic welding limitations:Joining technologies for continuous fiber-reinforced thermoplastics remain immature versus thermoset adhesive bonding, constraining battery enclosure design freedom.
Strategic Opportunities
- Dubai luxury EV platforms:High-performance electric vehicle programs in Dubai's industrial zones prioritize carbon fiber body-in-white structures where material cost sensitivity is secondary to range extension.
- MOHAP-GCC alignment pathway:Convergence between UAE vehicle safety protocols and broader Gulf Cooperation Council standardization creates single-certification access across six regional markets.
- Automated fiber placement hybridization:Combining AFP with 3D-printed core structures enables lattice-reinforced composite designs for next-generation crash absorption systems.
Industry Challenges
- Multi-material joining certification:ESMA and MOHAP require separate validation protocols for steel-aluminum-composite hybrid structures, extending homologation timelines by 8-14 months.
- Out-of-autoclave process scale-up:Transitioning aerospace-qualified OOA curing methods to automotive volume production demands capital-intensive press and tooling investments with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Automotive Composites Market |
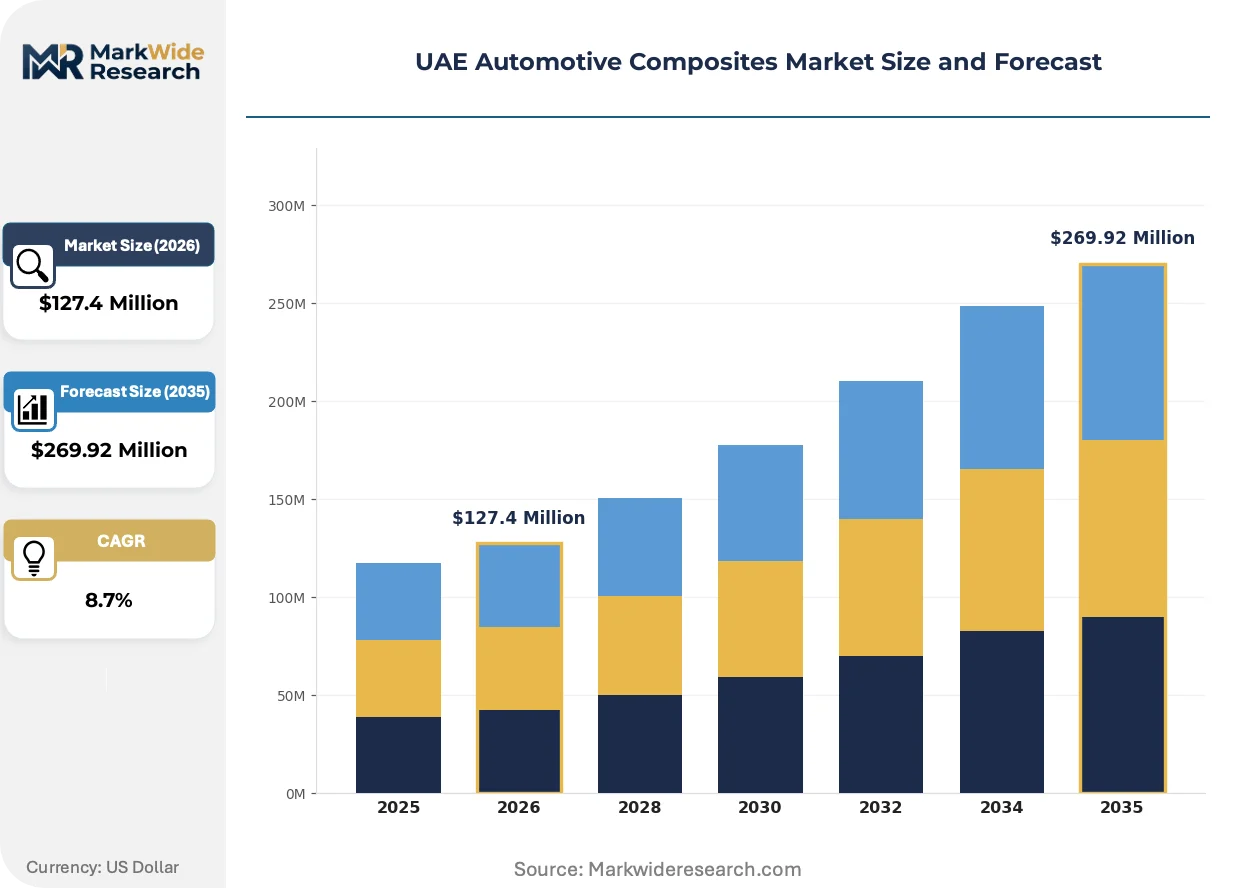
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $269.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Plastics, Carbon Fiber, Glass Fiber, Natural Fiber Application: Interior Components, Structural Parts, Exterior Panels, Electrical Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Compression Molding, Tape Laying, Hand Lay-Up |
| Companies Covered | Hexcel Corporation, Toray Industries Inc, SGL Carbon, Mitsubishi Chemical Carbon Fiber and Composites Inc, Toho Tenex, Teijin Limited, Owens Corning, Nippon Sheet Glass Company Limited, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Automotive Composites Market Evolving Landscape
Material-process combinations are compressing design-to-production cycles while regulatory stringency elevates performance verification requirements. Three developments are restructuring competitive positioning across the value chain.
Thermoplastic composites are consolidating their position in battery enclosure applications. SGL Carbon and domestic Tier-1 suppliers are qualifying continuous fiber-reinforced polypropylene and PEEK matrices for thermal runaway containment. This material shift is consolidating engineering workflows previously split between metals and thermosets into unified polymer platforms.
MOHAP's updated conformity assessment procedures now align with GCC Standardization Organization technical regulations. This harmonization reduces redundant testing for suppliers serving multiple Gulf markets. Domestic manufacturers are responding by consolidating certification documentation and pursuing single-audit qualification pathways.
Buyer concentration among Dubai and Abu Dhabi-based EV assemblers is compressing supplier negotiation leverage. Tier-2 composite converters now face direct sourcing pressure from OEMs seeking to capture margin previously retained by Tier-1 system integrators. This disintermediation is most visible in structural battery pack components where geometric complexity favors direct converter relationships.
UAE Automotive Composites Market Segmentation
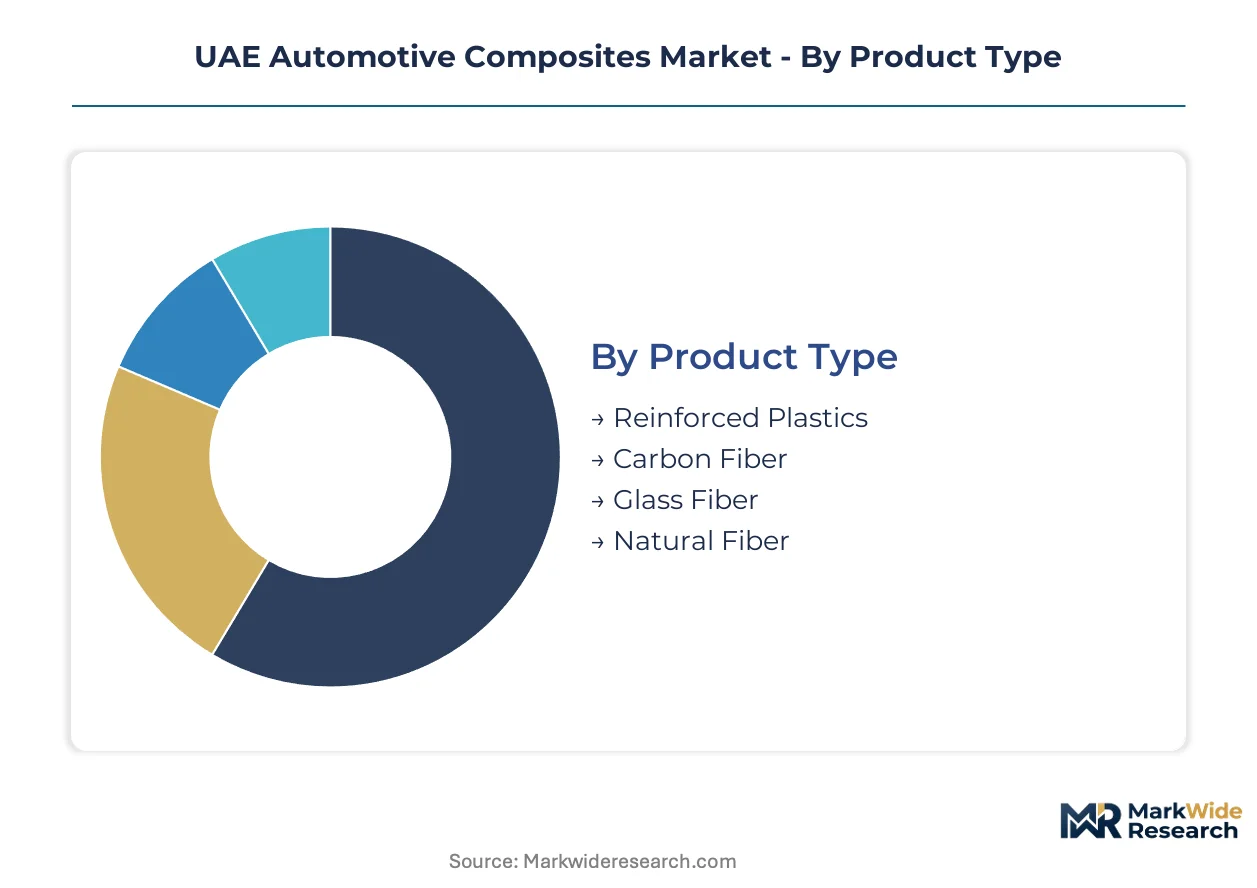
Composite material selection in the UAE automotive sector follows a strict hierarchy where performance requirements, regulatory compliance, and manufacturing scale intersect. Each segmentation dimension reveals distinct procurement patterns shaped by Dubai's luxury EV platforms and Abu Dhabi's aerospace-adjacent manufacturing corridors.
Product Type:
Volume applications favor cost-optimized glass formulations, while premium platforms absorb carbon fiber's material cost penalty for mass reduction gains.
- Reinforced Plastics:Thermoplastic matrices with short glass fiber reinforcement dominate interior component manufacturing through injection molding cycles under 60 seconds. Demand concentrates in dashboard carriers and door modules where ESMA flammability benchmarks favor halogen-free polypropylene formulations.
- Carbon Fiber:Continuous tow and fabric architectures achieve fiber volume fractions of 55-65% in epoxy or thermoplastic matrices for structural load-bearing applications. Dubai-based luxury EV assemblers specify carbon fiber body-in-white structures where range extension justifies material costs exceeding glass fiber alternatives by 8-12x.
- Glass Fiber:E-glass and S-glass rovings serve exterior panel applications through compression molding with SMC or BMC prepregs, balancing impact resistance against surface finish requirements.
- Natural Fiber:Flax and jute fiber reinforcements in bio-based matrices address emerging sustainability procurement criteria for non-structural interior trim where moisture sensitivity limits application scope.
Today's leader: Carbon fiber in structural applications. Tomorrow's challenger: Natural fiber as sustainability compliance tightens.
Application:
Functional requirements split procurement between crash-critical structural elements and aesthetic-driven exterior surfaces.
- Interior Components:Seating structures, instrument panels, and HVAC housings utilize glass-mat thermoplastics for complex geometries tolerating moderate mechanical loads. MOHAP occupant safety protocols drive material selection toward low-VOC emission polymers with controlled fogging characteristics.
- Structural Parts:B-pillars, floor pans, and crash absorption elements employ carbon fiber prepreg or RTM-processed fabrics where specific strength metrics exceed 300 MPa/(g/cm³). Abu Dhabi's aerospace corridor supplies qualified engineering talent for structural simulation and layup optimization.
- Exterior Panels:Hoods, fenders, and roof modules balance dent resistance against Class-A surface requirements through compression-molded SMC with optimized filler content.
- Electrical Systems:Battery enclosures and high-voltage component housings demand flame-retardant thermoplastic composites meeting UL94 V-0 ratings with thermal runaway containment capability.
Structural parts command premium pricing; interior components drive volume scale.
End User:
Procurement authority concentrates with vehicle assemblers while Tier-1 suppliers retain process integration expertise.
- OEMs:Original equipment manufacturers in Dubai's industrial free zones direct-source carbon fiber prepregs for proprietary EV platform architectures, bypassing traditional Tier-1 margins on critical structural components.
- Tier-1 Suppliers:System integrators manage multi-material joining validation for hybrid steel-aluminum-composite assemblies, absorbing ESMA and MOHAP homologation complexity on behalf of vehicle assemblers.
- Aftermarket Providers:Specialty converters serve performance vehicle modification segments with aesthetic carbon fiber upgrades where regulatory compliance requirements remain minimal.
- Vehicle Assemblers:Domestic manufacturing facilities in Abu Dhabi and Dubai coordinate just-in-sequence composite delivery from bonded logistics hubs within industrial free zones.
OEMs consolidate strategic material sourcing; Tier-1 suppliers defend value through certification management.
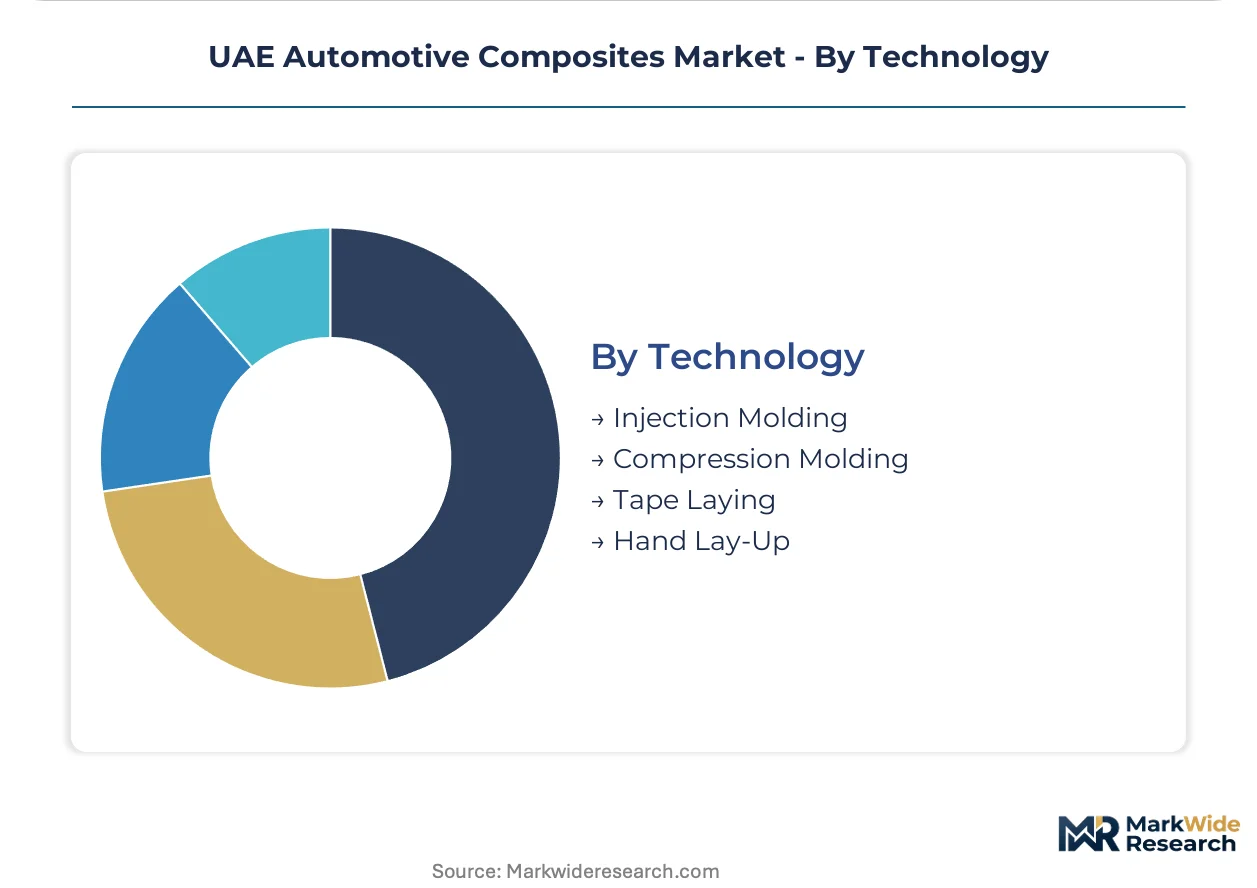
Technology:
Cycle time economics favor thermoplastic molding for high-volume programs while thermoset processes retain structural performance advantages.
- Injection Molding:Short-fiber reinforced thermoplastics achieve sub-90-second cycle times for complex interior geometries with ribbed structures and snap-fit features, dominating dashboard and door panel production.
- Compression Molding:Sheet molding compound and bulk molding compound processes produce exterior panels with integrated styling lines and paint-ready surfaces, serving both OEM and aftermarket channels.
- Tape Laying:Automated fiber placement of unidirectional thermoplastic tapes enables localized reinforcement in battery enclosure structures with weldable joining interfaces.
- Hand Lay-Up:Manual prepreg placement persists in low-volume luxury vehicle programs and prototype development where tooling investment recovery remains uncertain.
Injection molding owns volume leadership; tape laying gains share fastest in electrification applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Composite manufacturing in the UAE traces its industrial lineage to Abu Dhabi's aerospace investments during the 2000s, which established precursor supply chains and engineering talent pools now migrating into automotive applications. Dubai's luxury vehicle assembly platforms subsequently absorbed this technical infrastructure for electric vehicle programs.
Dubai
High-performance EV assemblers in Dubai's industrial free zones specify carbon fiber body-in-white structures where range extension justifies material cost premiums. ESMA's updated interior flammability benchmarks pull thermoplastic composites into seating and dashboard programs. The Dubai South logistics corridor coordinates just-in-sequence composite delivery from bonded hubs serving multiple OEM platforms.
Abu Dhabi
Aerospace-adjacent manufacturing corridors supply qualified engineering talent for structural simulation and layup optimization in automotive programs. MOHAP's vehicle safety protocols align with GCC Standardization Organization technical regulations, reducing redundant testing for suppliers. Khalifa Industrial Zone hosts automated fiber placement facilities transitioning from aviation to EV structural component production.
Sharjah
Tier-2 composite converters in Sharjah's industrial areas face direct sourcing pressure from OEMs seeking to capture margin previously retained by Tier-1 integrators. The emirate's logistics infrastructure supports resin transfer molding supply chains feeding Dubai and Abu Dhabi assembly lines. Sharjah's technical training institutes are expanding composite technician certification programs aligned with MOHAP workforce standards.
Northern Emirates
Ras Al Khaimah and Fujairah host glass fiber processing facilities serving cost-optimized exterior panel applications through compression molding with SMC prepregs. These emirates benefit from lower industrial land costs for high-volume thermoplastic compounding operations. MOHAP's emissions framework is accelerating facility upgrades to meet thermal management requirements for battery enclosure components.
UAE Automotive Composites Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material grade and certification complexity, with aerospace heritage suppliers commanding structural composite premiums while glass fiber converters compete on cycle time economics. The supplier base concentrates around three strategic archetypes: carbon fiber precursor specialists leveraging vertical control over acrylonitrile-to-tow conversion, thermoplastic compounders optimizing for injection molding cycle efficiency, and hybrid material integrators managing multi-material joining validation. Dominant competitive moves include backward integration into precursor production and strategic partnerships with Dubai-based EV assemblers for platform-exclusive supply agreements.
Among US-based material science conglomerates, Hexcel Corporation and Owens Corning occupy positions spanning carbon fiber and glass fiber portfolios respectively. Japanese industrial groups Toray Industries Inc, Teijin Limited, and Mitsubishi Chemical Carbon Fiber and Composites Inc exemplify the precursor-to-prepreg integrated archetype. German specialist SGL Carbon represents the thermoplastic composite niche where thermal management requirements dominate battery enclosure material selection.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries Inc |
| SGL Carbon |
| Mitsubishi Chemical Carbon Fiber and Composites Inc |
| Toho Tenex |
| Teijin Limited |
| Owens Corning |
| Nippon Sheet Glass Company Limited |
| Solvay |
| Others |
Value Network & Pricing Analysis
Carbon fiber premium tier divergence from glass fiber commodity tiers manifests in dual supply chain configurations across UAE automotive manufacturing. MOHAP's emissions framework compresses qualification timelines for aerospace-grade material pathways while ESMA flammability benchmarks sustain parallel thermoplastic compounder networks for interior volume programs.
Pricing Analysis
Three-tier pricing structure across aerospace-grade carbon fiber, automotive-qualified glass fiber, and commodity thermoplastic compounds governs procurement negotiations. Price differentiation rests on MOHAP certification tier and fiber volume fraction specifications. Cost compression in glass fiber SMC compounding is intensifying because Sharjah-based converters add press capacity. Tier-1 system integrators exhibit lowest price sensitivity; Tier-2 specialty converters face direct OEM sourcing pressure.
Supply Chain Analysis
Scrap carbon fiber recovery and prepreg remnant reprocessing flow through dedicated logistics channels serving Abu Dhabi's aerospace corridor. Primary precursor supply draws from Japan, Germany, and the United States. Acrylonitrile feedstock volatility and Red Sea shipping lane disruptions constitute persistent supply chain risk. Distribution runs through Dubai South bonded logistics hubs coordinating just-in-sequence delivery to assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
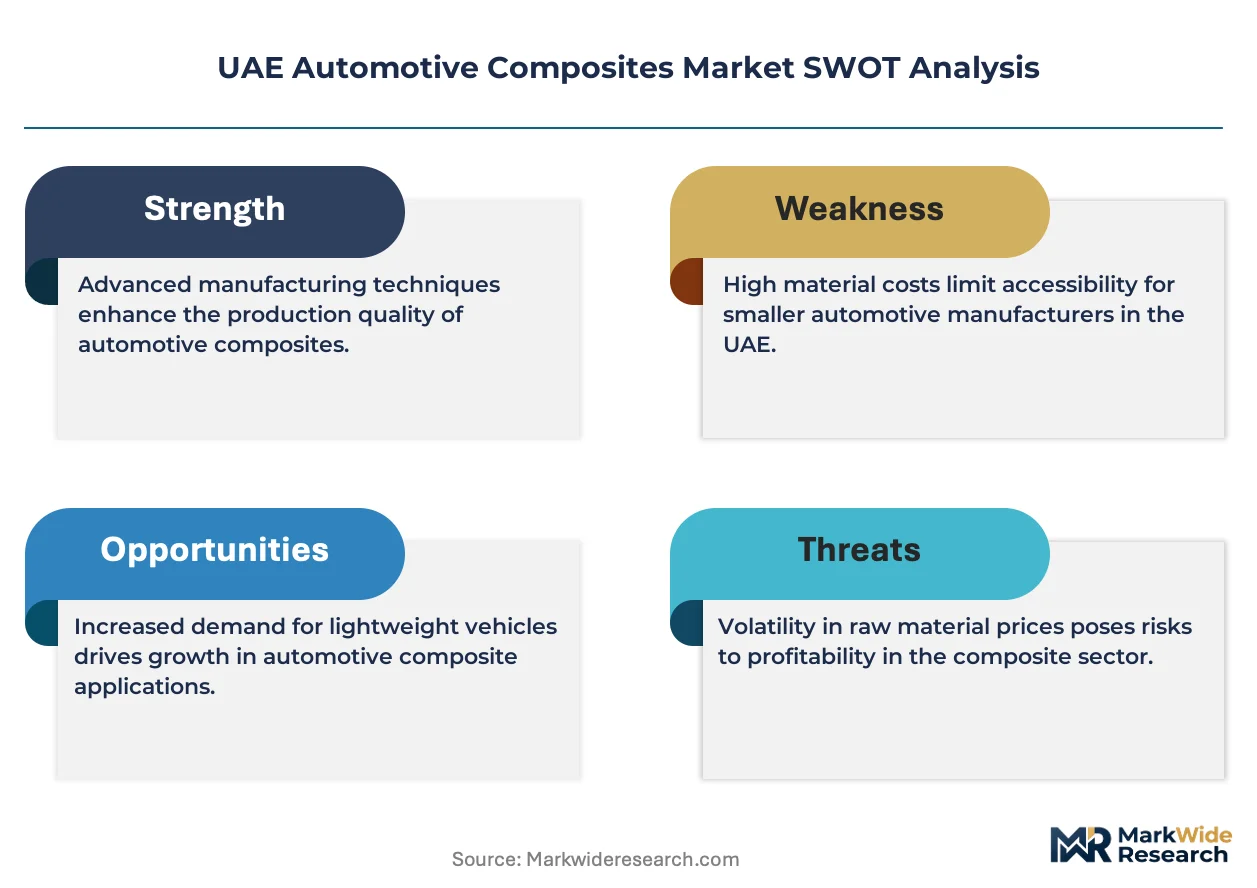
UAE automotive composites function as a stable compounder anchored by MOHAP's decoupling of legacy steel architectures from EV platform mandates. Regulatory stringency sustains predictable material substitution cycles across the projection horizon.
For Market Incumbents: Deepen backward integration into acrylonitrile precursor supply to offset petrochemical feedstock volatility. Secure platform-exclusive supply agreements with Dubai-based luxury EV assemblers before Tier-2 converter disintermediation accelerates. Invest in automated fiber placement capacity at Khalifa Industrial Zone to capture aerospace-to-automotive talent migration.
For New Entrants and Emerging Players: ESMA's updated interior flammability benchmarks in the UAE open a window for halogen-free polypropylene compounders to displace legacy formulations in seating and dashboard programs. Target Sharjah's Tier-2 converter segment where OEM direct sourcing pressure has weakened incumbent negotiation leverage. Qualify through MOHAP-GCC single-audit pathways to access six regional markets with one certification investment.
For Investors and Strategic Acquirers: Consolidation pressure builds where thermoplastic welding technology gaps constrain battery enclosure design freedom. The five-to-ten year viability window favors acquisition of automated fiber placement specialists with aerospace heritage transitioning to automotive volume production. Monitor MOHAP-GCC alignment progress as inflection indicator for regional market access scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile supply insulates margin from petrochemical volatility in UAE conversion operations. |
| MOHAP-GCC Single-Audit Qualification | Unified certification pathway reduces redundant testing costs across six Gulf Cooperation Council markets. |
| Automated Fiber Placement Capacity Expansion | Aerospace-qualified AFP systems transition to EV structural component production at Khalifa Industrial Zone. |
| Thermoplastic Composite Welding R&D Investment | Mature joining technologies unlock design freedom for continuous fiber-reinforced battery enclosures. |
| Platform-Exclusive Supply Agreement | Direct OEM relationships in Dubai industrial free zones capture margin previously retained by Tier-1 integrators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged Tier-1 supplier procurement directors, OEM platform engineers, composite converter operations managers, and MOHAP regulatory affairs specialists. Secondary validation drew from GCC Standardization Organization technical regulations, ESMA material flammability filings, customs trade data for carbon fiber precursor imports, and vehicle production databases. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Segment-weighted forecasting applied vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the analysis window. CAGRs derived from regression analysis against MOHAP regulatory phase-in schedules and EV platform launch timelines. Industry-specific inputs included fiber volume fraction adoption curves and resin transfer molding cycle time improvement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acrylonitrile price spike conditions or Red Sea logistics disruptions. Practitioners should monitor MOHAP-GCC harmonization progress and thermoplastic welding technology maturation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Heater Core Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
GCC Automotive Lubrication Services Market