
 Automotive Exhaust Silencer Market | 2026-2036
Automotive Exhaust Silencer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Silencer Market Analytics
Commercial vehicle applications is repositioning demand toward heavy-duty silencer configurations with higher thermal tolerance. Tenneco Inc. leverages its integrated exhaust aftertreatment platform to anchor North American OEM contracts. Forvia Faurecia sustains European market presence through advanced acoustic engineering capabilities. Eberspächer Group dominates commercial vehicle exhaust systems with specialized muffler architectures for diesel powertrains.
An automotive exhaust silencer is an acoustic attenuation device installed in vehicle exhaust systems, typically fabricated from 409-grade stainless steel or aluminized mild steel with internal baffle chambers, perforated tubes, and absorption packing to reduce sound pressure levels. Its primary industrial purpose is to attenuate combustion noise while managing backpressure to preserve engine performance and fuel efficiency. Absorption silencers lead the product type category due to superior broadband frequency attenuation in passenger vehicle applications, while reflective silencers retain strong positions in cost-sensitive commercial segments where narrow-band noise reduction suffices. Stainless steel commands the material segment on the strength of corrosion resistance and extended service life, whereas aluminum gains traction in lightweighting strategies for electric vehicle platforms.
The US EPA and NHTSA enforce noise emission limits that compel OEMs to certify exhaust systems against stationary and drive-by test protocols, while Euro 7 standards from the European Commission integrate noise limits with particulate and NOx thresholds. China's MIIT implements GB standards for vehicle noise that condition market access for domestic and imported exhaust components. Stakeholders must monitor regulatory divergence between acoustic and emission requirements as jurisdictions adopt divergent testing cycles that reshape product development priorities and certification costs.
Market Dynamics
Euro 7 emission and noise standards are compressing product development cycles while forcing acoustic and aftertreatment system convergence, fundamentally restructuring supplier-OEM technical relationships and certification burdens.
Growth Catalysts
- Heavy-duty fleet expansion:Commercial vehicle operators in Germany and China are retrofitting existing fleets with advanced noise-attenuation hardware to preempt municipal noise ordinances.
- GB standards enforcement:China's MIIT is tightening stationary noise test protocols, compelling domestic exhaust component manufacturers to upgrade acoustic engineering capabilities.
- Stainless steel thermal tolerance:409-grade material advances are extending service intervals in high-temperature diesel applications, reducing total cost of ownership for fleet managers.
Market Restraints
- Aluminum price volatility:Lightweighting strategies for electric vehicle platforms face input cost instability from London Metal Exchange aluminum contract fluctuations.
- Supplier concentration in Baden-Württemberg:German acoustic engineering clusters create geographic single-point vulnerability for European OEM just-in-sequence delivery.
- Backpressure-performance tradeoff:Stricter noise attenuation targets degrade engine breathing efficiency, forcing complex multi-chamber designs that raise manufacturing complexity.
Strategic Opportunities
- India commercial vehicle penetration:BIS noise certification requirements for Bharat Stage VI trucks create first-mover advantage for suppliers with localized thermal-acoustic testing facilities.
- Electric vehicle platform integration:Synthetic absorption materials are converging with thermal management systems in battery electric architectures, opening adjacent component markets.
- US IRA clean vehicle credits:Domestic content bonuses for North American-assembled exhaust aftertreatment systems are redirecting supplier capital toward Michigan and Ohio manufacturing bases.
Industry Challenges
- Acoustic simulation talent scarcity:Computational fluid dynamics and finite element analysis expertise for multi-physics exhaust modeling commands premium compensation in Stuttgart and Detroit labor markets.
- Euro 7 certification timeline compression:Simultaneous particulate, NOx, and noise homologation testing is extending validation cycles and straining OEM-supplier program management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Silencer Market |
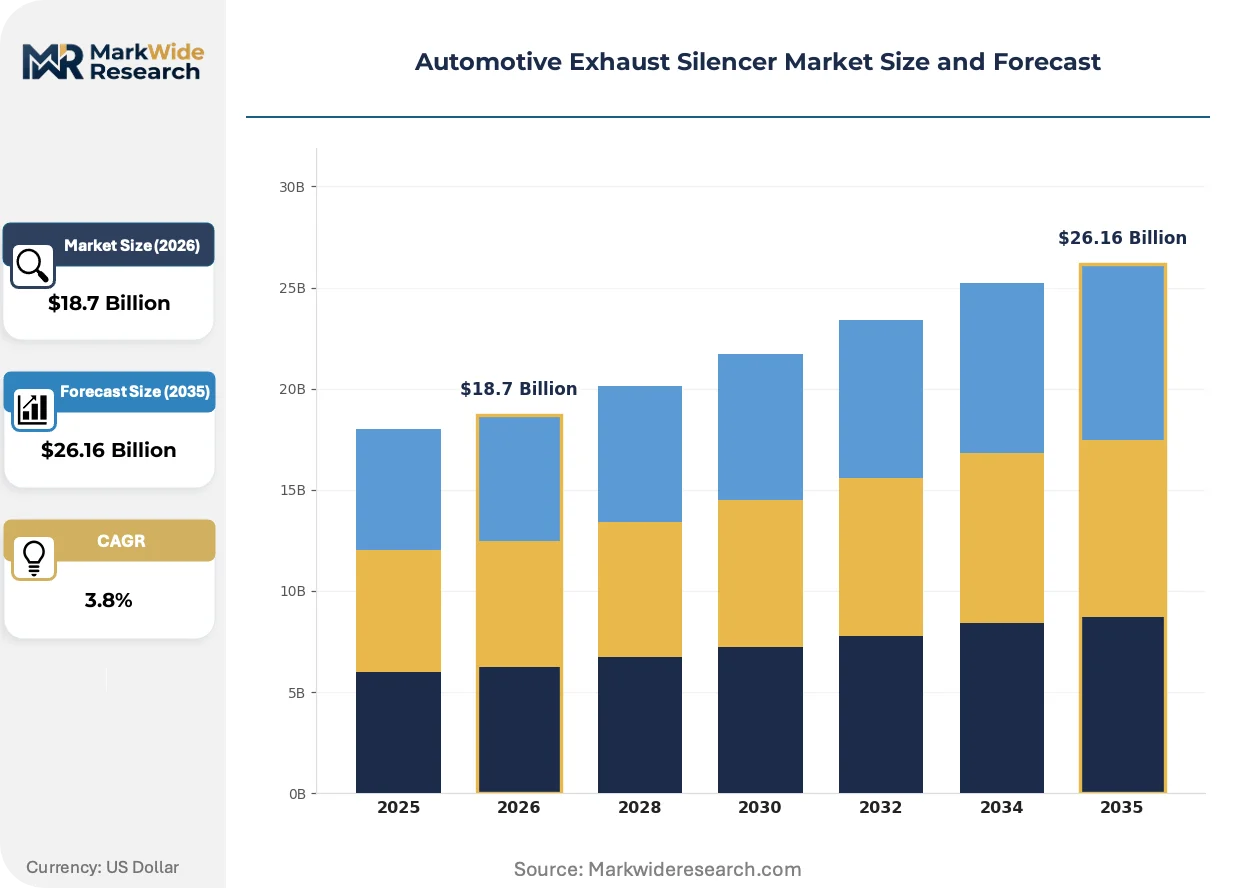
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorption Silencers, Reflective Silencers, Combination Silencers, Perforated Tubes Material: Stainless Steel, Aluminum, Mild Steel, Carbon Fiber End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks |
| Companies Covered | Tenneco Inc., Forvia Faurecia, Eberspächer Group, Bosal Group, Futaba Industrial Co., Ltd., BENTELER International, Calsonic Kansei Corporation, Katcon Global, Sharda Motor Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Silencer Market Evolving Landscape
Active noise cancellation hardware and predictive acoustic modeling are displacing passive baffle architectures, while material science advances enable thinner-walled, higher-temperature tolerant configurations that reduce mass without attenuation loss.
Micro-perforated panel absorbers are integrating broadband frequency cancellation across 500-4000 Hz ranges that dominate diesel combustion signatures. Heavy-duty truck manufacturers in the United States are adopting these panels for engine-aftertreatment packaging constraints. The technology is integrating thermal and acoustic functions into single-layer substrates that compress part count and assembly labor.
REACH chemical restrictions are banning certain fiberglass absorption packing formulations used in legacy muffler designs. European suppliers are reformulating with basalt fiber and aerogel composites to maintain acoustic performance. Passenger vehicle applications face the steepest reformulation costs due to volume scale and warranty exposure.
Fleet procurement departments are consolidating exhaust system suppliers to capture volume-scale acoustic engineering support and unified warranty handling. Direct OEM relationships are displacing tiered distribution for commercial vehicle segments above 7.5 tons gross vehicle weight. This concentration is most visible in German and US long-haul trucking operations where total cost of ownership modeling dominates sourcing decisions.
Automotive Exhaust Silencer Market Segmentation
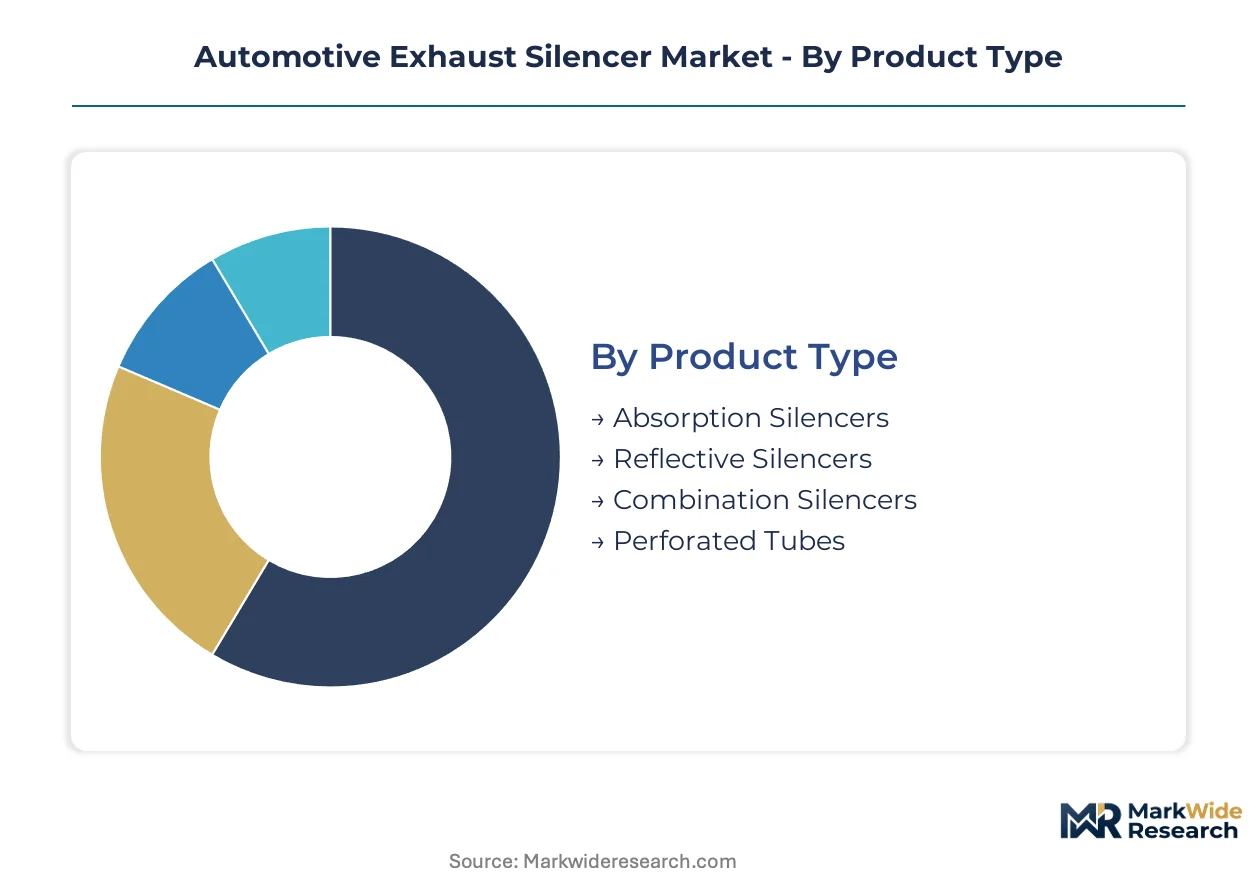
Exhaust silencer segmentation determines tooling investments, thermal testing protocols, and supply chain positioning across divergent acoustic engineering requirements. Material selection and product architecture choices cascade through manufacturing footprint decisions and OEM qualification timelines.
Product Type:
Capital intensity varies sharply across acoustic architectures, with active noise cancellation hardware demanding the steepest upfront R&D investment while passive baffle systems leverage mature stamping and welding equipment.
- Absorption Silencers:These devices employ porous packing materials—typically basalt fiber or stainless steel wool—within perforated chambers to dissipate acoustic energy across broadband frequencies. Passenger vehicle OEMs in Germany and the United States specify absorption designs for gasoline direct-injection powertrains where 500-4000 Hz combustion noise dominates cabin intrusion. Euro 7 noise limits are compressing development cycles for these configurations.
- Reflective Silencers:Expansion chambers and Helmholtz resonators create destructive interference through geometric tuning rather than porous media. Commercial vehicle fleet operators in China favor reflective architectures for diesel narrow-band attenuation where cost sensitivity outweighs broadband performance requirements. Simpler manufacturing tolerances reduce per-unit capital burden.
- Combination Silencers:Hybrid architectures merge absorption and reflective stages for tiered frequency targeting.
- Perforated Tubes:Single-element attenuators serve packaging-constrained applications in motorcycle and compact vehicle platforms.
Absorption silencers absorb the bulk of installed capacity; combination silencers are expanding most quickly as Euro 7 forces multi-physics integration.
Material:
Raw material selection governs thermal tolerance thresholds, corrosion warranty exposure, and weight-driven fuel economy compliance across divergent powertrain thermal profiles.
- Stainless Steel:409-grade ferritic alloys deliver oxidation resistance above 650°C in diesel aftertreatment proximity. German commercial vehicle manufacturers specify stainless architectures for 10-year corrosion warranties on long-haul tractors. Thermal cycling durability justifies 40-60% material cost premiums over aluminized alternatives.
- Aluminum:5xxx and 6xxx series extrusions enable 30-50% mass reduction for battery electric vehicle thermal-acoustic modules where exhaust gas temperatures are eliminated. Michigan-based OEMs are qualifying aluminum stampings for electric platform integration under US IRA domestic content incentives.
- Mild Steel:Aluminized coatings provide intermediate corrosion protection for cost-sensitive emerging market applications.
- Carbon Fiber:Thermoset composite shells serve motorsport and ultra-premium segments where mass minimization overrides unit economics.
Stainless steel commands the largest share of production volume; aluminum is climbing the fastest as electric vehicle architectures proliferate.
End User:
Customer type determines warranty liability structures, technical service requirements, and procurement consolidation patterns across divergent volume scales.
- OEMs:Original equipment manufacturers impose stringent acoustic validation protocols including 160-hour thermal aging and salt spray corrosion testing. Direct OEM relationships concentrate in Baden-Württemberg and Detroit engineering corridors where just-in-sequence delivery demands geographic proximity.
- Aftermarket Providers:Independent distributors and repair networks stock replacement mufflers for vehicle parc maintenance. China's MIIT enforcement of GB noise standards is expanding aftermarket upgrade demand for non-compliant legacy fleets.
- Vehicle Assemblers:Contract manufacturers without captive exhaust engineering rely on tiered supplier integration.
- Fleet Operators:Commercial vehicle owners above 50-unit scale negotiate direct acoustic engineering support and unified warranty handling.
OEMs absorb the bulk of installed capacity; fleet operators are gaining share fastest as procurement consolidation accelerates.
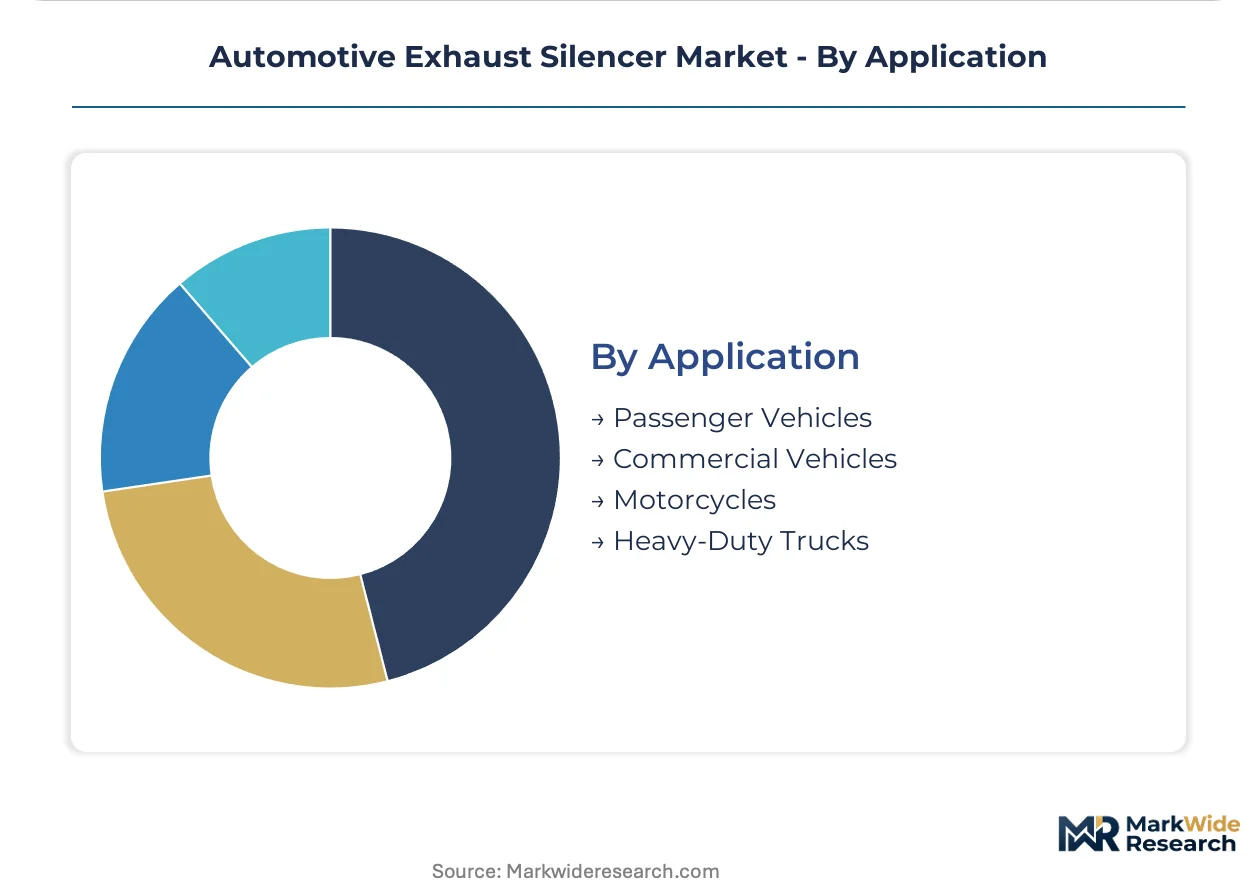
Application:
Thermal environment severity and packaging constraints fragment engineering requirements across vehicle mass classes and duty cycles.
- Commercial Vehicles:Heavy-duty diesel powertrains generate exhaust gas temperatures exceeding 600°C and acoustic signatures dominated by low-frequency combustion rumble. German fleet operators retrofit advanced attenuation hardware to preempt municipal noise ordinances in urban delivery zones. Thermal tolerance specifications exceed passenger vehicle requirements by 150-200°C.
- Passenger Vehicles:Gasoline and hybrid powertrains demand broadband attenuation across 500-4000 Hz with minimal backpressure penalty. US EPA drive-by noise protocols condition OEM specification sheets. Active noise cancellation integration is displacing passive architectures in premium segments.
- Motorcycles:Compact packaging and weight minimization drive perforated tube and short-path absorption designs.
- Heavy-Duty Trucks:Severe-duty applications above 15 tons gross vehicle weight require specialized multi-chamber architectures with thermal shielding.
Passenger vehicles absorb the bulk of installed capacity; commercial vehicles are expanding most quickly as fleet emission and noise regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive engineering corridor concentrates exhaust system R&D through Stuttgart-based acoustic simulation clusters. US IRA clean vehicle credits are redirecting supplier investment toward Michigan and Ohio manufacturing zones. China's MIIT enforcement of GB noise standards is reshaping procurement patterns across Asia-Pacific supply chains.
United States
Heavy-duty fleet operators retrofit advanced attenuation hardware to preempt municipal noise ordinances in urban delivery corridors. The EPA and NHTSA enforce stationary and drive-by test protocols that condition OEM certification requirements. Detroit engineering clusters anchor just-in-sequence delivery relationships with domestic manufacturers.
Germany
Commercial vehicle manufacturers specify 409-grade stainless architectures for extended corrosion warranties on long-haul tractors. Euro 7 standards from the European Commission integrate noise limits with particulate and NOx thresholds. Stuttgart labor markets command premium compensation for computational fluid dynamics expertise in multi-physics exhaust modeling.
China
Domestic exhaust component manufacturers upgrade acoustic engineering capabilities to meet tightening MIIT stationary noise test protocols. GB standards enforcement conditions market access for imported exhaust components. Yangtze River Delta manufacturing bases concentrate production capacity for both domestic OEMs and export markets.
India
BIS noise certification requirements for Bharat Stage VI trucks create procurement consolidation among fleet operators above 50-unit scale. The central bank's monetary policy framework influences commercial vehicle financing costs that cascade into aftermarket upgrade cycles. Maharashtra and Gujarat industrial corridors host localized thermal-acoustic testing facilities serving domestic OEMs.
Japan
Passenger vehicle OEMs specify broadband absorption designs for gasoline direct-injection powertrains where combustion noise dominates cabin intrusion. METI industrial policy supports lightweighting material advances in 5xxx and 6xxx series aluminum extrusions. Kanto and Kansai manufacturing regions concentrate stamping and welding equipment for mature baffle system production.
Automotive Exhaust Silencer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct OEM relationships concentrating in engineering corridors while aftermarket distribution retains tiered channel structures. The supplier base exhibits moderate consolidation around integrated exhaust aftertreatment platforms and specialized acoustic engineering capabilities. Three archetypes dominate: vertically integrated system integrators, standalone acoustic engineering specialists, and regional fabrication houses serving cost-sensitive fleet retrofit markets. Competitive dynamics center on M&A activity targeting thermal-acoustic testing capabilities and strategic partnerships for Euro 7 certification bandwidth.
Among North American-integrated system suppliers, Tenneco Inc. exemplifies the vertically integrated archetype through its captive aftertreatment platform. European specialists occupy distinct positioning, with Forvia Faurecia representing advanced acoustic engineering capabilities and Eberspächer Group anchoring commercial vehicle exhaust system concentration. These three entities collectively illustrate the geographic and technical segmentation that structures supplier-OEM negotiation leverage across divergent regulatory jurisdictions.
| Leading Market Players |
|---|
| Tenneco Inc. |
| Forvia Faurecia |
| Eberspächer Group |
| Bosal Group |
| Futaba Industrial Co., Ltd. |
| BENTELER International |
| Calsonic Kansei Corporation |
| Katcon Global |
| Sharda Motor Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Active noise cancellation hardware adoption simultaneously compresses per-unit manufacturing economics and concentrates supplier bargaining power among acoustic engineering specialists with multi-physics simulation capabilities. Euro 7 certification burdens force OEMs toward direct contracting relationships that bypass tiered distribution markups, while raw material volatility in aluminum and specialty alloys feeds back into contract restructuring.
Pricing Analysis
Short lead-time premiums of 15-25% apply to just-in-sequence contracts with Baden-Württemberg engineering clusters, while spot inventory from regional fabrication houses trades at discounts. Three-tier pricing structure across premium, standard, and economy levels differentiates by thermal tolerance certification and corrosion warranty duration. Pricing pressure stems from fleet procurement consolidation above 50-unit scale. Aftermarket retrofit segments exhibit highest price sensitivity; OEM direct contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with 409-grade stainless steel feedstock concentrated in German and Chinese mill operations. Raw material flows draw from nickel-chromium alloy suppliers in South Africa, ferritic steel producers in Germany, and aluminum smelters in China. Tariff exposure on specialty alloys creates margin compression risk. Distribution runs through just-in-sequence pipelines to Stuttgart and Detroit assembly corridors, with aftermarket channels serving fragmented repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic simulation talent scarcity props pricing power for suppliers with captive CFD capabilities, constraining capacity expansion across the analysis window.
For Market Incumbents: Anchor Euro 7 certification bandwidth through backward integration into thermal-acoustic testing facilities in Michigan and Baden-Württemberg. Consolidate aftermarket distribution to capture fleet procurement consolidation above 50-unit scale. Defend against reflective silencer commoditization by locking OEM platform engineering relationships. For New Entrants and Emerging Players: Predictive acoustic modeling software offers a technology-first wedge into Tier 2 supplier relationships underserved by incumbent engineering support. Target India's Bharat Stage VI retrofit market where localized testing infrastructure remains underdeveloped. Pursue direct fleet operator contracts bypassing OEM qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated aftertreatment platforms seeking acoustic engineering capabilities. Five-to-ten-year viability favors suppliers with Euro 7 homologation bandwidth and IRA domestic content positioning. Watch MIIT enforcement intensity in China as inflection indicator for Asia-Pacific supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal-Acoustic Testing | Captive CFD capabilities reduce Euro 7 certification cycle times for OEM contracts. |
| Geographic Manufacturing Footprint Expansion | Michigan and Ohio facilities qualify for US IRA domestic content bonus structures. |
| Platform Standardization Across Vehicle Classes | Modular silencer architectures amortize R&D across passenger and commercial segments. |
| Long-term Supply Agreement with Stainless Mills | 409-grade alloy price hedging insulates against nickel-chromium volatility. |
| Acquisition of Basalt Fiber Formulation Specialist | REACH-compliant absorption materials replace banned fiberglass packing formulations. |
Research Methodology
Vehicle production databases, IHS Markit registration data, and SEC filings from Tier 1 suppliers formed the secondary backbone of this analysis. Primary interviews with OEM platform engineers, aftermarket distributor procurement heads, and thermal-acoustic testing facility operators combined with bottom-up and top-down triangulation. Secondary validation drew from customs records, Euro 7 regulatory drafts, and MIIT enforcement bulletins.
Bottom-up modeling anchored volume projections to vehicle class and propulsion architecture segmentation, while top-down cross-checks referenced aggregate automotive exhaust system spend patterns. Growth rates derived from elasticity analysis across regulatory compliance cycles, material substitution trends, and fleet replacement dynamics. Forecast inputs incorporated Euro 7 timeline uncertainty and aluminum price volatility assumptions.
Several conditions sit outside the modeled scope, including pre-emption of passive silencer architectures by full electric vehicle adoption and divergence between acoustic and emission regulatory timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Radiator Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Automotive Door Module Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market