
 Automotive Steering Wheel Market | 2026-2036
Automotive Steering Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steering Wheel Market Analysis
The capital-intensity divergence between full-system integrators and component specialists is collapsing as module consolidation accelerates. Nexteer Automotive Group leverages its vertically aligned manufacturing footprint to sustain cost discipline across North American and Asian plants. ZF Friedrichshafen AG anchors its position through advanced driver-assistance system integration within steering wheel architectures. JTEKT Corporation differentiates via precision torque-sensor technology that competes directly with European module suppliers.
An automotive steering wheel is a circular control interface mechanically or electronically linked to a vehicle's steering system, typically constructed from magnesium or aluminum armatures overmolded with polyurethane foam and finished in leather, vinyl, or synthetic substrates. Its primary function transmits driver directional input to the road wheels while housing airbag modules, control switches, and heating elements in modern configurations. Multifunctional feature integration leads segment value pools as haptic feedback and capacitive touch interfaces displace conventional button arrays. Heated steering wheels represent the fastest-growing product type in cold-climate markets where consumer willingness-to-pay for thermal comfort has hardened. Leather material grades retain premium positioning despite vinyl and synthetic alternatives gaining share in mass-market electric vehicle platforms.
NHTSA Federal Motor Vehicle Safety Standards govern airbag deployment integrity and steering column intrusion resistance in the United States, while ECE R12 and ECE R94 regulations in Europe mandate comparable occupant protection criteria. REACH compliance and RoHS substance restrictions constrain adhesive, coating, and polymer selections across export-bound production lines. Stakeholders must monitor pending software-defined vehicle protocols that will determine whether steering wheels evolve into detachable computing peripherals or persist as fixed mechanical anchors in partially automated driving architectures.
Market Dynamics
Module consolidation is collapsing the traditional boundary between full-system integrators and component specialists, forcing steering wheel suppliers to absorb sensor, heating, and haptic functions previously sourced separately.
Growth Catalysts
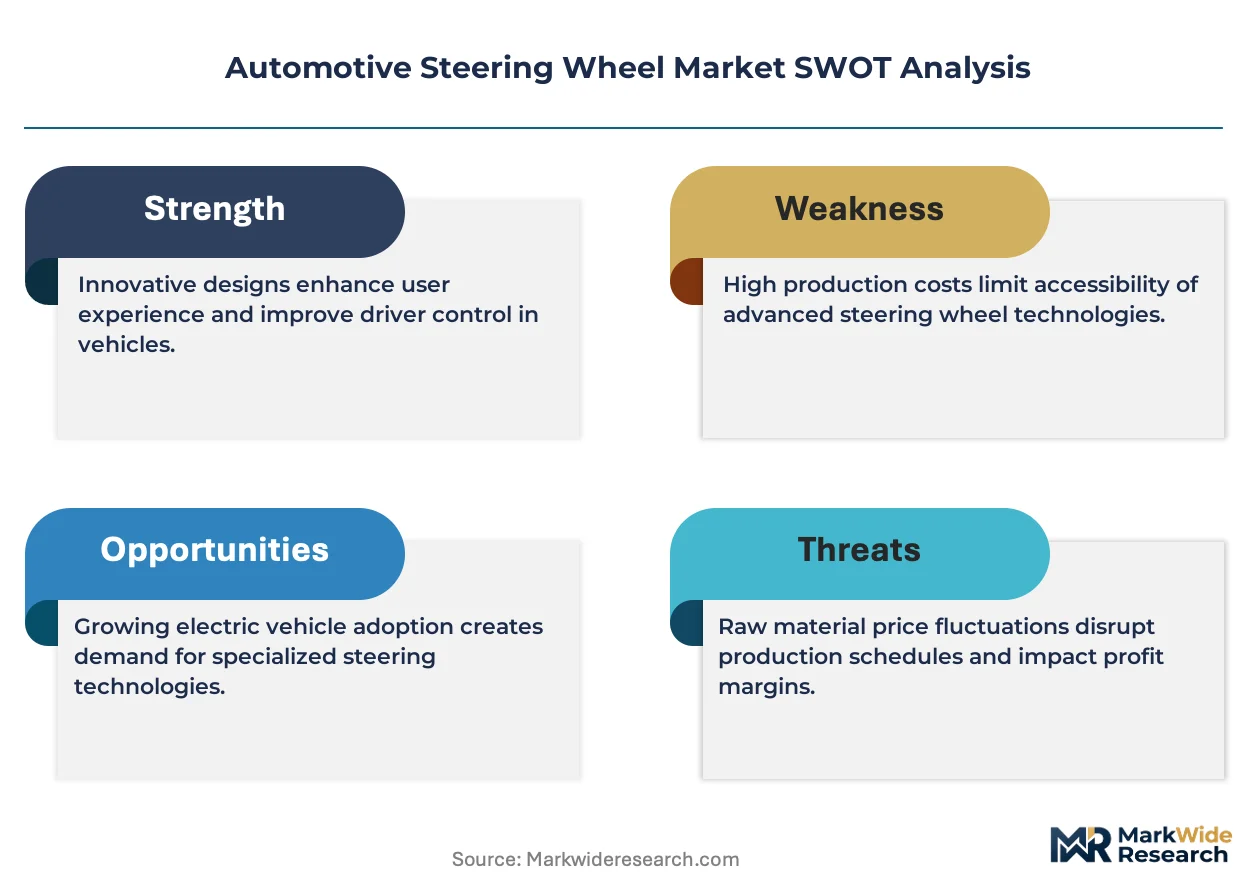
- EU Safety Mandates:ECE R12 and ECE R94 regulations mandate stricter occupant protection criteria, compelling OEMs to upgrade steering wheel structural integrity and airbag integration.
- Magnesium Armature Demand:Lightweight magnesium core constructions reduce unsprung mass in electric vehicle platforms, aligning with dual carbon goals in China and Europe.
- Cold-Climate Comfort Premium:Heated steering wheels command sustained willingness-to-pay in Germany, Canada, and Nordic markets where thermal comfort features drive option penetration.
Market Restraints
- Polyurethane Feedstock Volatility:Foam overmolding relies on isocyanate and polyol inputs subject to petrochemical price swings and REACH substance scrutiny.
- Airbag Module Supply Concentration:Three suppliers control over 80% of pyrotechnic inflator capacity, creating single-source vulnerability for tier-one steering wheel assemblers.
- Capacitive Touch Reliability Limits:Haptic feedback interfaces face field failure rates higher than mechanical switches, complicating warranty exposure for premium segment suppliers.
Strategic Opportunities
- Detachable Steering Wheel Architectures:Software-defined vehicle protocols may legitimize removable wheel designs for autonomous modes, opening aftermarket and fleet retrofit channels.
- India Premium EV Penetration:PLI scheme incentives for electric vehicle manufacturing are drawing steering wheel suppliers to establish local foam-overmolding and leather-wrapping operations.
- Biometric Sensor Convergence:Integration of heart-rate and grip-pressure monitoring into wheel rims creates new data service revenue streams for health and driver monitoring applications.
Industry Challenges
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance for torque-sensor-integrated wheels extends development timelines by 14-18 months.
- Legacy Platform Integration Friction:Retrofitting heated and multifunctional wheels into carryover vehicle architectures requires column and wiring harness redesigns that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Wheel Market |
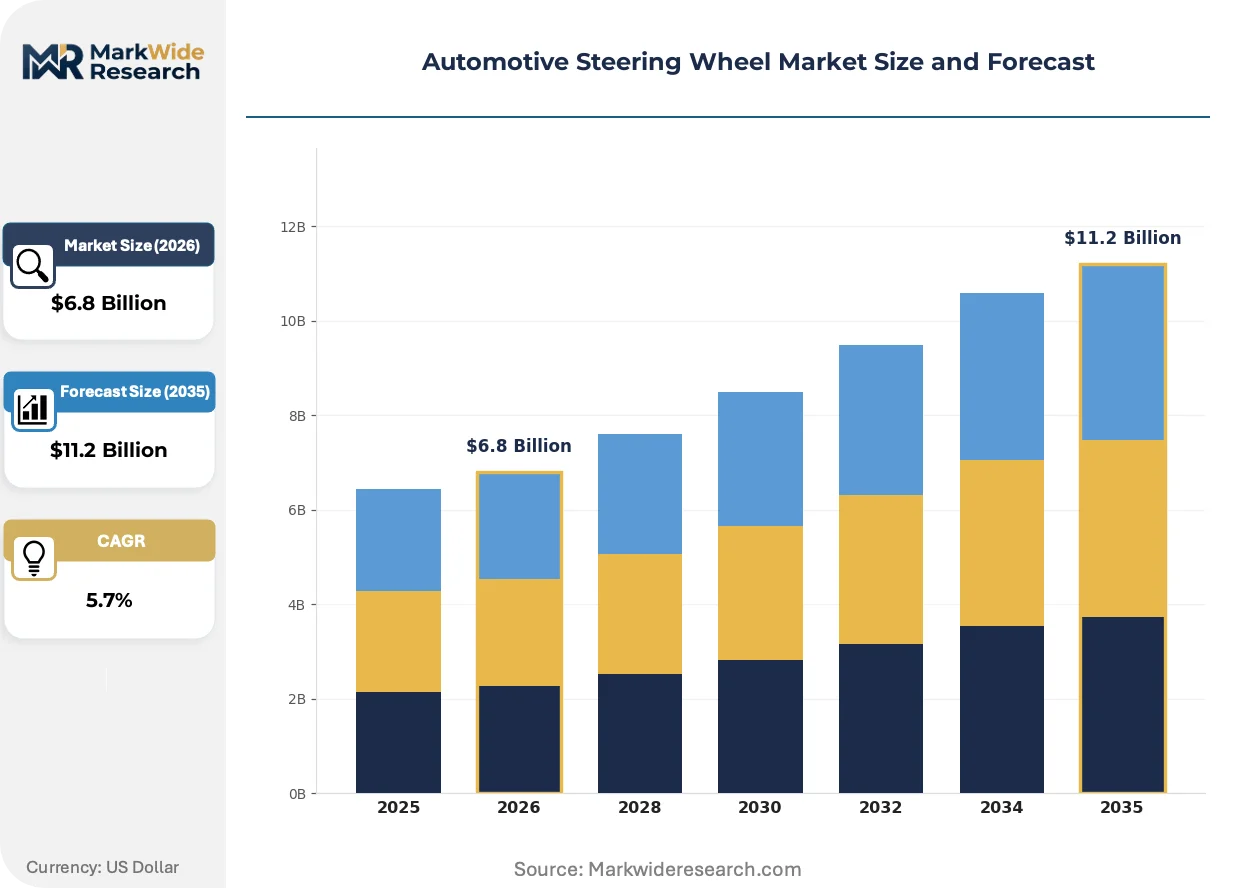
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Sports, Luxury, Heated Material: Leather, Vinyl, Wood, Plastic Feature: Multifunctional, Tilt, Adjustable, Ergonomic End User: OEMs, Aftermarket Suppliers, Automotive Manufacturers, Exporters |
| Companies Covered | Nexteer Automotive Group, JTEKT Corporation, ZF Friedrichshafen AG, Continental AG, Robert Bosch GmbH, Autoliv Inc., Joyson Safety Systems, Valeo SA, Toyoda Gosei Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Wheel Market Emerging Trajectories
Capacitive sensing and solid-state haptics are compressing control surface area while expanding input vocabulary, forcing a fundamental redesign of how drivers interact with vehicle systems through the steering wheel interface.
Solid-state haptic actuators are miniaturizing beneath leather and synthetic substrates to deliver localized vibration feedback without mechanical button travel. Electric vehicle OEMs in Germany and California are specifying these interfaces for level-two and level-three automated driving hand-off alerts. The technology is miniaturizing formerly discrete switch modules into continuous surface topologies that reduce part count and assembly labor.
REACH substance restrictions and RoHS compliance are eliminating legacy adhesive chemistries and chrome-plated decorative elements from export-bound production lines. European suppliers have reformulated polyurethane foam systems to exclude restricted isocyanate variants ahead of 2025 enforcement windows. Leather tanning operations face parallel pressure to substitute chromium-based processes with vegetable alternatives, particularly for wheels destined for EU and Nordic markets.
Fleet procurement of steering wheels is unbundling from complete vehicle orders as rental and mobility-as-a-service operators negotiate separate wear-item replacement schedules. Tier-one suppliers now maintain dedicated fleet SKU catalogs with accelerated availability commitments and consolidated logistics to centralized refurbishment hubs. This pattern is most pronounced in the United States and United Kingdom where large fleet operators command sufficient volume to justify direct supplier relationships.
Automotive Steering Wheel Market Segmentation
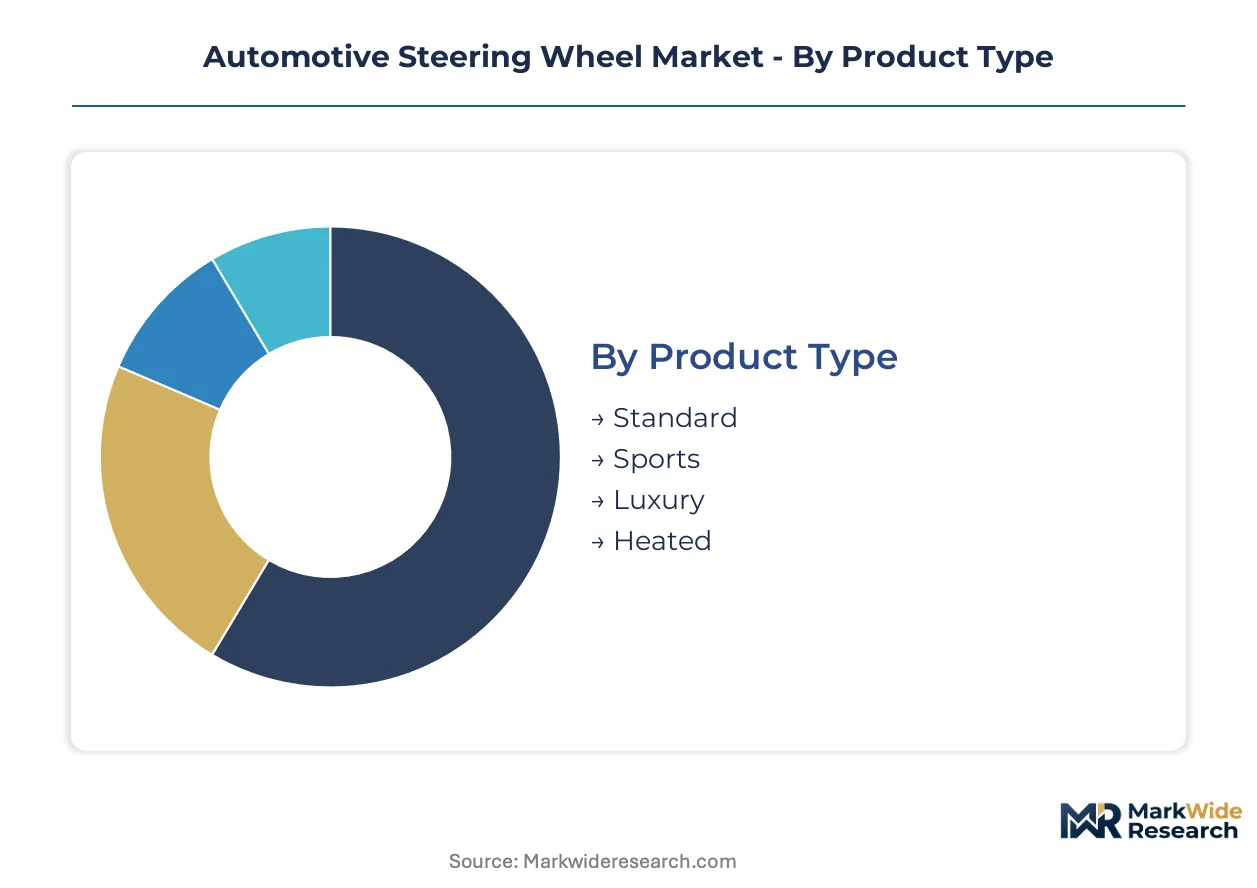
Steering wheel procurement channels diverge sharply across product tiers, with OEM direct sourcing dominating premium configurations while aftermarket distributors capture replacement volume for standard and wear-intensive variants. Material and feature specifications determine margin structures, creating distinct competitive arenas for integrated system suppliers versus component specialists.
Product Type:
Channel mix splits between OEM captive production for luxury and heated variants and tier-one supplier integration for standard and sports wheels bound for volume vehicle platforms.
- Standard:Polyurethane foam-overmagnesium construction serves mass-market ICE and entry EV platforms where cost discipline overrides feature density. Procurement concentrates through tier-one integrators supplying assembly plants in Germany, China, and the United States with 48-hour dock-to-line commitments.
- Heated:Resistive element integration beneath leather or synthetic substrates commands premium positioning in cold-climate markets. Demand clusters in Canada, Germany, and Nordic countries where thermal comfort features drive option penetration rates above temperate-market baselines.
- Sports:Flat-bottom rim profiles with enhanced grip geometry target performance vehicle segments. Thicker rim sections and contrast stitching differentiate cabin aesthetics for German and Italian premium OEMs.
- Luxury:Hand-wrapped leather with wood or metal inlay finishes serves flagship sedan and SUV configurations. Small-batch production runs through specialized trim shops maintain craftsmanship positioning.
Standard wheels dominate installed base. Heated configurations are where expansion concentrates.
Material:
Cost tiering separates premium natural substrates from synthetic alternatives gaining share in mass-market EV cost-down programs.
- Leather:Full-grain and Nappa grades retain premium positioning despite REACH pressure on chromium tanning processes. German and Italian OEMs specify vegetable-tanned alternatives for EU-bound production to satisfy substance restrictions.
- Vinyl:Thermoplastic polyolefin formulations displace leather in entry and mid-range EV platforms where durability and cleanability outweigh tactile authenticity. Chinese OEMs have accelerated vinyl adoption across domestic-market electric vehicle lines.
- Wood:Veneer and solid wood rim inserts serve ultra-premium configurations with heritage brand positioning. Limited to low-volume flagship production due to supply chain fragility and moisture sensitivity.
- Plastic:Injection-molded structural substrates form armature foundations beneath foam and finish layers. Cost minimization in emerging-market vehicle platforms drives specification of visible-grade plastics with textured finishes.
Leather commands price premiums at the top tier. Vinyl is climbing the fastest as EV platform cost engineering intensifies.
Feature:
Application-specific bundling determines which feature combinations flow through integrated module suppliers versus standalone component channels.
- Multifunctional:Capacitive touch surfaces and haptic feedback actuators consolidate HVAC, audio, and ADAS controls into rim-mounted interfaces. German OEMs specify these for Level 2 and Level 3 automated driving hand-off protocols.
- Tilt:Manual and powered column adjustment mechanisms accommodate driver ergonomics across vehicle classes. Universal fitment in North American and European markets where driving position customization is expected.
- Adjustable:Telescoping reach and rake modifications serve shared-vehicle and fleet applications where driver anthropometry varies widely. Rental operators in the United States negotiate accelerated replacement schedules for high-wear adjustable mechanisms.
- Ergonomic:Contoured rim profiles with thumb rests and palm swells reduce fatigue in long-haul commercial and luxury touring applications. Commercial vehicle OEMs in Germany specify ergonomic designs for heavy-duty truck platforms.
Multifunctional integration dominates technology roadmaps. Ergonomic specialization shows steepest expansion trajectory in commercial vehicle segments.
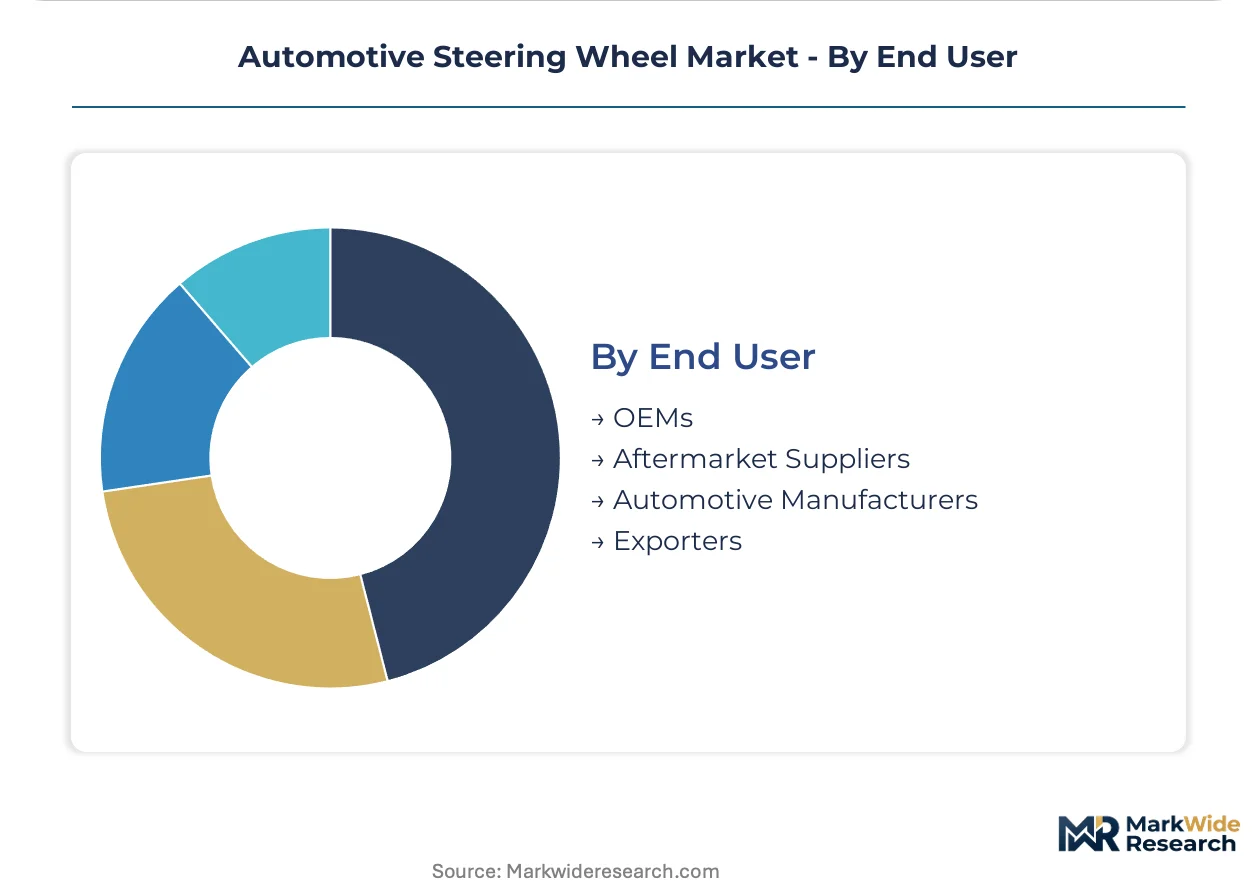
End User:
Customer type dictates contract structures, with automotive manufacturers and OEMs locking in multi-year supply agreements while aftermarket suppliers and exporters navigate spot-market and refurbishment economics.
- OEMs:Original equipment manufacturers specify complete steering wheel modules with integrated airbag, heating, and control electronics. Long-term agreements with tier-one suppliers like ZF and Nexteer anchor procurement for high-volume vehicle programs.
- Automotive Manufacturers:Vehicle assembly operations source steering wheels as part of complete interior module kits. Just-in-time delivery requirements favor suppliers with proximate manufacturing footprints in Germany, China, and the United States.
- Aftermarket Suppliers:Independent distributors serve collision repair, customization, and wear-item replacement demand. United States and United Kingdom fleet operators negotiate direct relationships for consolidated refurbishment hub supply.
- Exporters:Cross-border traders move steering wheels as knock-down kits or finished goods to markets with limited local production. REACH and RoHS compliance documentation requirements constrain adhesive and coating selections for EU-bound shipments.
OEMs and automotive manufacturers control volume procurement. Aftermarket channels are where margin expansion concentrates as fleet unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and the United States consume steering wheels through divergent channel structures, with German OEMs favoring integrated module sourcing, Chinese electric vehicle platforms driving heated-feature penetration, and US fleet operators pioneering unbundled procurement from complete vehicle orders.
United States
Detroit Three automakers specify multifunctional steering wheels with capacitive touch interfaces for Level 2 automated driving systems. NHTSA Federal Motor Vehicle Safety Standards govern airbag deployment integrity and steering column intrusion resistance. Michigan and Ohio assembly clusters anchor procurement volumes through tier-one suppliers with 48-hour dock-to-line commitments.
Germany
Premium OEMs in Stuttgart and Munich source heated and haptic-feedback steering wheels for flagship electric vehicle platforms. ECE R12 and ECE R94 regulations mandate stricter occupant protection criteria and structural integrity standards. Bavarian and Baden-Württemberg manufacturing corridors concentrate module integration facilities serving domestic and export-bound production.
China
Domestic electric vehicle OEMs accelerate orders for magnesium-armature steering wheels to reduce unsprung mass and satisfy dual carbon goals. MIIT and GB standards govern vehicle safety system integration and material specifications. Yangtze River Delta and Pearl River Delta industrial clusters host foam-overmolding and leather-wrapping operations for both local brands and joint-venture partners.
Japan
Precision torque-sensor technology drives steering wheel specification for hybrid and battery-electric platforms targeting domestic and export markets. METI industrial policy supports advanced driver-assistance system component development. Kanto and Chubu manufacturing regions maintain specialized production of ergonomic rim profiles for commercial vehicle and luxury touring applications.
India
PLI scheme incentives for electric vehicle manufacturing draw steering wheel suppliers to establish local foam-overmolding capabilities. BIS standards constrain material selections for adhesive and polymer components in export-bound production. Maharashtra and Gujarat automotive corridors concentrate emerging procurement volumes as premium EV penetration accelerates.
Automotive Steering Wheel Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-system integrators absorbing sensor, heating, and haptic functions previously sourced separately. The capital-intensity divergence between these tiers is collapsing as module consolidation accelerates and tier-one suppliers expand captive production of formerly discrete components. Three strategic archetypes dominate: vertically aligned manufacturing specialists, ADAS-integrated module suppliers, and precision sensor technology providers. Competitive moves center on backward integration into magnesium armature casting and strategic partnerships with electric vehicle OEMs for platform-specific designs.
Among integrated system suppliers, Nexteer Automotive Group, ZF Friedrichshafen AG, and JTEKT Corporation occupy positions that exemplify the three dominant competitive vectors. Nexteer represents the vertically aligned manufacturing archetype with proximate plant footprints. ZF anchors the ADAS-integration tier through steering wheel architectures that consolidate control electronics. JTEKT sits within the precision technology tier, competing directly with European module suppliers on torque-sensor specifications.
| Leading Market Players |
|---|
| Nexteer Automotive Group |
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| Robert Bosch GmbH |
| Autoliv Inc. |
| Joyson Safety Systems |
| Valeo SA |
| Toyoda Gosei Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Forty-eight-hour dock-to-line commitments from tier-one suppliers to Michigan and Ohio assembly clusters concentrate pricing power among integrated module producers with proximate manufacturing footprints. This lead-time compression favors buyers with multi-year offtake agreements while spot-market purchasers absorb volatility from polyurethane feedstock swings.
Pricing Analysis
Long-term offtake contracts anchor procurement for German and US OEMs, with three-tier pricing structure across premium, standard, and economy levels reflecting leather grade, magnesium armature specification, and ADAS integration depth. Price differentiation hinges on ISO 26262 certification tier and regional delivery cost from Yangtze River Delta production hubs. Cost compression in vinyl-wrapped mass-market configurations is intensifying because Chinese EV platforms prioritize cleanability over tactile authenticity. Fleet operators in the United States demonstrate highest price sensitivity through unbundled refurbishment hub negotiations, while luxury OEMs in Stuttgart show least sensitivity to premium leather grades.
Supply Chain Analysis
Pyrotechnic inflator capacity concentration among three suppliers creates single-source vulnerability for tier-one steering wheel assemblers sourcing across Germany, China, and Mexico. Magnesium armature casting draws from Qinghai smelter output, isocyanate foam precursors rest on petrochemical complexes in the US Gulf Coast, and Nappa leather feeds from Italian tanneries facing REACH substance restrictions. Tariff exposure on magnesium imports from China threatens cost structures for North American EV platforms. Distribution runs through tier-one integrators with captive airbag module integration and direct OEM dock-to-line logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet refurbishment services and biometric data monetization layers are expanding faster than hardware replacement cycles, positioning the steering wheel as a recurring-revenue anchor rather than a one-time component sale.
For Market Incumbents: Secure backward integration into magnesium armature casting to offset feedstock volatility, and lock in multi-year heated-wheel supply agreements with Yangtze River Delta EV producers before local competitors achieve scale. Capacitive touch reliability failures represent the primary warranty exposure threatening margin stability. For New Entrants and Emerging Players: ISO 26262 ASIL-D certification fast-track opens procurement channels with German premium OEMs specifying torque-sensor-integrated wheels for Level 3 automated driving platforms. India premium EV penetration under PLI incentives offers the most penetrable geography, with local foam-overmolding partnerships as the essential go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a module consolidation play because tier-one suppliers are absorbing sensor, heating, and haptic functions previously sourced separately, collapsing capital-intensity divergence between full-system integrators and component specialists. Target precision torque-sensor technology providers with established OEM validation. The signal to watch is software-defined vehicle protocol finalization determining detachable versus fixed steering wheel architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering bandwidth strain from legacy vehicle architecture retrofits. |
| Battery Supply Agreement | Aligns magnesium armature demand with dual carbon goals in Chinese EV production. |
| Software-Defined Vehicle Investment | Determines whether steering wheels evolve into detachable computing peripherals. |
| Geographic Manufacturing Footprint | Proximity to Germany, China, and US assembly clusters compresses dock-to-line lead times. |
| Charging Infrastructure Partnership | Less relevant for steering wheel suppliers; substitute with Biometric Sensor Convergence. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations heads anchored the qualitative base. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA safety filings, and REACH substance restriction notices. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across material, feature, and end-user dimensions.
Sensitivity analysis tested forecast robustness against polyurethane feedstock volatility, airbag module supply concentration, and regulatory timeline shifts over the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from historical shipment trajectories, platform rollout schedules, and option penetration rate assumptions. Industry-specific inputs incorporated MIIT dual carbon enforcement intensity and ECE R12 structural integrity mandate adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EV platform expansion and stable REACH enforcement would require recalibration. Forecasts reflect documented assumptions about magnesium cost trajectories and capacitive touch reliability improvement rates. Practitioners should keep alternative scenarios live as software-defined vehicle protocol finalization and detachable wheel regulatory approval evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Exterior Smart Lighting Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Exterior Car Accessories Market