
 Power Seat Adjustment Motor Market | 2026-2036
Power Seat Adjustment Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Power Seat Adjustment Motor Market Insights
The gap between premium and commodity tiers is shifting from motor count to software-defined positioning precision. Brose Fahrzeugteile GmbH & Co. KG leverages its mechatronics heritage to dominate high-axis count systems for luxury platforms. Johnson Electric Holdings Limited anchors volume production through scalable DC motor architectures for mass-market OEMs. Nidec Corporation differentiates via rare-earth magnet efficiency gains that reduce thermal load in compact seat rail envelopes.
Power seat adjustment motors are electromechanical actuators that convert electrical energy into linear or rotary motion to reposition seat structures, typically operating at 12V DC with stall torque ratings between 8-25 Nm for lumbar and slide functions. Rotary motor configurations retain the largest installed base, yet linear motor adoption is accelerating in aviation and premium automotive segments where space constraints favor direct-drive elimination of gear trains. OEM end users capture the dominant value share, while aftermarket providers face margin compression from integrated non-serviceable seat modules.
NHTSA Federal Motor Vehicle Safety Standards and ECE R17 regulations govern seat strength and retention, indirectly mandating motor durability under crash loads. China MIIT dual carbon goals are pushing domestic suppliers toward copper-rotor induction designs that reduce rare-earth dependency. ISO 26262 functional safety requirements are filtering down from autonomous vehicle platforms into seat control architectures. Stakeholders must weigh motor standardization against platform-specific customization as vehicle electrical architectures consolidate zone controllers.
Market Dynamics
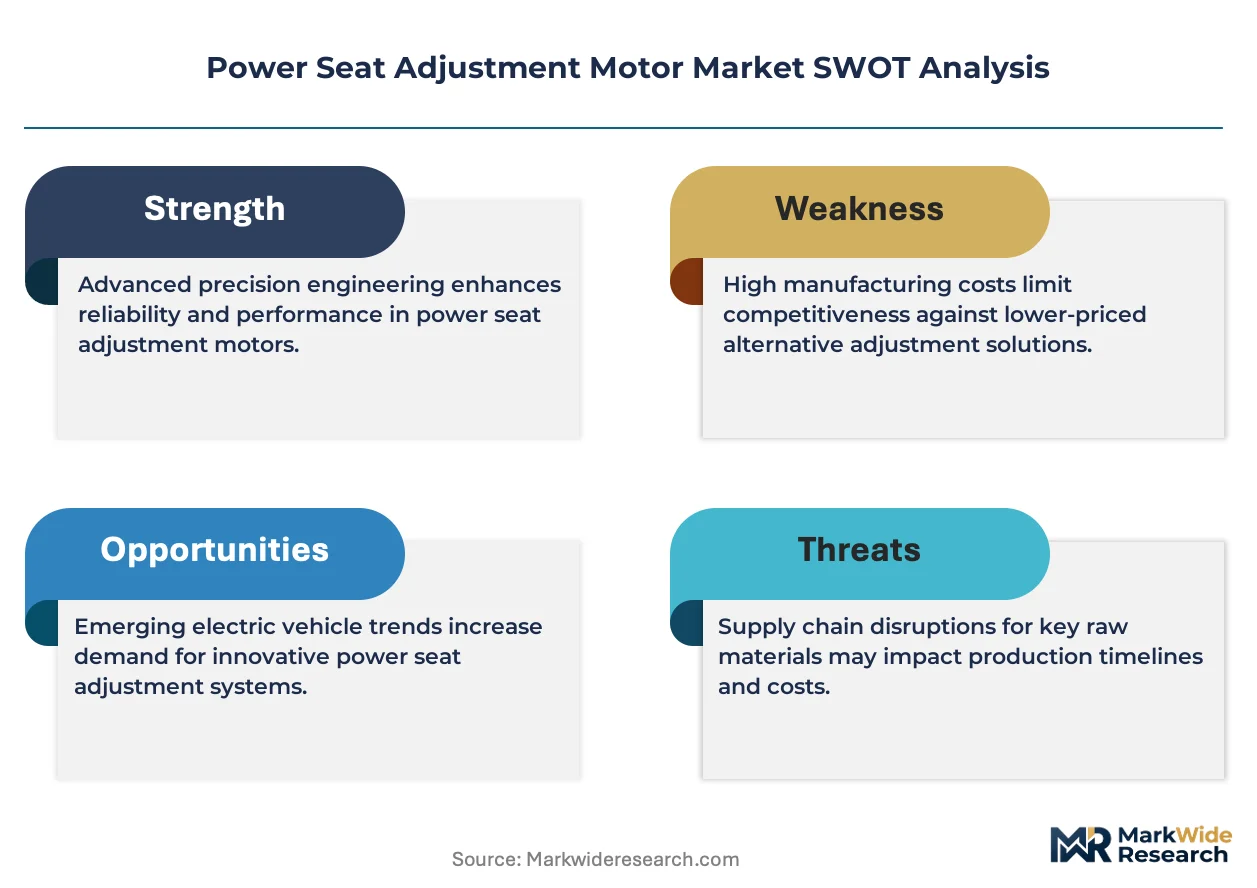
Software-defined seat architectures are compressing hardware margins while elevating firmware and calibration IP as the primary value capture mechanism. Tier 1 suppliers now compete on positioning algorithms rather than motor torque specifications.
Growth Catalysts
- NHTSA Occupant Positioning Mandates:Crash safety standards require precise seat retention under dynamic loads. OEMs must source motors with validated stall torque tolerance and redundant position sensing.
- Copper-Rotor Induction Designs:MIIT dual carbon targets push Chinese suppliers toward rare-earth-free motor topologies. Domestic EV brands adopt these architectures for supply security and carbon accounting compliance.
- Multi-Axis Seat Penetration:Luxury configurations with 12-16 way adjustment migrate into mid-tier vehicle lines. Mass-market OEMs specify compact motor modules that fit standard seat rail envelopes.
Market Restraints
- Neodymium Price Volatility:Permanent magnet motors face input cost swings from rare-earth concentrate markets. Suppliers hedge through long-term offtake contracts or pivot to ferrite alternatives with efficiency penalties.
- Integrated Module Non-Serviceability:Seat suppliers weld motors into structural carriers. Aftermarket providers lose access to replacement units, compressing spare parts revenue pools.
- ECE R17 Compliance Burden:European type approval requires extensive durability testing under temperature and vibration cycles. Development timelines extend by 8-14 months for new motor variants.
Strategic Opportunities
- Aviation Direct-Drive Linear Motors:Business jet cabins favor space-efficient actuation without gear trains. Premium seat OEMs source compact linear motor systems for pitch and slide functions.
- ISO 26262 Functional Safety Tier:ASIL-D rated seat control modules command pricing premiums. Suppliers with certified motor-driver integration capture autonomous vehicle platform sockets.
- Zone Controller Consolidation:Vehicle electrical architectures centralize seat control at domain level. Motor suppliers that deliver CAN-FD compatible smart actuators bypass legacy relay harness complexity.
Industry Challenges
- Embedded Firmware Talent Scarcity:Motor suppliers compete with automotive semiconductor firms for control algorithm engineers. Compensation inflation in Munich and Shanghai erodes project margins.
- Legacy LIN Bus Integration:Older vehicle platforms require backward-compatible motor communication. Suppliers maintain dual firmware branches, fragmenting validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Seat Adjustment Motor Market |
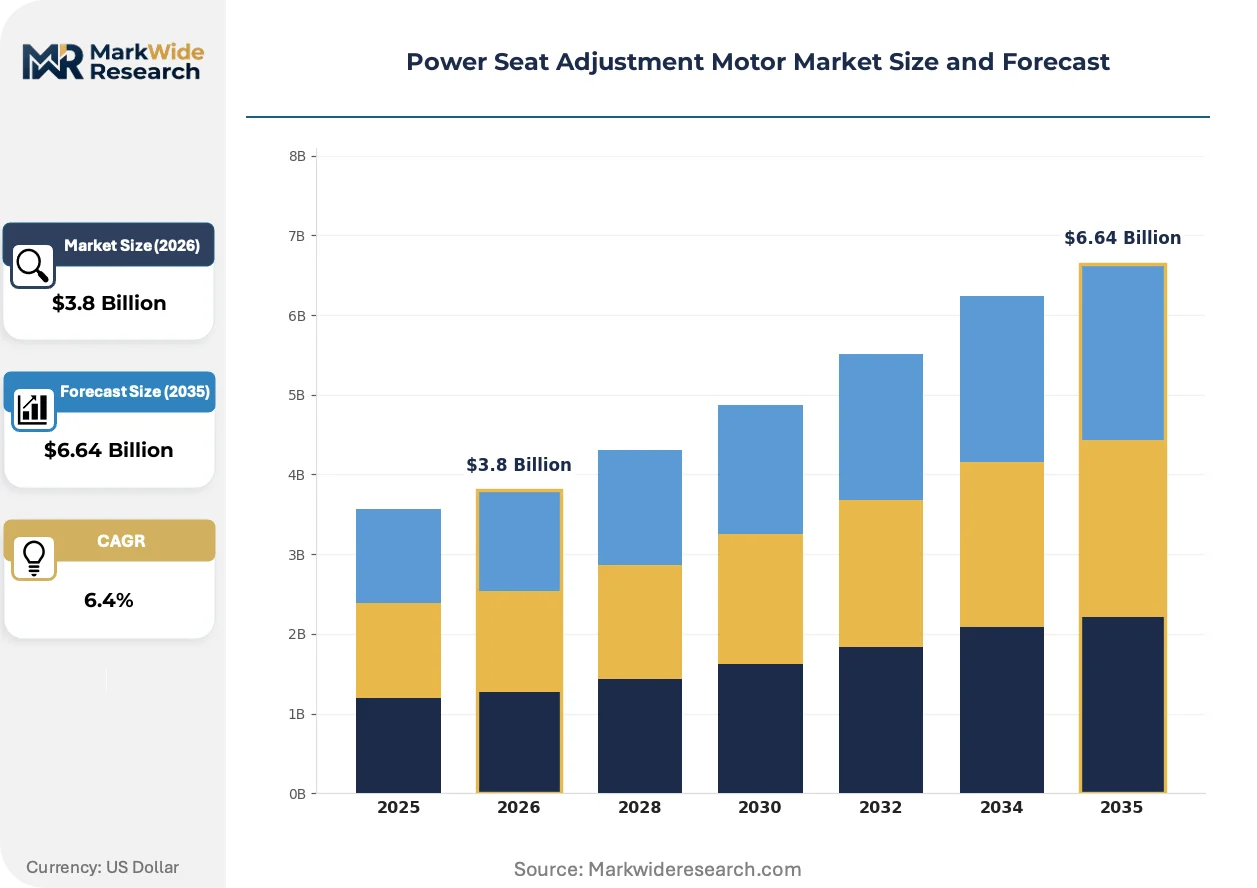
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Linear Motor, Rotary Motor, DC Motor, AC Motor Application: Passenger Vehicles, Commercial Vehicles, Aviation, Marine End User: OEMs, Aftermarket Providers, Fleet Operators, Custom Builders Technology: Electric, Pneumatic, Hydraulic, Others |
| Companies Covered | Brose Fahrzeugteile GmbH & Co. KG, Johnson Electric Holdings Limited, Nidec Corporation, Robert Bosch GmbH, Denso Corporation, Mitsuba Corporation, Valeo S.A., Mabuchi Motor Co., Ltd., ASMO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Seat Adjustment Motor Market Trends and Innovations
Actuator intelligence is migrating from centralized body controllers into edge devices. Smart motors with integrated position feedback and diagnostic capability are becoming the default specification across premium automotive platforms.
Brushless DC motor architectures with integrated Hall-effect sensing are displacing brushed commutator designs in lumbar and headrest applications. Tier 1 seat suppliers specify these for 2 million cycle life targets. The technology is integrating torque ripple compensation algorithms that eliminate perceptible vibration during micro-adjustments.
REACH substance restrictions on hexavalent chromium plating force suppliers to adopt zinc-nickel or organic coating alternatives for motor housings. European OEMs now mandate coating qualification to 720-hour salt spray resistance. Seat rail motor suppliers in Stuttgart and Turin have retooled surface treatment lines to meet the specification.
Fleet operators and mobility service providers now specify seat durability by usage hours rather than vehicle lifetime. Rental car companies negotiate motor warranty terms based on predicted actuation cycles per month. This recalibration is most visible in North American airport shuttle and corporate fleet procurement contracts.
Power Seat Adjustment Motor Market Segmentation
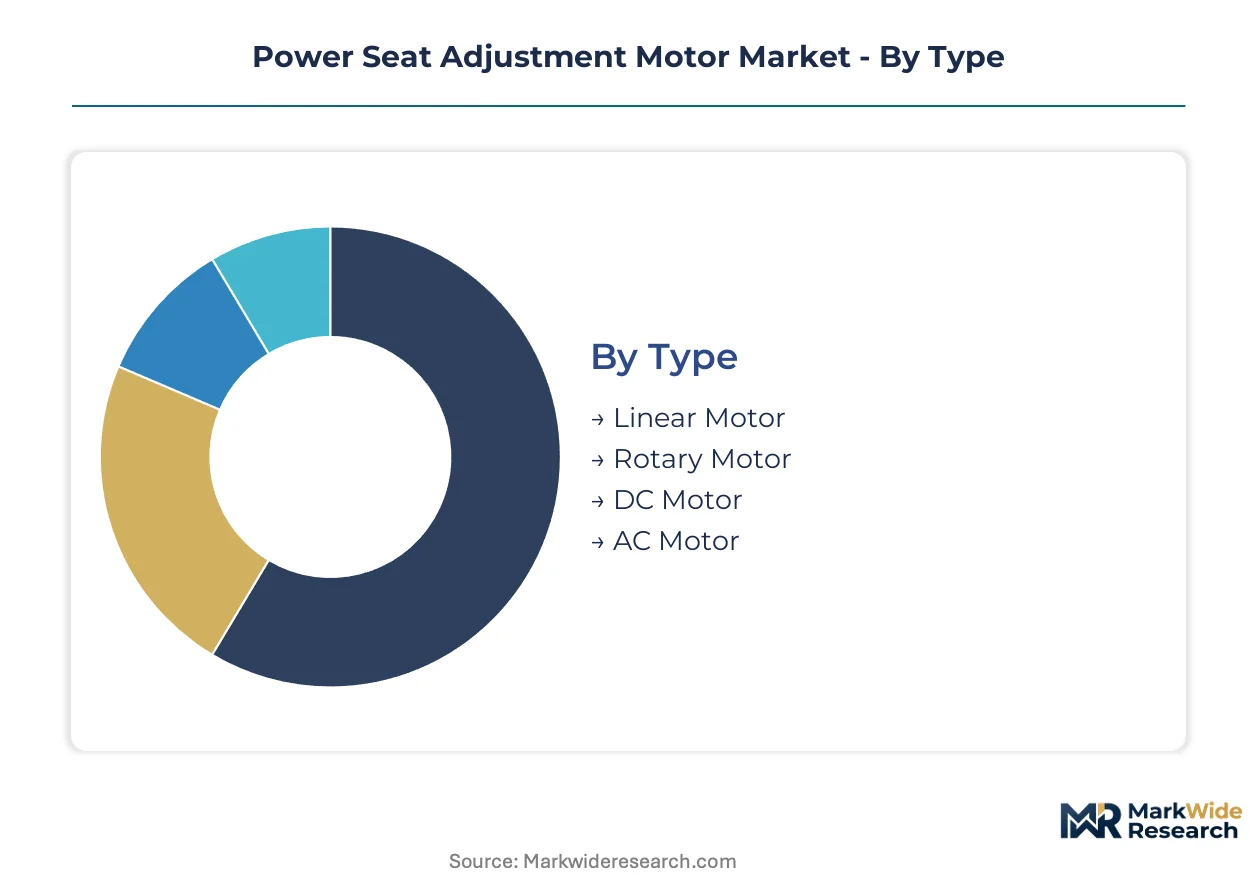
Power seat adjustment motor segmentation reveals divergent technical requirements across mobility platforms. Motor topology selection directly determines thermal envelope, precision capability, and supply chain exposure to rare-earth price cycles.
Type:
Volume production concentrates on proven DC architectures, while premium platforms absorb higher-cost linear and brushless alternatives for space and efficiency gains.
- Linear Motor:Direct-drive actuation eliminates gear trains for pitch and slide functions in business jet cabins and luxury automotive segments. Aviation seat OEMs in Wichita and Toulouse specify compact linear systems where envelope constraints override cost considerations.
- Rotary Motor:Brushed DC configurations with planetary gear reduction retain the largest installed base across mass-market automotive platforms. Chinese EV manufacturers source rotary motor modules from domestic suppliers to meet MIIT dual carbon compliance timelines.
- DC Motor:12V brushed architectures dominate standard seat rail applications with stall torque ratings between 8-25 Nm. Tier 1 suppliers in Stuttgart anchor volume production through scalable platforms serving European mass-market OEMs.
- AC Motor:Induction designs with copper rotors gain traction in Chinese domestic supply chains seeking rare-earth independence. MIIT carbon accounting rules accelerate AC motor qualification for new energy vehicle platforms.
Mature deployment sits with Rotary Motor. Newer deployment is concentrated in Linear Motor.
Application:
Passenger automotive captures the dominant revenue share, yet aviation and commercial vehicle specifications command pricing premiums for certification and durability.
- Passenger Vehicles:Multi-way adjustable seats with 12-16 motor axes migrate from luxury into mid-tier vehicle lines. NHTSA occupant positioning mandates force OEMs to specify motors with validated stall torque tolerance and redundant position sensing.
- Commercial Vehicles:Fleet procurement contracts now specify motor durability by predicted actuation cycles per month rather than vehicle lifetime. North American airport shuttle operators negotiate warranty terms based on usage-hour metrics.
- Aviation:FAA certification requirements and space constraints favor direct-drive linear motors without gear trains. Business jet cabin retrofits in Teterboro and Van Nuys drive demand for compact actuation systems.
- Marine:Salt spray resistance specifications to 720-hour exposure govern motor housing coatings for yacht seating applications. European superyacht builders in Viareggio specify sealed motor enclosures for helm and lounge seating.
Volume concentration remains with Passenger Vehicles. Margin expansion is steepest in Aviation.
End User:
OEM integration of motors into non-serviceable seat modules is compressing aftermarket revenue pools while elevating fleet operator specification power.
- OEMs:Seat suppliers weld motors into structural carriers, eliminating field service access. ECE R17 compliance testing extends development timelines by 8-14 months for new motor variants bound for European vehicle platforms.
- Aftermarket Providers:Integrated module designs restrict replacement unit availability. Independent distributors face margin compression as warranty coverage shifts to seat system-level rather than component-level terms.
- Fleet Operators:Rental car companies and mobility service providers negotiate motor warranties based on actuation frequency data. Corporate fleet procurement in Dallas and Atlanta now mandates predictive maintenance telemetry integration.
- Custom Builders:Low-volume specialty vehicle manufacturers source configurable motor control modules for bespoke seating geometries. Restoration specialists in Coventry specify period-correct motor housings with modern internal architectures.
Procurement authority is consolidating with Fleet Operators. Specification influence is fragmenting across Custom Builders.
Technology:
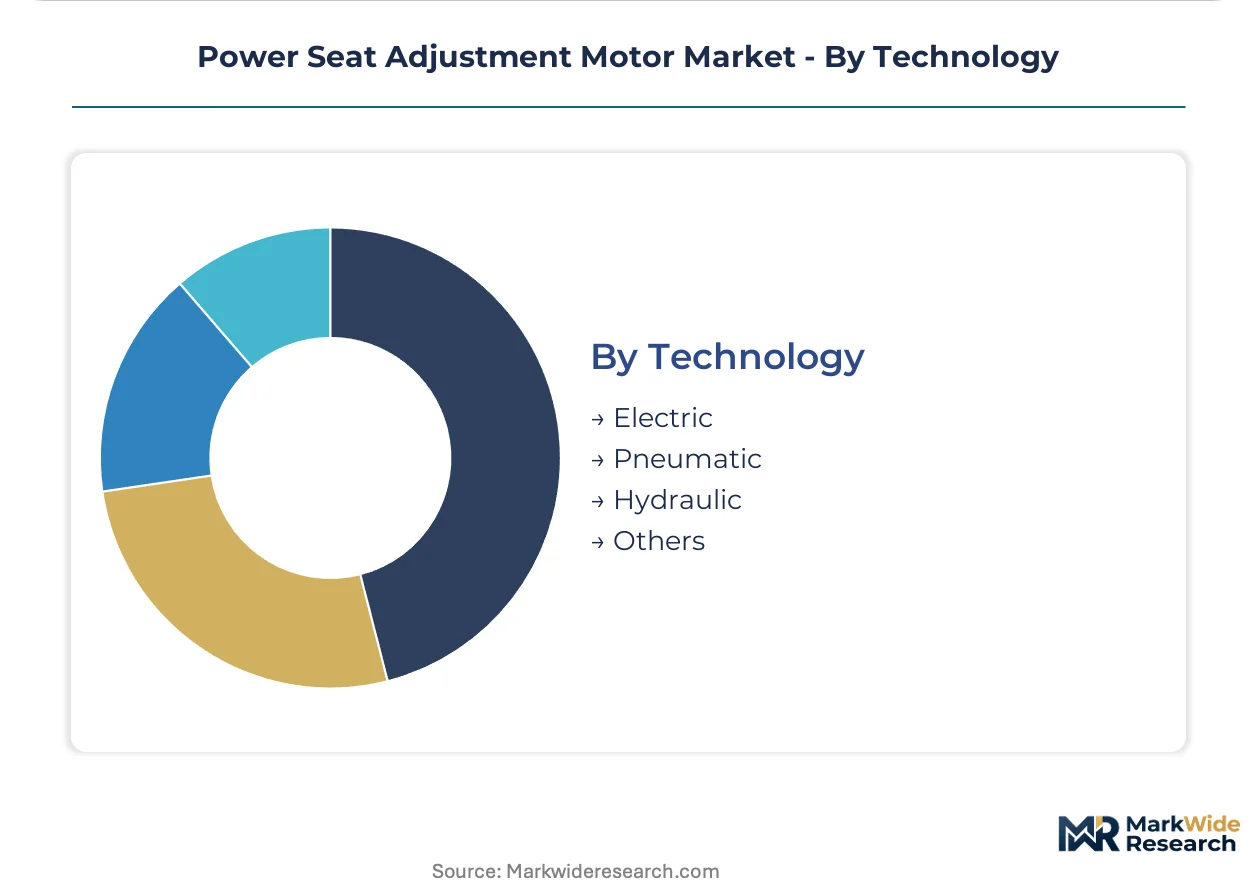
Electric actuation is displacing legacy pneumatic and hydraulic alternatives as vehicle electrical architectures centralize control at domain level.
- Electric:Brushless DC architectures with integrated Hall-effect sensing target 2 million cycle life for lumbar and headrest applications. ISO 26262 ASIL-D certification commands pricing premiums for autonomous vehicle platform sockets.
- Pneumatic:Bladder-based lumbar support systems persist in cost-optimized vehicle lines where motor precision exceeds functional requirements. Legacy platforms in emerging markets specify pneumatic actuation for supply chain simplicity.
- Hydraulic:High-force applications in heavy-duty commercial seating retain hydraulic power packs for durability under extreme load cycles. Mining vehicle operators in Western Australia specify hydraulic lumbar for vibration isolation.
- Others:Shape-memory alloy experimental actuation remains confined to concept vehicle demonstrations and aerospace research programs. Technical universities in Munich and Shanghai publish prototype evaluations without production scaling.
Technology transition is accelerating toward Electric. Hydraulic retains niche deployment in heavy-duty Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the highest concentration of seat system engineering, with Tier 1 suppliers clustering around Porsche, Mercedes-Benz, and Bosch headquarters. German motor manufacturers supply precision actuation modules across European luxury platforms. Chinese EV brands in Shanghai and Shenzhen now specify equivalent multi-axis configurations as standard equipment.
United States
NHTSA occupant positioning mandates force Detroit-based OEMs to source motors with validated stall torque tolerance. The FAA certifies direct-drive linear systems for Wichita and Van Nuys business jet retrofits. Michigan seat rail suppliers now integrate predictive maintenance telemetry for Dallas and Atlanta fleet operators.
Germany
ECE R17 compliance testing extends development timelines by 8-14 months for Stuttgart motor variants. REACH substance restrictions on hexavalent chromium plating force Turin and Stuttgart suppliers to adopt zinc-nickel coatings. Brose Fahrzeugteile GmbH & Co. KG anchors high-axis count production for regional luxury platforms.
China
MIIT dual carbon goals accelerate copper-rotor induction motor adoption across domestic EV brands. Shanghai and Shenzhen manufacturers integrate 12-16 way adjustable seats as standard differentiators. Nidec Corporation supplies rare-earth-efficient architectures to reduce thermal load in compact seat rail envelopes.
Japan
METI industrial policy supports brushless DC motor R&D for 2 million cycle life targets. Johnson Electric Holdings Limited and Mabuchi Motor Co., Ltd. occupy positions in scalable DC architectures for mass-market export programs. Nagoya-area suppliers target ASIL-D functional safety certification for autonomous vehicle platform sockets.
Italy
European superyacht builders in Viareggio specify sealed motor enclosures meeting 720-hour salt spray resistance. Turin seat rail suppliers retooled surface treatment lines for REACH-compliant coating qualifications. The region captures margin premiums in marine and aviation actuation segments.
Power Seat Adjustment Motor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software-defined positioning precision rather than motor count. The vendor base organizes into three tiers: mechatronics heritage specialists commanding high-axis luxury sockets, scalable DC architects anchoring mass-market volume, and rare-earth efficiency innovators reducing thermal envelopes. Consolidation pressure intensifies as zone controller architectures eliminate legacy relay harness complexity. Capacity expansion and strategic partnerships dominate competitive moves as suppliers seek firmware talent in Munich and Shanghai.
Within the mechatronics heritage tier, Brose Fahrzeugteile GmbH & Co. KG and Johnson Electric Holdings Limited exemplify divergent scale-positioning strategies. Brose occupies a position in high-axis count systems for luxury automotive platforms, while Johnson Electric anchors volume production through scalable architectures. Nidec Corporation sits within the efficiency-driven segment, representing rare-earth magnet optimization approaches that address supply security concerns.
| Leading Market Players |
|---|
| Brose Fahrzeugteile GmbH & Co. KG |
| Johnson Electric Holdings Limited |
| Nidec Corporation |
| Robert Bosch GmbH |
| Denso Corporation |
| Mitsuba Corporation |
| Valeo S.A. |
| Mabuchi Motor Co., Ltd. |
| ASMO |
| Others |
Pricing and Supply Chain Analysis
NHTSA occupant positioning mandates for validated stall torque tolerance have concentrated procurement authority with Tier 1 seat suppliers capable of bearing extended ECE R17 compliance timelines. This buyer consolidation toward certified motor architectures compresses margin capture for undifferentiated commodity producers while elevating firmware-integrated suppliers.
Pricing Analysis
Value-based pricing anchored to ISO 26262 ASIL-D functional safety certification commands premiums from autonomous vehicle platform sockets. Three-tier pricing structure across premium, standard, and economy levels separates rare-earth-efficient brushless DC architectures from copper-rotor induction alternatives and legacy brushed DC commodity units. Cost compression in mass-market rotary motor tiers intensifies as Chinese EV manufacturers leverage domestic supply chains for MIIT dual carbon compliance. Fleet operators exhibit highest price sensitivity due to usage-hour warranty negotiations, while aviation OEMs prioritize space-efficient linear motor configurations over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart, Shanghai, and Detroit automotive clusters, with Tier 1 seat suppliers integrating motors into non-serviceable structural carriers. Manufacturing concentration centers on Germany, China, and Japan for precision actuation modules. Raw material dependencies rest on neodymium permanent magnets, copper rotor windings, and zinc-nickel coating chemistries. Single-source vulnerability in rare-earth concentrate markets exposes suppliers to input cost volatility. Distribution runs through just-in-time delivery networks synchronized to vehicle assembly plant schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rare-earth magnet supply constraints prop pricing power for copper-rotor induction alternatives, with MIIT dual carbon timelines limiting rapid capacity expansion. Firmware talent scarcity in Munich and Shanghai further tightens supply for smart actuator architectures.
For Market Incumbents: Deepen backward integration into copper-rotor induction motor production to hedge neodymium price volatility and secure MIIT compliance pathways for Chinese EV platform sockets. Add certified firmware development capacity in Stuttgart and Shanghai to defend against automotive semiconductor firms recruiting control algorithm engineers. Prioritize ASIL-D functional safety certification investments to maintain pricing premiums as zone controller architectures consolidate seat control hierarchies. For New Entrants and Emerging Players: Begin with aviation direct-drive linear motor segments where FAA certification requirements and space constraints limit incumbent penetration and sustain margin premiums. Target marine applications in European superyacht builder specifications for sealed motor enclosures meeting 720-hour salt spray resistance. Pursue fleet operator procurement channels in Dallas and Atlanta with predictive maintenance telemetry integration as a differentiated service layer. For Investors and Strategic Acquirers: The window for entry favors mechatronics heritage specialists with existing ASIL-D certification and high-axis count production platforms. Long-term viability rests on firmware IP ownership rather than motor hardware scale. Monitor NHTSA rulemaking on occupant positioning precision as an inflection indicator for regulatory-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Talent Acquisition | Control algorithm engineering capacity in Munich and Shanghai determines smart actuator market access. |
| Copper-Rotor Induction Scale-Up | Rare-earth-free motor topologies align with MIIT dual carbon compliance timelines for Chinese EV brands. |
| ASIL-D Certification Investment | Functional safety tiering commands pricing premiums from autonomous vehicle platform sockets. |
| Aviation Linear Motor Qualification | FAA-certified direct-drive architectures capture business jet cabin retrofit demand in Wichita and Van Nuys. |
| Zone Controller Integration | CAN-FD compatible smart actuators bypass legacy relay harness complexity in consolidated electrical architectures. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement directors, OEM platform engineers, and aftermarket distributor operations underwrites the qualitative findings in this study. Primary interviews with seat system R&D heads, motor manufacturing plant managers, and fleet operator maintenance directors combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standards filings, ECE R17 type approval databases, and MIIT new energy vehicle production records. Bottom-up motor shipment estimates triangulated against top-down vehicle production data across the analysis window.
Comparable-period anchoring to historical vehicle registration and seat configuration penetration data established baseline assumptions for projection modeling. Segmentation dimensions span motor topology, application platform, end-user procurement authority, and technology type, with vehicle class and regional regulatory cluster as automotive-specific overlays. CAGRs derive from fitted growth curves calibrated to technology transition rates and regulatory compliance deadlines. Forecast inputs incorporate NHTSA mandate implementation timelines and MIIT dual carbon policy phase-ins.
Underlying measurement precision varies by segment; aviation and marine applications carry tighter precision than aftermarket replacement due to certification documentation requirements. Forecasts reflect assumptions on rare-earth price stability, firmware talent availability, and zone controller adoption velocity. Practitioners should monitor NHTSA occupant positioning rulemaking, MIIT carbon accounting enforcement, and neodymium concentrate market movements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
LNG Engine Market
Powertrain
Automotive Carburetor Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Automotive Powertrain Market
Powertrain
Automotive Camshaft Market
Powertrain
Global Automotive Clutch Market
Powertrain
Engine Starter Market
Powertrain
Transmission Fluids Market
Powertrain
Global Driveline Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
CNG Powertrain Market