
 Tachometer Market | 2026-2036
Tachometer Market Size, Share, and Industry Trends Forecast 2026-2036
Tachometer Market Outlook
The tachometer supply base is consolidating around a widening gap between precision instrumentation for automated factories and low-cost analog gauges for legacy machinery. Pepperl+Fuchs SE leverages its sensor integration depth to dominate optical tachometer architectures for hazardous environments. KUBLER GmbH anchors its position through captive encoder manufacturing in Germany, while Autonics competes aggressively on price in Asia's industrial equipment channels.
A tachometer measures rotational speed in revolutions per minute (RPM) using contact or non-contact sensing principles, with Hall Effect variants achieving accuracy within 0.1% through magnetic field detection of gear teeth or embedded magnets. Digital tachometers now lead the product type hierarchy as plant operators replace analog dial gauges with RS-485 networked instruments for predictive maintenance integration. Hall Effect technology captures the fastest expansion trajectory, displacing optical methods in contaminated industrial settings where dust and oil degrade photoelectric performance.
FCC electromagnetic compatibility rules in the United States constrain wireless tachometer transmitter designs, while EU machinery directives under CE marking mandate fail-safe rotational monitoring for automated production lines. Japan's METI industrial standards further shape export requirements for precision tachometers bound for East Asian automotive testing facilities. Stakeholders must monitor how IEC 61000 electromagnetic immunity standards evolve to accommodate 5G-enabled wireless tachometer installations without sacrificing measurement integrity in high-noise factory floors.
Market Dynamics
Automotive electrification in the European Union is compressing measurement tolerances for rotational-speed sensors, forcing suppliers to recalibrate Hall Effect architectures for electric drivetrain validation while legacy analog gauge demand flatlines in mature industrial economies.
Growth Catalysts
- EU Machinery Directives:CE marking mandates for fail-safe rotational monitoring on automated production lines are accelerating replacement cycles for non-compliant analog instruments in Germany and Italy.
- Electric Vehicle Testing:Precision Hall Effect tachometers are capturing expanded deployment in automotive validation facilities where embedded magnet detection replaces contact-based measurement for motor characterization.
- Contaminated Environment Migration:Dust and oil degradation of photoelectric sensors is pushing food processing and mining operations toward magnetic field detection methods with sealed housing architectures.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium supply concentration in China's processing infrastructure creates input cost volatility for Hall Effect sensor manufacturers dependent on consistent magnetic field strength.
- Wireless Certification Friction:FCC electromagnetic compatibility rules in the United States constrain transmitter designs for battery-powered tachometers, extending product development timelines by 8-14 months for 2.4 GHz implementations.
- Optical Sensor Inventory Overhang:Legacy photoelectric tachometer stockpiles in Eastern European machine tool sectors are delaying upgrade decisions despite demonstrated reliability failures in abrasive environments.
Strategic Opportunities
- 5G-Enabled Predictive Maintenance:IEC 61000 electromagnetic immunity standard evolution is opening installation pathways for wireless tachometer networks on high-noise factory floors previously inaccessible to unshielded transmitters.
- India PLI Scheme:Production-linked incentives for industrial automation equipment are attracting tachometer assembly investments serving domestic textile and pharmaceutical machinery demand.
- Automotive Testing Convergence:Integration of RS-485 networked tachometers with vibration analysis platforms is creating bundled instrumentation packages for powertrain validation laboratories in Japan and South Korea.
Industry Challenges
- Embedded Firmware Expertise Scarcity:Shortage of engineers proficient in magnetic field calibration algorithms is delaying product launches for mid-tier suppliers attempting Hall Effect transitions.
- Legacy System Integration Complexity:Analog-to-digital signal conversion requirements for retrofit installations are generating commissioning failures in 1970s-era machine tool parks across Midwestern United States manufacturing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tachometer Market |
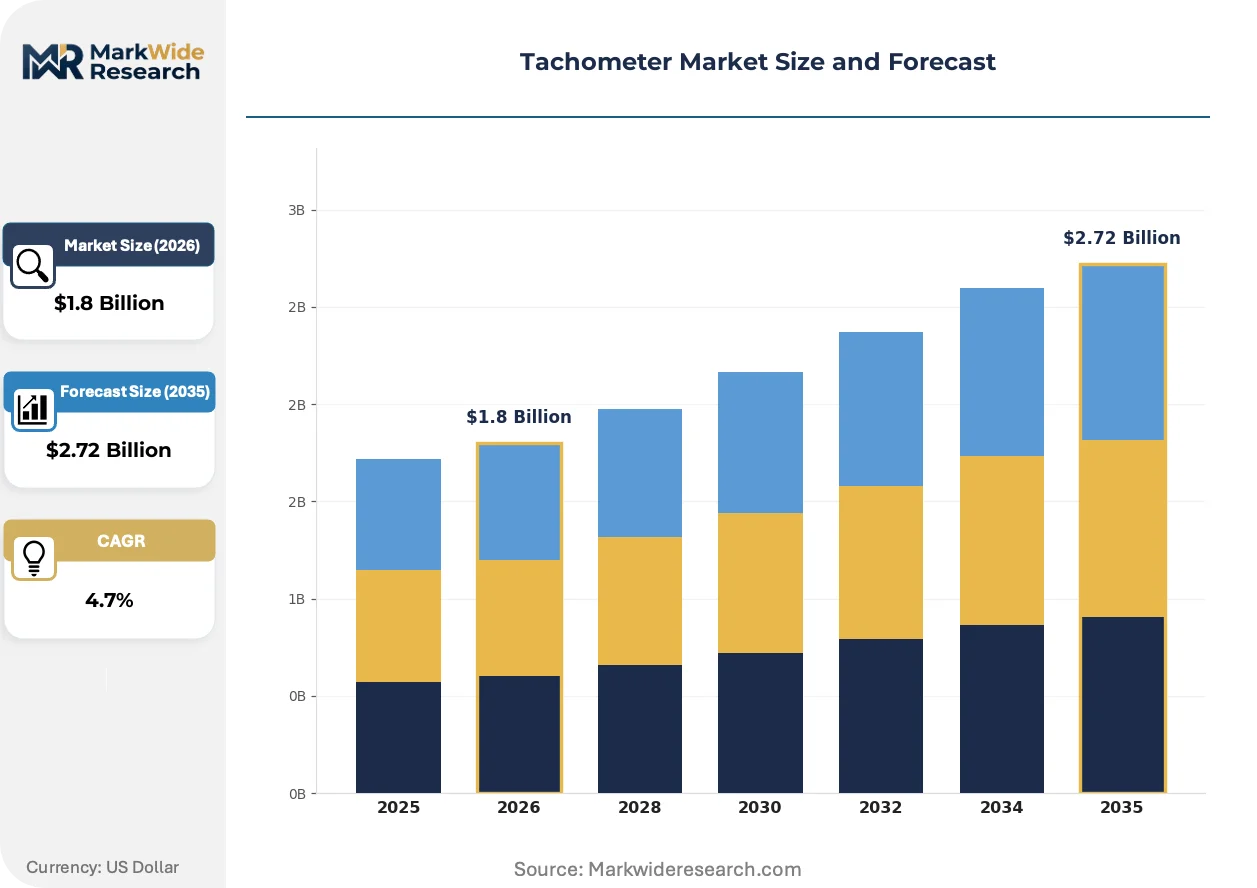
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dynamometer, Digital Tachometer, Analog Tachometer, Handheld Tachometer Technology: Optical, Magnetic, Capacitive, Hall Effect End User: Automotive Industry, Aerospace Sector, Industrial Equipment, Marine Applications Installation: Portable, Fixed, Integrated, Wireless |
| Companies Covered | Pepperl+Fuchs SE, KUBLER GmbH, Autonics, Emerson Electric, Dynapar, Delta Electronics, HENGSTLER, Rockwell Automation, OMRON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tachometer Market Strategic Shifts
Sensor architecture is fragmenting into application-specific modules as plant operators reject one-size-fits-all instrumentation, while regulatory pressure on electromagnetic emissions forces redesign cycles that favor software-configurable platforms over fixed-function hardware.
Multi-protocol communication hardware is modularizing across industrial tachometer designs, enabling single units to switch between 4-20 mA analog, RS-485 Modbus, and IO-Link outputs through firmware updates rather than hardware swaps. Automotive testing laboratories in Germany and Japan are piloting these flexible interfaces to reduce spare parts inventory. The approach is compressing supplier SKU proliferation while extending product lifecycles through field reconfiguration.
REACH substance restrictions on cadmium and lead in electronic components are forcing magnetic encoder manufacturers to reformulate solder alloys and magnet coatings for EU-bound equipment. Industrial automation OEMs are responding by dual-sourcing Hall Effect sensors from certified and non-certified production lines. The regulatory friction is most acute for precision instrumentation destined for German automotive supplier parks where RoHS compliance documentation is mandatory for contract eligibility.
Buyer consolidation among multinational automotive groups is concentrating procurement authority into centralized technical specifications that disqualify regional tachometer suppliers lacking global service networks. Tier-1 powertrain testing houses in Detroit, Stuttgart, and Toyota City are mandating 24-hour replacement part availability across three continents. The behavioral shift is elevating instrumentation vendors with captive logistics infrastructure while marginalizing geographically concentrated competitors.
Tachometer Market Segmentation
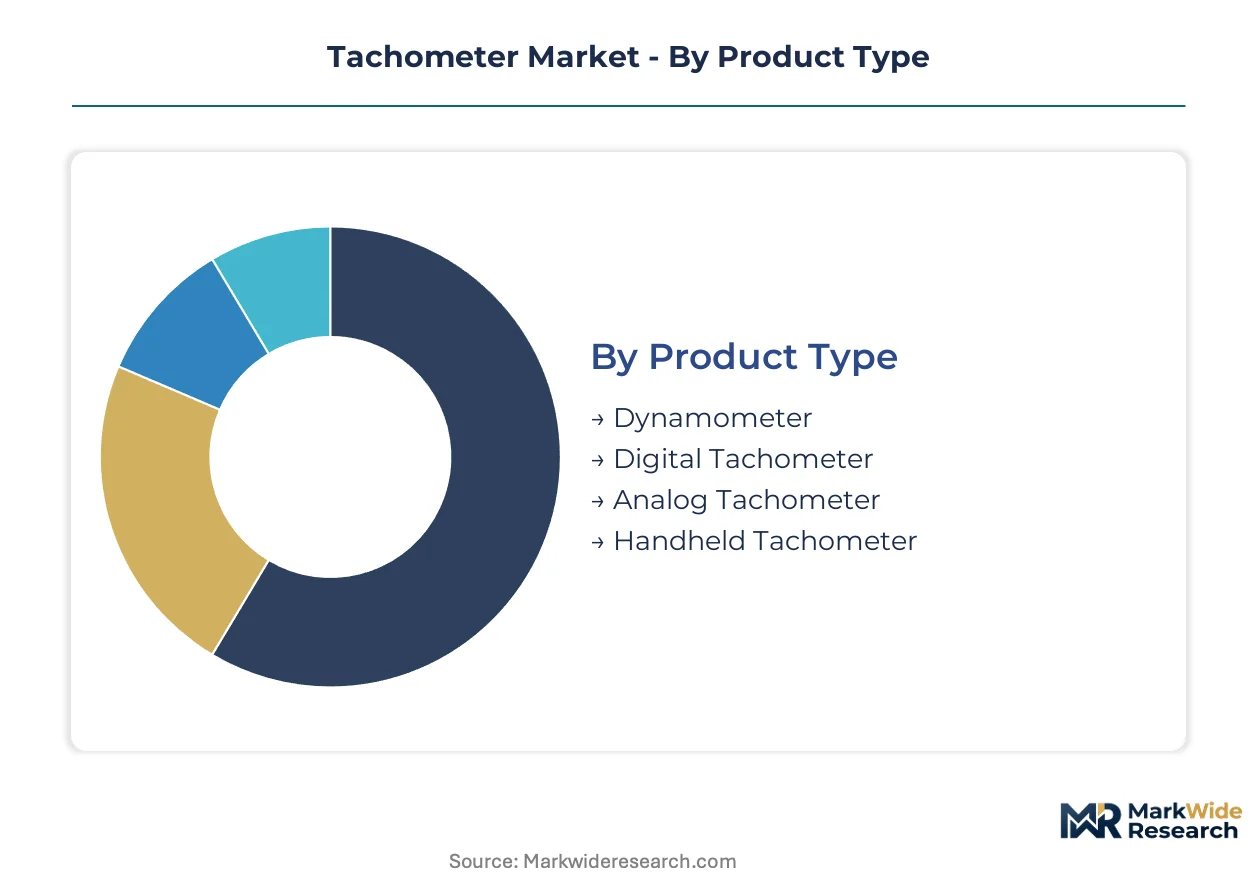
Segmentation in the tachometer market reflects divergent buyer priorities across precision requirements, environmental resilience, and connectivity architecture. Suppliers must configure portfolios spanning laboratory-grade Hall Effect validation tools to cost-optimized analog gauges for legacy machinery.
Product Type:
Customization depth varies sharply across this category, from configurable digital platforms with firmware-defined outputs to fixed-function analog dials with no parameter adjustment.
- Digital Tachometer:RS-485 networked instruments with predictive maintenance integration dominate new industrial automation deployments. Plant operators in Germany's precision manufacturing corridor are replacing analog dial gauges with these units for real-time rotational speed monitoring. Demand concentrates in automotive validation facilities where embedded software enables remote calibration.
- Analog Tachometer:Mechanical dial gauges with needle indicators persist in cost-sensitive retrofit applications and legacy machinery maintenance. Eastern European machine tool sectors retain substantial installed bases despite reliability limitations in contaminated environments. Upgrade delays stem from inventory overhang and minimal capital allocation for non-critical equipment.
- Dynamometer:Integrated power measurement systems combining torque and rotational speed sensing for powertrain test cells.
- Handheld Tachometer:Battery-powered portable units for field maintenance and spot-check diagnostics in mining and food processing operations.
Most installed capacity flows through Analog Tachometer. Expansion is steepest in Digital Tachometer.
Technology:
Cost tier stratification separates premium magnetic sensing architectures from commodity optical methods vulnerable to environmental degradation.
- Hall Effect:Magnetic field detection achieves accuracy within 0.1% through gear tooth or embedded magnet sensing. Automotive electrification programs in the European Union are tightening rotational-speed measurement requirements, forcing suppliers to recalibrate architectures for electric drivetrain validation. Germany's OEMs source these units for industrial automation and vehicle testing.
- Optical:Photoelectric sensors detect rotational markers through LED-photodiode pairs. Dust and oil degradation in mining and food processing operations is accelerating displacement toward sealed magnetic alternatives. Legacy stockpiles in Eastern European machine tool sectors delay complete phase-out despite demonstrated field failures.
- Magnetic:Variable reluctance sensors for high-temperature engine and transmission applications.
- Capacitive:Non-contact proximity detection for cleanroom semiconductor manufacturing and precision spindle monitoring.
Optical retains the largest installed base. Hall Effect is gaining share fastest.
End User:
Application intensity drives specification divergence, with aerospace and automotive demanding traceable calibration chains absent in general industrial equipment.
- Automotive Industry:Powertrain validation laboratories require precision rotational speed measurement for motor characterization and transmission efficiency mapping. Tier-1 testing houses in Stuttgart, Detroit, and Toyota City mandate 24-hour replacement part availability across three continents. Embedded magnet detection replaces contact-based methods for electric drivetrain development.
- Industrial Equipment:Factory automation lines deploy networked tachometers for predictive maintenance integration. CE marking mandates under EU machinery directives are accelerating replacement cycles for non-compliant analog instruments in Germany and Italy. Fail-safe rotational monitoring is mandatory for automated production lines.
- Aerospace Sector:Jet engine test cells and auxiliary power unit validation require high-temperature optical and magnetic architectures.
- Marine Applications:Propulsion shaft monitoring and diesel engine diagnostics in commercial shipping and naval vessels.
Industrial Equipment absorbs the highest unit volume. Automotive Industry shows the steepest specification escalation.
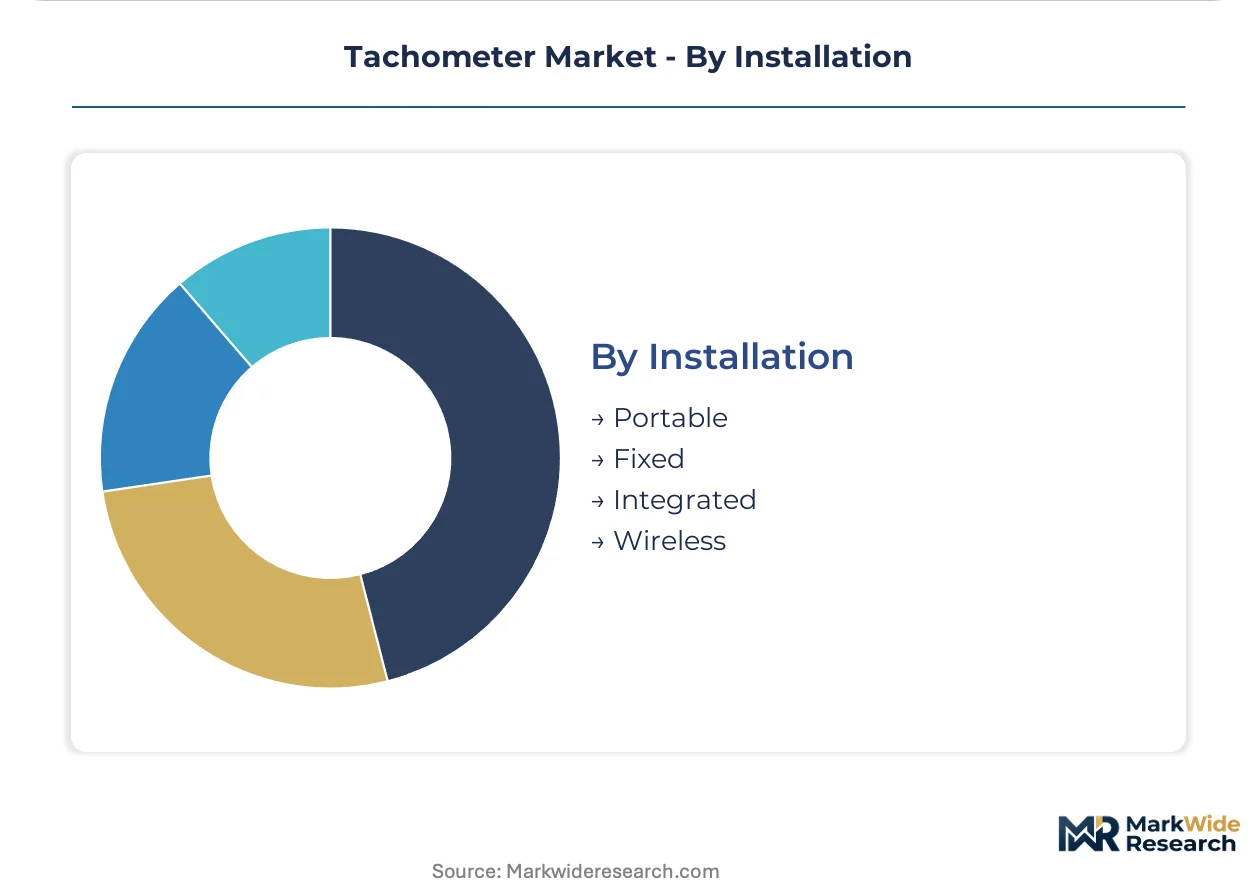
Installation:
Customer type splits between maintenance departments favoring portable flexibility and OEM integrators specifying fixed or embedded architectures.
- Fixed:Permanently mounted sensors on production machinery and test stands dominate high-volume manufacturing. EU machinery directives mandate fail-safe rotational monitoring, driving panel-mount digital tachometer adoption. German automotive supplier parks require RoHS compliance documentation for contract eligibility.
- Wireless:Battery-powered transmitters enable installation on rotating equipment without slip-ring complexity. FCC electromagnetic compatibility rules in the United States constrain 2.4 GHz designs, extending development timelines. IEC 61000 electromagnetic immunity standard evolution is opening pathways for 5G-enabled networks on high-noise factory floors.
- Portable:Handheld and clamp-on units for field diagnostics and temporary measurement campaigns.
- Integrated:Embedded sensors within motor housings, gearboxes, and turbine assemblies supplied as subsystems.
Fixed installation accounts for the majority of current deployments. Wireless is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent clusters around Stuttgart and Munich anchor precision instrumentation development for automotive validation. Japanese metrology expertise concentrates in Nagoya and Tokyo corridors for industrial automation applications. Chinese manufacturing engineers in Shenzhen and Shanghai drive cost-optimized sensor production for export markets.
Germany
Automotive electrification programs at BMW, Mercedes-Benz, and Volkswagen tighten rotational-speed measurement tolerances for electric drivetrain validation. CE marking mandates under EU machinery directives accelerate replacement cycles for non-compliant analog instruments. Stuttgart's precision manufacturing corridor sources high-accuracy Hall Effect tachometers from captive encoder suppliers for powertrain test cells.
United States
Detroit's Tier-1 powertrain testing houses mandate 24-hour replacement part availability across three continents for validation laboratories. FCC electromagnetic compatibility rules constrain wireless tachometer transmitter designs, extending product development timelines for 2.4 GHz implementations. Midwestern machine tool parks in Ohio and Michigan face analog-to-digital signal conversion challenges during retrofit commissioning.
Japan
METI industrial standards shape export requirements for precision tachometers bound for East Asian automotive testing facilities. Automotive testing convergence integrates RS-485 networked tachometers with vibration analysis platforms in Toyota City laboratories. Nagoya's industrial automation corridor demands multi-protocol communication hardware switching between 4-20 mA analog and IO-Link outputs.
China
Rare earth magnet processing concentration in Inner Mongolia and Jiangxi creates input cost volatility for Hall Effect sensor manufacturers dependent on neodymium supply. GB standards and MIIT regulations govern electromagnetic compatibility for domestic industrial equipment installations. Shenzhen's electronics manufacturing ecosystem produces cost-optimized Hall Effect modules for Asian industrial equipment channels.
India
PLI scheme production-linked incentives for industrial automation equipment attract tachometer assembly investments serving domestic textile and pharmaceutical machinery demand. BIS certification requirements shape product specifications for precision instrumentation entering government procurement channels. Gujarat's pharmaceutical machinery cluster and Tamil Nadu's textile equipment sector drive demand for predictive maintenance-integrated digital tachometers.
Tachometer Market Competitive Environment
Capital-heavy producers compete with asset-light designers across sensor architecture development, with captive manufacturing facilities in Germany and Japan facing modular assembly operations in China and Southeast Asia. The supplier base stratifies into three tiers: integrated industrial automation conglomerates with captive sensor divisions, precision instrumentation specialists with captive encoder manufacturing, and price-competitive module assemblers serving replacement markets. Strategic moves concentrate on backward integration into magnetic component supply and firmware-configurable platform development to compress SKU proliferation.
Among Germany-based precision specialists, Pepperl+Fuchs SE and KUBLER GmbH occupy positions within the sensor-integrated instrumentation tier, with KUBLER's captive encoder manufacturing anchoring supply security for automotive validation channels. Autonics represents the price-competitive archetype in Asian industrial equipment distribution. Emerson Electric and Rockwell Automation sit within the industrial automation conglomerate tier, leveraging captive distribution networks to bundle tachometer instrumentation with broader factory automation portfolios.
| Leading Market Players |
|---|
| Pepperl+Fuchs SE |
| KUBLER GmbH |
| Autonics |
| Emerson Electric |
| Dynapar |
| Delta Electronics |
| HENGSTLER |
| Rockwell Automation |
| OMRON |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on cadmium and lead in electronic components gate qualified supply for EU-bound tachometer manufacturers while segmenting pricing access between RoHS-certified premium tiers and uncertified economy alternatives. German automotive supplier parks mandate compliance documentation for contract eligibility, forcing dual-sourcing strategies that inflate procurement costs for validated production lines.
Pricing Analysis
Bundled calibration services versus unbundled hardware-only sales split pricing architectures across the tachometer market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy analog gauges intensifies because of Eastern European inventory overhang, while automotive validation laboratories show least price sensitivity due to traceable calibration requirements.
Supply Chain Analysis
Single-source vulnerability sits with China's neodymium processing infrastructure in Inner Mongolia and Jiangxi provinces. Magnetic encoder manufacturing draws from rare earth magnet feedstock, precision-wound copper coils, and RoHS-compliant solder alloys. Tariff exposure on Chinese-processed rare earths threatens input cost stability for Hall Effect sensor producers. Distribution runs through industrial automation OEMs and specialized instrumentation distributors serving replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tachometer market functions as a regulatory compounder where CE marking mandates under EU machinery directives continuously refresh replacement demand for fail-safe rotational monitoring equipment.
For Market Incumbents: Anticipate firmware-configurable platform transitions as optical sensor obsolescence accelerates in contaminated industrial environments. Secure captive encoder manufacturing capacity in Germany to defend against Asian price competitors. Prioritize IEC 61000 electromagnetic immunity certification investments to capture 5G-enabled wireless installation growth in high-noise factory floors. For New Entrants and Emerging Players: Wireless multi-protocol communication modules offer a technology-first wedge into predictive maintenance retrofit opportunities. Target India's PLI scheme-supported textile and pharmaceutical machinery clusters where digital tachometer penetration remains underdeveloped. Pursue channel partnerships with domestic industrial equipment assemblers rather than direct OEM confrontation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier analog gauge manufacturers with stranded Eastern European customer bases. Long-term viability favors precision instrumentation specialists with captive magnetic component supply and firmware development capabilities. Watch for IEC 61000 standard finalization as inflection signal for wireless tachometer network deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Components | Captive neodymium supply hedges against Chinese processing concentration volatility. |
| Firmware-Configurable Platform Development | RS-485/IO-Link/4-20 mA multi-protocol hardware compresses SKU proliferation for German OEMs. |
| RoHS Compliance Certification Investment | REACH substance documentation unlocks contract eligibility in Stuttgart automotive supplier parks. |
| Wireless Tachometer Network Pilot Programs | 5G-enabled installations penetrate high-noise factory floors previously inaccessible to unshielded transmitters. |
| India PLI Scheme Manufacturing Localization | Domestic assembly serves Gujarat pharmaceutical and Tamil Nadu textile machinery demand growth. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation against customs records and SEC filings, and technical specification analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included maintenance directors at German automotive validation facilities, instrumentation distributors serving Midwestern US machine tool parks, and magnetic component suppliers in China's rare earth processing corridor. Secondary sources encompassed EU machinery directive documentation, FCC electromagnetic compatibility rulings, and industrial automation OEM technical specifications.
Data-stream reconciliation across product type, technology architecture, end-use intensity, and installation format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level unit economics and replacement cycle modeling. Forecast inputs incorporated EU automotive electrification program timelines, REACH substance restriction phase-in schedules, and 5G industrial network deployment trajectories in Japanese automotive testing corridors.
The model holds under stable rare earth magnet supply conditions and continued CE marking enforcement; deviation in Chinese export restriction policies or IEC 61000 standard delays would shift replacement cycle assumptions. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and technology transition velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Steering Damper Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
United States Automotive Engine Oils Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Gasoline Turbochargers Market
Powertrain
Automotive Camshaft Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Clutch Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Automotive Counter Shaft Market