
 Brazil Automotive Engine Oils Market | 2026-2036
Brazil Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Engine Oils Market Outlook
Modular packaging configurations is pivoting buyer procurement patterns across Brazil's automotive service network. Petrobras leverages its captive refinery infrastructure to anchor supply security for bulk fleet contracts. ExxonMobil Corporation competes through specialized synthetic formulations targeting Brazil's flex-fuel engine population. Royal Dutch Shell Plc differentiates via controlled retail presence at branded service stations in major metropolitan corridors.
Brazil automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines operating under tropical temperature ranges and variable ethanol-blend fuel conditions. These products must maintain viscosity stability across 0W-20 to 15W-40 grades while resisting oxidation from acidic combustion byproducts common in flex-fuel applications. Synthetic formulations command premium positioning as OEM fill requirements tighten, while conventional segments retain volume dominance in independent aftermarket channels. Bulk packaging captures fleet and industrial maintenance demand, whereas bottle and can formats distribute through retail and service station networks serving individual vehicle owners.
ANVISA governs chemical substance registration and environmental safety disclosures for lubricant formulations sold in Brazil, while INMETRO administers mandatory conformity assessment programs verifying performance claims against ABNT technical standards. The national petroleum regulator, ANP, monitors fuel-lubricant interaction compliance as ethanol blending ratios fluctuate seasonally. Stakeholders must track proposed updates to PROCONVE emission tiers, which will force reformulation of lower-viscosity grades to protect after-treatment systems.
Market Dynamics
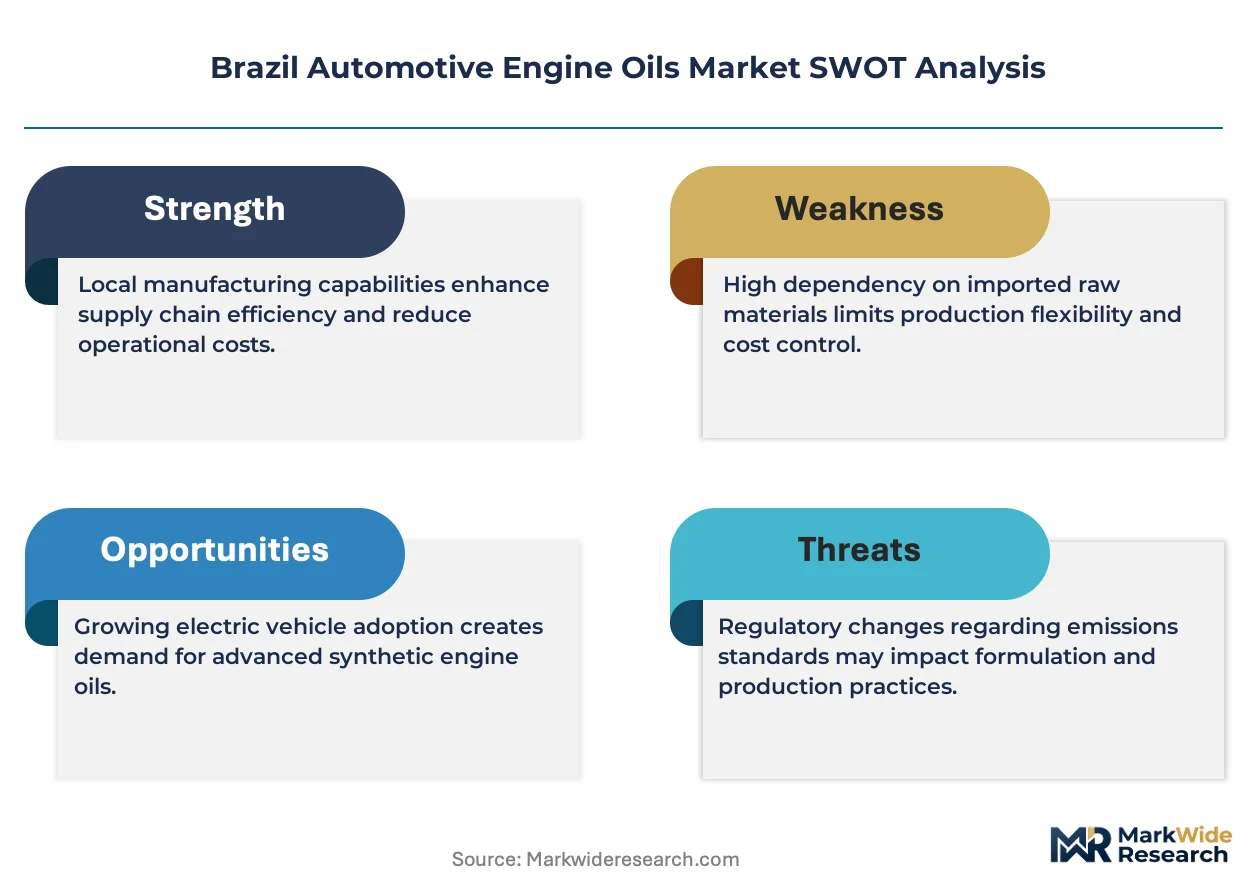
Brazil's automotive engine oils sector faces structural pressure from PROCONVE emission tier upgrades forcing viscosity grade reformulation, while flex-fuel engine proliferation demands oxidation-resistant additive chemistry adapted to variable ethanol blends.
Growth Catalysts
- PROCONVE Tier Advancement:Tighter emission standards mandate lower-viscosity lubricants protecting after-treatment systems, pulling demand toward synthetic formulations certified by INMETRO.
- Fleet Synthetic Conversion:São Paulo commercial transport operators are accelerating bulk procurement of synthetic grades to extend drain intervals and reduce downtime.
- Southeastern Manufacturing Concentration:Automotive assembly clusters around São Paulo state generate captive demand for OEM-fill and service-fill lubricant volumes.
Market Restraints
- Base Oil Import Dependence:API Group II/III base stock supply concentrates on Gulf Coast US and Asian refinery complexes, exposing blenders to freight cost volatility and currency fluctuation.
- ANVISA Registration Timelines:Chemical substance disclosure requirements extend new product introduction cycles, compressing window for formulation innovation.
- Conventional Segment Stickiness:Independent aftermarket channels retain price-sensitive volume demand resistant to synthetic upgrade, limiting premium penetration.
Strategic Opportunities
- Northeastern Distribution Gap:Pernambuco and Bahia states lack dedicated lubricant blending capacity, creating white space for regional bulk supply hubs.
- Ethanol-Optimized Additive Packages:Formulation chemistry addressing acidic combustion byproducts from high-ethanol blends offers differentiation in flex-fuel dominant parc.
- Controlled-Atmosphere Packaging:Modular bulk-to-retail configurations reduce contamination risk and extend shelf stability for tropical storage conditions.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in ethanol-compatible additive synergy remains concentrated among legacy blender technical teams.
- ABNT Certification Bottleneck:INMETRO conformity assessment queue delays performance claim verification, constraining marketing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Engine Oils Market |
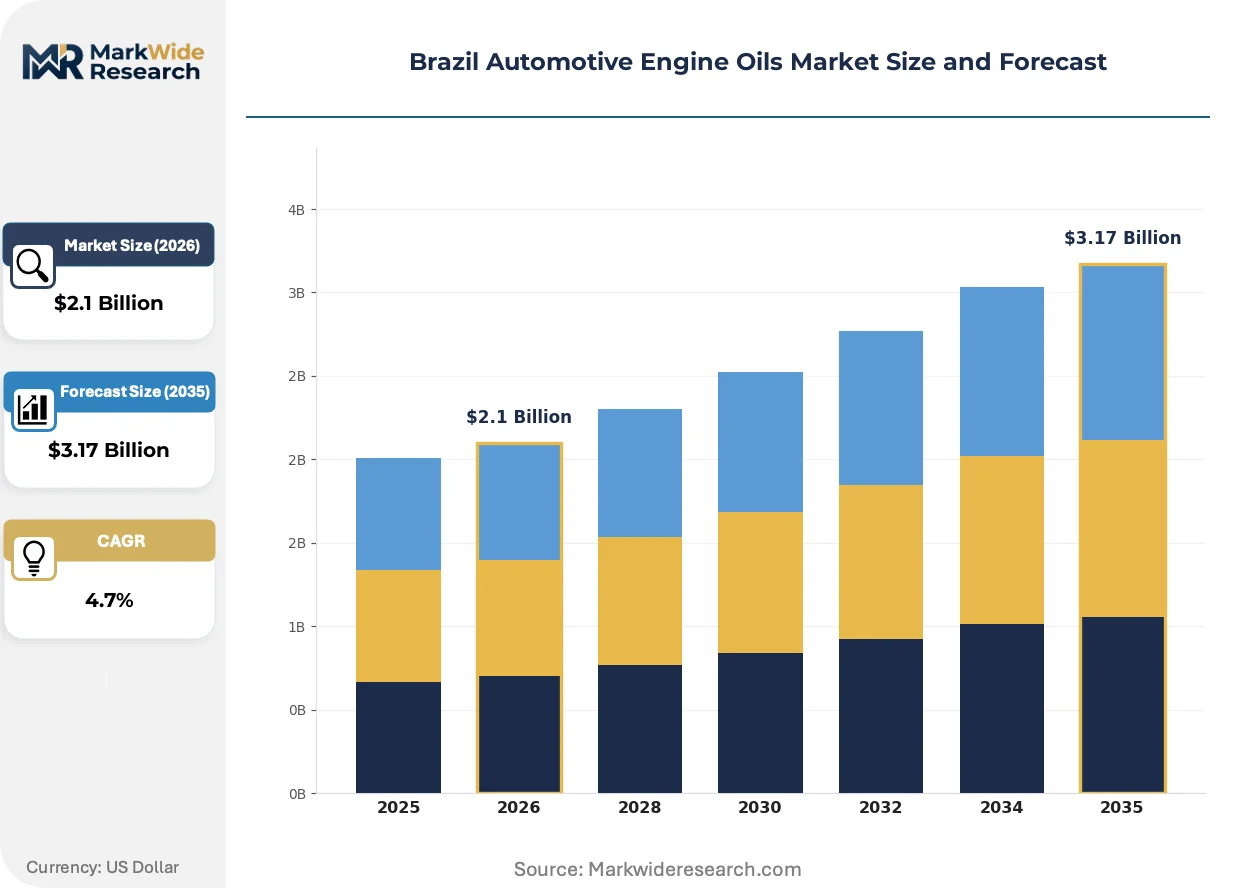
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Conventional, High Mileage Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bulk, Bottle, Can, Drum Distribution Channel: Retail, Online, Wholesale, Service Station |
| Companies Covered | Iconic Lubrificantes, TotalEnergies, Petrobras, Energis 8 Brasil, Gulf Oil International, ExxonMobil Corporation, Petronas Lubricants International, Lucheti Lubrificantes, Royal Dutch Shell Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Engine Oils Market Strategic Shifts
Formulation chemistry and distribution architecture are converging around ethanol adaptation and modular logistics, reshaping how lubricants move from refinery to service bay across Brazil's tropical operating environment.
Polyalphaolefin (PAO) synthetic base stocks are expanding into mainstream service-fill segments previously dominated by mineral formulations. Independent quick-lube chains in Minas Gerais and Rio de Janeiro are adopting PAO blends for mid-tier service packages. This expansion is compressing price premiums between synthetic and conventional grades, forcing reformulation economics toward additive differentiation rather than base oil cost arbitrage.
ANVISA's chemical substance registry requirements are tightening environmental safety disclosure thresholds for lubricant formulations. Blenders must now submit comprehensive toxicological profiles for additive components previously exempt from notification. São Paulo-based formulators are responding by consolidating supplier relationships to reduce registration burden, favoring additive houses with established Brazilian dossiers.
Fleet maintenance departments are consolidating lubricant procurement under annual volume contracts with technical service bundling. Large transport operators in the Mercosul corridor are displacing spot purchasing from distributor networks with direct blender relationships. This concentration is most visible among refrigerated cargo fleets operating between São Paulo and Porto Alegre, where unified drain interval management reduces total fluid cost per kilometer.
Brazil Automotive Engine Oils Market Segmentation
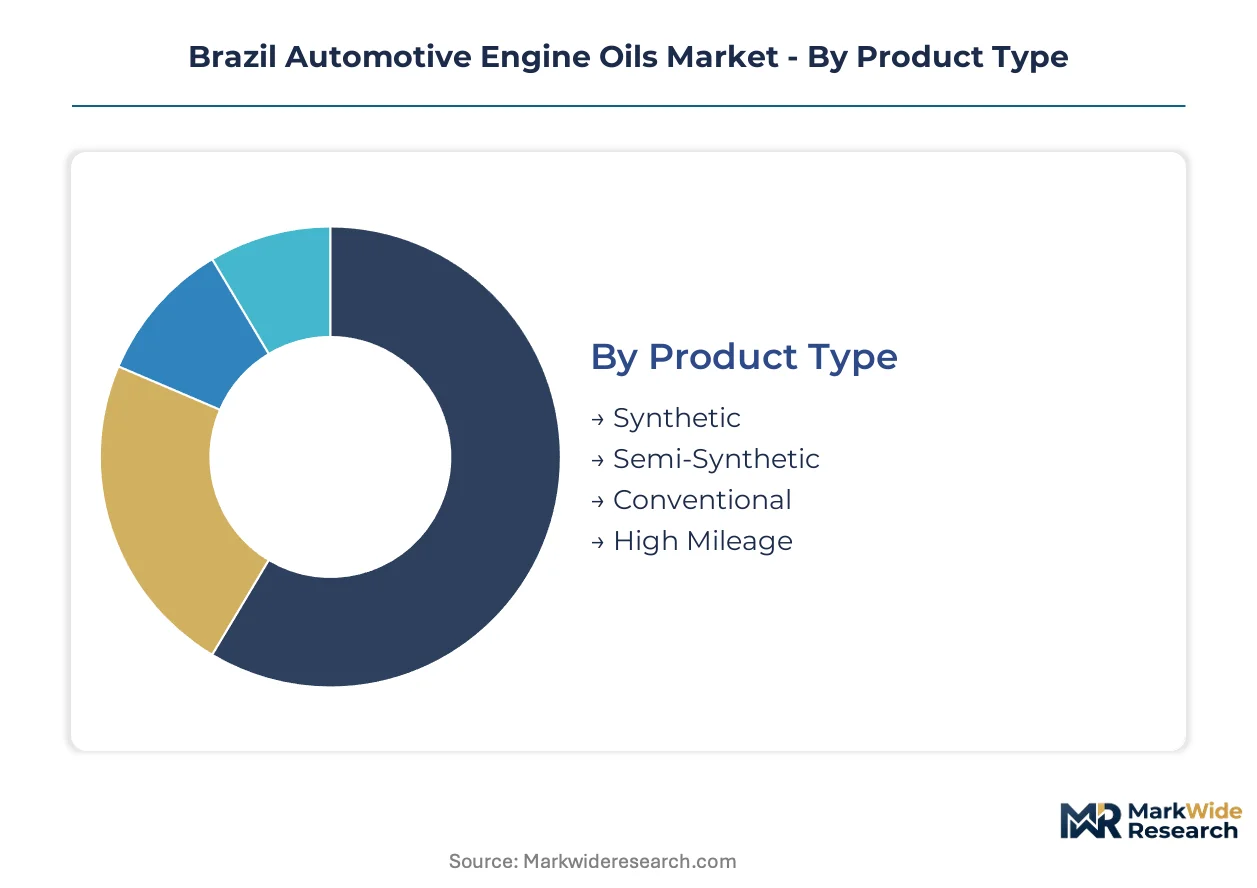
Brazil's automotive engine oils market segments across formulation chemistry, mechanical specification, logistics format, and route-to-customer architecture. Each dimension carries distinct margin profiles and regulatory exposure, shaping how blenders allocate technical resources and distribution investment.
Product Type:
Formulation chemistry spans the premiumization arc from mineral base stocks to engineered synthetics, with positioning driven by OEM certification requirements and drain interval economics.
- Synthetic:PAO and Group III base stocks deliver thermal stability for PROCONVE Tier 3/4 after-treatment protection. Fleet operators in São Paulo's refrigerated cargo corridors specify synthetics to extend drain intervals beyond 15,000 kilometers.
- Semi-Synthetic:Blended formulations balance cost and performance for independent quick-lube chains in Minas Gerais. These products capture service-fill demand from vehicle owners seeking upgrade from conventional without full synthetic pricing.
- Conventional:Mineral base stocks retain volume dominance in price-sensitive aftermarket channels across Brazil's interior states.
- High Mileage:Seal conditioner additives target vehicles exceeding 100,000 kilometers in Brazil's aging parc.
Most installed capacity flows through Conventional. Expansion is steepest in Synthetic.
Viscosity Grade:
Grade specification tracks engine architecture evolution, with Brazilian OEMs tightening toward lower-viscosity fills for fuel economy compliance.
- 0W-20:Ultra-low viscosity formulations reduce cold-start friction for modern flex-fuel engines. OEM fill specifications from São Paulo-state assembly plants are pulling this grade into mainstream service-fill channels.
- 5W-30:The workhorse specification balances tropical temperature performance with fuel economy gains. Independent workshops in Rio de Janeiro specify this grade for mixed-service applications.
- 10W-40:Legacy grade retains position in older vehicle segments and high-temperature operating conditions.
- 15W-50:Heavy-duty viscosity for commercial transport operating in Brazil's northern regions with elevated ambient temperatures.
Blend capacity concentrates on 5W-30. 0W-20 is climbing the fastest as OEM specifications tighten.
Packaging Type:
Logistics format determines contamination risk, handling economics, and customer access patterns across Brazil's tropical distribution environment.
- Bulk:Tanker and tote deliveries serve fleet maintenance depots with controlled-atmosphere transfer systems. Large transport operators along the Mercosul corridor specify bulk to minimize packaging waste and per-liter cost.
- Bottle:Retail-format polyethylene containers dominate independent aftermarket sales through auto parts distributors.
- Can:Metal packaging persists in premium positioning and export-oriented product lines.
- Drum:Intermediate bulk format serves industrial maintenance accounts and regional distributor stocking.
Volume throughput peaks in Bottle. Strategic investment is concentrating in Bulk.
Distribution Channel:
Route-to-market architecture separates spot purchasing from contracted supply, with channel choice determining price realization and technical service bundling.
- Retail:Auto parts chains and hypermarkets serve individual vehicle owners with immediate-need purchasing. Shelf placement in São Paulo's automotive districts drives brand visibility for premium formulations.
- Online:E-commerce platforms are capturing DIY maintenance demand, particularly for specialized viscosity grades with limited physical distribution.
- Wholesale:Distributor networks aggregate volume for independent workshops across Brazil's secondary cities.
- Service Station:Branded forecourt presence enables impulse purchase and emergency top-off demand in major metropolitan corridors.
Transaction volume flows through Retail. Digital penetration is expanding most quickly in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's automotive engine oils industry traces its modern scale to Petrobras' captive refinery investments during the 1970s national oil development program. State-led infrastructure anchored domestic blending capacity before multinational entry accelerated technical advancement. Today demand concentrates in southeastern manufacturing corridors while regulatory pressure reshapes formulation requirements nationwide.
São Paulo
São Paulo state's automotive assembly clusters generate captive OEM-fill and service-fill lubricant volumes. ANVISA chemical disclosure requirements tighten fastest here due to proximity to regulatory headquarters. Fleet operators in the metropolitan corridor specify synthetic grades for refrigerated cargo transport along the Mercosul highway.
Minas Gerais
Independent quick-lube chains in Belo Horizonte and surrounding industrial cities adopt semi-synthetic formulations for mid-tier service packages. INMETRO conformity assessment queues concentrate technical verification capacity in this southeastern hub. Mining equipment maintenance in the Iron Quadrangle sustains demand for heavy-duty viscosity grades.
Rio de Janeiro
Port infrastructure and petrochemical complexes support base oil import handling and coastal distribution logistics. PROCONVE emission tier enforcement tightens fastest in this regulatory coordination zone. Independent workshops across the metropolitan area specify 5W-30 as the workhorse grade for mixed-service applications.
Rio Grande do Sul
Southern Brazil's agricultural machinery parc sustains conventional oil demand resistant to synthetic upgrade. ANP fuel-lubricant interaction monitoring intensifies here due to seasonal ethanol blending fluctuations. Porto Alegre serves as the terminal node for Mercosul corridor fleet logistics extending into Uruguay and Argentina.
Bahia
Northeastern distribution gaps in lubricant blending capacity create white space for regional bulk supply hub development. Federal industrial development incentives target petrochemical investment in the Camaçari complex. Temperature extremes in the interior sertão sustain demand for high-viscosity formulations in commercial transport.
Brazil Automotive Engine Oils Market Competitive Environment
The competitive structure tilts toward integrated national oil companies with captive refinery access. Market concentration remains moderate with multinational majors competing against domestic blenders for fleet and retail channels. Three archetypes dominate: state-linked energy conglomerates with backward integration into base stocks, global lubricant specialists with formulation technology licensing, and regional distributors with logistics intimacy in secondary cities. Capacity expansion and portfolio diversification toward synthetic grades constitute the dominant competitive moves.
Among integrated energy conglomerates, Petrobras anchors supply security through captive refinery infrastructure. Global lubricant specialists ExxonMobil Corporation and Royal Dutch Shell Plc occupy positions emphasizing synthetic formulation portfolios and controlled retail presence. Domestic blenders Iconic Lubrificantes and Lucheti Lubrificantes exemplify regional distribution archetypes with logistics networks penetrating Brazil's interior states. Gulf Oil International and Petronas Lubricants International represent mid-tier multinational entrants competing through technical service bundling for fleet accounts.
| Leading Market Players |
|---|
| Iconic Lubrificantes |
| TotalEnergies |
| Petrobras |
| Energis 8 Brasil |
| Gulf Oil International |
| ExxonMobil Corporation |
| Petronas Lubricants International |
| Lucheti Lubrificantes |
| Royal Dutch Shell Plc |
| Others |
Value Chain & Pricing Dynamics
API Group II/III base stock costs transmit directly from Gulf Coast US and Asian refinery complexes into Brazilian blender pricing tiers, with freight volatility and currency fluctuation compressing margins most acutely at the conventional segment before amplifying through semi-synthetic and synthetic grades.
Pricing Analysis
Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy conventional levels anchors the market, with differentiation driven by INMETRO certification tier and volume scale in fleet contracting. Cost compression in conventional grades intensifies because independent aftermarket channels retain price-sensitive volume demand resistant to upgrade. Fleet operators exhibit lowest price sensitivity due to drain interval economics, while individual vehicle owners through retail auto parts chains show highest sensitivity.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand through annual volume contracts with technical service bundling, displacing spot purchasing from distributor networks. Raw material supply draws from US Gulf Coast, South Korea, and Singapore refinery complexes for API Group II/III base stocks, with additive packages sourced from established houses with Brazilian ANVISA dossiers. Single-source vulnerability concentrates in Group III synthetic base oil supply during peak PROCONVE reformulation cycles. Distribution runs through Petrobras captive refinery infrastructure for bulk fleet contracts, branded service station networks for retail impulse demand, and independent distributor webs for interior state penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's automotive engine oils market functions as a regulatory compounder where PROCONVE Tier 3/4 emission advancement mandates systematic reformulation toward lower-viscosity synthetic grades, forcing continuous technical investment and certification renewal across the supply base.
For Market Incumbents: Anticipate margin compression from flex-fuel engine chemistry demands and ethanol-optimized additive package requirements by deepening backward integration into captive base oil supply and consolidating ANVISA registration dossiers with fewer additive houses to reduce compliance burden. Prioritize capacity positioning in São Paulo's southeastern corridor where OEM-fill specifications tighten fastest. For New Entrants and Emerging Players: Refrigerated cargo fleet operators in the Mercosul corridor represent an underserved buyer archetype ripe for direct blender relationships with unified drain interval management and technical service bundling. White space concentrates in Pernambuco and Bahia bulk supply hub development and ethanol-optimized formulation chemistry for high-ethanol blend combustion byproducts. Enter through controlled-atmosphere packaging innovation for tropical storage conditions. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity concentrates among legacy blender technical teams and ABNT certification bottlenecks delay performance claim verification. Long-term viability favors blenders with established ANVISA dossiers and INMETRO conformity assessment track records over asset-light distributors. Monitor INMETRO queue length as inflection indicator for marketing timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive refinery access insulates Petrobras from Gulf Coast freight volatility and currency exposure. |
| Ethanol-Optimized Additive Package Development | Formulation chemistry addressing acidic combustion byproducts differentiates in flex-fuel dominant parc. |
| Controlled-Atmosphere Packaging Expansion | Modular bulk-to-retail configurations reduce contamination risk for tropical storage conditions. |
| Direct Fleet Relationship Consolidation | Annual volume contracts with technical bundling displace spot purchasing in Mercosul corridor. |
| ANVISA Dossier Consolidation | Supplier relationship reduction with established Brazilian additive houses accelerates new product introduction. |
Study Parameters
Bottom-up fleet operator and independent workshop modeling reconciled against top-down refinery output and import tracking forms the analytical core. Primary interviews with lubricant formulation chemists, fleet maintenance directors, auto parts distributor procurement managers, and ANVISA regulatory affairs specialists combined with secondary validation from ANP fuel-lubricant interaction reports, INMETRO conformity assessment databases, ABNT technical standard filings, and customs trade records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of synthetic conversion rates, viscosity grade migration, and packaging format shifts informs the projection framework across the analysis window. Segmentation dimensions span formulation chemistry, viscosity specification, packaging logistics, and route-to-customer architecture, with additional modeling of ethanol blend adaptation requirements. CAGRs derive from regression against PROCONVE tier implementation schedules and OEM fill specification tightening curves.
Underlying measurement precision varies by segment; synthetic grade demand and fleet channel volumes carry tighter precision than conventional aftermarket estimates. Forecasts reflect assumptions around PROCONVE enforcement timing, ethanol blend ratio stability, and base oil import cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Brake Booster Market
Powertrain
Crankshaft Oil Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Automotive Power Modules Market
Powertrain
Automotive Drivetrain Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
EV Powertrain Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Gear Oil Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Powertrain Domain Control Unit Platforms Market