
 North America Electrically Powered Hydraulic Steering Market | 2026-2036
North America Electrically Powered Hydraulic Steering Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electrically Powered Hydraulic Steering Market Analytics
The EPA Corporate Average Fuel Economy standards is decoupling hydraulic steering architectures from pure engine-driven designs across North American vehicle programs. JTEKT Corporation leverages its Kokomo, Indiana manufacturing footprint to supply integrated steering columns for light truck platforms. Robert Bosch GmbH sustains development of modular electro-hydraulic power packs that reduce parasitic engine load. ZF Friedrichshafen AG anchors its North American steering business through its Livonia, Michigan technical center, where engineers calibrate variable ratio systems for full-size pickup applications.
Electrically powered hydraulic steering combines an electric motor-driven hydraulic pump with conventional rack-and-pinion or recirculating-ball steering gears, typically operating at fluid pressures between 1,200 and 1,500 psi to deliver variable assist without continuous engine belt drive. The architecture preserves hydraulic road feel while enabling on-demand pump operation that cuts fuel consumption. Passenger car applications of active steering technology command premium pricing due to integration complexity with advanced driver assistance systems. Heavy duty truck demand for dual pinion steering configurations is expanding fastest among vehicle type segments, driven by commercial fleet requirements for maneuverability in urban delivery routes.
NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and electronic control unit reliability across United States vehicle certification programs. EPA emissions regulations and California Air Resources Board zero-emission vehicle mandates indirectly shape steering electrification timelines by pressuring powertrain efficiency gains. Transport Canada Motor Vehicle Safety Regulations align with United States standards through bilateral regulatory cooperation, streamlining cross-border component approvals. Stakeholders must monitor how forthcoming heavy-duty vehicle greenhouse gas rules in both countries redefine pump efficiency thresholds and control software validation requirements.
Market Dynamics
The EPA Corporate Average Fuel Economy standards are decoupling hydraulic steering architectures from pure engine-driven designs across North American vehicle programs. This regulatory pressure is forcing automakers to adopt electro-hydraulic systems that preserve road feel while eliminating parasitic engine load.
Growth Catalysts
- NHTSA Fuel Economy Mandates:Light truck fleets across the United States and Canada must meet escalating efficiency thresholds that electro-hydraulic steering directly addresses through on-demand pump operation.
- Dual Pinion Configurations:Heavy duty truck demand for maneuverability in urban delivery routes is accelerating adoption of advanced steering geometries that reduce turning radius without compromising load capacity.
- Detroit Three Integration:Michigan and Ontario manufacturing corridors concentrate engineering resources for full-size pickup platforms where variable ratio systems command premium positioning.
Market Restraints
- Hydraulic Fluid Cost Volatility:Synthetic hydraulic fluid formulations face petrochemical feedstock price swings that compress margin structures for pump and gear suppliers.
- Full Electric Steering Substitution:Steer-by-wire architectures eliminate hydraulic components entirely, threatening electro-hydraulic's intermediate position as battery costs decline and motor power density improves.
- Transport Canada Regulatory Friction:Bilateral alignment with United States standards occasionally lags on electronic control unit validation timelines, delaying cross-border platform launches.
Strategic Opportunities
- Active Steering Integration:Convergence with advanced driver assistance systems creates white space for premium passenger car applications where variable ratio calibration enhances lane-keeping performance.
- Zero-Emission Vehicle Mandates:California Air Resources Board requirements indirectly accelerate steering electrification timelines by pressuring comprehensive powertrain efficiency gains across light and medium duty segments.
- Urban Commercial Fleets:Last-mile delivery operators in Canadian metropolitan corridors represent underpenetrated demand for compact electro-hydraulic systems suited to cab-over-engine configurations.
Industry Challenges
- Control Software Validation:NHTSA Federal Motor Vehicle Safety Standards demand rigorous electronic control unit reliability testing that extends certification timelines and strains embedded systems engineering capacity.
- Legacy Platform Integration:Full-size pickup architectures with decades of recirculating-ball heritage require extensive recalibration of steering feel maps when transitioning to electro-hydraulic assist curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electrically Powered Hydraulic Steering Market |
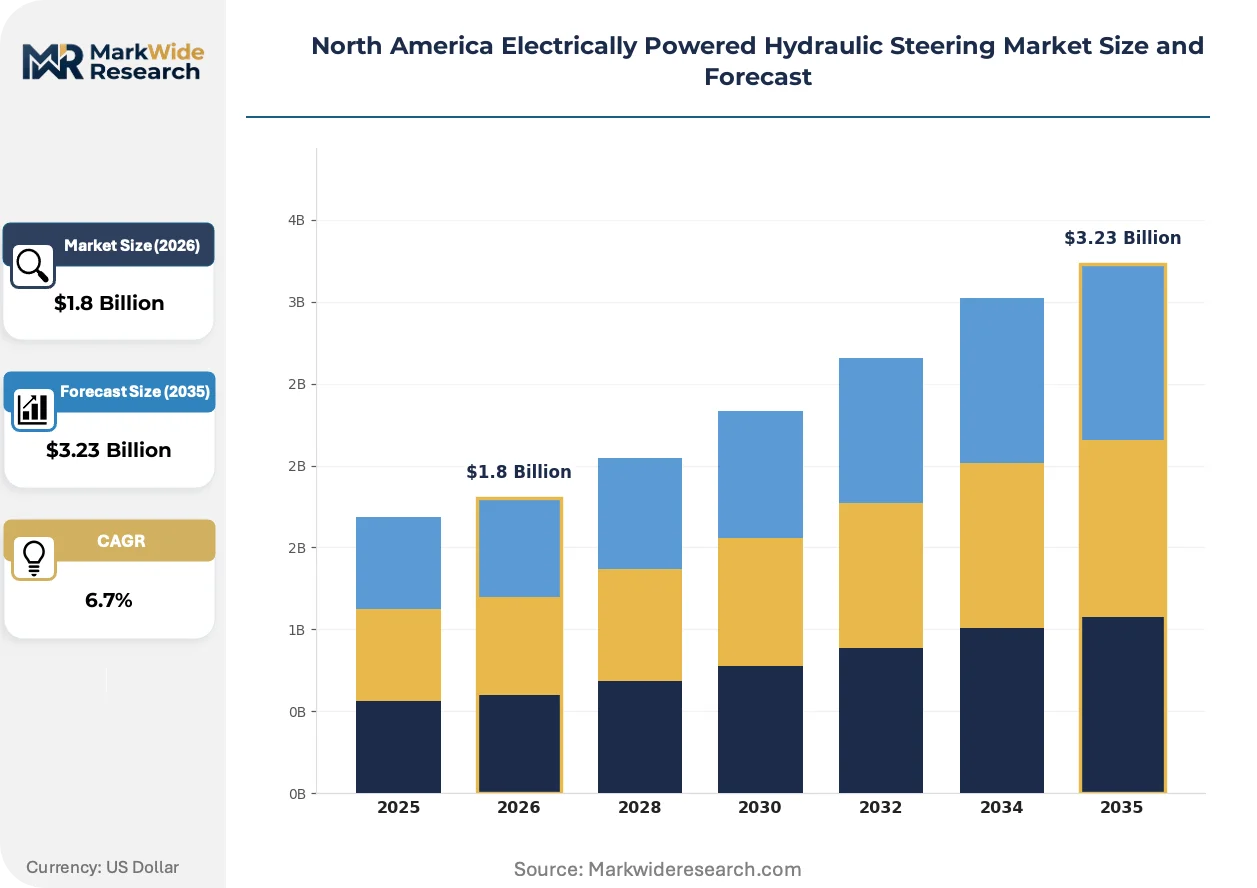
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Steering, Power Assisted Steering, Variable Ratio Steering, Dual Pinion Steering Vehicle Type: Passenger Cars, Light Trucks, Heavy Duty Trucks, SUVs End User: OEMs, Aftermarket, Fleet Operators, Commercial Vehicles System Component: Sensor Units, Control Units, Electric Motors, Hydraulic Pumps |
| Companies Covered | JTEKT Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Nexteer Automotive, NSK Ltd, Danfoss, Continental AG, Thyssenkrupp Presta AG, Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electrically Powered Hydraulic Steering Market Evolving Landscape
Active steering technology is reshaping competitive positioning across the North American electrically powered hydraulic steering market. Three developments are compressing development cycles and redefining system integration requirements.
Modular electro-hydraulic power packs are expanding into full-size pickup and heavy duty truck segments where variable displacement pumps enable precise flow matching to steering load. Commercial fleet operators adopting these configurations report measurable fuel economy improvements during urban delivery cycles. The technology is expanding into previously cost-excluded medium duty applications as manufacturing scale reduces unit economics.
EPA emissions regulations and California Air Resources Board zero-emission vehicle mandates are compressing steering electrification timelines across Detroit Three vehicle programs. Manufacturers must demonstrate powertrain efficiency gains that electro-hydraulic architectures uniquely deliver through on-demand pump operation. Heavy duty truck segments face the most acute compliance pressure, driving fastest adoption of dual pinion configurations with integrated electronic control.
After-sales service unbundling is disrupting traditional distribution relationships between steering system suppliers and commercial fleet operators. Direct procurement of replacement power packs and control modules through authorized technical centers is displacing dealer-channel dependence for maintenance-intensive urban delivery vehicles. This pattern concentrates in United States metropolitan corridors where fleet density supports dedicated service infrastructure investment.
North America Electrically Powered Hydraulic Steering Market Segmentation
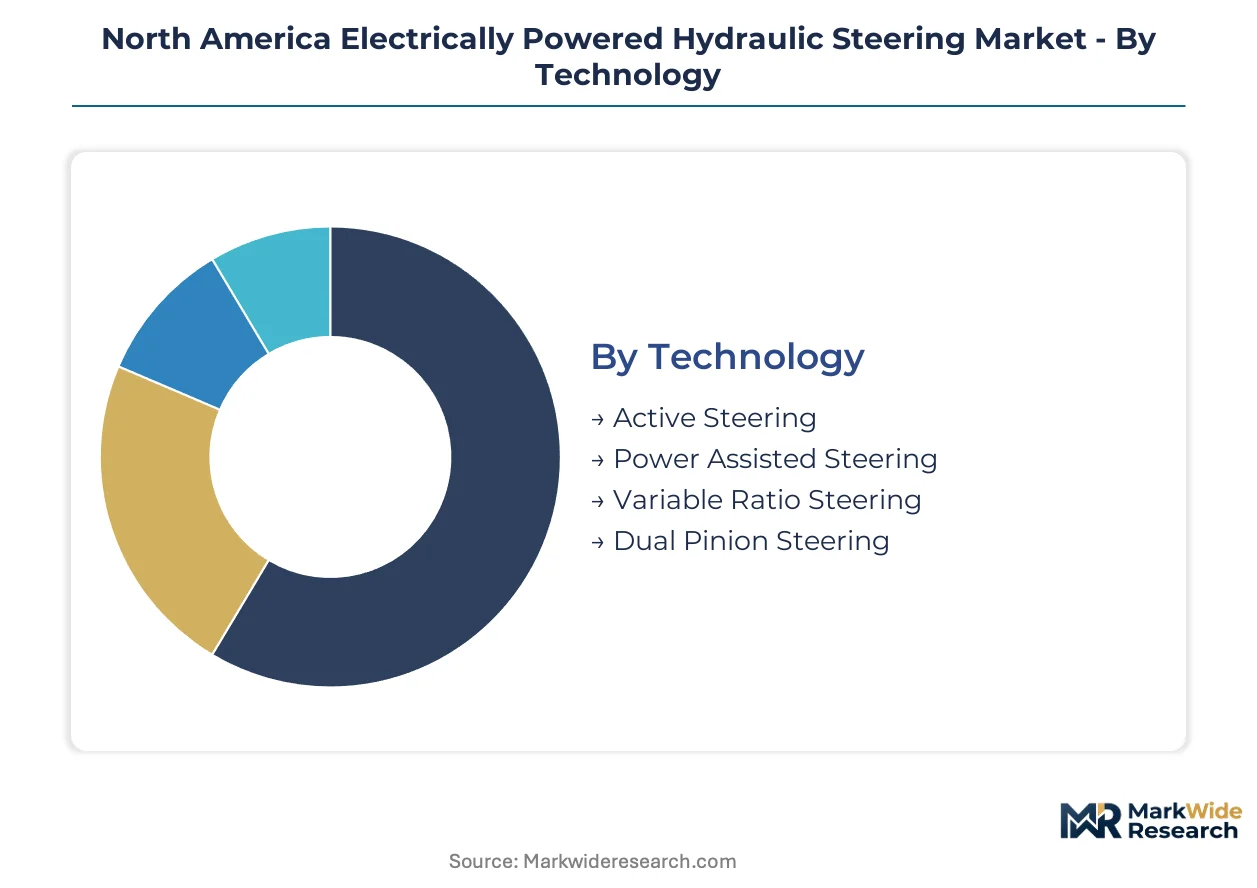
Electro-hydraulic steering architectures diverge sharply across vehicle platforms and duty cycles. Technology choices determine fuel economy compliance margins, while component sourcing strategies reshape supplier relationships across Michigan and Ontario manufacturing corridors.
Technology:
Cost tier separates premium calibration capabilities from commodity assist functions.
- Active Steering:Integrates variable ratio mapping with lane-keeping assistance through electronic control units that modulate hydraulic flow in real-time. Passenger car programs in California and Ontario specify these systems for premium trim levels where NHTSA safety ratings influence purchase decisions.
- Dual Pinion Steering:Employs two mesh points between rack and steering gear to reduce driver effort during low-speed maneuvering without hydraulic flow spikes. Heavy duty truck fleets operating urban delivery routes across Chicago and Toronto corridors specify these configurations to cut driver fatigue and insurance incident rates.
- Power Assisted Steering:Conventional electro-hydraulic architecture with fixed assist curves and on-demand pump operation.
- Variable Ratio Steering:Modifies steering sensitivity based on vehicle speed through electronically controlled valve timing.
Power Assisted Steering leads volumes today; Active Steering is gaining share fastest.
Vehicle Type:
Application duty cycle dictates hydraulic pressure specifications and pump displacement requirements.
- Heavy Duty Trucks:Demand 1,500 psi operating pressures and high-flow pumps to manage loaded axle weights during urban delivery cycles. Fleet operators across Texas and California corridors specify electro-hydraulic retrofits to meet EPA greenhouse gas phase 2 compliance deadlines.
- Light Trucks:Full-size pickup platforms from Detroit Three automakers integrate modular power packs that cut parasitic load during highway cruising. Michigan assembly plants concentrate procurement for F-150, Silverado, and Ram 1500 programs where fuel economy certification determines model year viability.
- Passenger Cars:Compact and mid-size sedans with rack-and-pinion architectures.
- SUVs:Crossover platforms blending car-like steering precision with truck-grade durability requirements.
Light Trucks dominate current installations; Heavy Duty Trucks show the steepest expansion trajectory.
End User:
Procurement authority determines warranty terms, service intervals, and software update protocols.
- Fleet Operators:Last-mile delivery companies across United States metropolitan corridors negotiate direct service contracts with technical centers in Livonia and Kokomo. These buyers unbundle maintenance from dealer channels, procuring replacement power packs and control modules through authorized facilities to minimize vehicle downtime.
- OEMs:Detroit Three automakers specify integrated steering columns for new vehicle programs.
- Aftermarket:Independent repair facilities serving aging vehicle populations.
- Commercial Vehicles:Vocational truck buyers with specialized body equipment requirements.
OEMs command the largest revenue share; Fleet Operators are expanding procurement fastest.
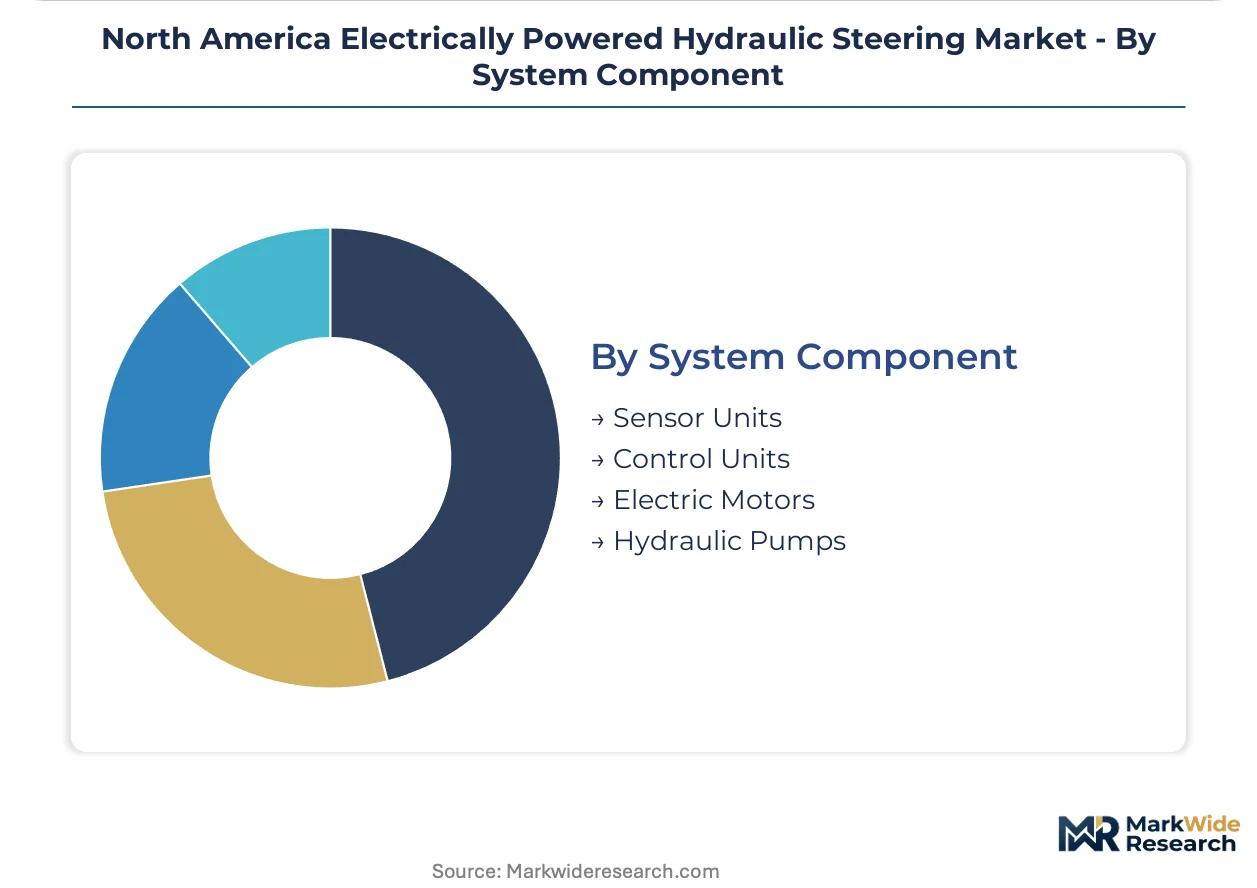
System Component:
Supply concentration varies by electronic versus hydraulic content, with distinct manufacturing footprints.
- Control Units:Embedded software validation for NHTSA Federal Motor Vehicle Safety Standards compliance extends development timelines. Suppliers calibrate these units at Livonia technical centers where full-size pickup steering feel maps require extensive recalibration from legacy recirculating-ball baselines.
- Hydraulic Pumps:Variable displacement designs enable on-demand flow matching that cuts fuel consumption during straight-line highway operation. Indiana manufacturing corridors concentrate production for light truck programs where scale economies compress unit costs.
- Sensor Units:Torque and position feedback devices for closed-loop control.
- Electric Motors:Brushless DC drives powering hydraulic pump shafts.
Hydraulic Pumps generate the highest shipment volumes; Control Units are climbing the fastest as software content expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electro-hydraulic steering scaled from Detroit's post-war automotive corridor, where integrated power steering first merged hydraulic assist with engine-driven pumps. The technology migrated to electrically driven architectures as NHTSA fuel economy mandates intensified. Today, manufacturing concentrates in Great Lakes industrial clusters serving Detroit Three programs.
United States
EPA Corporate Average Fuel Economy standards force light truck electrification of steering assist. NHTSA Federal Motor Vehicle Safety Standards govern electronic control unit validation for full-size pickup platforms. Michigan's Livonia-Kokomo corridor anchors calibration engineering and pump manufacturing for F-150, Silverado, and Ram programs.
Canada
Transport Canada Motor Vehicle Safety Regulations align with United States standards through bilateral cooperation, streamlining cross-border component approvals. Ontario's Windsor-Toronto manufacturing belt concentrates demand for integrated steering columns serving Detroit Three assembly plants. Fleet operators in Toronto and Vancouver metropolitan corridors accelerate procurement of compact electro-hydraulic systems for urban delivery routes.
Mexico
Nearshored automotive assembly expansion creates incremental demand for electro-hydraulic steering modules in light truck platforms. Mexico's national automotive regulator enforces safety standards harmonized with United States FMVSS benchmarks. Nuevo León and Bajío Region industrial parks attract tier-one steering component suppliers establishing regional technical centers.
North America Electrically Powered Hydraulic Steering Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the electro-hydraulic steering supply base. Integrated system suppliers with captive manufacturing assets dominate procurement relationships with Detroit Three automakers. Three archetypes define competitive positioning: full-system integrators owning column-to-pump vertical scope; modular power pack specialists supplying standardized electro-hydraulic units; and regional steering gear fabricators serving aftermarket channels. Dominant competitive moves include backward integration into electric motor manufacturing and geographic co-location with Michigan-Ontario assembly corridors.
Among full-system integrators, JTEKT Corporation occupies a position exemplifying Japanese engineering presence in Indiana manufacturing corridors. Robert Bosch GmbH anchors European technology transfer through modular electro-hydraulic development. ZF Friedrichshafen AG represents German industrial consolidation, sitting within the premium-tier supplier segment through its Livonia technical center concentration.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Nexteer Automotive |
| NSK Ltd |
| Danfoss |
| Continental AG |
| Thyssenkrupp Presta AG |
| Mando Corporation |
| Others |
Value Network & Pricing Analysis
Captive manufacturing of electronic control units at Livonia and Kokomo technical centers anchors supplier pricing power while compressing margin exposure to hydraulic fluid feedstock volatility. This backward integration into embedded software calibration allows full-system integrators to defend premium positioning against modular power pack specialists serving cost-sensitive fleet operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates active steering systems with ADAS integration from dual pinion configurations and conventional power assisted architectures. Price differentiation hinges on NHTSA safety certification tier and volume scale commitments from Detroit Three OEMs versus aftermarket procurement. Cost compression in economy tiers is intensifying because synthetic hydraulic fluid formulations face petrochemical price swings. Fleet operators exhibit highest price sensitivity due to unbundled procurement models, while OEMs accept premium positioning for integrated steering columns.
Supply Chain Analysis
Remanufacturing flows for control modules and power packs concentrate in Michigan and Indiana corridors where authorized technical centers process warranty returns from urban delivery fleets. Component sourcing draws from Mexico for electric motors, Canada for precision-machined steering gears, and domestic suppliers for variable displacement pumps. Single-source vulnerability sits with specialized torque sensor fabrication. Distribution runs through tier-one supplier direct contracts with Detroit Three assembly plants, bypassing traditional dealer channels for fleet maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Michigan's engineering density and Mexico's manufacturing labor differential creates margin expansion opportunities for suppliers establishing cross-border technical centers. NHTSA and Transport Canada regulatory alignment streamlines platform certification costs across the Great Lakes corridor.
For Market Incumbents: Hedge against steer-by-wire substitution by deepening embedded software capabilities for active steering calibration at Livonia technical centers. Secure captive supply of brushless DC motors through capacity addition in Nuevo León industrial parks. Defend OEM relationships through exclusive lane-keeping algorithm development that modular power pack specialists cannot replicate. For New Entrants and Emerging Players: Launch via direct service contracts with last-mile delivery operators in Toronto and Vancouver metropolitan corridors, bypassing entrenched dealer channels. Target compact electro-hydraulic retrofits for cab-over-engine configurations where incumbent coverage remains thin. White space exists in aftermarket control module refurbishment for aging Detroit Three full-size pickup platforms. For Investors and Strategic Acquirers: Roll-up economics work for regional steering gear fabricators because fragmented aftermarket channels lack scale to negotiate direct procurement with fleet operators. Five-to-ten year viability hinges on software-defined vehicle integration timelines. Monitor California Air Resources Board zero-emission vehicle mandate acceleration as the inflection signal for electro-hydraulic versus full electric steering substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces calibration complexity across F-150, Silverado, and Ram 1500 programs sharing modular power pack architectures. |
| Battery Supply Agreement | Secures brushless DC motor inputs from Mexico-based producers serving Kokomo manufacturing corridors. |
| Software-Defined Vehicle Investment | Enables over-the-air steering feel map updates for fleet operators unbundled from dealer service channels. |
| Geographic Manufacturing Footprint | Positions technical centers in Michigan-Ontario corridor to exploit NHTSA-Transport Canada regulatory harmonization. |
| Charging Infrastructure Partnership | Irrelevant for electro-hydraulic architectures; substitute with Active Steering Integration Partnership aligning ADAS roadmap with Detroit Three platform engineers. |
Research Methodology
Direct dialogue with OEM platform engineers, tier-one supplier procurement directors, fleet maintenance operations heads, and aftermarket distribution channel managers grounded qualitative findings. Secondary validation drew from NHTSA FMVSS certification databases, EPA fuel economy compliance filings, vehicle production registration data, and Transport Canada safety standard harmonization protocols. Bottom-up component shipment analysis triangulated against top-down Detroit Three platform content assumptions.
Segment-level value outputs across technology, vehicle type, end user, and system component dimensions were derived through structured market modeling. CAGRs were computed from annual installation rates projected against NHTSA fuel economy mandate phase-in schedules and EPA greenhouse gas rule compliance deadlines. Industry-specific inputs included hydraulic pump displacement specifications by vehicle class and electronic control unit software validation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated steer-by-wire adoption or hydraulic fluid supply disruption scenarios. Practitioners should monitor California ZEV mandate stringency and heavy-duty vehicle greenhouse gas rule finalization for early signals of electro-hydraulic substitution risk.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Global Driveline Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive TCU Market
Powertrain
Torque Limiter Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Automotive Fuel Pulsation Damper Market