
 Malaysia Brake Pads Market | 2026-2036
Malaysia Brake Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Brake Pads Market Outlook
Ceramic friction formulations is rebalancing cost-performance trade-offs across mid-range vehicle segments. Robert Bosch GmbH leverages its integrated sensor-to-pad systems architecture to sustain premium positioning in passenger vehicle fitments. Brembo S.p.A. dominates performance-tier supply through motorsport-derived thermal management technologies. Akebono Brake Industry Co., Ltd. specializes in copper-free formulations that navigate tightening environmental protocols.
Brake pads are friction-generating components installed in disc brake systems, typically comprising bonded fricative materials, thermoset resins, reinforcing fibers, and metallic fillers compressed under 10-20 MPa and cured at 150-250°C to achieve specified coefficient of friction and wear rates; they convert kinetic energy into thermal energy to decelerate or immobilize wheeled vehicles. Semi-metallic formulations lead volume share due to thermal durability under Malaysian tropical operating conditions, while ceramic segments command margin premiums from low-dust and noise-dampening properties. Aftermarket Providers represent the fastest-growing end-user channel as vehicle parc expansion outpaces original equipment assembly rates.
The Road Transport Department enforces brake performance testing aligned with UN ECE R90 provisions, compelling pad manufacturers to maintain type-approval documentation for market access. SIRIM QAS International administers product certification and quality auditing that filters non-compliant imports from regional supply chains. Stakeholders must monitor copper-content phase-out timelines and thermal fade test stringency as these parameters will determine which material platforms retain commercial viability.
Market Dynamics
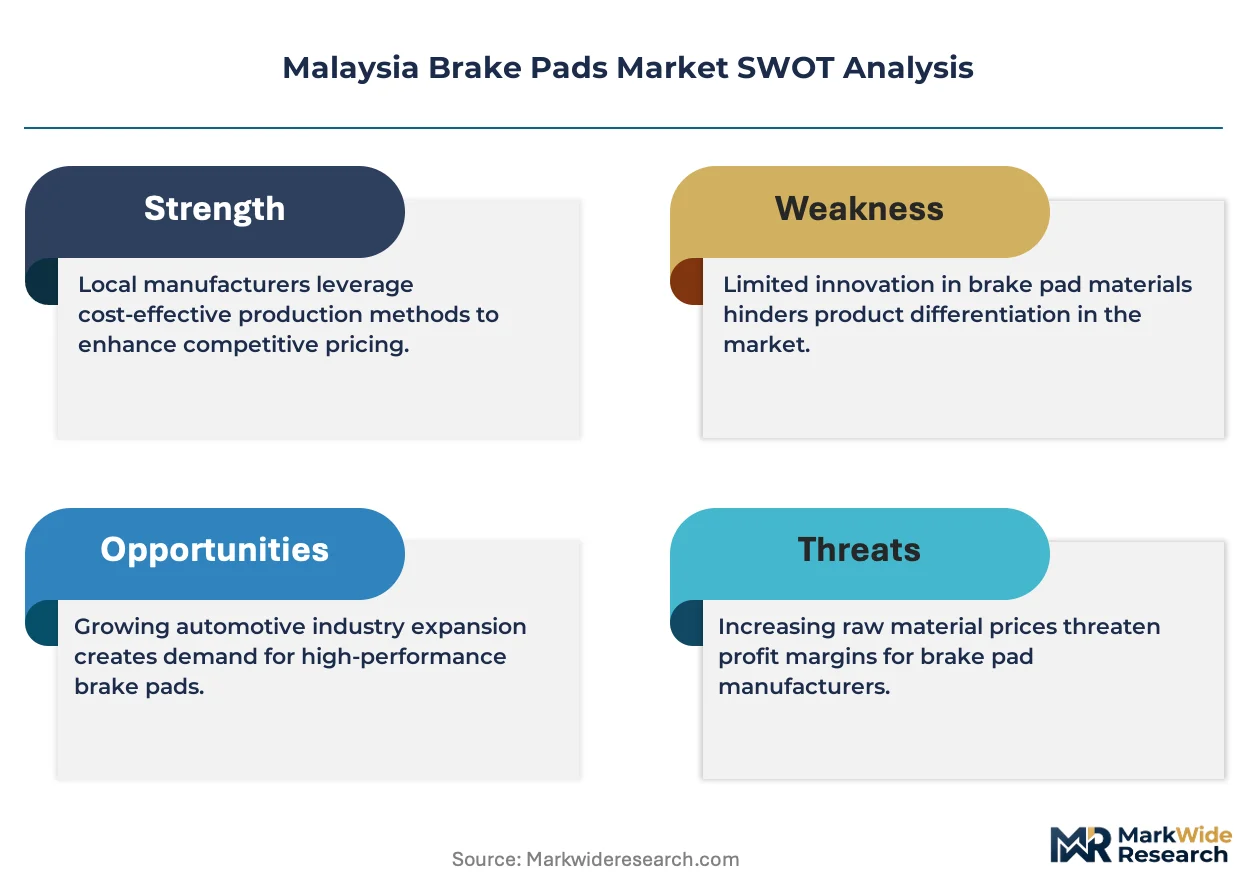
UN ECE R90 equivalent enforcement by Malaysia's Road Transport Department is compressing supplier margins while accelerating copper-free formulation transitions across the domestic manufacturing base.
Growth Catalysts
- Commercial Fleet Replacement Cycles:Logistics operators in Peninsular Malaysia are compressing brake pad change intervals from 40,000 km to 25,000 km under tropical heat load conditions.
- SIRIM QAS Certification Alignment:Mandatory type-approval documentation requirements are filtering substandard imports and elevating domestic manufacturer market access.
- Ceramic Formulation Maturation:Mid-range passenger vehicle segments are adopting copper-free ceramic composites that reduce brake dust emissions and noise signatures.
Market Restraints
- Raw Material Concentration Risk:Aramid fiber and specialty resin supply chains concentrate in Chinese and Japanese chemical processors, exposing Malaysian formulators to input cost volatility.
- Technical Performance Floor:Semi-metallic formulations retain dominance in heavy commercial applications due to ceramic thermal fade limitations under sustained downhill braking loads.
- Import Parity Pricing Pressure:Indonesian and Thai brake pad imports priced at SIRIM certification floor levels compress margin structures for domestic compounders.
Strategic Opportunities
- East Malaysia Penetration Gap:Sabah and Sarawak vehicle parc expansion outpaces established Klang Valley distribution infrastructure, creating whitespace for regional hub-and-spoke logistics models.
- Copper-Free Mandate Preparation:Anticipated alignment with California SB 346 and Washington state copper phase-out timelines positions early movers for export qualification.
- Sensor-Integrated Pad Architectures:Convergence of wear-indicator electronics with friction material substrates enables predictive maintenance service bundling for fleet management platforms.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Malaysian technical institutes produce limited graduates in tribology and thermoset composite engineering, constraining R&D pipeline velocity.
- UN ECE R90 Homologation Timeline:Type-approval testing cycles extend 8-14 months at SIRIM-accredited laboratories, delaying new product commercialization.
- Legacy Drum Brake Integration:Commercial vehicle platforms retaining rear drum configurations require dual-skill maintenance networks that fragment service provider capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Brake Pads Market |
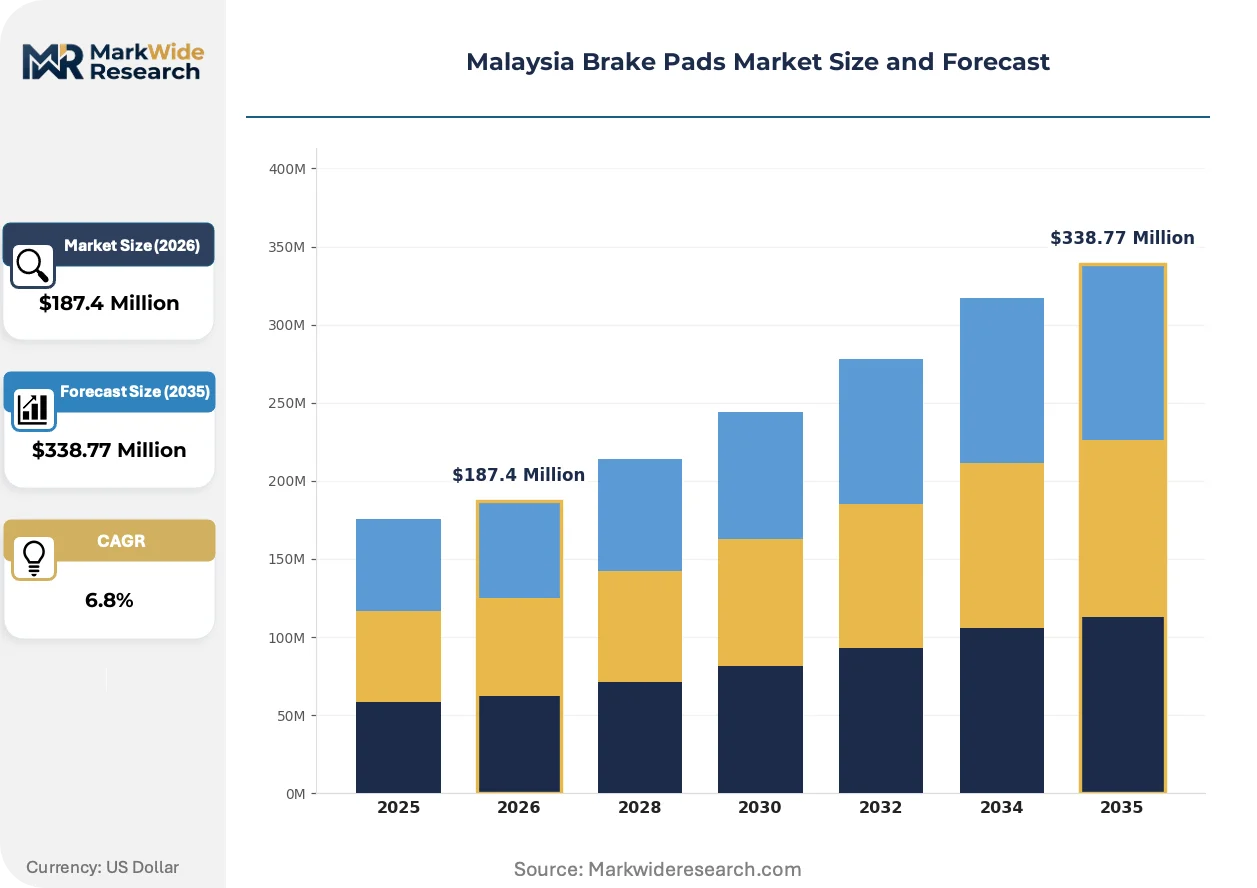
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Semi-Metallic, Ceramic, Low-Metallic Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Specialty Vehicles Material: Fricative Materials, Resins, Fibers, Metal Scraps End User: Automotive Manufacturers, Aftermarket Providers, Online Retailers, Independent Workshops |
| Companies Covered | Aisin Corporation, Brembo S.p.A., Robert Bosch GmbH, Federal-Mogul Motorparts LLC, Nisshinbo Brake Inc., ZF Friedrichshafen AG, Tenneco Inc., TMD Friction Holdings GmbH, Akebono Brake Industry Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Brake Pads Market Strategic Shifts
Friction material innovation is bifurcating between commodity semi-metallic dominance and premium ceramic migration, while regulatory compliance automation reshapes manufacturer operating models.
Ceramic matrix composite formulations is decentralizing thermal management architecture away from rotor-centric designs toward distributed friction surface engineering. Fleet operators in temperature-stressed corridors like the North-South Expressway are piloting these materials at 15-20% replacement premiums. The shift is compressing traditional semi-metallic volume concentration in the Klang Valley aftermarket.
Road Transport Department alignment with UN ECE R90 brake lining performance protocols is mandating dynamometer test documentation for every SKU variant. Domestic manufacturers are deploying in-house inertia brake dynamometers to accelerate certification cycles. Heavy commercial pad categories face the steepest compliance cost escalation as thermal fade test stringency tightens.
Direct procurement from compounders is displacing layered distributor networks among large fleet operators with centralized maintenance depots. These buyers are negotiating annual volume contracts with SIRIM-certified manufacturers, bypassing traditional spare parts wholesalers. The behavioral shift concentrates in Selangor-based logistics conglomerates operating cross-border ASEAN routes.
Malaysia Brake Pads Market Segmentation
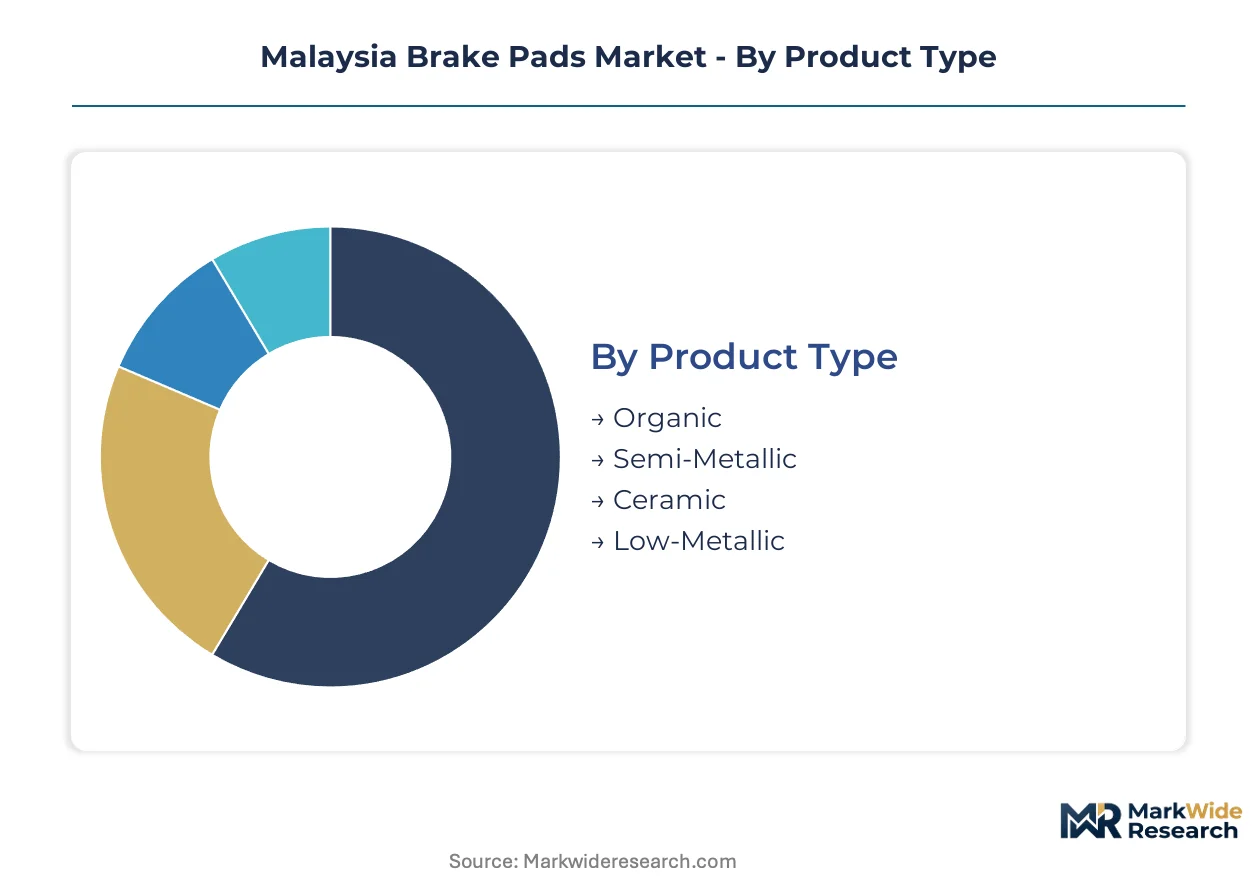
Brake pad segmentation in Malaysia reflects divergent capital requirements across formulation chemistry, application stress profiles, and distribution infrastructure. Understanding these structural divisions enables suppliers to align production capacity with SIRIM certification economics and thermal performance mandates.
Product Type:
Capital intensity varies sharply across formulation platforms, with ceramic and low-metallic variants demanding specialized curing equipment and raw material preprocessing infrastructure.
- Semi-Metallic:Iron and steel fiber composites bonded with thermoset resins deliver thermal durability under sustained braking loads. Fleet operators along the North-South Expressway specify these formulations for heavy commercial duty cycles where fade resistance outweighs dust generation concerns.
- Ceramic:Copper-free ceramic matrix composites incorporate potassium titanate and aramid fibers for low-dust, noise-dampening performance. Mid-range passenger vehicle owners in Selangor and Kuala Lumpur absorb 15-20% replacement premiums to reduce wheel soiling and urban noise signatures.
- Organic:Glass and rubber fiber formulations bound with phenolic resins serve economy-tier replacement demand in price-sensitive segments.
- Low-Metallic:Reduced metal content hybrids balance thermal conductivity with environmental compliance thresholds.
Semi-metallic formulations absorb the bulk of installed capacity; ceramic segments are expanding most quickly.
Application:
Vehicle duty cycles determine friction material specification stringency, with commercial platforms imposing the most severe thermal management requirements.
- Commercial Vehicles:Heavy trucks and buses operating cross-border ASEAN routes require brake pads rated for 500°C+ peak temperatures under sustained downhill braking. Logistics depots in Shah Alam and Port Klang compress replacement intervals to 25,000 km under tropical heat load conditions.
- Passenger Vehicles:Sedans and SUVs dominate volume consumption across the Klang Valley corridor, with ceramic penetration climbing fastest in premium Japanese and European nameplates.
- Two-Wheelers:Motorcycle brake pads concentrate in independent workshop channels serving urban commuter density.
- Specialty Vehicles:Off-road and agricultural equipment require specialized formulations for contaminated operating environments.
Passenger vehicles command the largest share of friction material throughput; commercial vehicle segments exhibit the steepest expansion trajectory as fleet renewal accelerates.
Material:
Raw material procurement strategies differentiate compounder economics, with fiber and resin supply chains concentrating in Northeast Asian chemical processors.
- Fricative Materials:Barium sulfate, calcium carbonate, and rubber granulates constitute the functional friction layer, with particle size distribution determining coefficient stability across temperature ranges.
- Resins:Phenolic and modified thermoset binders cure at 150-250°C under 10-20 MPa compression, requiring Malaysian formulators to import specialty grades from Japanese suppliers.
- Fibers:Aramid, glass, and steel reinforcement networks manage thermal expansion and mechanical strength.
- Metal Scraps:Recovered copper and brass fragments face phase-out pressure under anticipated alignment with California SB 346 copper reduction timelines.
Fricative materials and resins together absorb dominant input cost share; fiber substitution toward copper-free alternatives is climbing fastest.
End User:
Channel economics fragment across direct procurement, layered distribution, and digital intermediation, with certification requirements filtering market access.
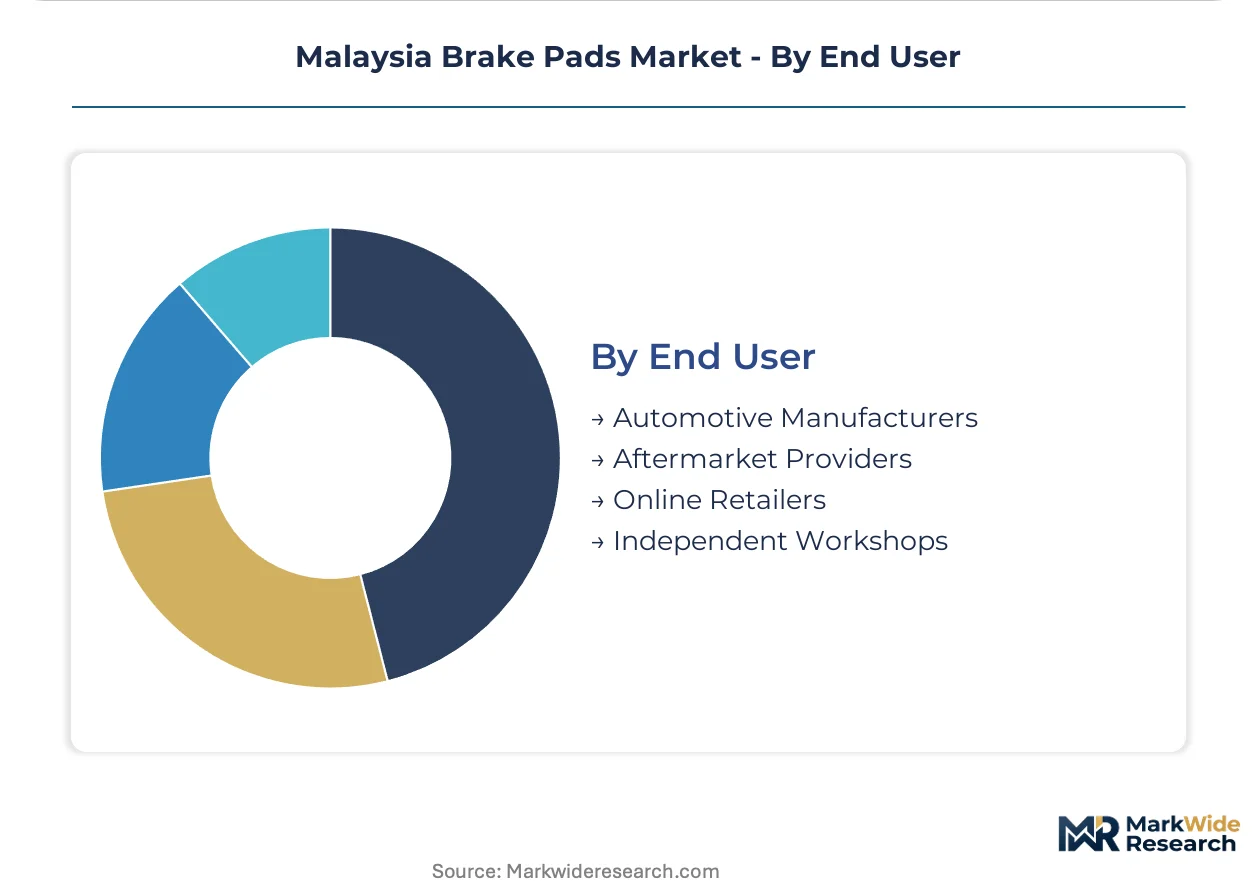
- Aftermarket Providers:SIRIM-certified distributors and spare parts wholesalers serve fragmented independent workshops across Peninsular Malaysia. Vehicle parc expansion outpaces OEM assembly rates, concentrating growth in replacement demand.
- Automotive Manufacturers:Original equipment fitments require UN ECE R90 type-approval documentation and just-in-sequence supply contracts with assembly plants in Shah Alam and Kulim.
- Online Retailers:E-commerce platforms bypass traditional wholesale tiers for price-transparent consumer procurement, though SIRIM compliance verification remains inconsistent.
- Independent Workshops:Small-scale service providers in secondary cities rely on informal supply chains with limited traceability to certified manufacturers.
Aftermarket providers capture the dominant share of friction material volume; online retail channels are gaining share fastest as digital procurement penetrates consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Friction material demand concentrates in Malaysia's Klang Valley corridor, where Kuala Lumpur and Selangor industrial zones absorb dominant replacement volumes. Fleet operators in Peninsular Malaysia compress brake pad change intervals under tropical heat load conditions. East Malaysia's Sabah and Sarawak regions present distribution infrastructure gaps as vehicle parc expansion outpaces established supply networks.
Selangor
Shah Alam logistics depots and Port Klang commercial hubs drive heavy-duty brake pad throughput for cross-border ASEAN fleet operators. The Road Transport Department enforces UN ECE R90 equivalent brake performance testing that filters substandard imports from regional supply chains. Domestic compounders in the Shah Alam industrial zone deploy in-house inertia brake dynamometers to accelerate SIRIM certification cycles for new product commercialization.
Kuala Lumpur
Mid-range passenger vehicle owners in the capital absorb ceramic formulation premiums to reduce wheel soiling and urban noise signatures. SIRIM QAS International administers mandatory type-approval documentation requirements that elevate certified manufacturer market access. Independent workshops across the metropolitan area source friction materials through layered distributor networks serving fragmented aftermarket demand.
Johor
Iskandar Malaysia's logistics corridors and proximity to Singapore generate commercial vehicle brake pad replacement density for temperature-stressed highway operations. The country's national standards body maintains quality auditing protocols that compress supplier margins while accelerating copper-free formulation transitions. Industrial zones near Johor Bahru host distribution hubs supplying cross-border fleet maintenance depots.
Penang
Kulim automotive assembly plants and electronics manufacturing clusters sustain original equipment fitment demand for just-in-sequence supply contracts. The Road Transport Department's tightening compliance thresholds compel pad manufacturers to maintain dynamometer test documentation for every SKU variant. Northern region distributors face import parity pricing pressure from Thai brake pad manufacturers certified at SIRIM floor levels.
Sabah
Kota Kinabalu and emerging urban centers in East Malaysia exhibit vehicle parc expansion that outpaces established Klang Valley distribution infrastructure. Informal supply chains with limited traceability to certified manufacturers still serve secondary city independent workshops. Regional hub-and-spoke logistics models present whitespace opportunities for SIRIM-certified manufacturers establishing direct procurement relationships with large fleet operators.
Malaysia Brake Pads Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium ceramic formulations commanding margin premiums while semi-metallic volumes dominate commercial fleet procurement. The supplier base concentrates around integrated sensor-to-pad system architects and copper-free formulation specialists. Three archetypes anchor competitive positioning: multinational tier-1 system integrators, regional compounders with SIRIM certification depth, and price-competitive import distributors. Capacity expansion in inertia brake dynamometer infrastructure and strategic partnerships with fleet management platforms constitute dominant competitive moves.
Among Japanese-origin specialists, Aisin Corporation and Akebono Brake Industry Co., Ltd. occupy positions within the premium-tier ceramic and environmental compliance vectors. Brembo S.p.A. exemplifies the performance-tier archetype through motorsport-derived thermal management positioning. Robert Bosch GmbH anchors the integrated systems tier with sensor-to-pad architectures. These representatives illustrate how geographic origin and corporate structure map to distinct competitive postures without mandating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Aisin Corporation |
| Brembo S.p.A. |
| Robert Bosch GmbH |
| Federal-Mogul Motorparts LLC |
| Nisshinbo Brake Inc. |
| ZF Friedrichshafen AG |
| Tenneco Inc. |
| TMD Friction Holdings GmbH |
| Akebono Brake Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fleet operator consolidation around SIRIM-certified direct procurement is forcing compounders to absorb certification cost burdens while defending volume positions against Indonesian and Thai import parity. This demand-side compression reshapes supplier economics toward in-house dynamometer investment and copper-free formulation transitions.
Pricing Analysis
Volume throughput concentrates in semi-metallic formulations serving commercial logistics, while ceramic segments capture margin premiums from passenger vehicle owners in Selangor and Kuala Lumpur. Price differentiation rests on SIRIM certification grade and thermal fade test performance tier. Cost compression in the economy organic segment is intensifying because Thai imports certified at SIRIM floor levels undercut domestic compounders. Fleet operators with centralized Shah Alam depots exhibit lowest price sensitivity; independent workshops in secondary cities show highest.
Supply Chain Analysis
Domestic-content alignment with UN ECE R90 equivalent standards is redirecting procurement toward SIRIM-accredited Malaysian compounders and away from uncertified regional imports. Raw material sourcing draws from Japanese phenolic resin suppliers, Chinese aramid fiber processors, and Australian mineral filler providers. Single-source vulnerability concentrates in specialty thermoset resin grades where Japanese chemical processors dominate. Distribution runs through layered aftermarket networks serving independent workshops, with direct procurement displacing traditional tiers among large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SIRIM certification capacity scarcity props pricing power for accredited manufacturers, constraining supply elasticity as fleet operators accelerate replacement cycles. This bottleneck sustains margin premiums for compounders with in-house dynamometer infrastructure.
For Market Incumbents: Hedge against Indonesian and Thai import encroachment by deepening backward integration into copper-free raw material preprocessing. Prioritize inertia brake dynamometer capacity expansion in Shah Alam industrial zones to compress UN ECE R90 homologation timelines. Defensive consolidation around sensor-integrated pad architectures locks in fleet management platform partnerships before electronics specialists enter friction material substrates. For New Entrants and Emerging Players: UN ECE R90 equivalent enforcement by Malaysia's Road Transport Department opens a window for SIRIM-certified regional compounders to capture East Malaysia whitespace. Target Sabah and Sarawak distribution gaps with hub-and-spoke logistics models bypassing Klang Valley concentration. Pursue direct procurement relationships with emerging logistics fleets in Kota Kinabalu as the most penetrable entry vector, leveraging copper-free formulation positioning for export qualification to California and Washington state timelines. For Investors and Strategic Acquirers: The window for entry favors SIRIM-certified mid-cap compounders with dynamometer infrastructure and established fleet relationships. Long-term viability centers on copper-free formulation pipelines and sensor integration capabilities. Monitor California SB 346 and Washington state copper phase-out alignment announcements as the critical inflection signal for export-qualified asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| In-House Dynamometer Investment | Accelerates SIRIM certification cycles and compresses new product commercialization timelines for domestic compounders. |
| Copper-Free Formulation Transition | Positions manufacturers for anticipated alignment with California SB 346 and Washington state environmental protocols. |
| East Malaysia Distribution Buildout | Captures vehicle parc expansion in Sabah and Sarawak outpacing established Klang Valley supply infrastructure. |
| Sensor-Integrated Pad Development | Enables predictive maintenance service bundling with fleet management platforms in Selangor logistics corridors. |
| Direct Procurement Contracting | Bypasses layered distributor networks by securing annual volume agreements with Shah Alam-based fleet operators. |
Study Parameters
Document review covered Road Transport Department enforcement guidelines, SIRIM QAS certification protocols, and UN ECE R90 technical provisions, complemented by interviews with brake pad compounders, fleet maintenance directors at Shah Alam logistics depots, aftermarket distributors serving the Klang Valley corridor, and procurement leads at cross-border ASEAN fleet operators. Secondary validation drew from customs trade data, vehicle registration databases, and industrial zone capacity disclosures. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry and application segments.
Revenue and volume trajectories across the analysis window reflect segmented modeling by product type, vehicle application, material composition, and end-user channel. CAGRs derive from regression analysis of replacement cycle compression, vehicle parc expansion rates, and regulatory compliance cost absorption. Industry-specific inputs include thermal fade test stringency parameters, copper-content phase-out timelines, and fleet operator procurement behavior shifts.
The model assumes a particular technology adoption path; alternative pathways for ceramic matrix composite thermal management would alter the outlook for semi-metallic volume concentration. Forecasts reflect assumptions around SIRIM certification timeline stability and ASEAN import parity pricing persistence. Regulatory acceleration or raw material supply disruption in Japanese resin channels would necessitate revision. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Drum Brake Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Electro Hydraulic Power Steering Market
Automotive Parts
Hydraulic Lash Adjuster Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Heavy Duty Engines Market