
 Automotive Performance Tuning Market | 2026-2036
Automotive Performance Tuning Market Size, Share, and Industry Trends Forecast 2026-2036
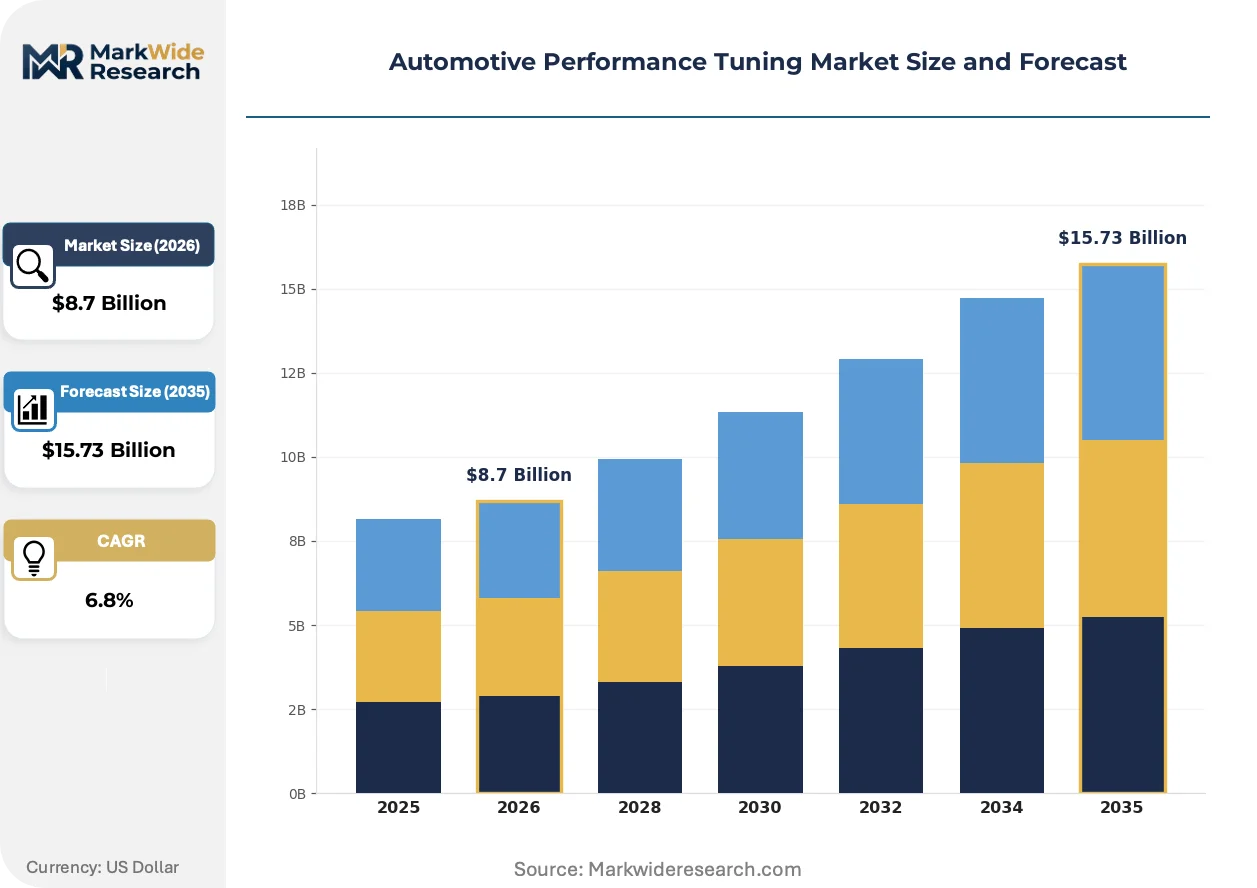
Automotive Performance Tuning Market Outlook
Market Context
Subscription-based ECU map updates are hardening into a recurring revenue layer that shifts tuning from one-time hardware sales to ongoing software relationships. Cobb Tuning leverages over-the-air calibration platforms to sustain enthusiast engagement across multiple vehicle generations. ABT Sportsline anchors its premium positioning through factory-backed warranty programs that differentiate it from unlicensed aftermarket operators.
Technical Definition and Segments
Automotive performance tuning encompasses the modification of engine control parameters, induction and exhaust flow characteristics, and forced induction systems to increase power output, torque delivery, or throttle response beyond original equipment manufacturer specifications. ECU tuning modifies fuel injection timing, ignition advance curves, and boost pressure thresholds through reprogrammed engine management software. Engine modifications and turbochargers occupy the highest margin pools where material costs for forged internals and ball-bearing turbo assemblies support premium pricing. Electronic and software-based technologies represent the fastest-expanding dimension as flash tuning replaces physical chip replacements and enables remote calibration delivery.
Regulatory Frame and Outlook
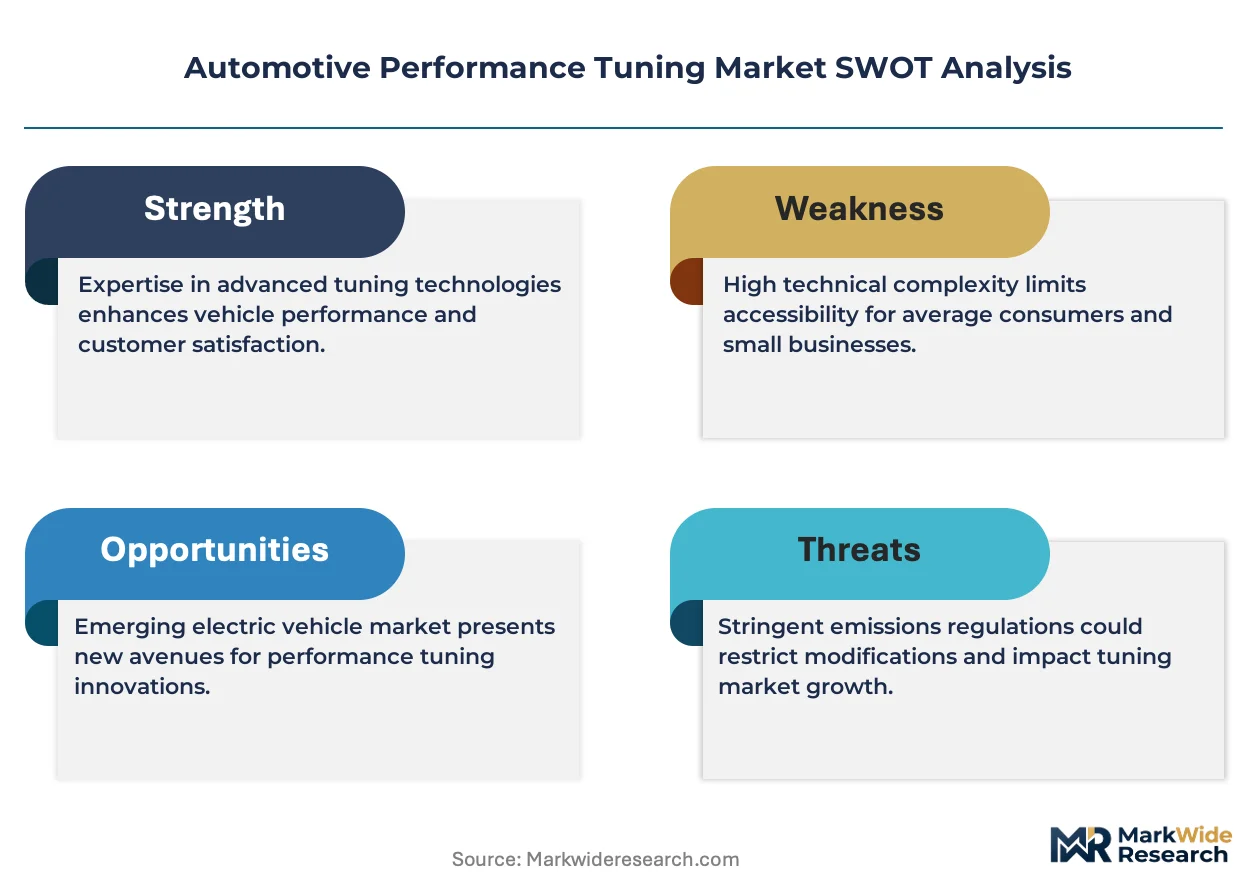
EPA enforcement in the United States and EU Green Deal emissions benchmarks in Europe are tightening type-approval requirements for modified vehicles, constraining hardware-focused tuners while creating regulatory space for emissions-compliant software solutions. Germany's KBA and California's Air Resources Board both mandate emissions retention for street-legal modifications, forcing calibration houses to document compliance or restrict sales to track-use disclaimers. Stakeholders must monitor how jurisdictional fragmentation between EPA waivers, EU whole-vehicle approval frameworks, and emerging carbon border adjustments reshapes which tuning products can cross borders legally.
Market Dynamics
Software-defined powertrain calibration is compressing hardware tuner margins while elevating emissions-compliant ECU remapping as the dominant value capture mechanism. The shift from physical component sales to recurring software subscriptions restructures revenue recognition and customer lifetime economics across the aftermarket.
Growth Catalysts
- EU F-Gas Regulation:Tightened emissions compliance for modified vehicles accelerates demand for software-centric tuning solutions that preserve factory catalytic converter efficiency and OBD-II readiness.
- Aftermarket workshop consolidation:Independent garages in Germany and the United States are pooling calibration investments to access tier-one flash tuning platforms, expanding addressable service capacity.
- Over-the-air delivery infrastructure:Remote ECU programming eliminates geographic constraints on tuner reach and enables real-time map refinement based on datalogged engine parameters.
Market Restraints
- Forced induction component costs:Ball-bearing turbocharger assemblies and forged internal engine components face raw material volatility in nickel and titanium alloys, compressing margin pools on hardware-intensive builds.
- Supply concentration in ECU hardware:Dominant semiconductor foundries in East Asia control production of automotive-grade flash memory and processing units, creating single-source vulnerability for calibration tool manufacturers.
- California Air Resources Board enforcement:EPA-aligned state regulations mandate emissions retention for street-legal modifications, forcing tuners to restrict product lines or absorb compliance documentation costs.
Strategic Opportunities
- Track-day enthusiast segments:Closed-course racing applications bypass street-legal emissions constraints, creating compliant revenue streams for high-performance calibration maps with explicit competition-use disclaimers.
- Electric vehicle powertrain tuning:Battery thermal management and inverter switching algorithms represent emerging calibration surfaces as performance EVs proliferate in Germany and the United States.
- Subscription-based map libraries:Cloud-hosted calibration repositories with seasonal or fuel-quality variants convert one-time transactions into recurring revenue relationships with enthusiast owners.
Industry Challenges
- ECU encryption complexity:Manufacturer-specific bootloader locks and rolling-code protection schemes require continuous reverse-engineering investment to maintain flash tuning access.
- Calibration engineer scarcity:Deep expertise in combustion modeling, emissions optimization, and safety-limit validation concentrates among specialists in Stuttgart, Detroit, and Osaka tuning clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Performance Tuning Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Modifications, Exhaust Systems, ECU Tuning, Turbochargers Technology: Mechanical, Electronic, Software, Hybrid End User: Enthusiasts, Racing Teams, Automotive Workshops, Aftermarket Retailers Application: Performance Racing, Street Performance, Custom Builds, Off-Road Enhancements |
| Companies Covered | Revo Technik, EcuTek Technologies, APR LLC, RS Tuning, Quantum Tuning, Cobb Tuning, RaceChip, ABT Sportsline, DTE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Performance Tuning Market Strategic Shifts
Flash-based ECU reprogramming is displacing socketed chip replacement across all vehicle segments, collapsing installation time from hours to minutes while enabling iterative refinement. This technical pivot restructures competitive advantage toward software architecture and emissions validation capabilities.
Remote calibration platforms are consolidating aftermarket service delivery by enabling tuners to diagnose, modify, and validate engine parameters without physical vehicle presence. Independent workshops in the United States and Germany are adopting these tools to access specialist expertise without geographic relocation. The technology is consolidating regional tuner networks into centralized calibration houses with distributed execution footprints.
The EU Green Deal's whole-vehicle approval framework is tightening type-approval documentation requirements for modified vehicles entering member state markets. German regulators at KBA now demand emissions retention proof for software-based powertrain alterations, forcing calibration providers to invest in chassis dynamometer validation infrastructure. Street-legal product lines face certification timeline extensions that favor established suppliers with captive testing capacity.
Enthusiast procurement patterns are fragmenting across direct-to-consumer digital channels and traditional workshop intermediaries. Younger vehicle owners in North America and Western Europe favor self-service flash tools with community-validated map libraries, displacing legacy tuner-dealer relationships. This channel rotation concentrates margin capture with platform operators who aggregate calibration intellectual property and distribute through licensed installer networks.
Automotive Performance Tuning Market Segmentation
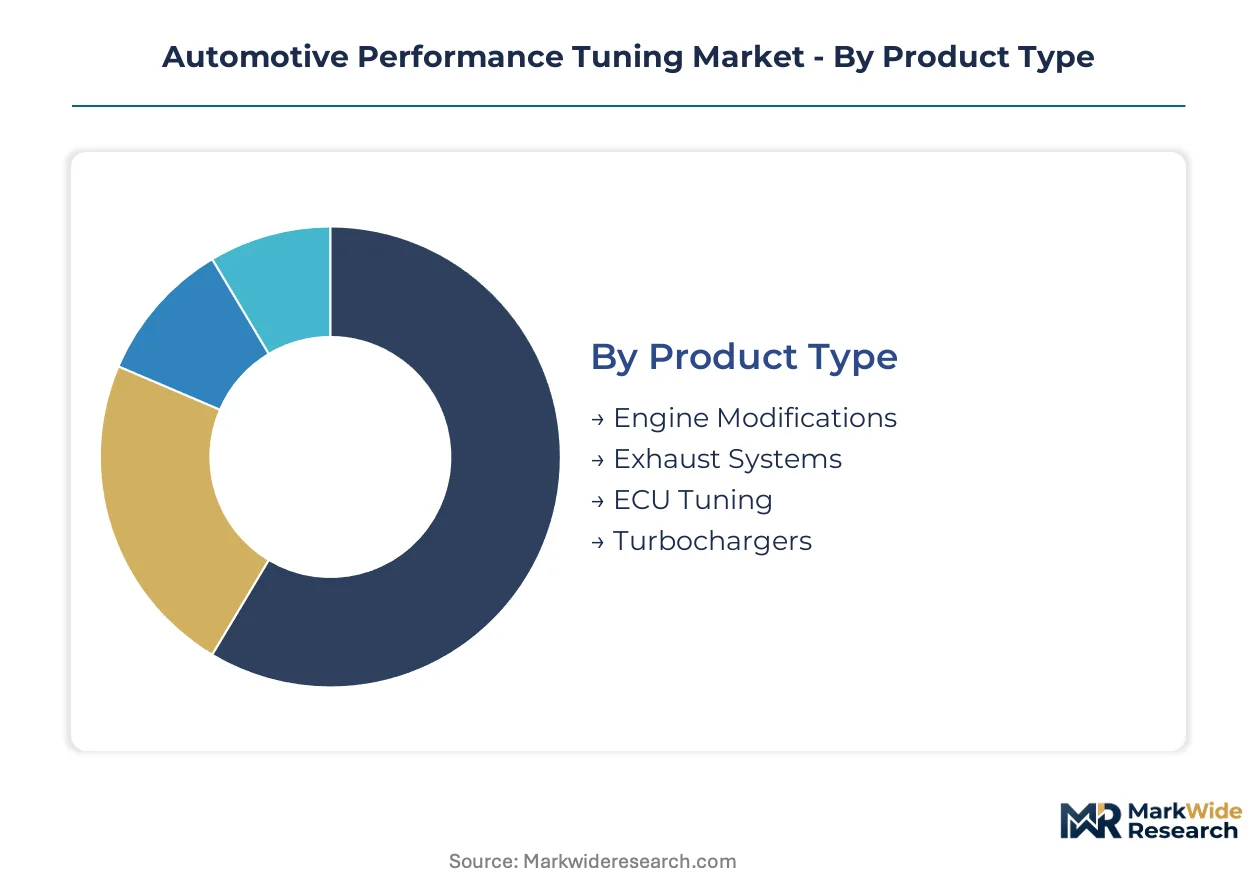
Performance tuning procurement splits sharply between hardware-intensive builds requiring physical component installation and software-centric calibrations deliverable through diagnostic ports. Buyer priorities vary by vehicle age, regulatory environment, and whether the application must retain street-legal emissions compliance.
Product Type:
Workshop selection hinges on margin structure and installation complexity, with labor-intensive hardware segments commanding premium service billing against rapid-turn software offerings.
- Engine Modifications:Forged pistons, connecting rods, and camshaft upgrades demand precision machining and extended installation timelines. German aftermarket workshops in Stuttgart and Munich concentrate demand for these builds, driven by track-day enthusiasts seeking durability under sustained high-load operation.
- ECU Tuning:Flash-based reprogramming of fuel maps, ignition timing, and boost pressure thresholds requires no physical component replacement. Adoption concentrates among younger vehicle owners in California and Texas who prioritize throttle response gains without hardware investment.
- Exhaust Systems:Cat-back and axle-back configurations alter flow dynamics and acoustic signature. California Air Resources Board certification requirements constrain street-legal product lines to pre-approved component architectures.
- Turbochargers:Ball-bearing and journal-bearing forced induction assemblies represent the highest hardware expenditure category. Nickel alloy supply volatility from Russian and Indonesian sources compresses margin stability for specialist suppliers.
ECU Tuning leads on scale; Turbochargers lead on momentum.
Technology:
Calibration delivery methods stratify by vehicle model year and manufacturer encryption sophistication, with newer platforms restricting access to authorized dealer networks.
- Electronic:Piggyback controllers and standalone engine management units intercept factory sensor signals. Demand clusters among Japanese import enthusiasts in Osaka and Los Angeles seeking reversible modifications that preserve warranty coverage.
- Software:Direct flash programming of factory ECU memory enables parameter adjustment without auxiliary hardware. German KBA type-approval requirements now mandate emissions validation documentation for street-legal software releases.
- Mechanical:Carburetor jetting, distributor advance curves, and naturally aspirated induction modifications serve pre-OBD-II vehicle populations. Collector vehicle specialists in Arizona and Florida sustain residual demand for these legacy techniques.
- Hybrid:Combined mechanical and electronic interventions optimize powertrain response across multiple operating modes. Porsche and BMW performance divisions in Germany deploy hybrid architectures for factory-authorized tuning packages.
Software dominates volume capture; Hybrid approaches gain share fastest.
End User:
Channel structure fragments between direct-to-consumer digital platforms and traditional workshop intermediaries, with procurement authority shifting toward enthusiast self-service tools.
- Automotive Workshops:Independent garages and franchise operations source calibration tools and component inventory for retail installation. German workshop consolidation in the Rhine-Ruhr region pools purchasing power for tier-one flash tuning platform licenses.
- Enthusiasts:Individual vehicle owners procure self-service flash tools and community-validated map libraries. North American demand concentrates among millennials and Gen Z owners who displace legacy tuner-dealer relationships with direct digital procurement.
- Racing Teams:Closed-course competitors bypass street-legal emissions constraints for maximum power extraction. California and Nevada desert racing series sustain specialized demand for competition-only calibration maps.
- Aftermarket Retailers:Parts distributors and e-commerce platforms aggregate component supply for downstream workshop and consumer channels. Amazon and Rock Auto dominate North American fulfillment infrastructure for bolt-on performance hardware.
Automotive Workshops anchor revenue scale; Enthusiasts drive channel transformation.
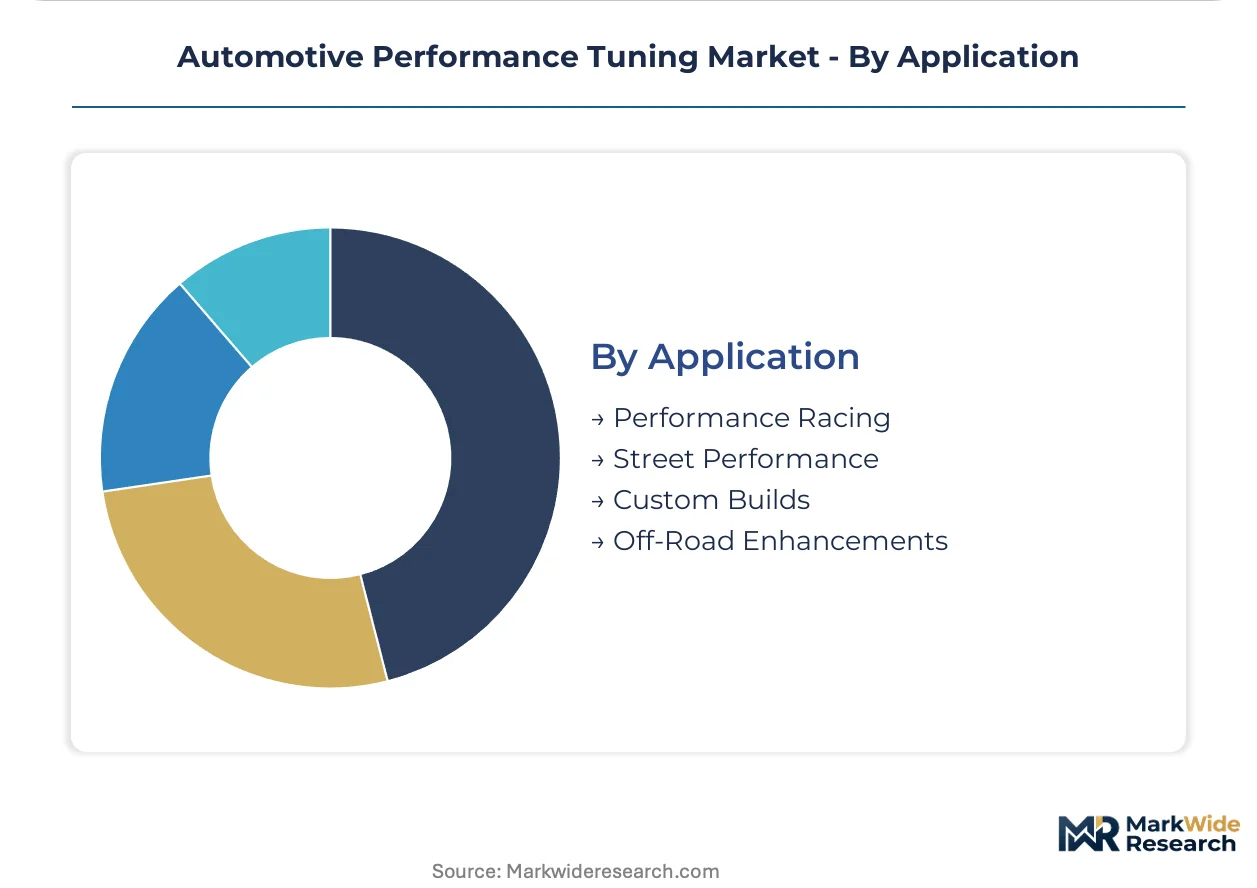
Application:
Regulatory jurisdiction determines product architecture, with street-legal applications requiring emissions retention validation and track-use segments permitting unconstrained calibration.
- Street Performance:Modifications must preserve OBD-II readiness and catalytic converter efficiency for regulatory compliance. EPA enforcement and CARB certification requirements constrain product development timelines for US-market suppliers.
- Performance Racing:Closed-course applications operate outside street-legal emissions frameworks. Nürburgring and Hockenheim circuit proximity sustains German demand for competition-specific engine builds.
- Custom Builds:One-off vehicle projects combine multiple tuning disciplines for personalized output characteristics. SEMA Show exhibitors in Las Vegas showcase integrated mechanical and electronic architectures.
- Off-Road Enhancements:Suspension, drivetrain, and engine modifications optimize traction and power delivery for unpaved terrain. Arizona and Utah desert recreation areas concentrate US demand for these specialized applications.
Street Performance commands volume; Performance Racing expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in regulatory posture, with Stuttgart's KBA mandating emissions documentation for street-legal software while California's CARB enforces parallel constraints through EPA-aligned state frameworks. This jurisdictional fragmentation shapes which tuning architectures can operate legally in each market.
Germany
Track-day culture and Autobahn-accessible vehicle fleets sustain dense demand for powertrain optimization across Bavaria and Baden-Württemberg. The KBA's tightened type-approval requirements under EU Green Deal frameworks now compel calibration houses to invest in chassis dynamometer validation infrastructure. Stuttgart anchors Europe's deepest cluster of ECU engineering expertise, where ABT Sportsline and DTE Systems maintain captive testing capacity for street-legal certification timelines.
United States
Millennial and Gen Z enthusiasts in Texas and Florida favor direct-to-consumer flash tools with community-validated map libraries over traditional workshop relationships. EPA enforcement and CARB certification requirements constrain product development timelines for suppliers targeting California's 39 million registered vehicles. Cobb Tuning leverages over-the-air calibration platforms from its Utah base to sustain engagement across multiple vehicle generations without geographic dealer networks.
United Kingdom
Revo Technik and Quantum Tuning anchor a specialist ecosystem serving compact performance hatchbacks and German import enthusiasts around Birmingham and Manchester. Post-Brexit divergence from EU type-approval frameworks creates parallel certification burdens for products accessing both markets. Silverstone and Brands Hatch circuit proximity sustains competition-specific demand that bypasses street-legal emissions constraints entirely.
Japan
Osaka and Nagoya tuning clusters concentrate expertise in piggyback controllers and standalone engine management for JDM import markets. METI standards for OBD-II readiness create baseline compliance requirements that calibration providers must document for domestic street-legal product lines. The country's semiconductor foundry dominance in Kyushu supplies automotive-grade flash memory to calibration tool manufacturers worldwide.
Australia
Desert racing series across South Australia and the Northern Territory sustain specialized demand for competition-only calibration maps with explicit off-road disclaimers. The country's national automotive regulator mandates emissions retention for modified vehicles accessing public roads, pushing street-legal tuners toward software-centric solutions. Sydney and Melbourne workshops pool calibration investments to access tier-one flash tuning platforms originally developed for European and North American markets.
Automotive Performance Tuning Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with software-defined calibration houses capturing recurring revenue streams while hardware-intensive turbocharger suppliers face raw material volatility. The vendor base concentrates among three strategic archetypes: factory-authorized tuners with captive OEM relationships, independent flash calibration specialists with platform-agnostic toolsets, and component fabricators supplying forged internals and forced induction assemblies. Competitive positioning hardens through M&A consolidation of regional workshop networks and strategic partnerships securing semiconductor supply for automotive-grade flash memory.
Within the factory-authorized tier, ABT Sportsline and DTE Systems exemplify German GmbH-structured specialists that anchor premium positioning through emissions-compliant certification capacity. Cobb Tuning occupies a scale-driven position among North American platform operators aggregating calibration intellectual property for distribution through licensed installer networks. These three entities represent divergent geographic and structural approaches to capturing value as the industry pivots from hardware transactions toward subscription-based software relationships.
| Leading Market Players |
|---|
| Revo Technik |
| EcuTek Technologies |
| APR LLC |
| RS Tuning |
| Quantum Tuning |
| Cobb Tuning |
| RaceChip |
| ABT Sportsline |
| DTE Systems |
| Others |
Value Chain & Pricing Dynamics
Track-day enthusiast clusters in Stuttgart and Munich concentrate procurement authority for forged internals and ball-bearing turbo assemblies, anchoring a project-based pricing model where installation complexity and material grade drive differentiation.
Pricing Analysis
Capacity additions in Chinese semiconductor foundries are reshaping price floors for automotive-grade flash memory used in calibration tools. Three-tier pricing structure across premium, standard, and economy levels separates KBA-certified street-legal packages from track-use disclaimers and unlicensed aftermarket alternatives. Cost compression in hardware-intensive turbocharger assemblies intensifies because nickel alloy volatility from Indonesian sources feeds into forged component costs. Workshop buyers exhibit highest price sensitivity on mechanical engine modifications, while enthusiast direct-to-consumer segments absorb premium pricing for over-the-air subscription platforms.
Supply Chain Analysis
Reverse-logistics flows for remanufactured turbocharger cartridges and refurbished ECU hardware create secondary supply channels that compete with new component sales. Manufacturing concentration centers on Germany for precision-machined forged internals, Taiwan for automotive-grade flash memory and processing units, and China for exhaust system fabrications. Raw material dependencies draw from Russian and Indonesian nickel alloys, titanium billet stock, and Kyushu-sourced semiconductor wafers. Single-source vulnerability in East Asian foundry capacity for automotive-grade ECU hardware exposes calibration tool manufacturers to geographic concentration risk. Distribution runs through licensed installer networks in Germany and direct-to-consumer digital platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive performance tuning market functions as a geographic-arbitrage play where German KBA certification costs exceed California CARB compliance investments by multiples, creating margin capture opportunities for suppliers with dual-jurisdiction validation capacity.
For Market Incumbents: Lock in emissions-compliant calibration IP through captive chassis dynamometer infrastructure that accelerates KBA type-approval timelines. Defend against unlicensed flash tuning entrants by deepening backward integration into semiconductor supply for proprietary calibration tool hardware. Prioritize subscription platform architecture that converts one-time map sales into recurring revenue relationships resistant to price erosion. For New Entrants and Emerging Players: Begin with electric vehicle powertrain tuning in Texas and Florida, where battery thermal management calibration remains underpenetrated by legacy combustion-focused suppliers. Target competition-only track-day segments that bypass street-legal emissions constraints entirely. Deploy community-validated map libraries through direct-to-consumer digital channels to displace established workshop intermediaries. For Investors and Strategic Acquirers: Tier 1 automotive suppliers with software-defined vehicle programs are the most active acquirer in this space, seeking calibration capabilities for factory-authorized performance packages. Long-term viability hinges on regulatory compliance infrastructure rather than hardware fabrication scale. Monitor EPA enforcement intensity and EU F-Gas Regulation amendments as inflection indicators that would accelerate consolidation toward emissions-validated software specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions Compliance Certification Investment | KBA and CARB validation capacity separates street-legal suppliers from track-only competitors. |
| Over-the-Air Platform Development | Cobb Tuning demonstrates how remote calibration delivery collapses geographic constraints on tuner reach. |
| Backward Integration into Semiconductor Supply | Captive flash memory sourcing insulates calibration tool manufacturers from East Asian foundry concentration. |
| Subscription Map Library Launch | Cloud-hosted seasonal and fuel-quality variants convert transactions into recurring revenue. |
| Electric Vehicle Powertrain Calibration Entry | Battery thermal management and inverter algorithms represent emerging surfaces as performance EVs proliferate. |
Study Parameters
Multiple input streams — structured interviews with ECU calibration engineers, primary fieldwork with aftermarket workshop operators, and secondary validation against regulatory filings — were reconciled to construct segment-level demand estimates. Stakeholder engagement encompassed Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors in Germany and the United States, and racing team technical directors. Secondary sources drew from KBA type-approval databases, EPA enforcement actions, vehicle production registries, and EU Green Deal implementation documents. Bottom-up demand aggregation across product types and technologies was cross-checked against top-down market sizing from industry trade associations.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation dimensions including product type, calibration technology, end-user channel, and application compliance tier. CAGRs were derived from fitted trend analysis adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated semiconductor supply lead times, KBA certification timeline distributions, and enthusiast demographic shift patterns.
Several conditions sit outside the modeled scope, including abrupt EPA enforcement escalations, EU carbon border adjustment implementations, and manufacturer bootloader encryption breakthroughs that would foreclose flash tuning access. Forecasts reflect underlying assumptions about emissions regulation stability and semiconductor supply continuity. Practitioners should monitor KBA type-approval backlog durations and nickel alloy spot price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Power Transmission Gearbox Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Diesel Engine Management System Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Transmission Oil Filters Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Racing Clutches Market
Powertrain
Gear Oil Market
Powertrain
Diesel Engine Market
Powertrain
Gear Reduction Starter Market