
 Automotive Power Distribution Block Market | 2026-2036
Automotive Power Distribution Block Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Distribution Block Market Analysis
EV-first OEMs is bifurcating procurement away from traditional internal-combustion suppliers as voltage architectures climb toward 800V. TE Connectivity leverages its high-voltage connector portfolio to anchor position in European EV platforms. Eaton Corporation competes through integrated power management systems that consolidate fuse, relay, and breaker functions. Yazaki Corporation dominates cabin-mount and under-hood configurations across Japanese and North American vehicle programs.
An automotive power distribution block is an electromechanical assembly that routes, protects, and manages electrical power flow across vehicle subsystems, typically incorporating stamped copper busbars, molded thermoplastic housings rated to 150°C, and blade-type or cartridge fuse positions. Its primary purpose is to consolidate circuit protection and power distribution into a single replaceable module, reducing wiring mass and assembly complexity. Fuse block and relay module configurations retain the largest installed base, though compact and custom form factors are capturing margin pools as OEMs shrink engine-bay packaging volumes. Under-hood installation types face thermal management constraints that push engineering investment toward integrated and remote-mount designs with improved ingress protection.
The EPA tailpipe rules, NHTSA safety standards, and EU Green Deal vehicle-emission targets collectively mandate higher electrical loads and tighter component reliability, which expands specification requirements for distribution blocks in electrified powertrains. China's MIIT dual carbon goals and GB standards for new energy vehicles impose additional certification layers that filter market access for non-domestic suppliers. Stakeholders must monitor how 800V platform rollouts and regional content requirements reshape supplier qualification timelines across major vehicle-producing markets.
Market Dynamics
Platform voltage escalation toward 800V architectures is restructuring supplier qualification criteria and procurement authority migration from Tier-2 component vendors to OEM engineering teams.
Growth Catalysts
- EU Green Deal vehicle-emission targets:Mandates for electrified powertrains expand specification requirements for high-reliability distribution blocks across German and French vehicle programs.
- Stamped copper busbar integration:Advanced forming processes reduce electrical resistance and thermal mass, enabling compact module designs that satisfy shrinking engine-bay packaging constraints.
- China MIIT dual carbon goals:Certification layers for new energy vehicles filter market access and accelerate domestic supplier capacity expansion in high-voltage architectures.
Market Restraints
- Copper price volatility:Primary metal input costs fluctuate with commodity cycles, compressing margin stability for stamped conductor manufacturers.
- Thermoplastic housing supply concentration:High-temperature PPA and PPS resin production clusters in German and Japanese chemical corridors, creating geographic single-source exposure.
- GB standards compliance friction:China's technical certification requirements impose extended validation timelines that delay non-domestic supplier market entry.
Strategic Opportunities
- Remote-mount power distribution:Relocation of fuse and relay modules away from engine-bay thermal zones opens cabin and trunk-mount configurations with improved ingress protection ratings.
- US IRA clean vehicle tax credits:Domestic content incentives accelerate North American supplier qualification for electrified platform procurement.
- Solid-state circuit protection convergence:Integration of semiconductor-based current interruption with traditional electromechanical architectures enables arc-free operation and faster fault response.
Industry Challenges
- High-voltage safety certification timelines:OEM validation protocols for 800V-rated components extend development cycles and strain engineering resource allocation.
- Legacy 12V system integration complexity:Dual-architecture vehicles require distribution blocks that bridge conventional low-voltage circuits with high-voltage domains without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Distribution Block Market |
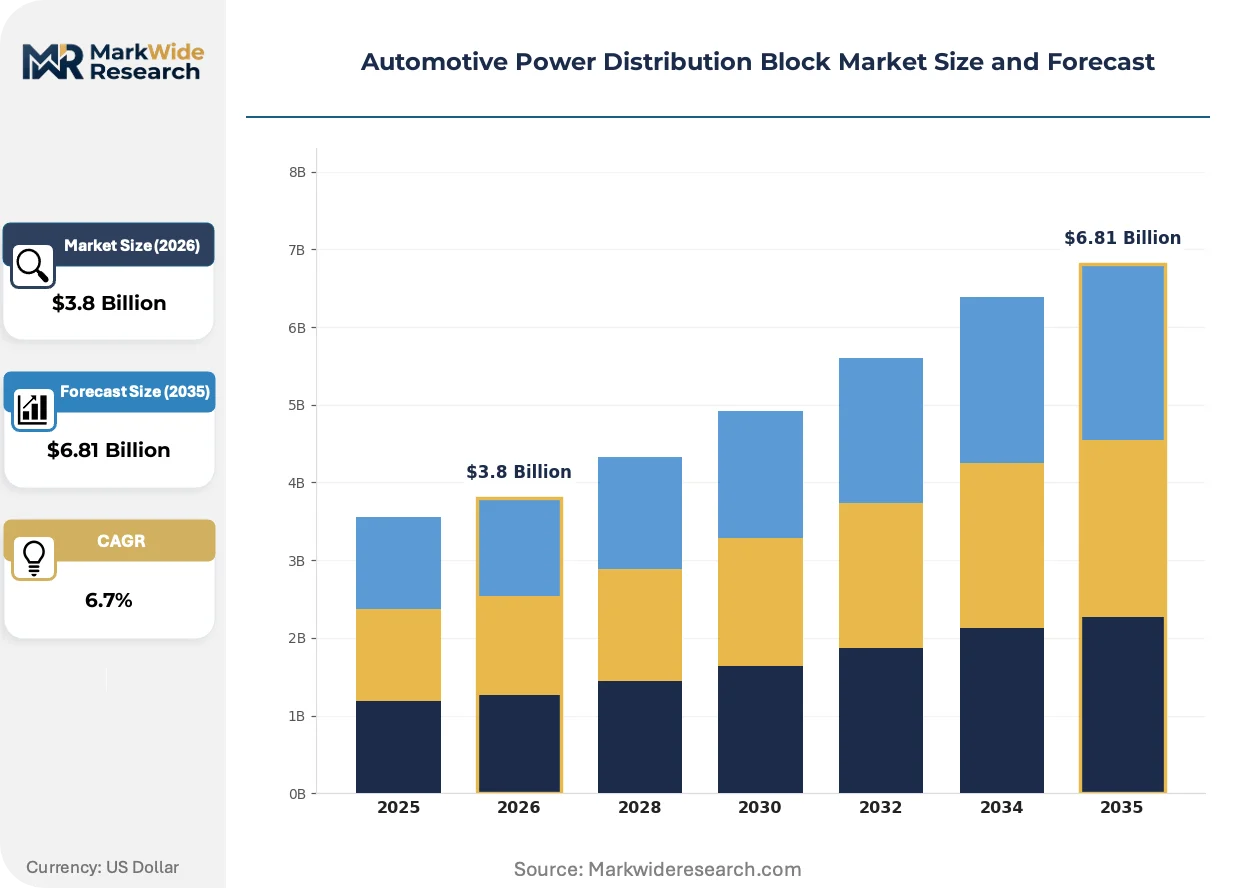
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
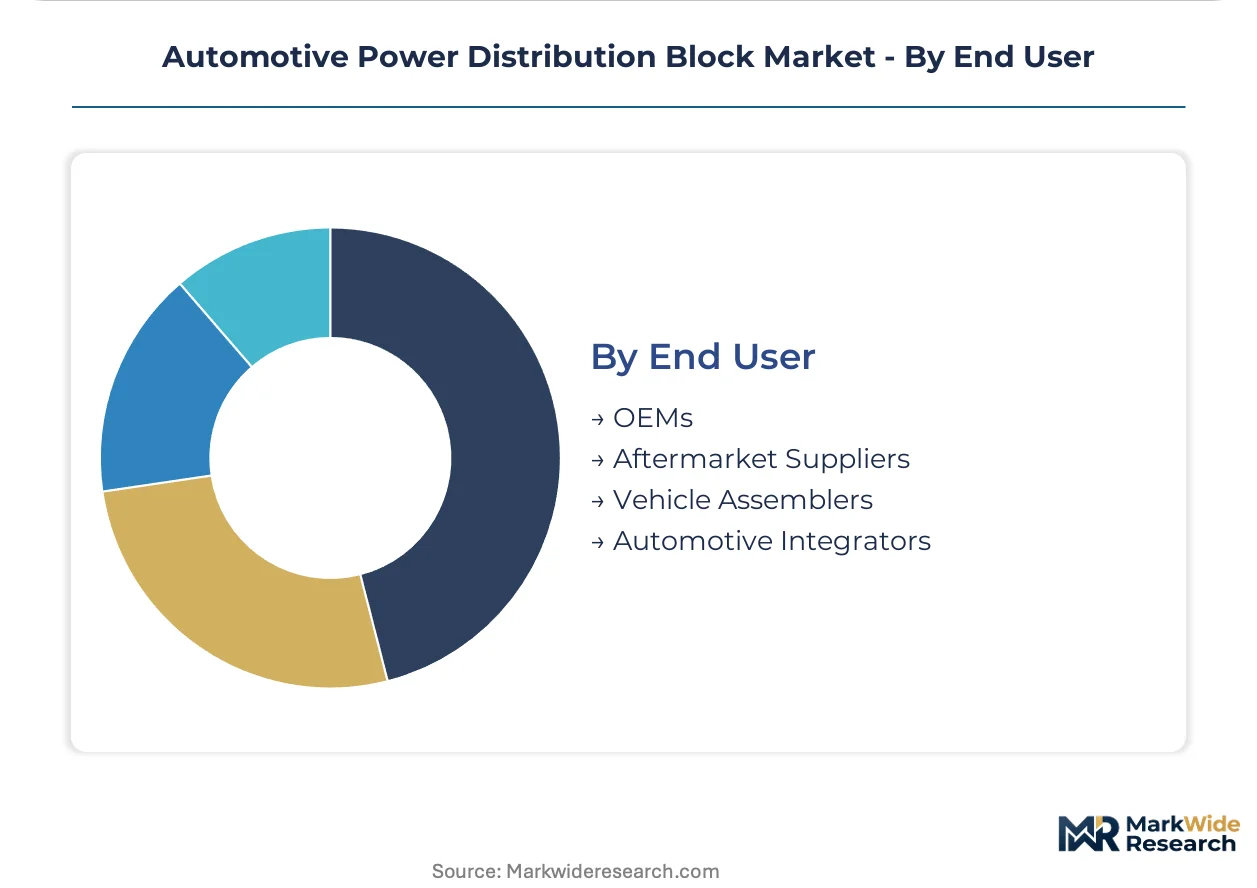
| Segmentation | Component: Fuse Block, Relay Module, Power Connector, Breaker Terminal Form Factor: Miniature, Standard, Compact, Custom Installation Type: Under Hood, Cabin Mount, Remote Mount, Integrated End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Automotive Integrators |
| Companies Covered | TE Connectivity, Eaton Corporation, Lear Corporation, Yazaki Corporation, Sumitomo Electric Industries, Littelfuse, Furukawa Electric, Leoni, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Distribution Block Market Emerging Trajectories
Active material substitution and regulatory pressure on thermal performance are compressing traditional electromechanical designs while expanding semiconductor-based protection architectures.
Stamped copper-aluminum hybrid busbars are displacing pure copper conductors in cost-sensitive volume platforms. Chinese and South Korean battery-electric vehicle programs have adopted these laminates for non-critical current paths, reducing conductor mass by approximately one-third while maintaining ampacity. The displacement of solid copper is compressing raw material exposure for mid-market suppliers.
EPA tailpipe rules and NHTSA safety standards collectively mandate higher electrical loads and tighter component reliability specifications. These regulations expand qualification testing for thermal cycling and vibration resistance across US-designed electrified powertrains. Distribution block suppliers serving Detroit-based OEMs have responded with integrated housing designs that consolidate multiple fuse positions into single molded assemblies.
Fleet procurement departments now specify outcome-based performance warranties rather than component-level purchasing. Commercial vehicle operators in German and US logistics corridors contract for guaranteed uptime metrics, transferring reliability risk to distribution block manufacturers. This model compresses spot-market component sales and elevates integrated power management system vendors with diagnostic and predictive maintenance capabilities.
Automotive Power Distribution Block Market Segmentation

Segmentation in automotive power distribution blocks reveals how voltage architecture shifts and packaging constraints reshape procurement priorities across electrified platforms. Component-level substitution pressures and form factor compression drive divergent margin structures across supplier tiers.
Component:
Fuse blocks face the most acute substitution threat as semiconductor-based protection architectures displace electromechanical interruption in high-voltage domains.
- Fuse Block:Stamped copper busbar assemblies with molded thermoplastic housings rated to 150°C dominate conventional 12V and emerging 400V architectures. German and US passenger EV programs concentrate procurement for these configurations as dual-voltage vehicles bridge legacy and electrified circuits.
- Relay Module:Electromechanical switching assemblies consolidate multiple circuits into single replaceable modules. Demand clusters in Japanese and North American vehicle programs where Yazaki Corporation anchors cabin-mount and under-hood supply relationships.
- Power Connector:High-voltage interface assemblies enabling safe mating under load.
- Breaker Terminal:Resettable overcurrent protection for commercial vehicle electrical systems.
Fuse blocks anchor the volume base while relay modules gain share at the steepest rate as integrated power management systems consolidate functions.
Form Factor:
Cost tier stratification separates premium custom solutions from commoditized standard formats serving volume platforms.
- Miniature:Reduced-footprint modules for space-constrained cabin and trunk-mount installations. Chinese battery-electric vehicle programs adopt these formats aggressively as MIIT dual carbon goals compress packaging allowances.
- Standard:Conventional blade-fuse and relay positions serving legacy internal-combustion architectures. These configurations retain installed base across cost-sensitive vehicle segments in India and Southeast Asia.
- Compact:Intermediate density for mid-range electrified platforms.
- Custom:Application-specific geometries for 800V architectures.
Standard formats dominate current production volumes while miniature configurations expand most quickly under thermal management pressures in electrified powertrains.
Installation Type:
Application-driven thermal zoning dictates engineering investment and ingress protection specification divergence.
- Under Hood:Engine-bay mounting exposes modules to temperature cycling, vibration, and fluid ingress. EPA tailpipe rules and NHTSA safety standards mandate enhanced thermal cycling qualification for these configurations in US-designed electrified powertrains.
- Cabin Mount:Interior installation with moderated thermal exposure and improved service access. European OEMs concentrate specification here as EU Green Deal vehicle-emission targets elevate electrical load requirements in passenger compartments.
- Remote Mount:Relocated fuse and relay modules away from thermal zones.
- Integrated:Consolidated power management within battery pack or inverter enclosures.
Under-hood mounting retains the largest installed base while remote-mount configurations climb the fastest as thermal management constraints intensify.
End User:
Customer type determines procurement authority migration patterns as platform voltage escalation concentrates decision-making.
- OEMs:Vehicle manufacturers with direct engineering authority over high-voltage architecture specification. 800V platform proliferation pulls procurement decisions toward OEM engineering teams with dedicated electrification programs in Germany, China, and the United States.
- Aftermarket Suppliers:Independent distributors and service channel providers for replacement and retrofit applications. These stakeholders concentrate in mature vehicle parc regions with extended fleet lifecycles.
- Vehicle Assemblers:Contract manufacturing operations with limited design authority.
- Automotive Integrators:Tier-1 system suppliers consolidating multiple electrical functions.
OEM direct procurement anchors the value base while automotive integrators gain specification influence fastest as integrated power management systems consolidate fuse, relay, and breaker functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific automotive component throughput, while German autobahns and US interstate corridors distribute electrified vehicle platforms across their respective manufacturing belts.
United States
Detroit Three OEMs consolidate 800V platform procurement authority within internal engineering teams. NHTSA safety standards mandate enhanced thermal cycling qualification for under-hood distribution blocks. The Southeast manufacturing corridor spanning Tennessee and South Carolina attracts supplier capacity expansion for electrified vehicle programs.
Germany
BMW, Mercedes-Benz, and Volkswagen anchor European demand for high-voltage distribution architectures. EU Green Deal vehicle-emission targets compress electrification timelines across Bavarian and Baden-Württemberg production networks. Stuttgart engineering clusters concentrate fuse and relay module specification authority with OEM direct procurement.
China
BYD, NIO, and CATL-backed vehicle programs drive volume procurement for 400V and 800V distribution systems. MIIT dual carbon goals and GB standards impose certification layers that filter non-domestic supplier market access. Yangtze River Delta manufacturing zones concentrate stamped copper busbar fabrication capacity for battery-electric platforms.
Japan
Toyota, Honda, and Nissan maintain hybrid-first strategies that sustain dual-voltage distribution block demand. METI industrial policy supports domestic supplier retention in cabin-mount and under-hood configurations. Nagoya and Tokyo metropolitan manufacturing belts concentrate relay module production for export-oriented vehicle programs.
South Korea
Hyundai-Kia and Samsung SDI partnerships accelerate 800V platform rollout across domestic and US manufacturing. MFDS-equivalent automotive component standards align with global electrification benchmarks. Gyeonggi Province supplier parks concentrate compact form factor distribution block production for battery-electric vehicle exports.
Automotive Power Distribution Block Market Vendor Landscape
Concentration sits with diversified electrical component conglomerates that span connector, fuse, and relay portfolios. The supplier base stratifies across three tiers: integrated power management system vendors, specialized distribution block fabricators, and commodity fuse assembly operators. Engineering-led OEM procurement is compressing Tier-2 component vendor influence. Dominant competitive moves include strategic partnerships for 800V qualification and geographic expansion into Chinese domestic supplier networks.
Within the integrated system tier, TE Connectivity and Eaton Corporation exemplify archetypes that consolidate fuse, relay, and breaker functions into single replaceable modules. Yazaki Corporation anchors a position among cabin-mount and under-hood specialists with established supply relationships across Japanese and North American vehicle programs. These three entities represent distinct strategic postures: connector-centric diversification, power management integration, and regional supply relationship depth.
| Leading Market Players |
|---|
| TE Connectivity |
| Eaton Corporation |
| Lear Corporation |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Littelfuse |
| Furukawa Electric |
| Leoni |
| Molex |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty days of safety stock for high-temperature PPA and PPS resins concentrate pricing power with German and Japanese chemical corridors, while OEMs with 800V platform commitments leverage volume commitments to compress unit costs for stamped copper busbar assemblies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market, with premium tiers commanding spreads based on ISO 26262 functional safety certification and GB standards compliance for Chinese market access. Price differentiation hinges on thermal cycling qualification depth and vertical integration of stamping operations. Cost compression in standard-tier fuse blocks is intensifying because Chinese battery-electric vehicle programs have adopted copper-aluminum hybrid laminates for non-critical current paths. Fleet procurement departments exhibit the lowest price sensitivity due to outcome-based performance warranties, while aftermarket distributors face the highest.
Supply Chain Analysis
China, Germany, and Japan anchor stamped copper busbar fabrication, high-temperature thermoplastic housing production, and electromechanical relay manufacturing respectively. The supply chain draws from copper cathode markets, PPA/PPS resin production, and precision stamping tooling. Single-source vulnerability in high-temperature resin supply creates geographic concentration risk. Distribution runs through Tier 1 automotive integrators with direct OEM engineering relationships, bypassing traditional component distributors for high-voltage architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for 800V safety certification and dual-architecture integration is constraining supplier qualification timelines, creating acquisition premiums for firms with validated high-voltage portfolios.
For Market Incumbents: Secure 800V platform qualification with German and US OEMs before semiconductor-based protection architectures displace electromechanical fuse blocks. Deepen backward integration into high-temperature resin compounding to reduce exposure to German and Japanese chemical corridor concentration. Prioritize diagnostic and predictive maintenance capabilities to capture fleet procurement contracts with outcome-based performance warranties. For New Entrants and Emerging Players: MIIT certification fast-tracks for 400V architectures offer the most penetrable entry point into Chinese battery-electric vehicle programs. Target remote-mount power distribution configurations where thermal management constraints have fragmented incumbent supply relationships. Pursue joint development agreements with Yangtze River Delta manufacturing zones to access stamped copper busbar fabrication capacity without capital-intensive greenfield investment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because engineering-led OEM procurement is compressing Tier 2 component vendor influence and elevating integrated power management system vendors. Target acquisition candidates with validated 800V portfolios and established supply relationships across German, Chinese, and US manufacturing corridors. The signal to watch is NHTSA and EPA regulatory acceleration for thermal cycling qualification standards that would extend validation timelines for non-incumbent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces SKU complexity for OEMs consolidating 400V and 800V architectures. |
| Battery Supply Agreement | Secures captive demand for integrated power management modules in CATL-backed programs. |
| Software-Defined Vehicle Investment | Enables predictive maintenance capabilities required by German and US fleet operators. |
| Geographic Manufacturing Footprint | Positions suppliers for US IRA clean vehicle tax credit domestic content requirements. |
| Charging Infrastructure Partnership | Creates aftermarket channel access for replacement distribution blocks in electrified parc. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed electrical component suppliers, and MIIT new energy vehicle certification records. Primary interviews engaged Tier 1 supplier procurement managers, OEM platform engineers for 800V architectures, aftermarket distributors, and dealership operations heads. Bottom-up triangulation across component-level bill-of-materials analysis and top-down reconciliation against vehicle production forecasts validated volume estimates.
Segmentation dimensions modeled include propulsion architecture, voltage platform tier, form factor class, installation type, and regional production cluster. CAGRs were derived from regression analysis of historical content-per-vehicle trends and OEM platform rollout schedules across the projection horizon. Forecast inputs incorporated copper price trajectory assumptions and GB standards compliance timeline estimates for non-domestic suppliers.
Decision-makers should treat outputs as directional under assumptions of sustained EPA tailpipe rule enforcement and continued MIIT dual carbon goal implementation; material deviation in regulatory trajectory or commodity price volatility would warrant model refresh. Recalibration cycles align with material shifts in NHTSA safety standard revisions and 800V platform adoption rates across major OEM electrification programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Fan Clutch Market
Powertrain
High Speed Engine Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Fuel Pumps Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Transmission Control System Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Camshaft Market
Powertrain
Torque Converter Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Turbine Housing for Automobile Market