
 Automotive Racing Seats Market | 2026-2036
Automotive Racing Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Racing Seats Market Outlook
Composite laminator talent pools in Italy's Motor Valley is collapsing, constraining output at OMP Racing S.p.A and Sabelt S.p.A just as order backlogs lengthen. Sparco S.p.A leverages its Borgo Panigale headquarters to sustain proximity to Ducati and Lamborghini motorsport programs. Recaro Holding GmbH anchors its position through captive supply of steel tube frames from Schwäbisch Hall.
Automotive racing seats are occupant restraint systems engineered to withstand specified g-loads through integrated harness slots, energy-absorbing foam layers, and shell constructions meeting FIA 8855-1999 or SFI 39.1 standards; their primary purpose is to reduce spinal compression and submarining risks during high-deceleration incidents. Bucket seats dominate professional motorsport due to fixed-back rigidity and weight minimization, while hybrid seats capture growth in amateur track-day segments where street-to-circuit convertibility matters. Carbon fiber shells command premium positioning at the expense of fiberglass alternatives, though leather upholstery retains share among automotive enthusiasts prioritizing tactile comfort over absolute mass reduction.
FIA homologation protocols and SFI Foundation certification requirements dictate shell deformation limits and flammability thresholds, effectively filtering non-compliant suppliers from sanctioned competition supply chains. DOT regulations for street-legal variants create dual-certification burdens for manufacturers serving both racing and enthusiast road-use segments. Stakeholders must monitor evolving side-impact test protocols under pending FIA revisions, as these will force redesign cycles before next homologation windows open.
Market Dynamics
FIA homologation protocols are compressing supplier qualification timelines while carbon fiber shell adoption accelerates material substitution cycles across motorsport tiers.
Growth Catalysts
- FIA 8855-1999 Certification Mandates:Tightened crash-test thresholds force professional racing teams to replace legacy equipment ahead of standard renewal cycles, sustaining replacement demand.
- Carbon Fiber Layup Automation:Autoclave-cured pre-preg manufacturing is reducing shell production cycle times and enabling mass-customization of seat geometries for driver-specific ergonomics.
- Nürburgring Circuit Ecosystem:Dense supplier networks surrounding Germany's premier racing circuits create procurement efficiency and technical collaboration density for European motorsport programs.
Market Restraints
- Epoxy Resin Price Volatility:Aerospace-grade resin supply constraints and petrochemical feedstock fluctuations compress margin structures for composite shell manufacturers.
- Italian Composite Laminator Scarcity:Collapsing talent pools in Emilia-Romagna's Motor Valley constrain output capacity at established suppliers just as order backlogs lengthen.
- Dual-Certification Burden:DOT street-legal requirements layered atop FIA competition standards force redundant testing cycles and SKU proliferation for manufacturers serving both segments.
Strategic Opportunities
- Amateur Track-Day Hybrid Seats:Street-to-circuit convertibility captures enthusiast segments underserved by fixed-back professional equipment, opening volume tiers below motorsport-grade pricing.
- Pending FIA Side-Impact Protocols:Anticipated revisions to lateral crash-test standards will force redesign cycles before next homologation windows, advantaging R&D-capable incumbents.
- Steel Tube Frame Backward Integration:Captive supply of structural frames from Schwäbisch Hall-style manufacturing clusters insulates against automotive seating component shortages.
Industry Challenges
- FIA Homologation Timeline Compression:Certification cycles for revised shell deformation limits and flammability thresholds strain engineering bandwidth and delay revenue recognition.
- Harness Slot Integration Complexity:Six-point restraint geometry must reconcile with energy-absorbing foam layers without compromising structural integrity under multi-axis loading.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Racing Seats Market |
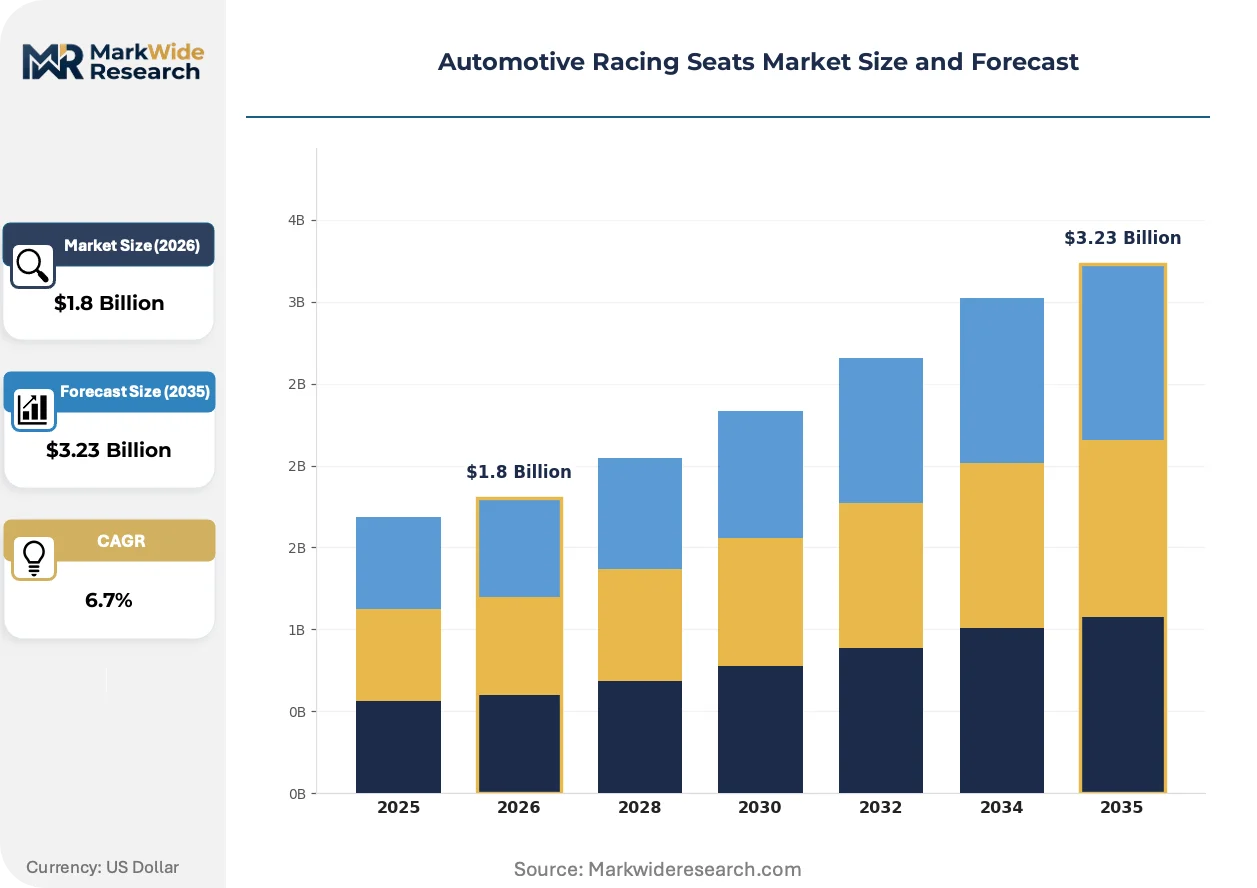
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Seats, Reclining Seats, Full Bucket Seats, Hybrid Seats Material: Carbon Fiber, Fiberglass, Leather, Alcantara End User: Professional Racers, Amateur Racers, Racing Teams, Automotive Enthusiasts Regulatory Compliance: SFI, FIA, SNELL, DOT |
| Companies Covered | Recaro Holding GmbH, Sparco S.p.A, Faurecia SE, OMP Racing S.p.A, Cobra Seats, Corbeau USA LLC, BRAUM Racing, Racetech Manufacturing Ltd., Sabelt S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Racing Seats Market Strategic Shifts
Active matrix infusion processes and regulatory pre-positioning are compressing product development cycles while demand fragments across professional motorsport and amateur enthusiast tiers.
Pre-impregnated carbon fiber autoclave curing is miniaturizing shell wall thicknesses while maintaining FIA-specified g-load resistance. GT3 and prototype racing programs are adopting these shells fastest, with some teams replacing fiberglass inventory entirely within single seasons. The technology is miniaturizing weight-to-strength ratios and enabling seat designs that were structurally impossible with wet-layup fiberglass construction.
REACH chemical restrictions on hexavalent chromium plating are forcing hardware suppliers to transition to trivalent alternatives for seat mounting brackets and harness anchors. European manufacturers face the steepest compliance costs, though the regulatory pressure is compressing supply chain differentiation as Asian suppliers accelerate equivalent certification. Motorsport-specific hardware vendors in Germany and Italy are responding by consolidating plating operations to capture economies of scale.
Direct-to-team technical consultation is displacing distributor-mediated specification for professional racing programs. Factory engineers now embed with customer squads during seat fitting protocols, capturing data that feeds iterative shell geometry refinement. This pattern is most visible in Formula regional and sports-car endurance categories, where driver-specific ergonomics determine competitive advantage and repeat procurement loyalty.
Automotive Racing Seats Market Segmentation
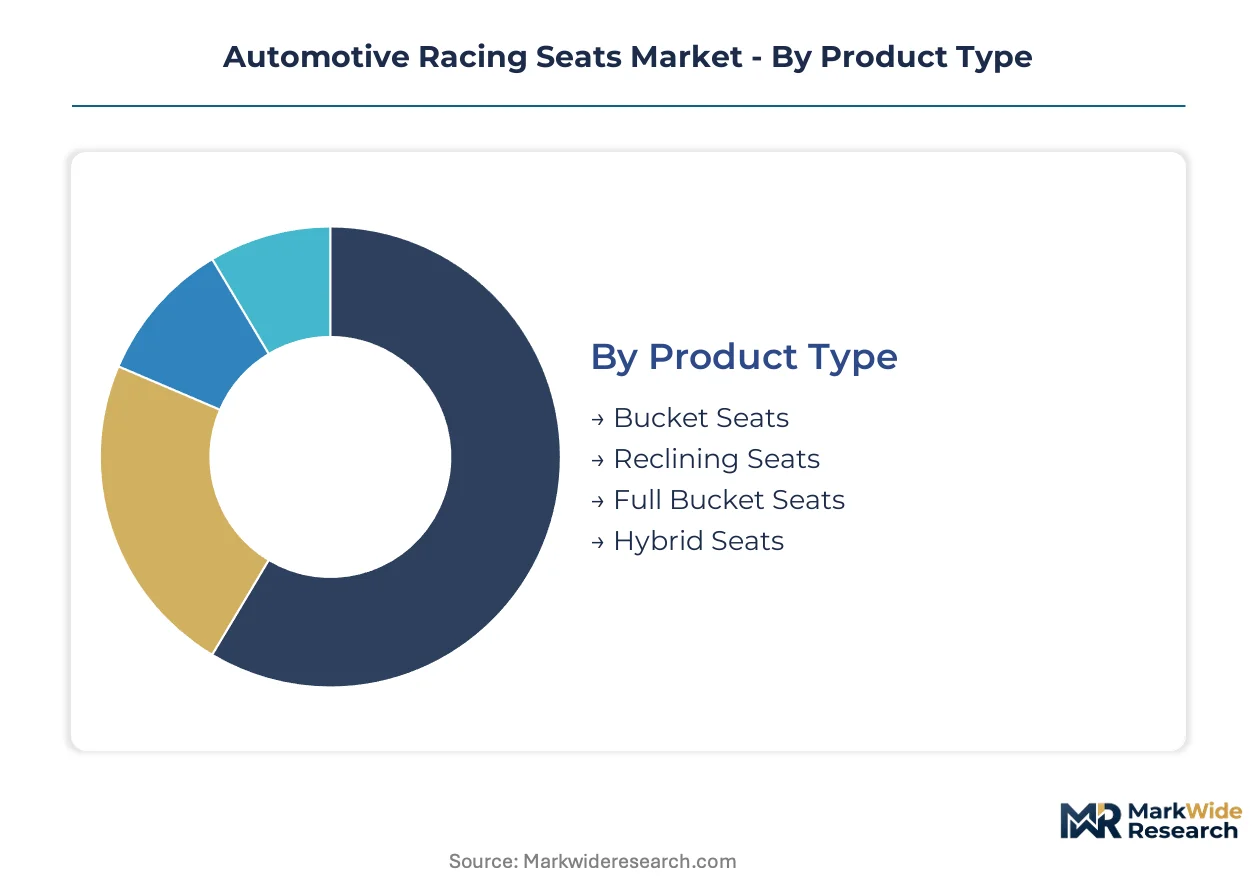
Racing seat procurement splits across certification grades, material technologies, and user sophistication levels. Each segmentation axis carries distinct margin profiles and engineering requirements that shape supplier specialization.
Product Type:
FIA 8855-1999 and SFI 39.1 certification tiers create rigid segmentation between fixed-back competition equipment and convertible street-circuit variants.
- Bucket Seats:Fixed-back rigid shells with integrated harness slots and energy-absorbing foam layers meeting FIA-specified g-load resistance. Professional motorsport programs in Germany's Nürburgring circuit ecosystem concentrate procurement here, driven by mandatory equipment replacement cycles under tightening crash-test thresholds.
- Hybrid Seats:Street-to-circuit convertible designs with reclining mechanisms and DOT street-legal certification layered atop competition-grade safety. Amateur track-day segments across Italy's Motor Valley and UK club racing circuits favor these, constrained by dual-certification testing burdens that compress supplier margins.
- Reclining Seats:Adjustable-back configurations prioritizing street drivability with secondary track capability.
- Full Bucket Seats:Maximum containment designs with pronounced side bolsters for high-g cornering loads.
Established volume favors Bucket Seats; emerging adoption favors Hybrid Seats.
Material:
Cost tier and performance tier separate autoclave-cured composites from conventional laminates and upholstery surfaces.
- Carbon Fiber:Autoclave-cured pre-preg shells with miniaturized wall thicknesses maintaining structural integrity under multi-axis loading. GT3 and prototype racing programs in Germany and Italy are displacing fiberglass inventory entirely within single seasons, constrained by epoxy resin price volatility and aerospace-grade supply constraints.
- Fiberglass:Wet-layup composite construction with higher mass-to-strength ratios and lower unit economics. Amateur endurance racing and entry-level formula categories sustain demand, though carbon fiber layup automation is compressing its addressable market.
- Leather:Premium upholstery prioritizing tactile comfort over absolute mass reduction among automotive enthusiasts.
- Alcantara:Synthetic suede surface treatment with enhanced grip characteristics for high-g maneuvers.
Premium positioning concentrates in Carbon Fiber; volume accessibility concentrates in Fiberglass.
End User:
Customer sophistication and procurement scale separate factory-direct technical relationships from distributor-mediated transactions.
- Professional Racers:Individual competitors requiring driver-specific shell geometry refinement through embedded factory engineer consultation. Formula regional and sports-car endurance categories in Germany and Italy exhibit this pattern, where repeat procurement loyalty depends on ergonomic competitive advantage.
- Racing Teams:Multi-car operations with centralized equipment standardization and bulk replacement scheduling. FIA homologation timeline compression strains their engineering bandwidth most acutely.
- Amateur Racers:Club-level competitors balancing performance requirements against personal budget constraints.
- Automotive Enthusiasts:Road-car owners seeking aesthetic and functional upgrades with occasional track use.
Technical collaboration density centers on Professional Racers; volume scaling potential centers on Racing Teams.
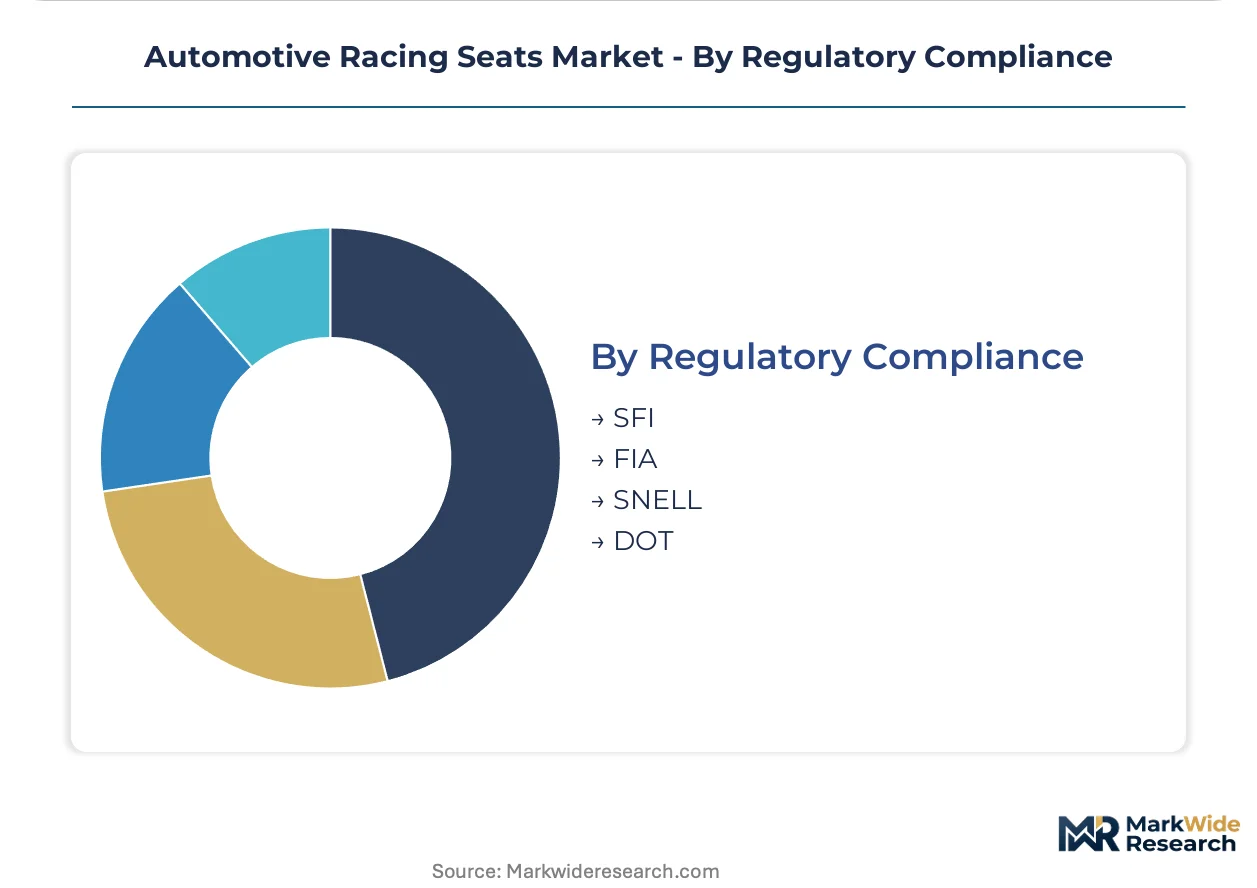
Regulatory Compliance:
Certification jurisdiction determines market access and redesign cycle frequency across competition and street-legal segments.
- FIA:8855-1999 shell deformation limits and flammability thresholds governing sanctioned international competition. European motorsport programs face pending side-impact protocol revisions that will force redesign cycles before next homologation windows.
- DOT:Street-legal requirements for occupant restraint systems creating dual-certification burdens when layered atop competition standards. US enthusiast segments drive this compliance layer.
- SFI:Foundation certification requirements filtering non-compliant suppliers from North American competition supply chains.
- SNELL:Supplementary helmet and equipment safety standards occasionally referenced for comprehensive program certification.
Competition access depends on FIA; street-legality depends on DOT.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates procurement of fixed-back competition equipment under tightening FIA protocols, while Italy's Motor Valley sustains artisan composite production and the United States drives dual-certification demand from amateur track-day segments. This three-way consumption split distinguishes the market's geographic footprint.
Germany
Nürburgring and Hockenheimring circuit ecosystems sustain dense supplier networks for professional motorsport procurement. KBA vehicle safety oversight intersects with FIA homologation timelines to compress equipment replacement cycles. Schwäbisch Hall manufacturing clusters anchor captive steel tube frame supply for integrated seat producers.
Italy
Emilia-Romagna's Motor Valley generates concentrated demand from Ducati and Lamborghini motorsport programs. REACH chemical restrictions on hexavalent chromium plating force hardware suppliers toward trivalent alternatives for mounting brackets. Borgo Panigale headquarters proximity enables Sparco S.p.A to sustain embedded technical consultation with factory racing teams.
United States
Amateur track-day enthusiasts drive hybrid seat procurement requiring DOT street-legal certification layered atop competition standards. SFI Foundation certification filters non-compliant suppliers from North American competition supply chains. California and Texas club racing circuits concentrate distributor-mediated transactions for convertible street-circuit equipment.
United Kingdom
Silverstone and Brands Hatch ecosystems sustain club-level endurance racing demand for fiberglass-shell entry equipment. Health and Safety Executive workplace regulations indirectly shape composite manufacturing protocols through laminator safety standards. Midlands manufacturing corridors host specialist seat fabricators serving historic motorsport restoration segments.
Japan
Super GT and Super Formula programs generate precision-engineered seat demand with driver-specific ergonomics requirements. METI industrial standards coordinate with FIA protocols for equipment import homologation. Osaka-Nagoya manufacturing corridors concentrate automotive seating component suppliers with motorsport diversification strategies.
Automotive Racing Seats Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Automotive Racing Seats Market. The upper tier commands FIA homologation expertise and captive composite manufacturing capacity, while mid-tier specialists compete on regional certification agility and driver-specific customization. Three archetypes dominate: vertically integrated shell producers with autoclave curing assets, hybrid-seat specialists navigating dual-certification burdens, and steel-frame fabricators with backward integration into structural components. Competitive moves concentrate on geographic expansion into Nürburgring-proximate supplier networks and portfolio diversification toward amateur track-day convertible designs.
Among German-integrated manufacturers, Recaro Holding GmbH anchors the steel-frame fabrication archetype through Schwäbisch Hall supply cluster control. Italian specialists Sparco S.p.A and OMP Racing S.p.A occupy positions within the composite shell tier, with Sparco exemplifying proximity-based technical collaboration models and OMP representing artisan laminator-dependent production constraints. These three entities collectively illustrate the geographic and capability segmentation shaping competitive positioning.
| Leading Market Players |
|---|
| Recaro Holding GmbH |
| Sparco S.p.A |
| Faurecia SE |
| OMP Racing S.p.A |
| Cobra Seats |
| Corbeau USA LLC |
| BRAUM Racing |
| Racetech Manufacturing Ltd. |
| Sabelt S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day autoclave curing cycles for carbon fiber shells concentrate pricing power with Italian and German manufacturers possessing captive composite capacity, compressing margins for distributors dependent on spot-market resin procurement. FIA homologation timelines extend order-to-delivery windows, forcing racing teams to absorb premium pricing for certified inventory or risk competitive disqualification.
Pricing Analysis
Long-term offtake agreements dominate professional motorsport procurement, with factory-direct contracts spanning full seasons anchoring revenue visibility for Recaro Holding GmbH and Sparco S.p.A. Price differentiation rests on certification grade—FIA 8855-1999 homologation commands substantial premiums over SFI 39.1 equivalents—and driver-specific customization intensity. Cost compression in fiberglass tiers is intensifying because carbon fiber layup automation erodes the cost gap between composite grades. Amateur track-day enthusiasts exhibit highest price sensitivity, while factory-backed racing teams prioritize ergonomic precision over unit economics.
Supply Chain Analysis
Inbound logistics costs for aerospace-grade epoxy resin from Rotterdam port corridors fluctuate with container availability across Asia-Europe trade lanes, amplifying working capital requirements for shell producers. Manufacturing gravity centers on Germany, Italy, and Japan, with Emilia-Romagna's Motor Valley and Schwäbisch Hall clusters anchoring European output. Raw material dependencies encompass carbon fiber pre-preg, steel tube frames, and energy-absorbing foam formulations. Single-source vulnerability in Italian composite laminator talent pools threatens output continuity. Distribution runs through circuit-proximate technical centers and motorsport equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FIA side-impact protocol revisions represent a regulatory inflection compressing product development cycles while carbon fiber shell adoption accelerates material substitution across motorsport tiers. This disruption creates asymmetric opportunity for R&D-capable incumbents and agile specialists.
For Market Incumbents: Fortify captive composite manufacturing capacity through autoclave asset expansion in Schwäbisch Hall-adjacent clusters, insulating against Italian laminator scarcity. Deepen embedded technical consultation protocols with factory racing teams to lock repeat procurement loyalty before pending FIA homologation windows open.
For New Entrants and Emerging Players: Lead with amateur track-day hybrid seats as the most penetrable white space, exploiting dual-certification burdens that constrain established suppliers' margin structures. Target California and Texas club racing circuits through direct-to-consumer digital channels, circumventing distributor-mediated specification dominated by incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive seating conglomerates with underexploited motorsport divisions possessing dormant FIA homologation expertise. Long-term viability hinges on carbon fiber shell automation capabilities and proximity to Nürburgring-proximate supplier networks. Monitor REACH chemical restriction enforcement as an inflection signal for hardware supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Expansion | Captive curing assets insulate against Italian laminator scarcity and compress shell production cycle times. |
| FIA Pre-Homologation Investment | Early side-impact protocol compliance secures certification windows before competitor redesign cycles complete. |
| Hybrid Seat Portfolio Diversification | Street-to-circuit convertibility captures amateur track-day volume tiers below professional motorsport pricing. |
| Steel Tube Frame Backward Integration | Schwäbisch Hall manufacturing cluster control anchors structural component supply against automotive seating shortages. |
| Direct-to-Team Technical Consultation | Embedded factory engineer protocols capture driver-specific ergonomic data and sustain repeat procurement loyalty. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FIA homologation databases, KBA vehicle safety filings, and composite materials trade publications, cross-checking interview-derived demand signals with customs and production data. Primary engagements encompassed racing team equipment managers, composite manufacturing engineers, motorsport distributor procurement leads, and regulatory compliance officers across Germany, Italy, and the United States. Bottom-up seat shipment tallies by certification grade and material technology were triangulated against top-down market sizing derived from motorsport program expenditure patterns.
Segmentation dimensions modeled span product type, material technology, end-user sophistication, and regulatory compliance jurisdiction across the analysis window. Carbon fiber adoption curves, FIA homologation renewal frequencies, and circuit-proximate supplier network densities informed volume projections. CAGRs were derived from regression analysis of historical equipment replacement cycles and forward-looking regulatory timeline compression.
The analysis sits within stated boundaries; outcomes outside continued FIA protocol tightening, stable aerospace-grade resin supply, and sustained Nürburgring circuit ecosystem investment would require recalibration. Forecasts reflect assumptions regarding homologation timeline adherence and composite laminator workforce stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Automotive Heaters Market