
 Motorcycle Hub Motor Market | 2026-2036
Motorcycle Hub Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Hub Motor Market Foresight
Skilled magnet wire winding technicians is unwinding as a bottleneck across Southeast Asian motor plants, forcing manufacturers to automate stator assembly lines earlier than planned. Yadea leverages its captive ferrite magnet supply chain to shield margins from rare earth volatility. Honda anchors its hub motor R&D at its Kumamoto facility, where thermal management patents give it an edge in high-power density designs.
A motorcycle hub motor integrates the electric motor directly into the wheel hub, eliminating chains, belts, or gears through direct torque transmission to the rim; typical units operate at 48-72V with peak efficiencies exceeding 90% and rely on concentrated windings to minimize axial length. Brushless DC architectures dominate commuter and scooter applications where regenerative braking and silent operation matter most, while 1000W power ratings are gaining traction in dirt bike and off-road segments where torque density determines competitive positioning. Synchronous motor variants command premium positioning in touring bikes that require sustained highway speeds without thermal fade.
China's SAMR enforces GB/T motor efficiency tiers that disqualify induction hub motors from national subsidy eligibility, while India's CEA mandates localized testing under BIS certification before grid-connected charging infrastructure approval. The EU's F-Gas Regulation indirectly pressures thermal management design by restricting refrigerants used in battery cooling systems paired with hub motor powertrains. Stakeholders must track how battery-swapping standardization across ASEAN regulators reshapes motor-controller integration requirements before committing to platform architectures.
Market Dynamics
The motorcycle hub motor market pivots on China's GB/T efficiency tier enforcement, which disqualifies induction architectures from subsidy eligibility and forces synchronous motor adoption across Southeast Asian export supply chains.
Growth Catalysts
- GB/T Efficiency Tiers:China's SAMR mandates disqualify induction hub motors from national subsidies, accelerating brushless DC architecture penetration in Vietnam and Indonesia assembly plants.
- Last-Mile Fleet Electrification:Urban delivery operators in Ho Chi Minh City and Jakarta are procuring hub motor scooters at volumes that justify dedicated stator winding lines.
- Ferrite Magnet Supply Security:Captive ferrite sourcing insulates margin structures from rare earth price volatility affecting neodymium-dependent competitors.
Market Restraints
- Rare Earth Concentration:Neodymium supply chains concentrate in Chinese processing facilities, exposing non-integrated assemblers to input cost spikes.
- Induction Motor Exclusion:GB/T tier requirements structurally bar induction architectures from subsidy pools, compressing technology choice flexibility.
- Thermal Management Complexity:Sustained highway speeds in touring applications demand liquid cooling systems that add mass and assembly cost.
Strategic Opportunities
- Battery-Swapping Convergence:ASEAN regulator coordination on swapping standards creates white space for motor-controller integration platforms serving Vietnam, Thailand, and Philippines fleets.
- Off-Road Power Scaling:Dirt bike segments above 1000W remain underpenetrated by hub solutions, offering torque density positioning against chain-drive competitors.
- EU F-Gas Thermal Design:Refrigerant restrictions on battery cooling systems paired with hub motors force thermal management innovation that patents can capture.
Industry Challenges
- Magnet Wire Technician Scarcity:Skilled stator winding labor pools in Hanoi and Ho Chi Minh City manufacturing corridors cannot scale with assembly line expansion timelines.
- BIS Certification Timelines:India's CEA mandates localized testing before grid-connected charging approval, delaying hub motor platform launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Hub Motor Market |
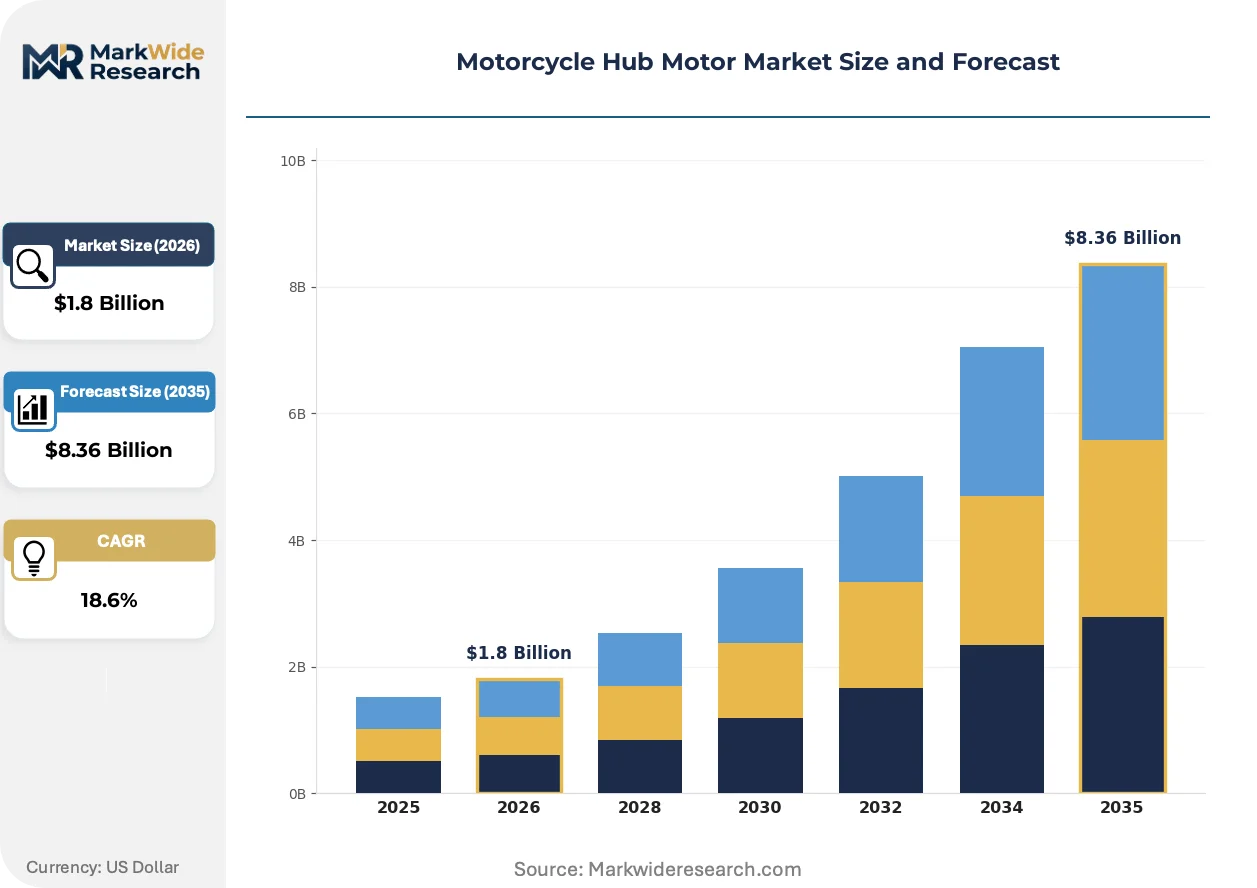
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless DC, Stepper, Synchronous, Induction Power Rating: 250W, 500W, 750W, 1000W Vehicle Type: Electric Bikes, Dirt Bikes, Touring Bikes, Scooters Application: Commuting, Off-Roading, Racing, Recreational |
| Companies Covered | Ducati, TYCORUN, Yadea, Hero Electric, Kymco, Yamaha, Suzuki, Niu Technologies, Honda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Hub Motor Market Shifts & Advancements
Hub motor architecture is splitting along thermal performance lines as commuter efficiency mandates diverge from touring power density requirements, reshaping R&D allocation across supplier tiers.
Concentrated winding topologies are bifurcating the market into axial-length-optimized commuter units and radial-flux touring designs. Scooter fleet operators in Vietnamese manufacturing corridors specify sub-120mm axial lengths for wheel packaging, while highway-capable touring bikes demand distributed windings that sustain 90kph thermal equilibrium. This technical split is compressing supplier R&D budgets into parallel development tracks with incompatible tooling.
The EU's F-Gas Regulation restricts refrigerants in battery cooling systems paired with hub motor powertrains, forcing air-cooled thermal architectures for sub-3kW commuter segments. Manufacturers serving German and French markets are redesigning stator housings with integrated heat sinks that eliminate refrigerant loops entirely. Touring bike suppliers targeting autobahn-capable speeds retain liquid cooling but must certify alternative working fluids under ECHA review timelines.
Fleet procurement contracts now specify motor-controller integration standards ahead of ASEAN battery-swapping harmonization. Indonesian and Thai last-mile operators are rejecting hub motors without CAN-bus interoperability, forcing controller suppliers to pre-certify protocol stacks. This behavior concentrates procurement among vertically integrated motor-controller pairings that can guarantee swapping station compatibility before regulator finalization.
Motorcycle Hub Motor Market Segmentation
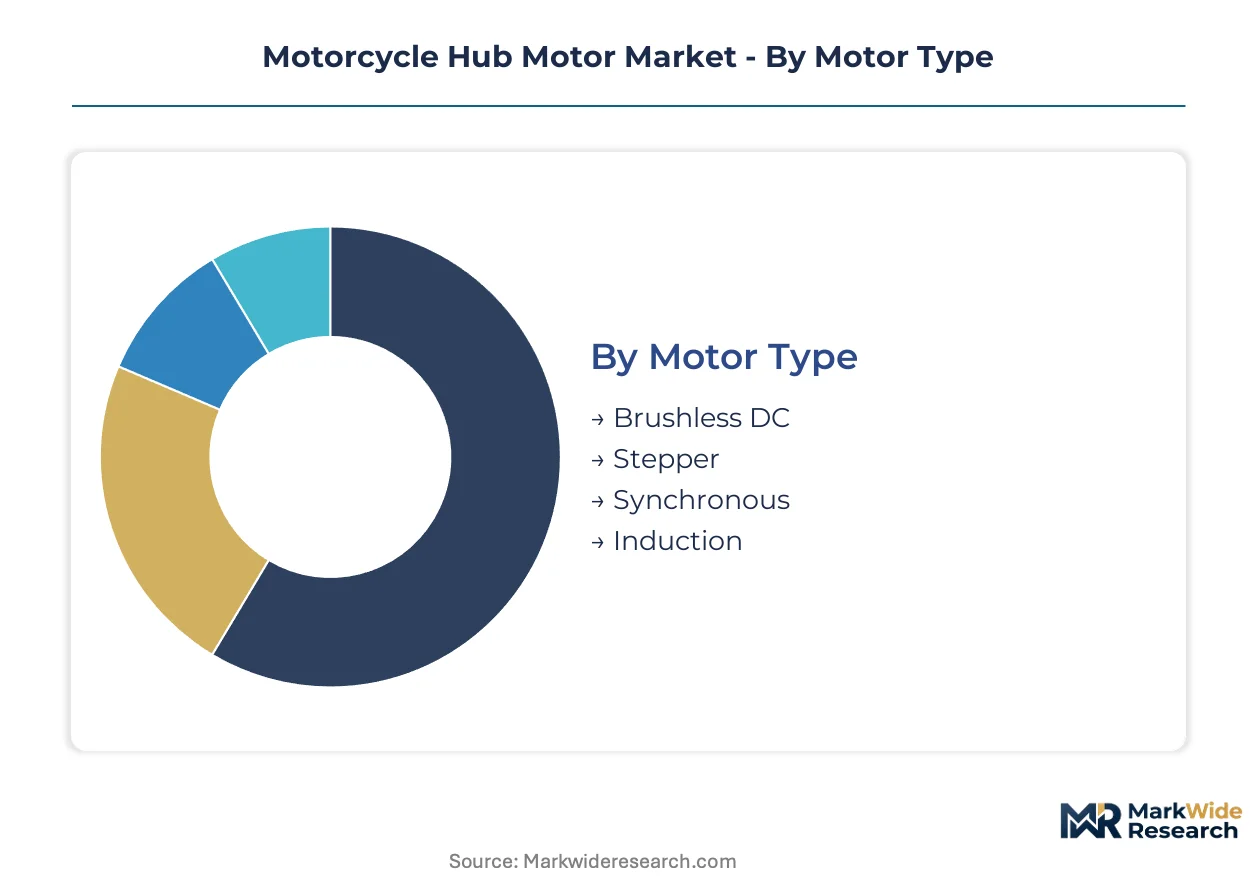
Hub motor procurement channels diverge sharply between fleet operators demanding standardized 48V commuter units and specialty distributors serving performance segments. Understanding these channel-segment pairings reveals where margin pools concentrate and which technical specifications gate market entry.
Motor Type:
Channel mix splits between mass-market assemblers sourcing brushless DC architectures and premium distributors stocking synchronous variants for thermal-critical applications.
- Brushless DC:Permanent magnet rotors with electronic commutation deliver peak efficiencies above 90% at 48-72V operating ranges. Vietnamese scooter fleet operators in Hanoi and Ho Chi Minh City procurement corridors specify these units exclusively for last-mile delivery electrification, driven by SAMR GB/T efficiency tier compliance requirements that disqualify induction alternatives from subsidy eligibility.
- Synchronous:Field-excited or permanent magnet synchronous architectures sustain thermal equilibrium at sustained highway speeds without flux weakening. German and French touring bike manufacturers source these through specialized thermal-management distributors, constrained by EU F-Gas Regulation refrigerant restrictions that force air-cooled or alternative-fluid designs.
- Stepper:Discrete angular positioning capability suits experimental autonomous motorcycle prototypes and precision torque control applications in racing telemetry systems.
- Induction:Squirrel-cage rotor designs without rare earth dependencies attract cost-focused assemblers, though Chinese subsidy exclusion compresses addressable demand pools.
By volume, Brushless DC leads. By growth pace, Synchronous is climbing the fastest.
Power Rating:
Cost tier stratification maps directly to licensing regimes and battery pack economics across ASEAN manufacturing corridors.
- 250W:Pedal-assist threshold compliance for European L1e-A classification and Asian bicycle-motorcycle regulatory boundaries. Indonesian and Thai commuter assemblers dominate procurement through battery-swapping network integrators.
- 500W:Urban scooter standard balancing acceleration against range preservation; dominates Ho Chi Minh City fleet replacement cycles.
- 750W:Emerging sweet spot for Vietnamese domestic market models bridging moped displacement equivalence without full motorcycle licensing requirements.
- 1000W:Torque density positioning against chain-drive competitors in dirt bike segments; off-road distributors in Philippines and Malaysia specification sheets increasingly feature hub alternatives.
By volume, 500W leads. By margin expansion, 1000W is gaining share fastest.
Vehicle Type:
Application maturity determines whether channels flow through OEM direct procurement or aftermarket retrofit distributors.
- Electric Bikes:Pedal-assist and throttle-controlled variants with integrated battery-motor systems; dominates European urban commuter channels and Asian fleet electrification.
- Scooters:Step-through architectures with swingarm-integrated hub motors; Vietnamese and Indonesian manufacturing corridors concentrate assembly capacity for Grab and Gojek fleet operators.
- Touring Bikes:Highway-capable designs demanding sustained thermal performance; German autobahn-rated specifications drive liquid-cooled synchronous adoption through premium distributor networks.
- Dirt Bikes:Off-road torque density requirements historically served by chain drives; hub motor penetration remains underdeveloped above 1000W ratings.
By volume, Scooters lead. By technology upgrade intensity, Touring Bikes are expanding most quickly.
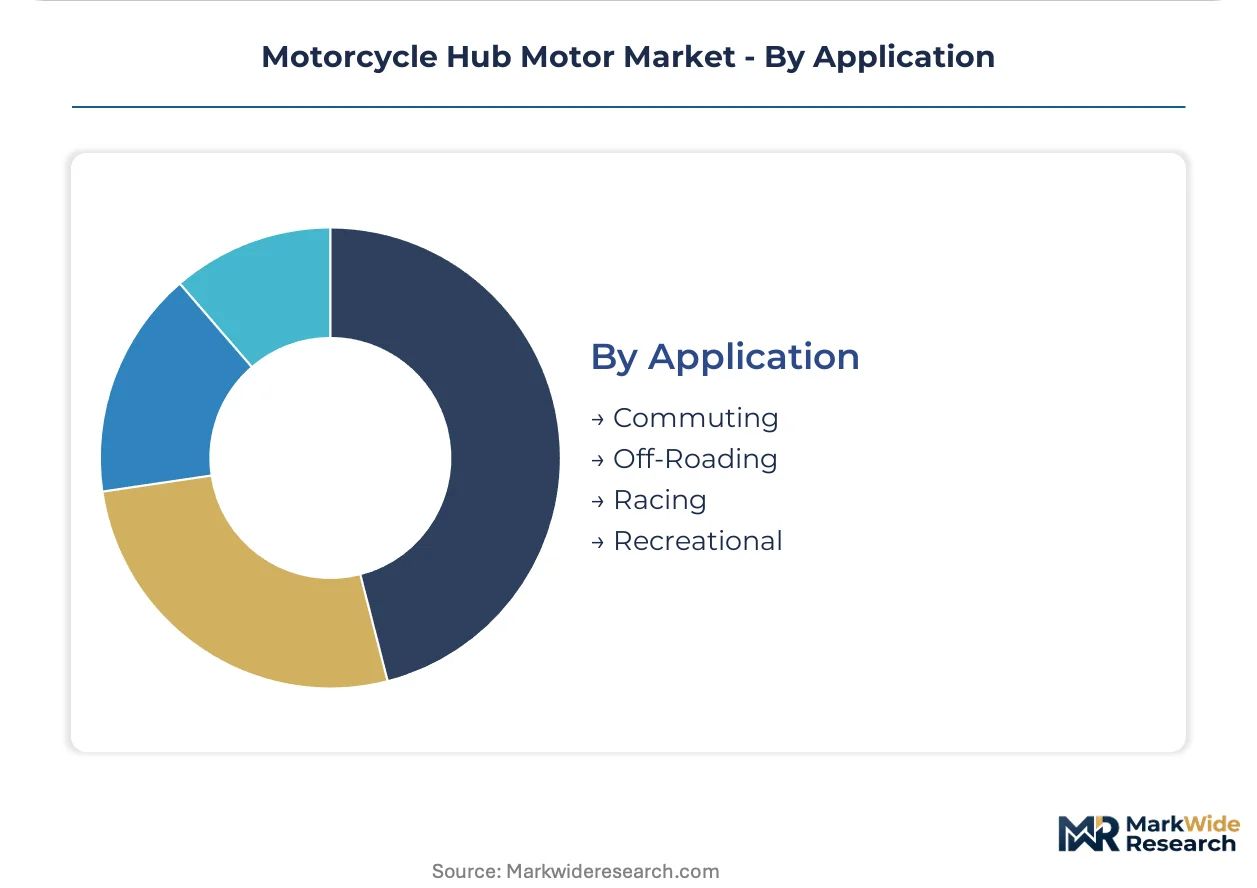
Application:
Customer type segmentation separates fleet procurement standardization from individual purchaser performance prioritization.
- Commuting:Daily urban transport with reliability and cost-per-kilometer optimization; Indonesian and Thai last-mile operators specify CAN-bus interoperability ahead of ASEAN battery-swapping harmonization.
- Off-Roading:Terrain-variable torque demands with impact resistance requirements; Philippines and Malaysian trail bike distributors test hub durability against mud intrusion and shock loading.
- Racing:Competition-specification thermal limits and weight minimization; track-day organizers in Japan and South Korea prototype hub motors for electric motorcycle racing series.
- Recreational:Weekend leisure riding with styling and acceleration emphasis; European consumer channels favor integrated design aesthetics over raw performance metrics.
By volume, Commuting leads. By specification intensity, Racing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China treats hub motors as export-platform components bound for Southeast Asian assembly plants, whereas Vietnam and Indonesia consume them through domestic fleet electrification programs that prioritize localized procurement.
China
GB/T efficiency tier enforcement by SAMR disqualifies induction architectures from national subsidy pools, forcing synchronous motor adoption across export supply chains. The MIIT tightens motor performance certification requirements quarterly. Yangtze River Delta manufacturing clusters near Shanghai export brushless DC units to Vietnamese assembly corridors.
Vietnam
Grab and Gojek fleet operators in Ho Chi Minh City and Hanoi specify 48-72V hub motors with CAN-bus interoperability for battery-swapping integration. The Ministry of Transport mandates electric two-wheeler registration standards that favor hub motor architectures. Manufacturing corridors near Hanoi scale dedicated stator winding lines to meet domestic assembly demand.
Indonesia
Last-mile delivery electrification in Jakarta drives procurement of 500W commuter units through battery-swapping network integrators. The national energy regulator aligns charging infrastructure standards with ASEAN harmonization timelines. Surabaya and Bandung assembly plants source hub motors through Thai distributor networks.
Germany
Autobahn-capable touring bike specifications demand liquid-cooled synchronous architectures that sustain thermal equilibrium above 90kph. The KBA enforces type-approval standards that restrict refrigerant-based cooling systems under EU F-Gas Regulation limits. Bavarian R&D facilities prototype air-cooled thermal management for sub-3kW commuter segments.
India
Domestic electric motorcycle assembly scales in Maharashtra and Tamil Nadu corridors where BIS certification delays platform launches by 8-14 months. The CEA mandates localized testing before grid-connected charging infrastructure approval. Bangalore and Chennai technical centers develop motor-controller integration for battery-swapping compatibility.
Motorcycle Hub Motor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on thermal management and winding automation. The upper tier commands procurement relationships with ASEAN fleet operators through captive magnet supply chains. Three archetypes dominate: vertically integrated automotive incumbents, ferrite-secured Chinese assemblers, and precision-winding equipment specialists. Competitive moves center on backward integration into magnet wire supply and geographic expansion into Vietnamese manufacturing corridors.
Among automotive-derived incumbents, Honda and Yamaha occupy positions defined by thermal management patent portfolios and highway-speed durability testing. Within the Chinese specialist tier, Yadea exemplifies ferrite supply security that insulates margin structures from rare earth volatility. Niu Technologies represents the fleet-focused archetype with controller integration capabilities aligned to ASEAN battery-swapping standardization timelines.
| Leading Market Players |
|---|
| Ducati |
| TYCORUN |
| Yadea |
| Hero Electric |
| Kymco |
| Yamaha |
| Suzuki |
| Niu Technologies |
| Honda |
| Others |
Supply & Pricing Matrix
China's GB/T efficiency tier enforcement by SAMR gates both supplier qualification and price differentiation simultaneously, compressing induction motor vendors into subsidy-ineligible tiers while rewarding synchronous architectures with premium positioning across Vietnamese and Indonesian procurement corridors.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement from Grab and Gojek operators, while spot purchases persist in aftermarket retrofit channels. Price differentiation separates CAN-bus certified units from basic commuter specifications, with thermal management patents commanding additional premiums in German touring segments. Cost compression in 500W commuter tiers is intensifying because ferrite-secured Chinese assemblers leverage captive magnet supply chains. Fleet operators exhibit highest price sensitivity, whereas autobahn-rated touring bike manufacturers prioritize thermal equilibrium over unit economics.
Supply Chain Analysis
Inventory lead times for neodymium-dependent stator assemblies stretch disproportionately against ferrite-sourced alternatives, forcing procurement teams to dual-source magnet wire specifications. Manufacturing concentrates in China, Vietnam, and Indonesia, with Yangtze River Delta clusters feeding export demand to Southeast Asian assembly plants. The supply chain draws from rare earth processing facilities in Chinese refining corridors, copper winding stock from Chilean concentrate, and ferrite powder from domestic Chinese mines. Single-source vulnerability in neodymium separation exposes non-integrated assemblers to input cost spikes. Distribution runs through ASEAN battery-swapping network integrators serving last-mile fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket thermal management retrofit services and controller firmware subscription layers are expanding faster than hub motor hardware shipments, creating service-attach economics that reshape vendor profitability models.
For Market Incumbents: Compound thermal management patent portfolios against emerging air-cooled synchronous competitors from Chinese specialist tiers. Add dedicated stator winding capacity in Vietnamese manufacturing corridors near Ho Chi Minh City to offset technician scarcity bottlenecks. Defend margin structures through backward integration into ferrite magnet supply rather than neodymium exposure. For New Entrants and Emerging Players: Anchor in dirt bike segments above 1000W where hub motor penetration remains underdeveloped against chain-drive incumbents. Target Philippine and Malaysian off-road distributors seeking torque density alternatives for trail bike specifications. Lead with CAN-bus pre-certification to capture ASEAN battery-swapping standardization timelines ahead of regulator finalization. For Investors and Strategic Acquirers: ASEAN battery-swapping harmonization milestones reshape the acquisition landscape toward motor-controller integration platforms with guaranteed station compatibility. Five-to-ten year viability favors vertically integrated specialists with captive ferrite supply and Vietnamese manufacturing footprints. Monitor BIS certification queue lengths in India as inflection indicators for platform launch delays affecting valuation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Magnet Supply | Yadea's captive sourcing insulates margins from rare earth volatility affecting neodymium competitors. |
| Stator Winding Automation Deployment | Automated assembly lines in Vietnamese corridors offset technician scarcity forcing procurement delays. |
| Thermal Management Patent Expansion | Honda's Kumamoto R&D leverages liquid-cooled architectures for autobahn-rated touring specifications. |
| CAN-Bus Controller Pre-Certification | Niu Technologies aligns motor-controller pairings to ASEAN battery-swapping standardization timelines. |
| Air-Cooled Architecture Redesign | EU F-Gas Regulation refrigerant restrictions force alternative thermal designs for sub-3kW commuter segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from listed electric two-wheeler manufacturers, MIIT motor performance certifications, and ASEAN trade customs data. Interviews with procurement managers at Vietnamese fleet operators, stator winding technicians in Ho Chi Minh City manufacturing corridors, thermal management engineers at Japanese R&D facilities, and battery-swapping network integrators in Jakarta provided demand-side validation. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Motor type, power rating, vehicle type, and application dimensions structure the analytical framework across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate GB/T efficiency tier enforcement timelines, BIS certification processing rates, and ASEAN regulator coordination on swapping standards.
Material uncertainties — rare earth price volatility, technician labor pool constraints, and regulatory certification delays — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
GPS Bike Computers Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Motorcycle Filter Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Bicycle Trip Market