
 Automotive Antenna Module Market | 2026-2036
Automotive Antenna Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Antenna Module Market Analysis
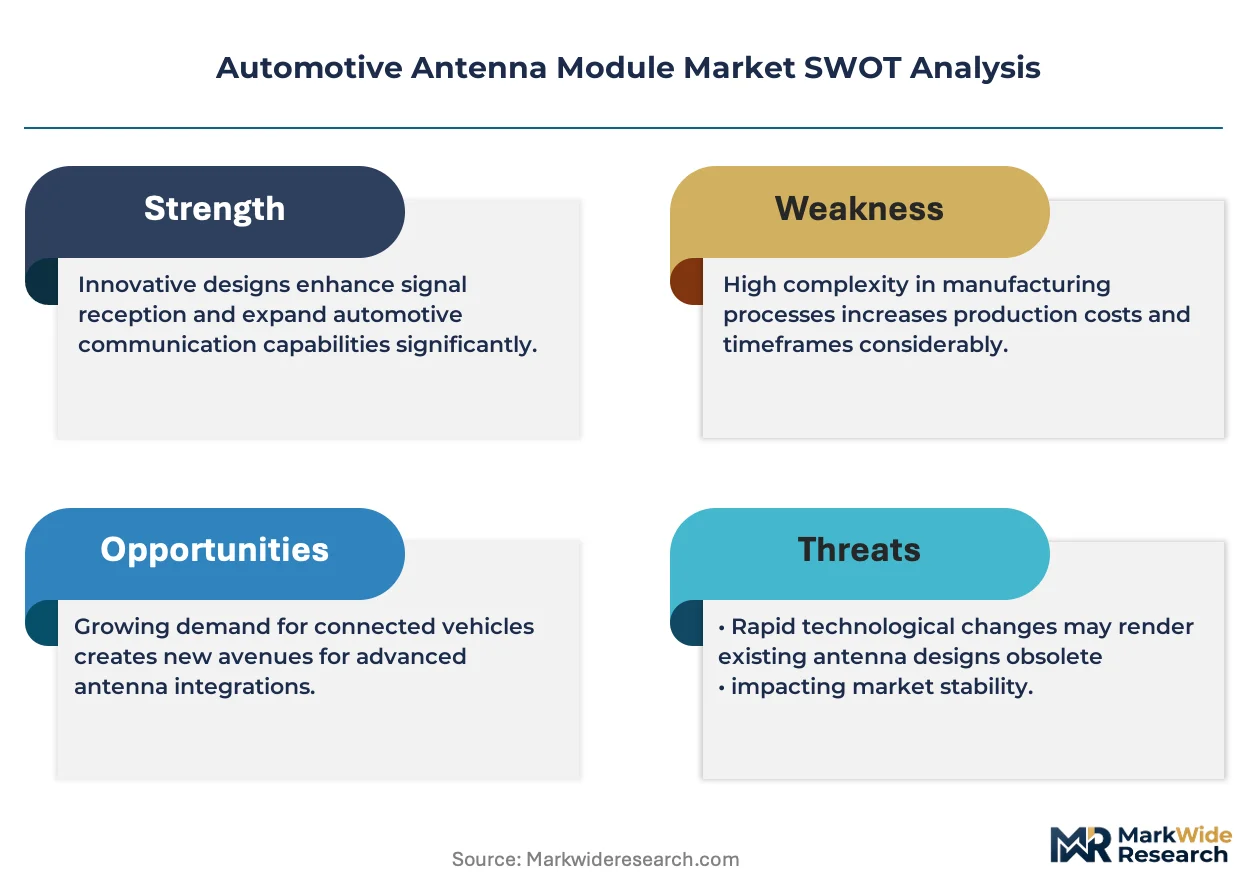
Polymer composites are displacing traditional metallic substrates and is recalibrating bill-of-materials economics for antenna housings. Continental AG leverages captive resin-compounding operations to protect margin pools on multi-band arrays. TE Connectivity anchors North American supply through vertically integrated coaxial cable production. Bosch competes on software-defined antenna tuning, differentiating its modules from hardware-only rivals.
An automotive antenna module is an electromechanical assembly that converts electromagnetic waves into electrical signals across specified frequency bands, typically incorporating low-noise amplifiers, ground planes, and dielectric substrates engineered for vehicle-grade thermal cycling. Its primary purpose is to enable reliable wireless communication for navigation, telematics, infotainment, and vehicle-to-everything protocols. Active antennas command premium positioning due to integrated amplification circuitry, while combination antennas consolidate GPS, cellular, and satellite reception into single enclosures to reduce roofline clutter. Bluetooth-enabled modules represent the fastest-growing technology segment as cabin wireless device pairing becomes standard across vehicle classes.
The EU Green Deal and REACH frameworks restrict hazardous substances in antenna substrates, compelling reformulation of polymer compounds. The EPA regulates electromagnetic emissions from automotive electronics in the United States, shaping shielding and filtering specifications for modules sold into that market. Stakeholders must weigh regulatory compliance timelines against module miniaturization roadmaps when allocating R&D budgets.
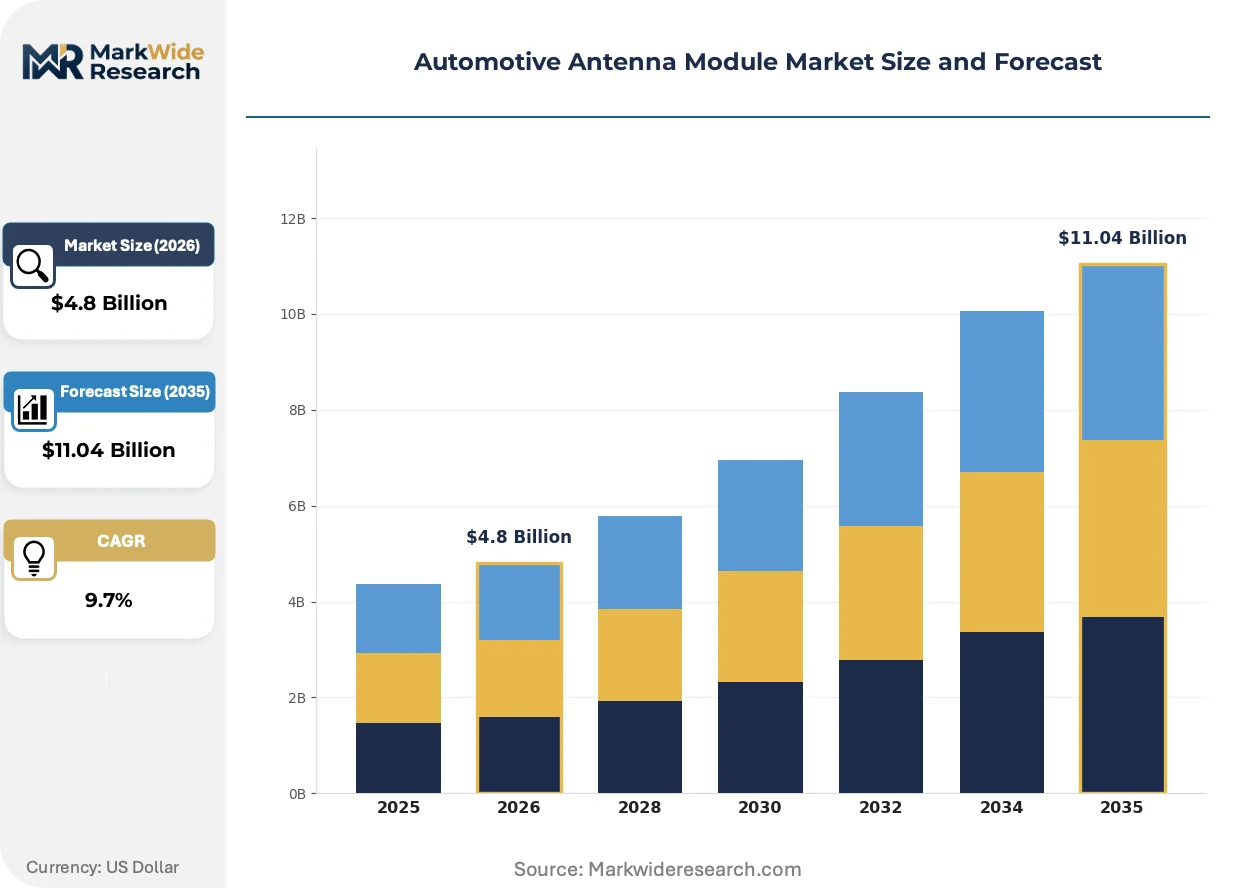
Market Dynamics
Polymer substrate substitution is compressing antenna housing costs while EU REACH compliance deadlines force simultaneous material reformulation, creating a dual-pressure environment where margin protection depends on captive resin supply.
Growth Catalysts
- EU Green Deal vehicle connectivity mandates:Binding emission and data-transmission standards are compelling OEMs to upgrade telematics hardware across production lines.
- Bluetooth-enabled cabin pairing:Standardization of wireless device integration across vehicle classes is pulling module demand through infotainment system refresh cycles.
- German automotive electronics clusters:Concentrated supplier ecosystems in Baden-Württemberg and Bavaria are reducing procurement friction for multi-band array sourcing.
Market Restraints
- Specialized polymer compound volatility:Dielectric substrate feedstocks face price instability due to petrochemical supply tightness and bio-based alternative scale limitations.
- Active antenna amplification cost structure:Integrated low-noise amplifier circuitry adds 15-25% bill-of-materials overhead versus passive alternatives.
- REACH substance restriction timelines:Accelerated hazardous substance phase-outs compress R&D windows for compliant substrate reformulation.
Strategic Opportunities
- Software-defined antenna tuning:Digital beamforming and AI-driven frequency optimization are converging with hardware modules to create service-recurring revenue models.
- Vehicle-to-everything protocol expansion:V2X communication mandates in urban pilot zones are opening dedicated antenna specification requirements.
- Combination antenna consolidation:GPS-cellular-satellite integration into single roofline enclosures addresses OEM aesthetic and aerodynamic priorities.
Industry Challenges
- Multi-physics simulation talent scarcity:Electromagnetic-thermal-mechanical co-design for automotive thermal cycling requires specialized CAE expertise that suppliers struggle to recruit.
- EMC certification timeline compression:EPA electromagnetic emission testing and CE marking convergence for modules sold into multiple markets extends validation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Antenna Module Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Antennas, Active Antennas, Combination Antennas, Integrated Antennas Technology: Radio Frequency, GPS, Wi-Fi, Bluetooth End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Embedded, External, Roof-Mounted, Integrated |
| Companies Covered | Continental AG, TE Connectivity, Amphenol Corp., Denso Corporation, Bosch, Laird Connectivity, Aptiv, Harada Industry Co. Ltd., Ficosa International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Antenna Module Market Emerging Trajectories
Antenna module architecture is pivoting from discrete hardware assemblies toward software-configurable platforms, with material science and regulatory chemistry simultaneously rewriting design constraints.
Dielectric substrate engineering is converging with additive manufacturing to enable conformal antenna geometries that conform to curved vehicle surfaces. Tier 1 suppliers are adopting polymer 3D printing for rapid prototyping of multi-band housing topologies. This convergence is compressing traditional stamping-to-molding lead times from months to weeks.
REACH substance restrictions are forcing wholesale reformulation of flame-retardant polymer compounds used in antenna enclosures. ECHA's SVHC candidate list expansion is disqualifying legacy brominated additives. Module suppliers serving European OEMs are accelerating halogen-free compound qualification programs to maintain market access.
Fleet telematics procurement is consolidating antenna specification authority at the vehicle platform level rather than the subsystem level. Tier 1 suppliers now negotiate directly with OEM architecture teams, bypassing traditional infotainment tier 2 channels. This pattern is most visible in German premium OEMs pursuing integrated connectivity domain controllers.
Automotive Antenna Module Market Segmentation
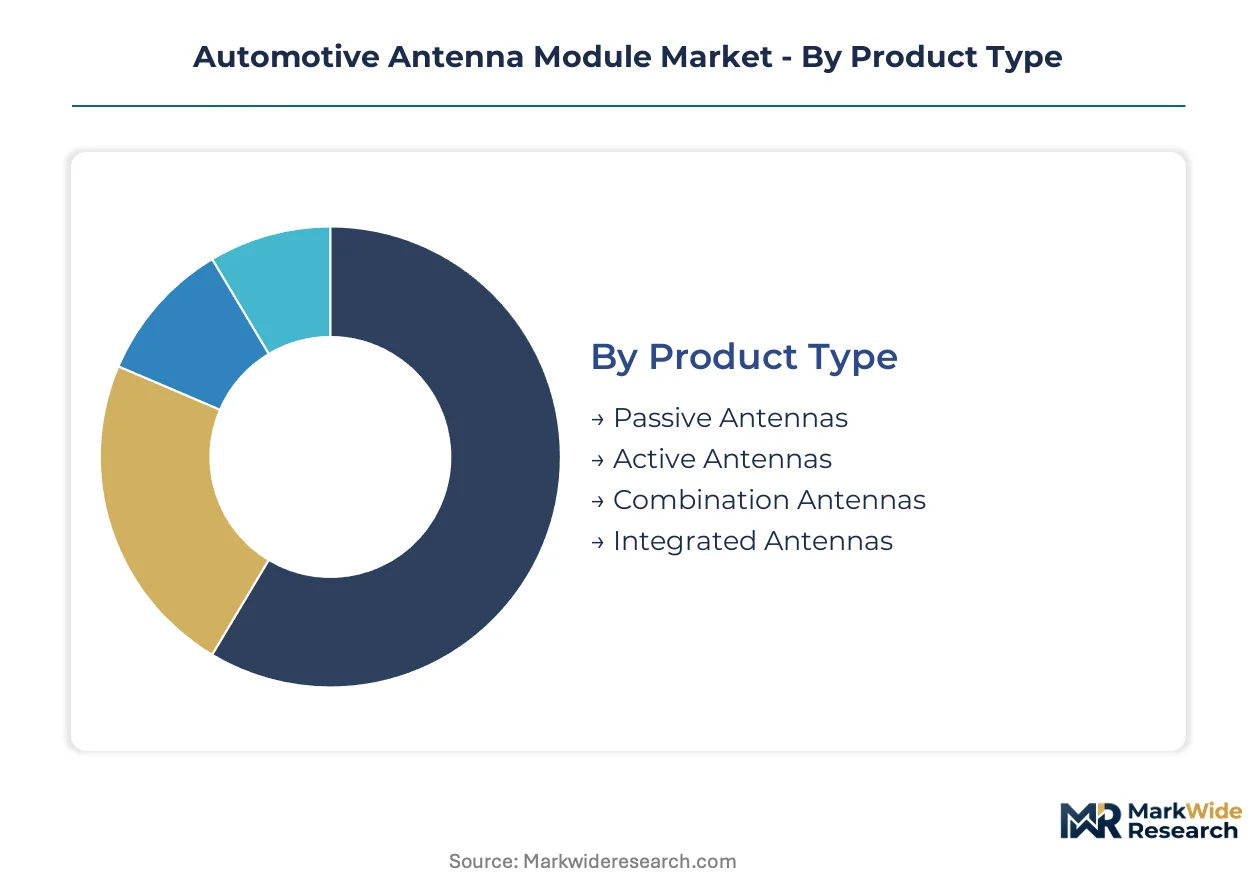
Antenna module segmentation reveals divergent capital requirements across product architectures. Technology choices determine dielectric substrate investments, while installation geometry shapes tooling amortization schedules for Tier-1 suppliers serving German OEM platforms.
Product Type:
Capital intensity peaks with active amplification circuitry and multi-band integration, where semiconductor die bonding and RF front-end calibration demand cleanroom-grade assembly lines.
- Active Antennas:Integrated low-noise amplifiers and filtering circuits require precision SMT placement and automated RF testing stations. German premium OEMs specify these for telematics domain controllers, absorbing the 15-25% bill-of-materials premium to ensure signal integrity across thermal cycling profiles.
- Combination Antennas:GPS-cellular-satellite reception consolidated into single enclosures demands complex multi-feed electromagnetic simulation and conformal ground plane engineering. Baden-Württemberg supplier clusters specialize in these roofline-consolidation designs for aerodynamic-sensitive vehicle platforms.
- Passive Antennas:Simpler conductor geometries without amplification stages suit cost-optimized vehicle classes where OEMs prioritize procurement scale over reception redundancy.
- Integrated Antennas:Embedded within body panels or glass substrates, these require co-development with automotive glazing and stamping suppliers early in platform architecture phases.
Most installed capacity flows through Passive Antennas. Expansion is steepest in Active Antennas.
Technology:
Frequency band diversity determines substrate dielectric constant tolerances and shielding investment levels, with higher gigahertz ranges demanding more expensive ceramic-filled polymer compounds.
- Bluetooth:Cabin wireless device pairing standardization across vehicle classes is pulling module refresh cycles through infotainment system upgrades. Lower-frequency 2.4 GHz operation permits cost-efficient FR-4 substrate derivatives, though antenna miniaturization for mirror-integrated placement still requires electromagnetic-thermal co-simulation expertise.
- GPS:Precision navigation mandates circularly polarized ceramic patch elements with tight axial ratio specifications. Bavarian automotive electronics clusters maintain concentrated qualification programs for these position-critical modules.
- Radio Frequency:AM/FM reception remains baseline specification despite streaming audio displacement, sustaining volume demand for whip and printed circuit antenna variants.
- Wi-Fi:Vehicle hotspot and over-the-air update throughput requirements are driving MIMO array configurations with multiple spatial streams.
Bluetooth modules are gaining share fastest. GPS maintains the highest average selling prices due to precision tolerances.
End User:
Procurement authority concentration varies sharply, with OEM architecture teams increasingly bypassing traditional tier-2 channels for fleet telematics specifications.
- OEMs:Direct platform-level antenna specification for connectivity domain controllers, particularly at German premium manufacturers consolidating supplier relationships.
- Tier-1 Suppliers:Intermediate integration responsibility for infotainment head units and telematics control modules, maintaining design influence where OEMs delegate subsystem authority.
- Vehicle Assemblers:Final installation and calibration sequencing on production lines, with limited design input but significant quality liability exposure.
- Aftermarket Providers:Replacement and upgrade modules for vehicle parc connectivity retrofits, facing shorter development cycles and reduced EMC validation rigor.
OEM direct procurement is expanding most quickly. Tier-1 Suppliers retain the deepest technical integration relationships.
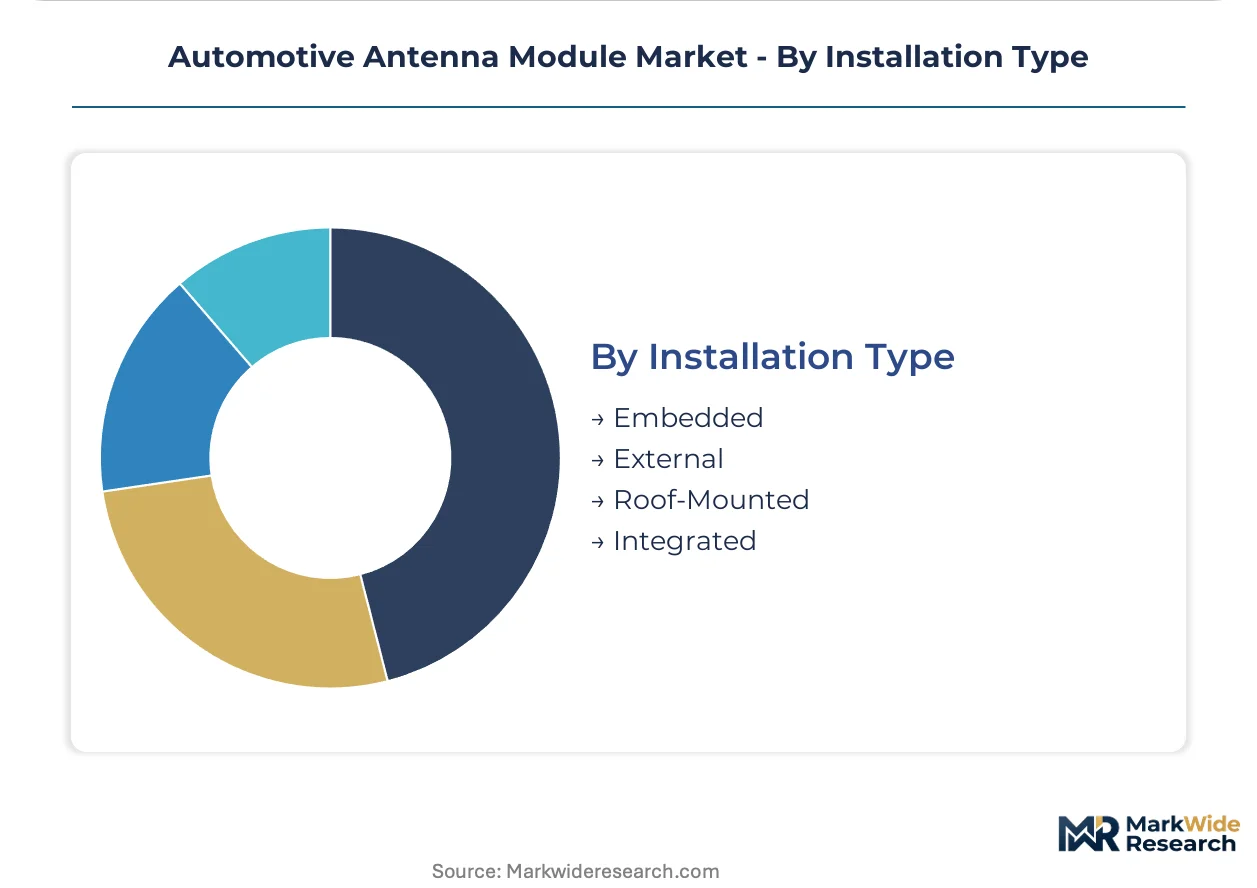
Installation Type:
Mounting geometry dictates environmental sealing investments and aerodynamic validation requirements, with exposed positions demanding automotive-grade IP6K9K ingress protection.
- Roof-Mounted:Shark-fin and blade-style enclosures dominate premium vehicle visibility, requiring UV-stable polymer compounds and integrated heating elements for ice mitigation.
- Embedded:Concealed within bumpers, mirrors, or glass surfaces, these sacrifice some radiation efficiency for styling flexibility and vandalism resistance.
- External:Removable or retractable whip configurations persist in commercial vehicle segments where maximum range outweighs aesthetic constraints.
- Integrated:Antenna functions distributed across conductive vehicle structures, demanding full-vehicle electromagnetic simulation and platform-level tuning.
Roof-Mounted designs command the highest unit economics. Embedded configurations are climbing fastest as OEMs prioritize surface cleanliness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive electronics cluster anchors the highest concentration of antenna module engineering capacity worldwide. The region's supplier density reduces procurement friction for multi-band array sourcing across premium OEM platforms. Regulatory mandates in multiple jurisdictions are simultaneously tightening emission standards and connectivity hardware requirements.
Germany
Bavarian and Baden-Württemberg clusters drive telematics hardware demand through OEM platform-level specification authority. The EU Green Deal's binding vehicle connectivity mandates compel production-line hardware upgrades. Stuttgart-based engineering centers specialize in combination antenna consolidation for aerodynamic-sensitive vehicle architectures.
United States
Fleet telematics procurement consolidation and V2X pilot zone mandates pull module demand through domestic OEM architecture teams. EPA electromagnetic emission regulations shape shielding specifications for modules sold into the market. Michigan and Ohio automotive corridors host concentrated RF testing and EMC validation infrastructure.
China
Domestic OEM connected vehicle platform expansion and MIIT vehicle connectivity standards accelerate module procurement cycles. The country's dual carbon goals tighten emission and data-transmission hardware requirements. Yangtze River Delta electronics manufacturing clusters scale polymer substrate compounding for cost-optimized antenna housings.
Japan
METI-connected vehicle initiatives and precision navigation mandates sustain GPS ceramic patch antenna demand. JIS standards for automotive electromagnetic compatibility extend validation timelines for module suppliers. Kanto region electronics clusters maintain concentrated qualification programs for position-critical navigation modules.
South Korea
Hyundai-Kia connected platform rollout and MFDS automotive electronics guidelines drive active antenna specification. Seoul Capital Area semiconductor packaging clusters support low-noise amplifier integration for premium telematics modules. Domestic OEMs specify multi-band arrays for integrated connectivity domain controllers.
Automotive Antenna Module Market Vendor Landscape
Software-defined capability acquisition dominates the current landscape as suppliers differentiate beyond hardware-only positioning. The market structures around three tiers: diversified automotive electronics conglomerates with captive RF engineering, specialized connectivity component manufacturers, and regional antenna subsystem suppliers. Strategic archetypes include full-stack domain controller integrators, polymer substrate compounders with electromagnetic simulation expertise, and software-tuning algorithm developers. M&A activity targets RF front-end calibration capabilities, while backward integration into dielectric substrate compounding protects margin pools.
Among diversified automotive electronics conglomerates, Continental AG exemplifies the full-stack integrator archetype through captive resin-compounding operations. TE Connectivity occupies a position among North American connectivity specialists with vertically integrated coaxial cable production. Bosch represents the software-tuning differentiation vector, competing on algorithm-driven antenna optimization rather than hardware specifications alone.
| Leading Market Players |
|---|
| Continental AG |
| TE Connectivity |
| Amphenol Corp. |
| Denso Corporation |
| Bosch |
| Laird Connectivity |
| Aptiv |
| Harada Industry Co. Ltd. |
| Ficosa International SA |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock indices for specialized polymer compounds cascade through antenna module manufacturing into three distinct procurement tiers. OEM platform-level specifications absorb premium positioning for active multi-band arrays, while aftermarket channels compete on stripped-down passive alternatives.
Pricing Analysis
Input-cost pass-through from resin compounding operations shapes contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified active antennas with integrated amplification from fleet-telecom bundled configurations and basic AM/FM replacement modules. Price differentiation rests on REACH-compliant substrate certification and electromagnetic simulation depth. Pricing pressure stems from bio-based polymer alternative scale limitations compressing margin pools in mid-tier segments. Aftermarket providers exhibit highest price sensitivity, while German premium OEMs absorb semiconductor content premiums for telematics domain controllers.
Supply Chain Analysis
EU local-content thresholds and MIIT domestic-sourcing mandates in China are reshaping supplier qualification programs for polymer substrate feedstocks. Manufacturing gravity centers on Germany, China, and South Korea, with Baden-Württemberg clusters anchoring precision RF engineering capacity. Raw material dependencies draw from petrochemical-derived dielectric compounds, ceramic-filled polymer formulations, and semiconductor-grade low-noise amplifier die. Single-source vulnerability concentrates in specialized resin-compounding operations serving REACH-compliant halogen-free formulations. Distribution runs through OEM architecture teams for platform-level specifications, bypassing traditional Tier-2 infotainment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-defined antenna tuning and captive substrate compounding as polymer substitution and active amplification premiums reshape value capture.
For Market Incumbents: Extend software-tuning algorithm development to differentiate beyond hardware-only positioning as Bosch has demonstrated. Backward integration into dielectric substrate compounding protects margin pools from petrochemical volatility. Defend against emerging RF front-end specialists by acquiring electromagnetic-thermal co-simulation talent scarce in the labor market. For New Entrants and Emerging Players: The 15-25% bill-of-materials gap between active and passive antenna tiers opens white-space targeting for cost-optimized combination antennas serving volume OEM platforms. Embedded antenna configurations for mirror-integrated placement remain underpenetrated relative to roof-mounted shark-fin dominance. Pursue direct OEM architecture team relationships bypassing Tier-2 channel capture, leveraging rapid polymer 3D-printing prototyping capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized connectivity component manufacturers possessing electromagnetic simulation expertise and halogen-free compound qualification programs. Long-term viability favors suppliers positioned at the convergence of material science and software-configurable platforms. Watch for V2X mandate acceleration in urban pilot zones as inflection signal for dedicated antenna specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Antenna Tuning Investment | AI-driven frequency optimization creates recurring service revenue beyond hardware margins. |
| Halogen-Free Polymer Compound Qualification | ECHA SVHC list expansion makes REACH-compliant substrates mandatory for European OEM access. |
| Multi-Band Combination Antenna Consolidation | GPS-cellular-satellite integration addresses aerodynamic priorities at Stuttgart-based premium manufacturers. |
| Captive Resin-Compounding Operations | Continental's vertical integration model protects margin pools from petrochemical feedstock volatility. |
| V2X Protocol-Ready Module Development | Urban pilot zone mandates in the United States and Europe open dedicated specification requirements. |
Methodological Framework
Multiple input streams — primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and SEC filings from diversified automotive electronics conglomerates; plus customs records for polymer substrate trade flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment patterns were cross-referenced against panel input from RF engineering specialists and telematics system architects. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster throughout the forecast period. CAGRs were derived from installed base penetration curves and technology refresh cycle timing, incorporating EU Green Deal mandate compliance schedules and Bluetooth standardization trajectories as industry-specific demand drivers.
Caveats apply where REACH substance restriction timeline acceleration, petrochemical supply disruptions, or EMC certification convergence delays could materially shift the outlook. Forecasts reflect documented assumptions regarding OEM platform-level specification authority migration and polymer additive manufacturing scale economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
India ECU Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market