
 Automotive HV Junction Box Busbar Insulator Market | 2026-2036
Automotive HV Junction Box Busbar Insulator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive HV Junction Box Busbar Insulator Market Insights
Buyer concentration among electric vehicle OEMs is decoupling from traditional tiered supply hierarchies as platform-specific insulator qualification demands direct engineering engagement. Robert Bosch leverages its systems integration depth to anchor high-voltage junction box programs across multiple OEM architectures. Yazaki Corporation sustains geographic dominance in Asian supply corridors through captive polymer compounding capabilities. TE Connectivity differentiates by controlling test-validation protocols that shorten OEM approval cycles for new insulator grades.
Automotive HV junction box busbar insulators are high-voltage dielectric components engineered from engineered thermoplastics such as polyphenylene sulfide and polyamide, manufactured through injection molding to achieve creepage distances exceeding 25mm and comparative tracking indices above 600V for 800V-class electric powertrains. Their primary purpose is to prevent arcing and leakage current between conductive busbars within compact junction box assemblies exposed to thermal cycling and vibration loads. Polyphenylene sulfide occupies the premium tier due to its resistance to hydrolysis and solder-reflow temperatures, while polyamide competes on cost-performance balance across volume electric vehicle platforms. Surface mount installations dominate current production, though embedded configurations are gaining traction as OEMs pursue junction box miniaturization for under-hood packaging constraints.
FDA material compliance for incidental food-contact scenarios in commercial vehicle cabins intersects with EPA REACH-aligned substance restrictions that govern halogen-free flame retardant formulations in US-bound insulator production. ECHA's SVHC candidate list and China's GB/T 2408 flammability standards collectively constrain polymer additive selection, forcing compounders to reformulate base resins ahead of regulatory deadlines. The EU AI Act's emerging requirements for autonomous vehicle electrical system traceability will extend documentation burdens to insulator batch records. Stakeholders must monitor how battery-electric platform consolidation among OEMs reshapes qualification volumes and whether polyphenylene sulfide supply commitments from resin producers keep pace with anticipated specification escalations.
Market Dynamics
The migration to 800V electric powertrain architectures is compressing junction box form factors while elevating dielectric performance requirements for busbar insulation systems.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating halogen-free flame retardant adoption in polyamide and polyphenylene sulfide compounds destined for European-bound electric vehicles.
- 800V platform proliferation:Premium and mass-market battery-electric vehicle programs are specifying comparative tracking indices above 600V, expanding addressable volume for high-grade thermoplastic insulators.
- Germany's manufacturing corridor:Concentrated OEM platform engineering in Stuttgart, Munich, and Wolfsburg is pulling Tier-1 suppliers into co-development relationships that bypass traditional specification hierarchies.
Market Restraints
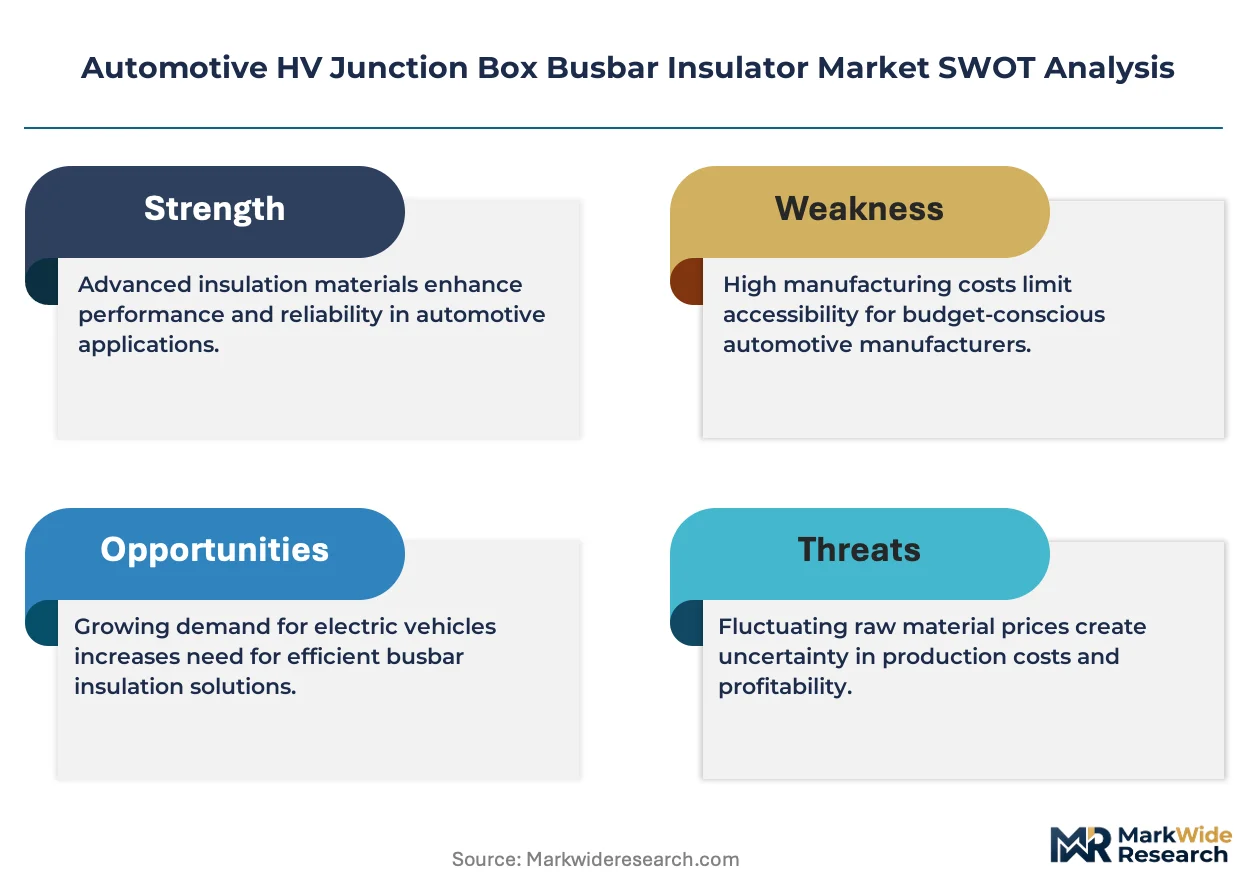
- Polyphenylene sulfide supply concentration:Resin production capacity remains captive to a limited number of chemical conglomerates, creating allocation risk during specification escalations.
- ECHA SVHC candidate list expansion:Anticipated additions of polymer additives are forcing compounders into reformulation cycles that compress margin structures and extend qualification timelines.
- Polyetherimide substitution threat:Alternative high-performance thermoplastics with comparable dielectric strength and thermal resistance are gaining evaluation traction among cost-sensitive platform programs.
Strategic Opportunities
- Embedded insulator configurations:Junction box miniaturization initiatives are creating specification openings for insert-molded busbar assemblies that integrate dielectric and structural functions.
- China's dual carbon goals:Domestic battery-electric vehicle production mandates are expanding procurement volume for locally qualified insulator grades under GB/T electrical safety standards.
- Autonomous vehicle electrical traceability:The EU AI Act's emerging documentation requirements will extend batch-record systems to insulator manufacturing, favoring compounders with existing serialization infrastructure.
Industry Challenges
- High-voltage safety certification timelines:OEM-specific test-validation protocols for creepage and clearance performance are extending new-grade approval cycles beyond 18 months.
- Polymer compounding talent scarcity:Formulation chemists with expertise in halogen-free flame retardant systems and hydrolysis-resistant thermoplastics command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive HV Junction Box Busbar Insulator Market |
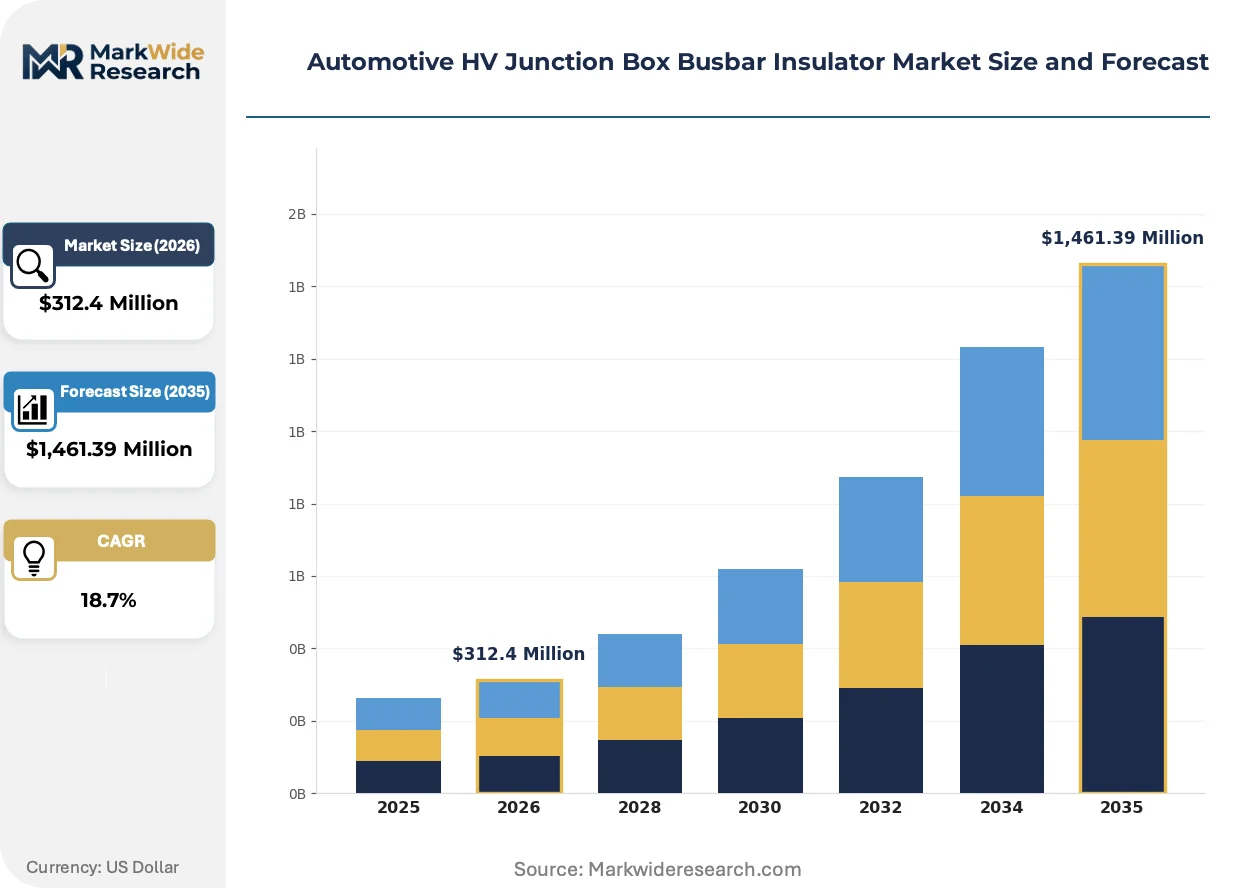
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Polyphenylene Sulfide, Polycarbonate, Polyester Application: Electric Vehicles, Hybrid Vehicles, Commercial Vehicles, Electric Bicycles End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Vendors, Retrofitters Installation Type: Surface Mount, Embedded, Modular, Integrated |
| Companies Covered | Robert Bosch, Yazaki Corporation, Sumitomo Electric Industries, TE Connectivity, Continental, Valeo, Lear Corporation, Aptiv, Furukawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive HV Junction Box Busbar Insulator Market Trends and Innovations
Active material science programs and regulatory compliance automation are converging to reshape how busbar insulators are specified, validated, and integrated into next-generation junction box architectures.
Laser direct structuring of molded thermoplastic substrates is automating the creation of three-dimensional circuit pathways that embed busbar insulation and current-carrying traces within single-component assemblies. Electric vehicle OEMs in Germany and South Korea are piloting this capability for under-hood junction boxes where packaging volume constraints are most severe. The technology is automating the elimination of separate wire harness connections and secondary fastening hardware from high-voltage distribution modules.
The EU AI Act's requirements for autonomous vehicle electrical system traceability are mandating serialized batch documentation that extends from resin pellet to finished insulator component. Compounders serving European automotive programs are deploying blockchain-enabled supply chain tracking to satisfy impending audit protocols. Insulator grades destined for Level 3+ autonomous platforms face the most intensive documentation burdens, with qualification contingent on demonstrable material provenance.
Direct engineering engagement between OEM platform teams and specialty compounders is displacing traditional tiered supply hierarchies for critical high-voltage components. Tier-1 harness suppliers are ceding specification control for 800V-class insulators to OEMs seeking proprietary dielectric formulations that differentiate platform architectures. This pattern is most pronounced in Germany's automotive manufacturing corridor, where Volkswagen, BMW, and Mercedes-Benz operate captive polymer qualification laboratories.
Automotive HV Junction Box Busbar Insulator Market Segmentation
Segmentation in automotive HV junction box busbar insulators reveals how material chemistry, vehicle electrification intensity, and supply chain position allocate margin capture across the value chain. Each dimension exposes distinct capital requirements and qualification barriers that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across resin platforms, with high-temperature thermoplastics demanding specialized compounding infrastructure and extended OEM validation cycles.
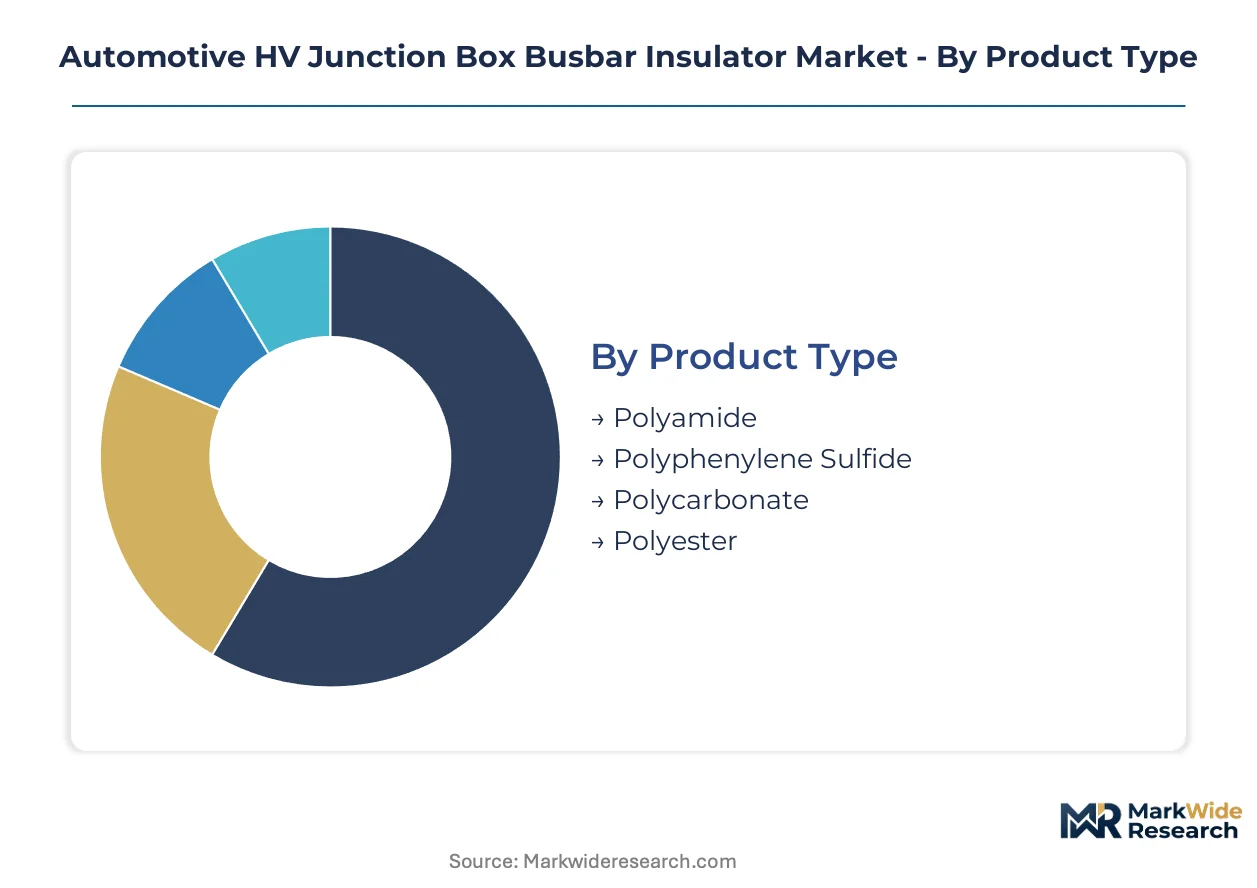
- Polyamide:This cost-optimized thermoplastic balances dielectric performance with processability, serving volume battery-electric platforms where GB/T 2408 flammability compliance suffices. Procurement concentrates among Chinese domestic OEMs prioritizing localized supply chains under dual carbon mandates.
- Polyphenylene Sulfide:Hydrolysis-resistant and solder-reflow compatible, this resin commands premium positioning for 800V architectures requiring comparative tracking indices above 600V. German OEM platform engineering in Stuttgart and Munich drives specification escalation here.
- Polycarbonate:Transparent variants enable visual inspection of busbar integrity during assembly, finding niche adoption in premium vehicle junction boxes.
- Polyester:Lower thermal ceiling limits deployment to auxiliary power distribution modules in hybrid vehicle architectures.
Most installed capacity flows through Polyamide. Expansion is steepest in Polyphenylene Sulfide.
Application:
Electrification voltage class and thermal load severity determine insulator grade selection across vehicle categories.
- Electric Vehicles:800V battery-electric platforms generate the most demanding specification set, with creepage distances exceeding 25mm and continuous operating temperatures above 150°C. South Korean OEMs in Seoul and Gwangju are piloting laser-direct-structured embedded configurations.
- Hybrid Vehicles:Dual-voltage architectures require insulators tolerant of frequent thermal cycling between electric and combustion modes. Japanese OEM qualification protocols here emphasize long-term aging under combined temperature-humidity stress.
- Commercial Vehicles:Extended duty cycles and cabin food-contact scenarios trigger FDA material compliance requirements alongside EPA REACH-aligned substance restrictions.
- Electric Bicycles:Cost-constrained 48V-72V systems accept lower-grade thermoplastics with reduced flame retardant loading.
Volume concentration sits with Electric Vehicles. Commercial Vehicles are climbing the fastest as electrification extends to heavy-duty segments.
End User:
Supply chain position dictates specification control, with direct OEM engagement displacing traditional tiered hierarchies for critical high-voltage components.
- OEM Manufacturers:Volkswagen, BMW, and Mercedes-Benz operate captive polymer qualification laboratories, bypassing Tier-1 suppliers to specify proprietary dielectric formulations.
- Tier-1 Vendors:Robert Bosch and Yazaki Corporation retain influence through systems integration depth and captive compounding capabilities respectively.
- Aftermarket Suppliers:Replacement demand concentrates in collision repair channels, with shorter qualification timelines but lower margin structures.
- Retrofitters:Niche players serving commercial vehicle electrification conversions face inconsistent specification standards across regional safety regulators.
Specification authority is concentrating in OEM Manufacturers. Aftermarket Suppliers are expanding most quickly as installed base scales.
Installation Type:
Packaging density requirements and assembly automation compatibility drive configuration selection.
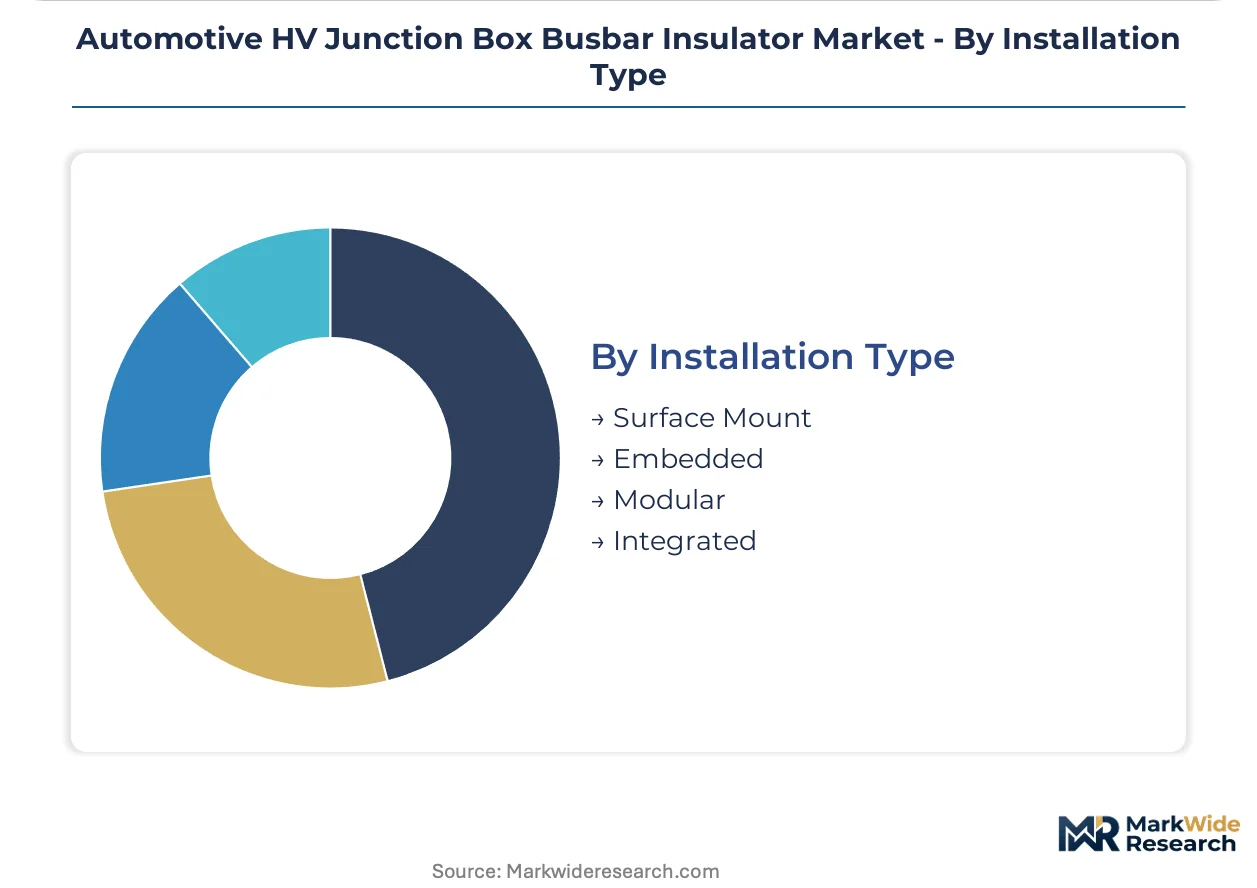
- Surface Mount:Dominates current production with established pick-and-place compatibility and rework accessibility for high-voltage harness integration.
- Embedded:Insert-molded busbar assemblies integrate dielectric and structural functions, enabling junction box miniaturization for under-hood packaging constraints in German and South Korean pilot programs.
- Modular:Field-replaceable configurations serve commercial vehicle fleets prioritizing serviceability over packaging optimization.
- Integrated:Battery pack-level distribution modules combine busbar insulation with cell monitoring circuitry, requiring compounders with existing serialization infrastructure for EU AI Act traceability compliance.
Production volume runs through Surface Mount. Embedded configurations are gaining share fastest as platform miniaturization intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's procurement volume for 800V-class insulators now exceeds Germany's, though German OEMs retain tighter specification control over dielectric formulations. Japan maintains captive resin compounding infrastructure that insulates its supply chain from allocation shocks. South Korea's laser-direct-structuring pilots are compressing junction box form factors faster than European timelines.
China
Domestic battery-electric vehicle production under dual carbon mandates is expanding procurement for locally qualified insulator grades. GB/T electrical safety standards and GB/T 2408 flammability requirements constrain polymer additive selection for compounders serving BYD and NIO platforms. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate Tier-1 supplier qualification activity for export-bound and domestic programs.
Germany
Volkswagen, BMW, and Mercedes-Benz operate captive polymer qualification laboratories that bypass traditional supply hierarchies for critical high-voltage components. EU F-Gas Regulation phasedown of fluorinated greenhouse gases accelerates halogen-free flame retardant adoption in polyamide and polyphenylene sulfide compounds. Stuttgart, Munich, and Wolfsburg engineering centers pull specialty compounders into direct co-development relationships.
United States
EPA REACH-aligned substance restrictions govern halogen-free flame retardant formulations in US-bound insulator production alongside FDA material compliance for commercial vehicle cabin applications. Michigan and Ohio automotive corridors host Tier-1 systems integrators qualifying insulators for Detroit Three electrification platforms. NHTSA high-voltage safety protocols extend OEM-specific validation timelines beyond 18 months for new insulator grades.
Japan
Japanese OEM qualification protocols emphasize long-term aging under combined temperature-humidity stress for hybrid vehicle dual-voltage architectures. METI industrial standards coordinate with JIS specifications for polymer dielectric performance in under-hood applications. Toyota City and Nagoya industrial clusters concentrate Sumitomo Electric and Furukawa Electric captive compounding capabilities.
South Korea
Seoul and Gwangju OEM engineering centers are piloting laser-direct-structured embedded insulator configurations for junction box miniaturization. MFDS automotive material regulations align with international IEC standards for high-voltage creepage and clearance performance. Busan-Ulsan manufacturing corridors integrate specialty compounders with Hyundai-Kia platform engineering for 800V battery-electric programs.
Automotive HV Junction Box Busbar Insulator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure anchored by systems integration depth. The market fragments across three strategic archetypes: captive resin compounders with backward polymer control, Tier-1 harness suppliers defending specification influence, and specialty material houses serving direct OEM engagement. Dominant competitive moves include M&A to secure halogen-free flame retardant formulation expertise and capacity expansion in polyphenylene sulfide compounding infrastructure.
Among diversified automotive suppliers, Robert Bosch, Yazaki Corporation, and TE Connectivity occupy positions that exemplify distinct competitive vectors. Bosch represents systems integration depth anchoring high-voltage junction box programs across multiple OEM architectures. Yazaki exemplifies geographic dominance through captive supply chain control in Asian corridors. TE Connectivity sits within the test-validation tier, with protocol ownership that compresses OEM approval cycles for new insulator grades.
| Leading Market Players |
|---|
| Robert Bosch |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| TE Connectivity |
| Continental |
| Valeo |
| Lear Corporation |
| Aptiv |
| Furukawa Electric |
| Others |
Pricing and Supply Chain Analysis
Polyphenylene sulfide resin price indices cascade through automotive HV junction box busbar insulator supply chains into three distinct pricing tiers anchored by thermal performance certification and OEM qualification status. German OEM captive laboratories and Chinese dual carbon procurement mandates create divergent price floors that compounders must navigate across regional supply corridors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for polyamide-based insulator grades serving domestic battery-electric platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by comparative tracking index certification and halogen-free flame retardant compliance under EU F-Gas Regulation. Cost compression in standard-grade polyamide is intensifying because GB/T 2408 flammability compliance alone suffices for volume Chinese OEM procurement. Aftermarket collision repair channels exhibit highest price sensitivity, while 800V-class polyphenylene sulfide specifications for German premium platforms demonstrate lowest elasticity.
Supply Chain Analysis
Refurbishment flows for end-of-life junction box assemblies remain underdeveloped, constraining circular material recovery for high-performance thermoplastics. Raw material concentration centers on Japan, China, and Germany for polyphenylene sulfide resin, polyamide compounding, and specialty additive masterbatches respectively. Compounders draw from halogen-free flame retardant systems, hydrolysis stabilizers, and laser-direct-structuring compatible substrates as critical inputs. Single-source vulnerability in polyphenylene sulfide resin production creates allocation risk during specification escalations. Distribution runs through Tier-1 harness suppliers for legacy programs and direct OEM engagement for 800V platform qualifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive HV junction box busbar insulator demand functions as a stable compounder, with 800V architecture proliferation providing durable volume expansion regardless of near-term battery-electric vehicle adoption volatility.
For Market Incumbents: Deepen backward integration into halogen-free flame retardant formulation expertise to defend margin structures against ECHA SVHC candidate list expansions. Secure captive polyphenylene sulfide resin commitments from Japanese and Chinese chemical conglomerates before specification escalations trigger allocation constraints. Prioritize serialization infrastructure deployment to capture EU AI Act traceability requirements for Level 3+ autonomous vehicle programs.
For New Entrants and Emerging Players: Capture embedded insulator configuration opportunities in South Korean and German pilot programs for junction box miniaturization, where laser-direct-structuring technology dissolves incumbent process advantages. Target commercial vehicle electrification segments in North America, where FDA material compliance and EPA REACH-aligned substance restrictions create qualification barriers that favor specialized compounders over diversified automotive suppliers. Lead with direct OEM engineering engagement rather than Tier-1 channel penetration.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty compounders possessing existing halogen-free flame retardant expertise and demonstrated OEM qualification track records. Five-to-ten-year viability hinges on polyphenylene sulfide supply security and autonomous vehicle electrical traceability infrastructure. Monitor ECHA SVHC candidate list publication schedules and OEM platform consolidation announcements as inflection indicators for qualification volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Flame Retardant Formulation Investment | ECHA SVHC compliance under EU F-Gas Regulation phases out legacy additive systems in European-bound production. |
| Polyphenylene Sulfide Compounding Capacity Expansion | Resin allocation security from Japanese and Chinese chemical conglomerates determines 800V platform qualification access. |
| Direct OEM Engineering Engagement | Volkswagen, BMW, and Mercedes-Benz captive laboratories bypass Tier-1 suppliers for proprietary dielectric specifications. |
| Serialization Infrastructure Deployment | EU AI Act batch-record requirements for autonomous vehicle electrical traceability favor compounders with blockchain-enabled tracking. |
| Laser-Direct-Structuring Process Qualification | Hyundai-Kia and German OEM pilot programs compress junction box form factors through embedded insulator configurations. |
Research Methodology
Bottom-up electric vehicle platform modeling reconciled against top-down resin compounding capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, specialty compounder technical directors, and automotive regulatory affairs specialists combined with secondary validation from GB/T standards documentation, ECHA SVHC candidate list publications, SEC filings of diversified automotive suppliers, and vehicle production databases. Triangulation across stakeholder perspectives and data sources ensures segmentation integrity across material chemistry, voltage class, and supply chain position dimensions.
Historical trendline analysis of polyphenylene sulfide and polyamide pricing against OEM qualification volumes established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, application voltage class, end user supply chain position, and installation configuration as core dimensions. CAGRs derived from regression analysis of platform-level content per vehicle assumptions, regional electrification intensity differentials, and regulatory compliance timeline impacts. Forecast inputs included 800V architecture adoption curves, ECHA SVHC list expansion schedules, and EU AI Act implementation protocols.
Polyphenylene sulfide supply allocation shocks, ECHA SVHC candidate list additions ahead of schedule, and OEM platform consolidation cancellations are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding resin producer capacity expansion intentions and regulatory implementation timelines. Practitioners should monitor ECHA publication schedules, Japanese chemical conglomerate capex disclosures, and German OEM platform engineering headcount trends for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market