
 Mobility Technologies Market | 2026-2036
Mobility Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Mobility Technologies Market Analysis
Fleet operators is redrawing procurement priorities away from individual consumers in the Mobility Technologies Market. Tesla leverages vertical integration across battery cell and software stack production to sustain pricing power in premium electric vehicle segments. Waymo anchors its position through captive lidar and mapping infrastructure that controls operational data loops for autonomous ride-hail deployment.
Mobility technologies encompass electrified propulsion systems, autonomous perception stacks, vehicle-to-everything communication modules, and cloud-native fleet management platforms operating at latency thresholds below 20 milliseconds for safety-critical decisions. Electric vehicles command the largest revenue pool among product types while autonomous vehicles extract the highest engineering margins due to sensor fusion complexity and regulatory certification barriers. AI Integration within the technology dimension is attracting disproportionate capital allocation as OEMs seek to reduce dependence on third-party chip architectures.
The EPA tailpipe standards and NHTSA automated driving system guidance in the United States, alongside the EU AI Act and MDR framework in Europe, are bifurcating compliance pathways for manufacturers seeking cross-border deployment. China's MIIT and NMPA administer parallel certification regimes for connected vehicle data localization and intelligent driving system safety validation. Stakeholders must monitor divergence between these regulatory blocs to determine whether to architect unified platforms or region-specific hardware variants.
Market Dynamics
Fleet procurement concentration and battery supply chain regionalization are compressing pricing power across the Mobility Technologies Market while forcing OEMs to reconfigure engineering footprints.
Growth Catalysts
- EU Green Deal emissions mandates:Binding carbon thresholds for automotive cooling systems and battery production are accelerating electrified platform deployment across German and French manufacturing clusters.
- Logistics routing optimization:Connected vehicle platforms with sub-20 millisecond latency are capturing expanded fleet operator procurement budgets for real-time freight coordination.
- Software-defined vehicle architectures:Cloud-native stack development is displacing hardware-centric design cycles, enabling over-the-air feature monetization throughout vehicle lifespans.
Market Restraints
- Lithium supply concentration:Processing and refining capacity clustering in specific geographies creates input cost volatility and geopolitical exposure for battery cell procurement.
- F-Gas Regulation compliance costs:The EU's tightening thresholds for fluorinated greenhouse gases in thermal management systems impose redesign expenses on established cooling architectures.
- Sensor fusion certification barriers:Autonomous perception stack validation requires extended regulatory timelines that compress engineering margins and delay revenue recognition.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing offer tariff-advantaged entry points for battery supply chain localization.
- Vehicle-to-everything infrastructure:Convergence of 5G networks and edge computing enables new revenue streams from traffic optimization services and insurance data products.
- EU AI Act compliance services:Mandatory conformity assessment for intelligent driving systems creates white space for third-party validation and documentation providers.
Industry Challenges
- Embedded systems software talent scarcity:Competition for functional safety engineers with ISO 26262 expertise is inflating compensation costs and extending hiring cycles.
- Cross-border data localization requirements:Divergent MIIT and GDPR frameworks for connected vehicle telematics force redundant infrastructure investments for unified platform architectures.
- Legacy fleet integration complexity:Retrofitting existing commercial vehicle pools with V2X modules requires customized hardware interfaces that fragment supplier economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobility Technologies Market |
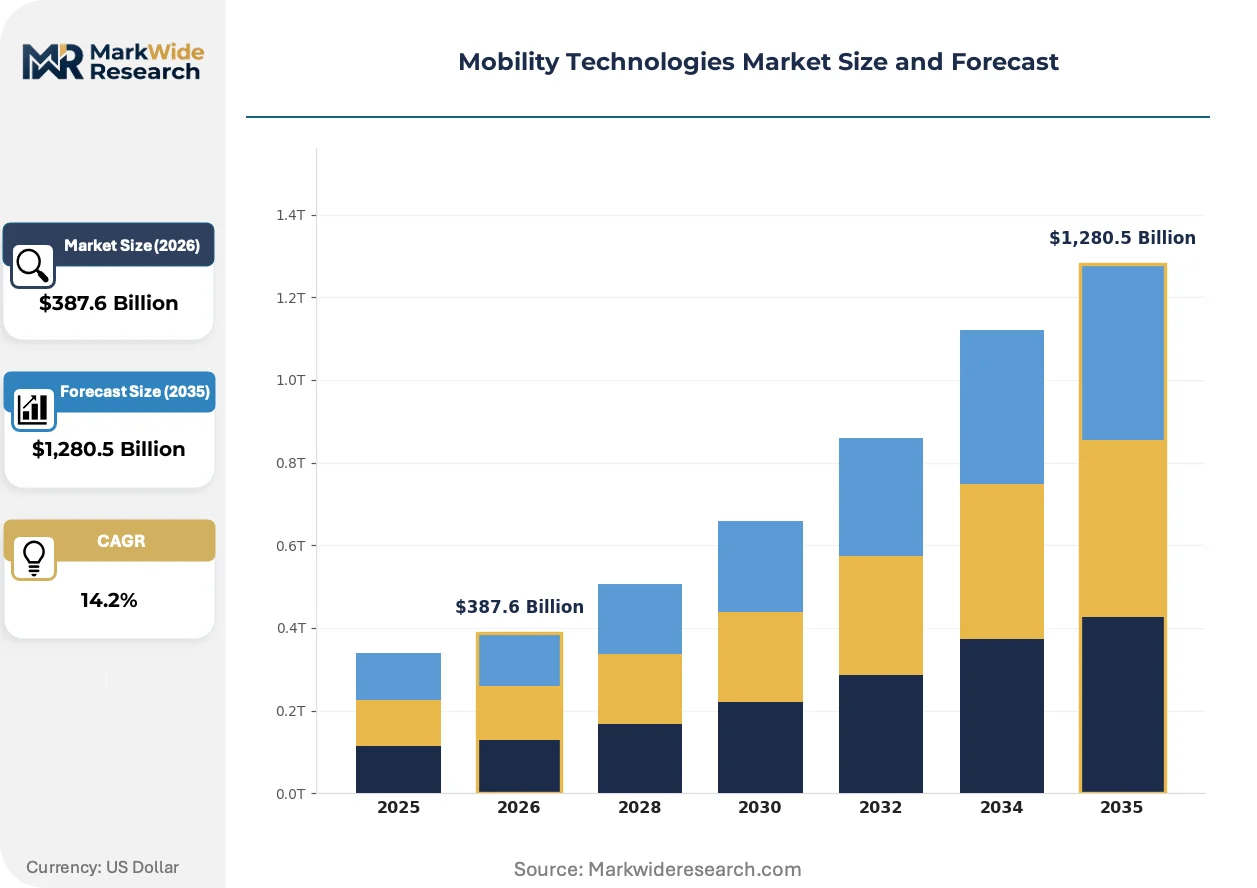
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Vehicles, Autonomous Vehicles, Connected Vehicles, Hybrid Vehicles Technology: V2X Communication, AI Integration, Sensor Technology, Cloud Computing Application: Logistics, Public Transportation, Personal Mobility, Ride Sharing End User: Consumers, Fleet Operators, Municipalities, Commercial Enterprises |
| Companies Covered | Tesla, Inc., Waymo LLC, BMW AG, Honda Motor Co., Ltd., Siemens AG, Qualcomm Inc., Intel Corporation, Apple Inc., Samsung Electronics Corporation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobility Technologies Market Emerging Trajectories
Solid-state battery chemistry and autonomous perception hardware are compressing form factors while regulatory pressure on supply chains is forcing geographic reconfiguration of engineering centers.
Solid-state electrolyte technology replaces liquid organic solvents with ceramic or sulfide compounds to eliminate thermal runaway risks. Korean and Japanese cell manufacturers are accelerating pilot line investments for automotive qualification. This architecture is miniaturizing pack volume requirements while enabling higher energy density configurations that extend electric vehicle range without platform redesign.
The EU AI Act's risk classification framework for autonomous systems imposes documentation and human oversight obligations on intelligent driving software. Tier-one suppliers must restructure development workflows to maintain audit trails for training data and decision logic. German OEMs are most affected, with engineering centers diverting resources from feature development to conformity assessment preparation.
Subscription-based access to advanced driver assistance features is displacing upfront hardware bundling in premium vehicle segments. Fleet operators and ride-hail platforms are the primary adopters, preferring operational expenditure models that align technology costs with utilization rates. This shift is most visible in California and Germany, where software-enabled revenue now exceeds powertrain margin contribution for certain electric vehicle lines.
Mobility Technologies Market Segmentation
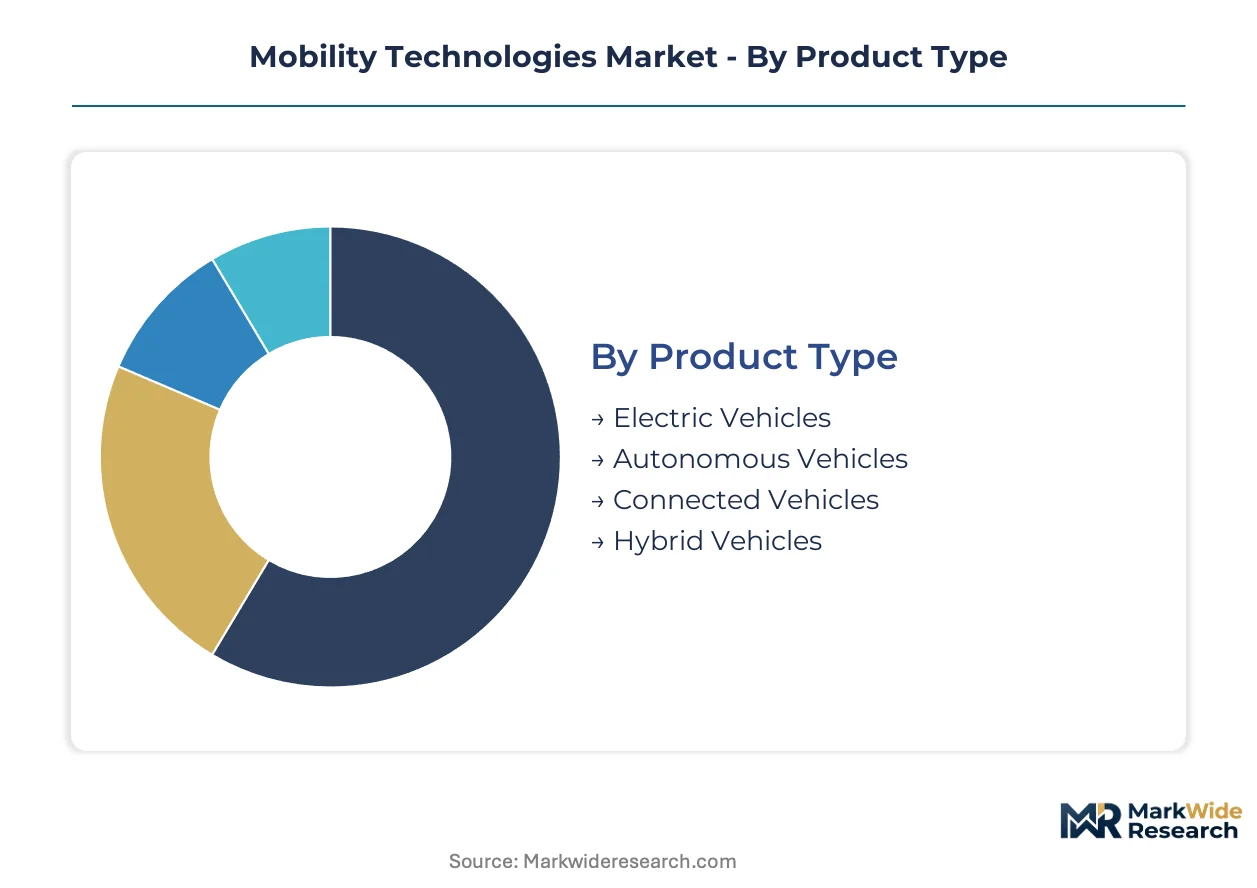
Segmentation in the Mobility Technologies Market exposes how capital allocation diverges across electrification, automation, and connectivity vectors. Fleet procurement patterns and regulatory compliance requirements create distinct performance profiles within each dimension.
Product Type:
Substitution pressure from solid-state architectures and hydrogen fuel cells threatens incumbent battery-electric platforms most acutely in commercial long-haul segments.
- Electric Vehicles:Battery-electric powertrains with lithium-ion or emerging solid-state cell chemistry dominate OEM platform investments. German and Chinese manufacturing clusters absorb the majority of cell capacity expansion as fleet operators consolidate procurement around standardized pack architectures.
- Autonomous Vehicles:Sensor fusion stacks combining lidar, radar, and camera arrays enable SAE Level 4 operation in geo-fenced urban corridors. Waymo and Baidu deployment zones in California and Beijing concentrate validation data accumulation for regulatory submission packages.
- Connected Vehicles:Cellular V2X modules operating on 5G networks enable real-time traffic coordination and predictive maintenance alerts.
- Hybrid Vehicles:Plug-in hybrid architectures bridge range anxiety gaps in markets with sparse charging infrastructure.
Electric Vehicles retains volume leadership; Autonomous Vehicles holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive hardware stacks from software layers with marginal replication economics.
- V2X Communication:Dedicated short-range communication and cellular vehicle-to-everything modules enable sub-20 millisecond latency for safety-critical messaging. EU C-ITS corridor deployments and Chinese smart highway investments concentrate infrastructure procurement budgets.
- AI Integration:Neural network inference engines for perception and path planning run on automotive-grade silicon with ISO 26262 functional safety certification. NVIDIA and Qualcomm chip architectures dominate training and inference workloads respectively.
- Sensor Technology:Solid-state lidar, 4D imaging radar, and high-resolution camera modules constitute the physical perception layer.
- Cloud Computing:Edge-to-cloud data pipelines process fleet telemetry for over-the-air updates and usage-based insurance products.
AI Integration commands premium engineering margins; V2X Communication scales fastest through infrastructure mandates.
Application:
Customer type fragmentation creates divergent procurement cycles between asset-heavy fleet operators and individual purchasers.
- Logistics:Autonomous trucking and last-mile delivery fleets prioritize total cost of ownership metrics over upfront capital expenditure. DHL and Amazon deployment schedules in Germany and the United States drive heavy-duty platform validation timelines.
- Public Transportation:Municipal bus electrification and autonomous shuttle pilots operate under constrained procurement budgets with extended payback requirements.
- Personal Mobility:Private vehicle ownership models face displacement from subscription and shared-access alternatives.
- Ride Sharing:Uber and Lyft driver supply constraints accelerate autonomous deployment economics in dense urban zones.
Logistics absorbs the largest absolute investment; Ride Sharing gains share fastest as utilization models displace ownership.
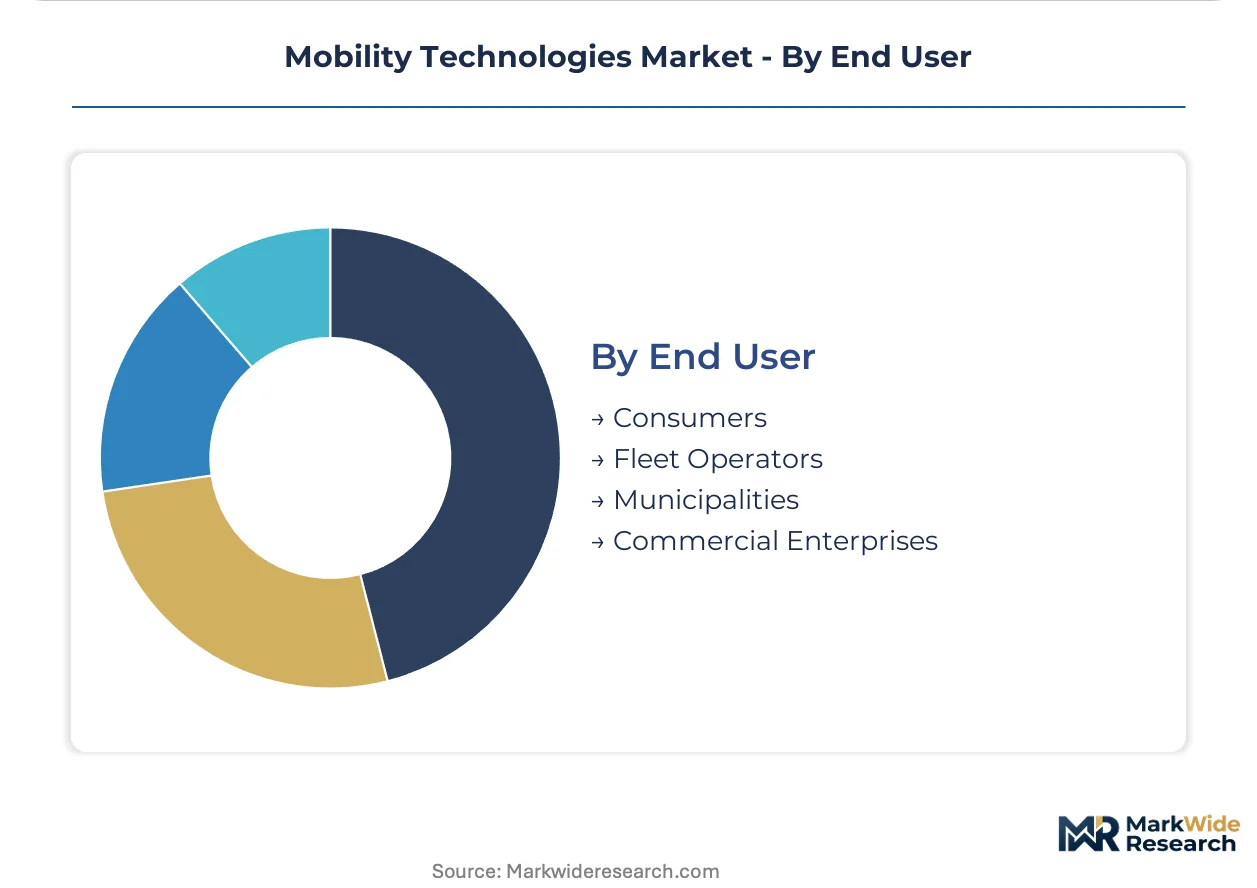
End User:
Supply concentration among battery cell and semiconductor vendors shapes bargaining power distribution across purchaser categories.
- Fleet Operators:Consolidated procurement entities negotiate volume-based pricing and custom software integrations for logistics and ride-hail platforms. Schneider National and J.B. Hunt in the United States specify telematics requirements that reshape supplier development roadmaps.
- Commercial Enterprises:Corporate vehicle pools and delivery subsidiaries balance electrification mandates against residual value risk.
- Consumers:Individual purchasers exhibit price elasticity that delays premium technology adoption curves.
- Municipalities:Transit authority procurement operates under public budget cycles with political visibility constraints.
Fleet Operators capture supplier attention through volume concentration; Commercial Enterprises expand fastest as ESG compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery cell fabrication clusters in China, South Korea, and Germany concentrate cathode active material supply and drive regional procurement patterns for electrified platforms. OEM engineering centers co-locate near these nodes to compress development cycles and manage logistics routing complexity.
United States
Fleet operators including Schneider National and J.B. Hunt consolidate procurement of connected vehicle platforms with sub-20 millisecond latency for freight coordination. The EPA tailpipe standards and NHTSA automated driving system guidance shape compliance pathways for cross-border deployment. Engineering activity concentrates in California's Silicon Valley and Michigan's Detroit-Warren corridor, where autonomous perception stack development intersects with legacy automotive manufacturing.
Germany
OEMs and tier-one suppliers co-locate battery and software engineering centers to respond to EU Green Deal emissions mandates and F-Gas Regulation thresholds for automotive cooling systems. The EU AI Act and MDR framework impose documentation obligations on intelligent driving software that divert resources from feature development. Manufacturing gravity sits in Bavaria and Baden-Württemberg, where solid-state battery pilot lines and functional safety certification workflows operate in parallel.
China
Domestic OEMs absorb the majority of cell capacity expansion as fleet procurement concentrates around standardized pack architectures. MIIT and NMPA administer parallel certification regimes for connected vehicle data localization and intelligent driving system safety validation. The Yangtze River Delta and Pearl River Delta clusters host the principal battery chemistry innovation centers and autonomous deployment zones in Beijing.
South Korea
Cell manufacturers accelerate pilot line investments for automotive qualification of solid-state electrolyte technology with ceramic and sulfide compounds. METI-aligned industrial policy supports cathode active material refining capacity expansion. Production concentrates in the Seoul Capital Area and Busan-Ulsan corridor, where energy density configuration R&D feeds German and US OEM supply agreements.
India
Production-linked incentives for advanced chemistry cell manufacturing under the PLI scheme offer tariff-advantaged entry points for battery supply chain localization. BIS standards and DGFT trade frameworks govern import substitution timelines for electrified platforms. Engineering activity clusters in Maharashtra and Tamil Nadu, where logistics fleet operators pilot connected vehicle platforms for last-mile delivery optimization.
Mobility Technologies Market Vendor Landscape
Concentration sits with vertically integrated OEMs and captive semiconductor suppliers that control battery cell and software stack production. The vendor base stratifies across three tiers: full-stack platform owners, tier-one component specialists, and infrastructure-dependent service operators. Strategic moves center on backward integration into cathode material refining and geographic expansion of engineering centers to satisfy data localization requirements.
Among US-based platform owners, Tesla, Inc. exemplifies the full-stack archetype through in-house production of battery cells and software-defined vehicle architectures. Waymo LLC occupies a position within the autonomous service tier, anchored by captive lidar and mapping infrastructure. German OEM representatives including BMW AG sit within the premium electrification segment, managing dual compliance with EU AI Act documentation obligations and EPA cross-border certification timelines.
| Leading Market Players |
|---|
| Tesla, Inc. |
| Waymo LLC |
| BMW AG |
| Honda Motor Co., Ltd. |
| Siemens AG |
| Qualcomm Inc. |
| Intel Corporation |
| Apple Inc. |
| Samsung Electronics Corporation Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for lithium hydroxide and cathode active material lock in supply access for German and Chinese cell manufacturers while anchoring price visibility against spot market volatility in raw material exchanges. These structures bundle volume commitments with indexed pricing mechanisms that transfer commodity risk upstream to mining and refining operators.
Pricing Analysis
Volume-discount tiering separates fleet operator procurement from individual purchaser transactions, with consolidated buyers capturing pricing advantages through standardized pack architecture commitments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales software bundling intensity. Cost compression in battery-electric platforms is intensifying because cathode material spot exposure feeds through to cell pricing. Fleet operators exhibit lowest price sensitivity due to total cost of ownership modeling, while individual consumers delay adoption at premium tier thresholds.
Supply Chain Analysis
Lithium brine evaporation in Chile's Atacama and hard-rock spodumene mining in Western Australia underwrites cathode precursor supply for Korean and Japanese cell manufacturers. Processing capacity concentrates in China, South Korea, and Germany, with these nodes refining cobalt sulfate, nickel matte, and lithium carbonate into battery-grade inputs. Single-source vulnerability sits with DRC cobalt concentrate and Indonesian nickel pig iron. Distribution runs through OEM-direct contracts and tier-one supplier hubs rather than spot market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-enabled revenue layers including over-the-air feature subscriptions and fleet telematics services are expanding faster than hardware margin contribution, reframing mobility technologies as a service-attach opportunity with recurring income streams.
For Market Incumbents: Shield engineering margins by accelerating backward integration into cathode active material refining to offset lithium cost volatility. Redirect R&D resources from feature development to EU AI Act conformity assessment preparation. Channel control through captive charging infrastructure locks in fleet operator loyalty against emerging platform competitors. For New Entrants and Emerging Players: ISO 26262 functional safety certification fast-tracks market entry by addressing talent scarcity that delays incumbent hiring cycles. Target India's PLI scheme for advanced chemistry cell manufacturing to secure tariff-advantaged production positioning. White space exists in third-party validation services for intelligent driving system documentation under EU regulatory frameworks. For Investors and Strategic Acquirers: Captive lidar and mapping infrastructure specialists represent acquisition targets with defensible data loop economics in autonomous deployment zones. Long-term viability hinges on distinguishing platform owners from component suppliers in a market where software-defined architectures concentrate value capture. Watch sensor fusion certification timeline compression as the inflection signal for engineering margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode material contracts with Korean cell manufacturers secure German OEM platform volumes. |
| Software-Defined Vehicle Investment | Cloud-native stack development enables over-the-air monetization throughout vehicle lifespans for fleet operators. |
| Geographic Manufacturing Footprint | Co-location of battery and software engineering centers in Bavaria compresses EU Green Deal compliance cycles. |
| Charging Infrastructure Partnership | High-power charging networks anchor fleet operator procurement decisions for heavy-duty electrified platforms. |
| Platform Standardization | Unified pack architectures reduce supplier fragmentation and enable volume-based pricing negotiations with cell vendors. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, fleet operator telematics directors, and aftermarket service heads, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring ensures cross-verification of volume and value outputs.
Variance-decomposition framing isolates driver contributions across propulsion architecture, vehicle class, content per vehicle, and regional production cluster dimensions over the projection horizon. CAGRs derive from segment-level growth trajectory modeling that weights fleet procurement concentration against individual purchaser elasticity. Industry-specific inputs include battery cell capacity expansion schedules and autonomous perception stack regulatory certification timelines.
Underlying assumptions cover lithium supply concentration stability and EU emissions mandate enforcement continuity, with deviation risk concentrated in geopolitical trade restrictions and sensor fusion validation timeline extensions. Practitioners should keep alternative scenarios live as F-Gas Regulation threshold tightening and MIIT data localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Automotive Platooning Systems Market