
 Hybrid Cars Market | 2026-2036
Hybrid Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Cars Market Outlook
Fleet operators is reorganizing procurement priorities around total cost of ownership, pulling ahead of individual consumers as the dominant buyer archetype in volume terms. Toyota Motor Corporation anchors its position through captive hybrid system production and vertical control over powertrain components. Ford Motor Company competes on truck and SUV hybrid variants that command higher transaction prices in North American markets. BYD Company Ltd. dominates battery-dominant plug-in architectures that blur the line with full electrification.
Hybrid cars integrate an internal combustion engine with one or more electric motors, a high-voltage battery pack typically rated between 1-15 kWh depending on architecture, and a power-split or clutch-coupled transmission that manages torque blending between propulsion sources. The primary purpose is to reduce fuel consumption and tailpipe emissions without requiring external charging infrastructure dependency. Full hybrid electric vehicles carry the largest installed base and mature service infrastructure, while plug-in hybrid electric vehicles capture the fastest expansion as daily commute distances fall within their electric-only range envelopes. Power-split hybrid technology leads in reliability metrics, though parallel hybrid designs gain ground in European performance-oriented applications.
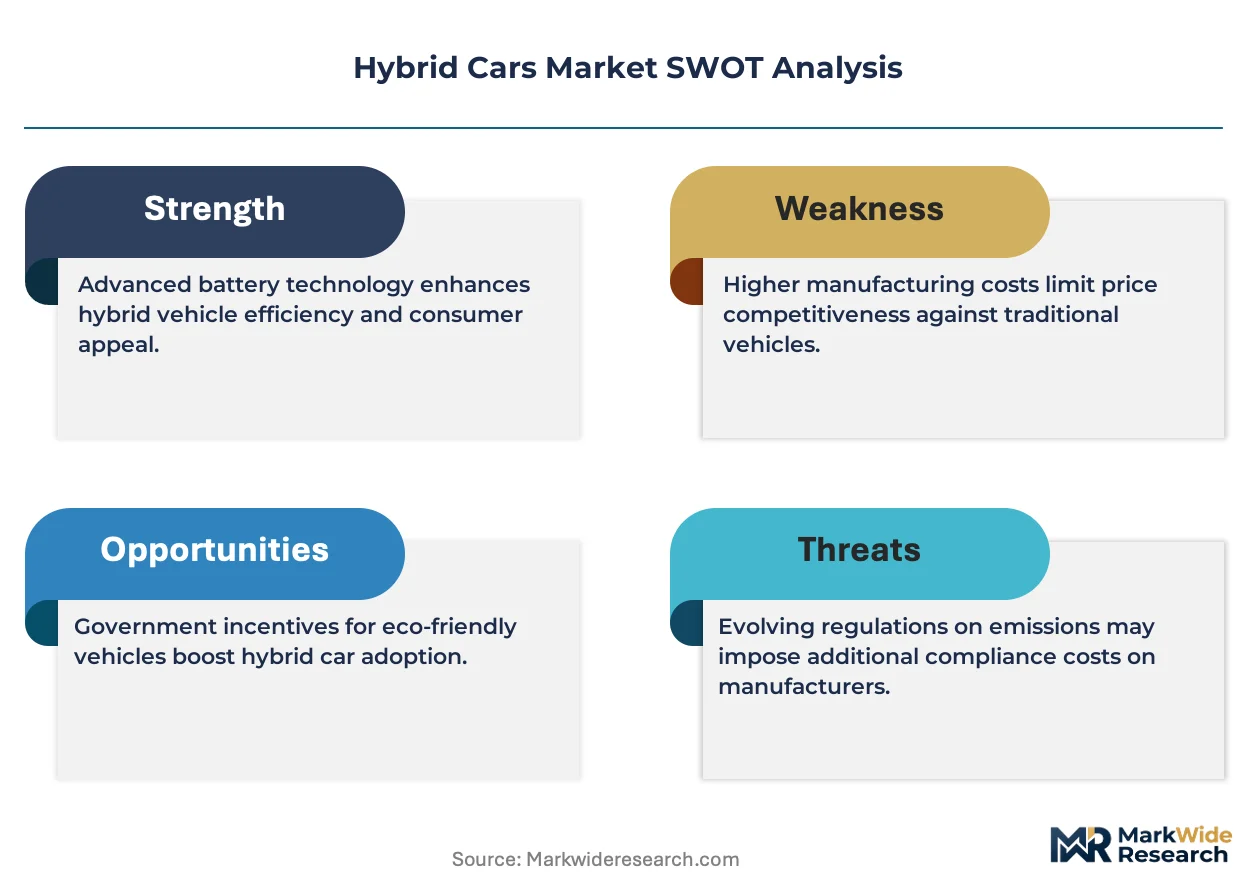
EPA Corporate Average Fuel Economy standards and California Air Resources Board zero-emission vehicle mandates directly shape product mix decisions and powertrain engineering budgets for manufacturers selling into the United States. The EU Green Deal and F-Gas Regulation on mobile air conditioning refrigerants add compliance layers that favor electrified thermal management systems in European-bound models. Stakeholders must monitor how battery mineral supply agreements and evolving tailpipe testing protocols reshape cost structures and certification timelines across their target markets.
Market Dynamics
Fleet procurement is reorganizing around total cost of ownership calculations, pulling ahead of retail consumers as the dominant volume buyer and compressing manufacturer margin structures through consolidated purchasing power.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Fleet operators face tightening compliance thresholds that accelerate hybrid powertrain adoption in light-duty commercial vehicles.
- Urban congestion charging zones:Cities including London, Singapore, and Stockholm impose entry fees on conventional combustion vehicles, creating direct operating cost penalties for non-electrified fleets.
- Lithium-ion pack density improvements:Cell chemistry advances reduce battery mass and packaging volume, enabling hybrid architectures in vehicle segments previously constrained by space or payload requirements.
Market Restraints
- Battery mineral supply concentration:Cobalt and lithium processing capacity clusters in the Democratic Republic of Congo and Chile, exposing procurement to geopolitical disruption and price volatility.
- Full battery electric substitution:Declining BEV sticker prices and expanding fast-charging infrastructure in China and Norway erode the hybrid value proposition for daily-use vehicles.
- F-Gas Regulation compliance costs:The EU mandate for low-global-warming-potential refrigerants forces redesign of thermal management systems, adding certification overhead to European-bound models.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing create localized battery supply for hybrid variants targeting price-sensitive domestic buyers.
- Power-split transmission convergence with 800V architectures:Integration of high-voltage electrical systems enables faster regenerative braking recovery and downsized internal combustion engines.
- Subscription-based fleet electrification services:New mobility-as-a-service platforms bundle vehicle, maintenance, and energy costs into per-mile pricing, lowering adoption barriers for small and mid-size fleet operators.
Industry Challenges
- Power electronics engineering talent scarcity:Shortage of specialists in inverter design and motor control algorithms extends development timelines for next-generation hybrid systems.
- Dual certification burden:Manufacturers must simultaneously satisfy EPA tailpipe testing protocols and California Air Resources Board zero-emission vehicle mandates, diverting engineering resources from product differentiation.
- Legacy dealer service infrastructure:High-voltage battery handling requirements and specialized diagnostic equipment create retraining costs and facility upgrade obligations across franchised networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Cars Market |
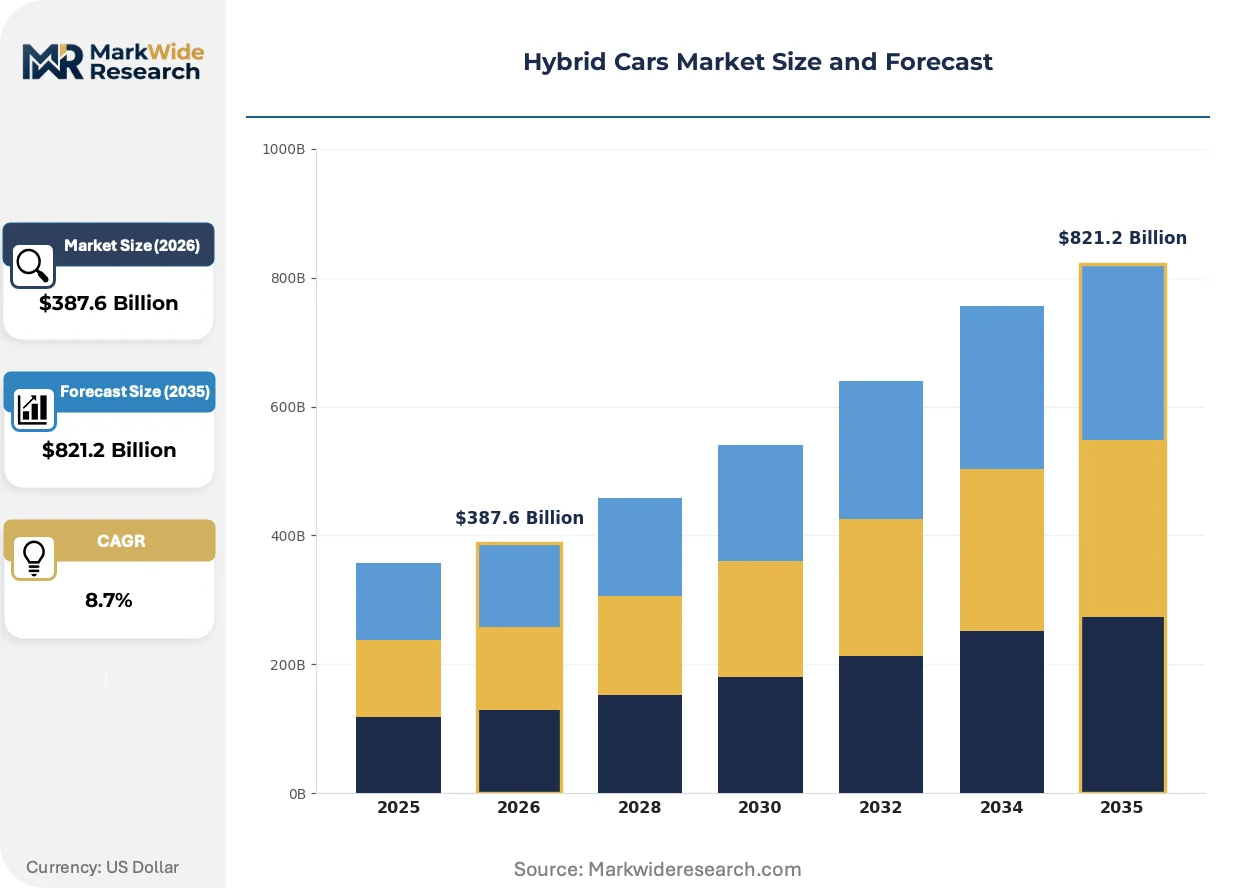
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plug-in Hybrid Electric Vehicles, Mild Hybrid Electric Vehicles, Full Hybrid Electric Vehicles, Battery Electric Vehicles End User: Individual Consumers, Government Fleets, Ride-Sharing Services, Corporate Fleets Technology: Series Hybrid, Parallel Hybrid, Power-Split Hybrid, Hydrogen Fuel Cells Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Toyota Motor Corporation, Honda Motor Co., Ltd., Ford Motor Company, Hyundai Motor Company, Volkswagen AG, BYD Company Ltd., Nissan Motor Corporation, Kia Motors Corporation, Daimler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Cars Market Strategic Shifts
Powertrain engineering is converging on modular architectures that share components across hybrid, plug-in, and full electric variants, compressing development cycles and supplier qualification overhead.
Silicon carbide power semiconductors are supplanting traditional insulated-gate bipolar transistors in inverter designs, cutting switching losses and enabling higher motor speeds. Tier 1 suppliers including Bosch and Denso have accelerated qualification timelines for 800V-rated modules. This transition is compressing the cost gap between premium and mass-market hybrid systems by reducing cooling system complexity.
The EU Green Deal's 2035 internal combustion phase-out deadline is forcing powertrain portfolio restructuring, with engineering budgets shifting toward electrified thermal management and waste heat recovery systems. German manufacturers face particular pressure from the KBA's evolving type-approval protocols for CO2 measurement under real-driving conditions. Product planners are responding by prioritizing plug-in hybrid variants with electric-only ranges that satisfy daily commute distances.
Fleet procurement departments are consolidating supplier relationships around full-lifecycle cost contracts that bundle vehicle acquisition, energy management, and residual value guarantees. Large logistics operators in Germany and Japan are displacing traditional lease structures with usage-based agreements indexed to fuel economy performance. This shift is most visible in last-mile delivery segments where route predictability enables accurate total cost of ownership modeling.
Hybrid Cars Market Segmentation
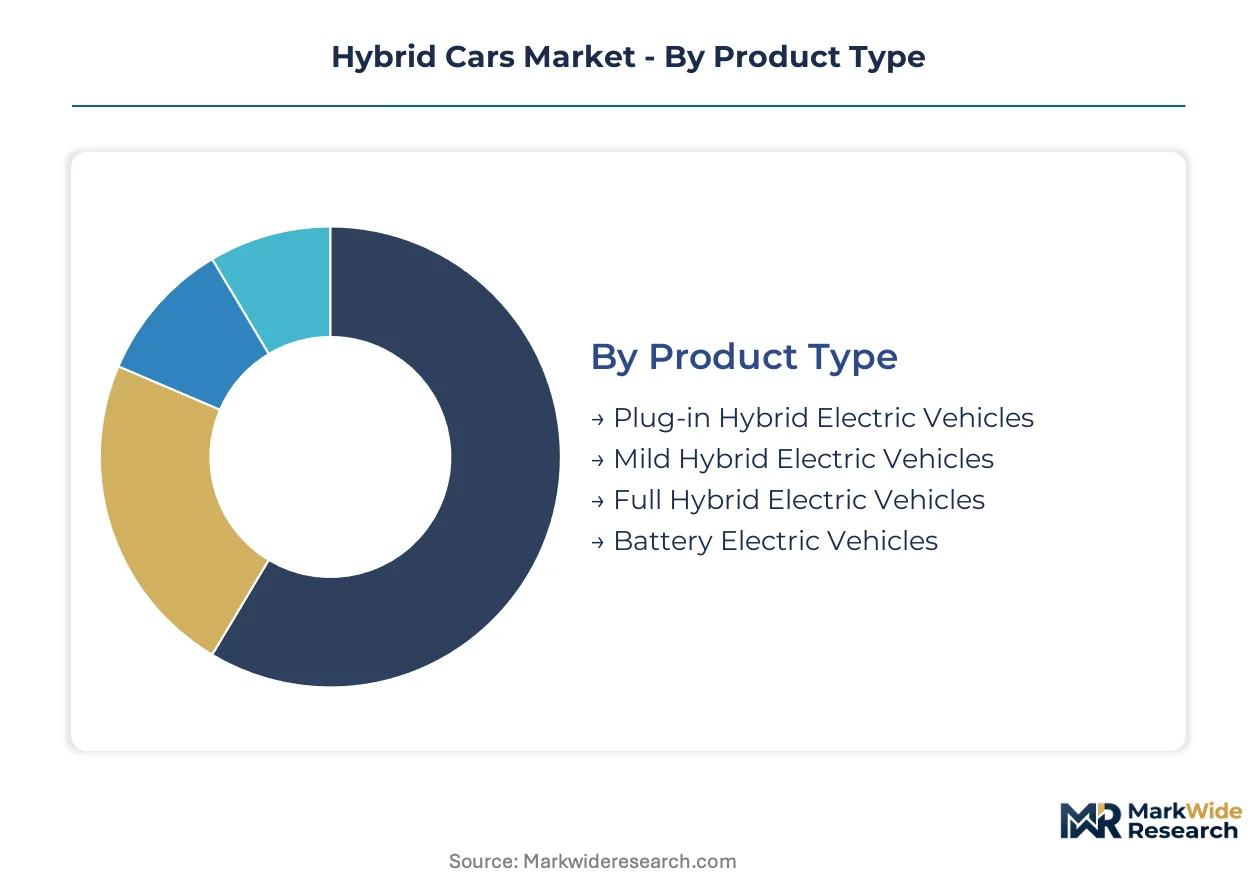
Segmentation in the hybrid cars market reveals distinct procurement patterns across buyer archetypes and powertrain architectures. Fleet operators and individual consumers diverge sharply in their prioritization of upfront cost versus total cost of ownership, while regional regulations favor specific technology configurations.
Product Type:
Channel distribution varies markedly by electrification depth, with full hybrids dominating franchised dealer networks and plug-in variants flowing increasingly through fleet-direct and subscription platforms.
- Full Hybrid Electric Vehicles:These systems combine internal combustion engines with electric motors and battery packs typically rated 1-2 kWh, eliminating plug-in dependency. Toyota's power-split architecture anchors volume production in Japan and North American markets where service infrastructure maturity supports mass-market penetration. EPA Corporate Average Fuel Economy compliance deadlines compress procurement timelines for light-duty commercial fleets.
- Plug-in Hybrid Electric Vehicles:Larger battery packs ranging 8-15 kWh enable 25-50 miles of electric-only range, straddling hybrid and full-electric use cases. BYD and European manufacturers concentrate production for China and Germany where urban congestion charging zones reward daily electric commute capability. Battery mineral supply concentration in Chile and the Democratic Republic of Congo constrains cost reduction trajectories.
- Mild Hybrid Electric Vehicles:48V belt-driven starter-generator systems provide modest torque assist and regenerative braking at minimal cost increment.
- Battery Electric Vehicles:Full electrification architectures without combustion backup, increasingly positioned as hybrid substitutes in Norway and China where charging infrastructure density satisfies range anxiety.
By volume, full hybrids lead. By growth pace, plug-in hybrids are expanding most quickly.
End User:
Procurement scale and contract structure differentiate buyer segments, with consolidated fleet purchasing power compressing manufacturer margins against fragmented retail transactions.
- Corporate Fleets:Large logistics and delivery operators in Germany and Japan negotiate usage-based contracts indexed to fuel economy performance, displacing traditional lease structures. Total cost of ownership modeling dominates procurement decisions where route predictability enables accurate energy cost forecasting.
- Government Fleets:Municipal and national procurement vehicles face tightening public sector carbon budgets and zero-emission vehicle mandates, particularly under California Air Resources Board protocols and EU Green Deal targets. Consolidated purchasing across agency pools accelerates hybrid adoption in light-duty administrative and service vehicles.
- Individual Consumers:Retail buyers prioritize upfront sticker price and brand familiarity over lifecycle cost calculations, creating demand concentration in established hybrid markets.
- Ride-Sharing Services:Platform operators optimize for vehicle utilization rates and fuel economy in high-mileage urban duty cycles.
Corporate fleets command the largest transaction volumes. Government fleets are climbing the fastest on regulatory compliance deadlines.
Technology:
Engineering talent scarcity in power electronics and motor control algorithms extends development timelines unevenly across architecture types, favoring incumbents with captive expertise.
- Power-Split Hybrid:Continuously variable transmission systems using planetary gearsets to blend engine and motor torque dominate reliability metrics and production scale. Toyota's vertical control over powertrain components anchors manufacturing in Japan and Kentucky.
- Parallel Hybrid:Clutch-coupled architectures allowing independent or combined propulsion gain ground in European performance applications where BMW and Mercedes-AMG prioritize driving dynamics. KBA type-approval protocols for real-driving CO2 measurement favor these configurations in German-bound models.
- Series Hybrid:Engine-generator sets powering electric traction motors without mechanical driveline connection suit commercial vehicle applications.
- Hydrogen Fuel Cells:Fuel cell electric vehicles with hydrogen storage represent an alternative electrification pathway with distinct infrastructure dependencies.
Power-split systems hold the installed base advantage. Parallel architectures are gaining share fastest in premium performance segments.
Price Tier:
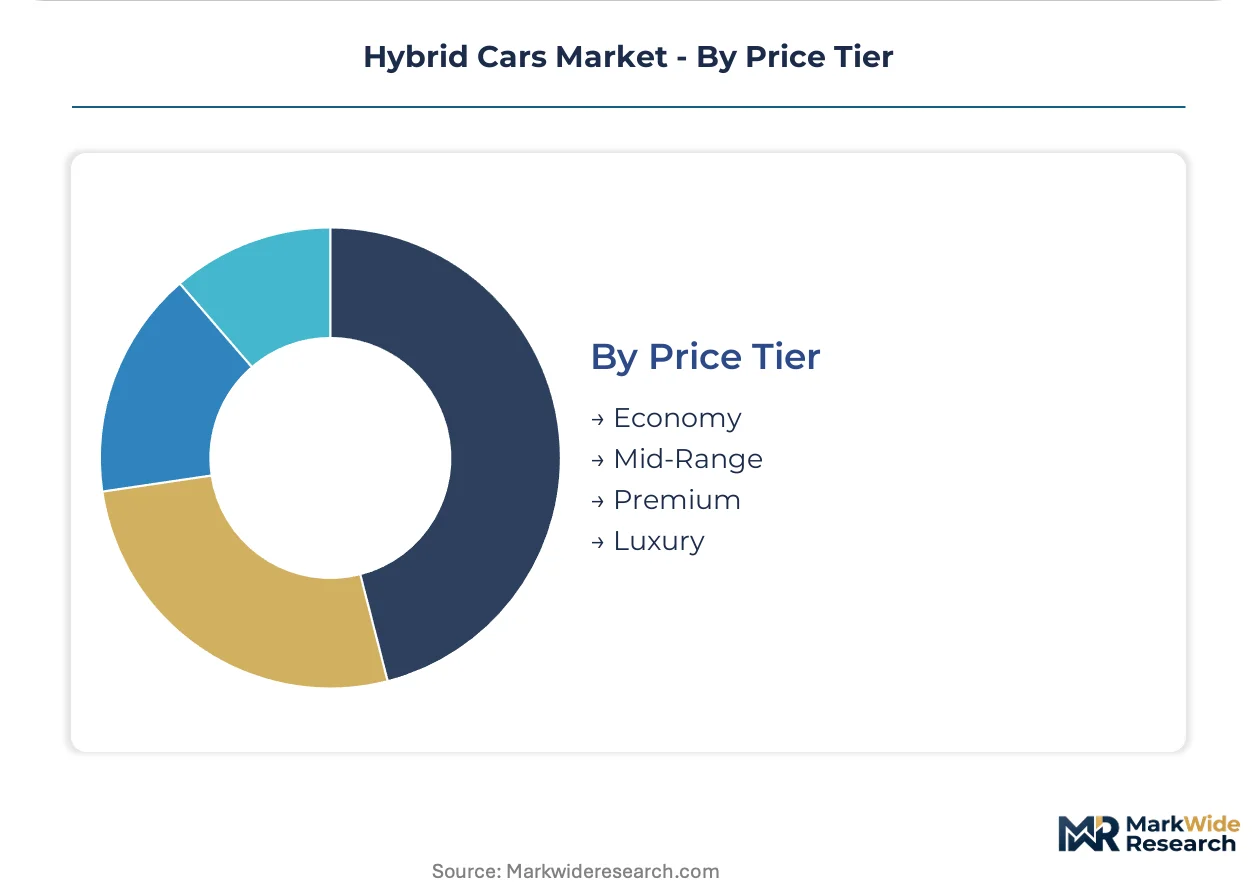
Margin structure stratifies sharply across tiers, with premium and luxury variants subsidizing development costs for economy-segment compliance vehicles.
- Premium:Mid-luxury positioning with advanced driver assistance and electrified thermal management commands transaction prices supporting 800V electrical architecture adoption. German manufacturers concentrate distribution in domestic and Chinese markets where brand equity sustains pricing power.
- Economy:Entry-level hybrids with simplified feature sets and smaller battery packs target price-sensitive buyers in India under PLI scheme incentives for localized cell manufacturing. Maruti Suzuki and Hyundai Motor India optimize for domestic content requirements and fuel economy certification.
- Mid-Range:Volume-focused configurations balancing equipment and cost for mainstream fleet and retail channels.
- Luxury:Ultra-premium positioning with bespoke powertrain calibration and materials.
Economy hybrids move the highest unit volumes. Premium tier hybrids are climbing the fastest on silicon carbide inverter cost reductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments in China concentrate the highest transaction volumes for hybrid powertrains, while regulatory pressure in Germany and California accelerates technology transitions faster than consumer-led markets.
China
Corporate fleet operators in Beijing and Shanghai dominate procurement volumes for plug-in hybrid architectures. The MIIT dual carbon goals and NEV mandate quotas force manufacturers to electrify powertrain portfolios. The Yangtze River Delta manufacturing cluster around Shanghai hosts BYD and SAIC production facilities scaling battery-dominant hybrid systems for domestic and export markets.
United States
Light-duty commercial fleets in California and Texas reorganize procurement around EPA Corporate Average Fuel Economy compliance deadlines. The California Air Resources Board zero-emission vehicle mandates create a bifurcated regulatory environment that favors plug-in variants in the Western states. Detroit's engineering centers concentrate power-split transmission development for truck and SUV hybrid variants targeting North American transaction prices.
Germany
Premium automotive manufacturers in Bavaria and Baden-Württemberg prioritize plug-in hybrid electric vehicles with electric-only ranges satisfying daily commute distances. The KBA's evolving type-approval protocols for real-driving CO2 measurement compress development timelines for powertrain calibration. Stuttgart and Munich anchor R&D investment in 800V electrical architectures and silicon carbide inverter qualification.
Japan
Toyota's power-split hybrid production in Aichi Prefecture supplies global demand for full hybrid electric vehicles with mature service infrastructure. METI's fuel economy standards and carbon neutrality targets accelerate mild hybrid adoption in kei-car segments. The Nagoya industrial corridor concentrates captive powertrain component manufacturing and vertical control over hybrid system production.
India
Price-sensitive domestic buyers in Maharashtra and Tamil Nadu drive demand for economy-segment hybrids under the PLI scheme for advanced chemistry cell manufacturing. The Bureau of Indian Standards fuel efficiency norms tighten compliance thresholds for light-duty vehicles. Maruti Suzuki and Hyundai Motor India optimize production in Haryana and Chennai for localized content requirements and certification protocols.
Hybrid Cars Market Competitive Environment
Player mix skews toward vertically integrated conglomerates with captive powertrain component supply. Consolidation pressures concentrate volume around manufacturers controlling battery chemistry, motor design, and transmission engineering in-house. Three archetypes dominate: Asian mass-market specialists with hybrid-first legacies, European premium brands pivoting from diesel competence, and Chinese battery-dominant challengers blurring hybrid-electric boundaries. Competitive moves center on M&A for mineral supply agreements and strategic partnerships for 800V architecture licensing.
Among Asian mass-market specialists, Toyota Motor Corporation and Honda Motor Co., Ltd. occupy positions defined by decades of power-split hybrid production scale. Ford Motor Company exemplifies the North American truck-SUV pivot toward electrified variants commanding higher transaction prices. BYD Company Ltd. anchors the battery-dominant archetype with plug-in architectures that leverage captive cell manufacturing.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Honda Motor Co., Ltd. |
| Ford Motor Company |
| Hyundai Motor Company |
| Volkswagen AG |
| BYD Company Ltd. |
| Nissan Motor Corporation |
| Kia Motors Corporation |
| Daimler AG |
| Others |
Value Chain & Pricing Dynamics
Long-term battery mineral offtake agreements with Chilean and Congolese suppliers lock in lithium and cobalt access while capping price volatility exposure for hybrid powertrain manufacturers facing fleet procurement consolidation.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lithium and cobalt benchmarks dominate procurement between cell manufacturers and OEMs. Three-tier pricing structure across premium, standard, and economy levels differentiates by battery pack capacity and power electronics specification. Price erosion runs through economy-segment hybrids as India's PLI scheme for advanced chemistry cell manufacturing expands localized supply. Fleet operators exhibit lowest price sensitivity due to total cost of ownership modeling, while individual retail buyers in emerging markets drive hardest bargain on sticker price.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and nickel sulfate supersedes just-in-time preferences as battery mineral supply concentration in Chile, the Democratic Republic of Congo, and Indonesia exposes procurement to geopolitical disruption. Cell production draws from cathode active material processing in China and South Korea. Single-source vulnerability around Indonesian nickel processing creates chokepoint risk. Distribution runs through captive Tier 1 supplier networks vertically controlled by Toyota and BYD, with aftermarket service parts flowing through franchised dealer channels requiring high-voltage certification upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid powertrain incumbents face substitution defense against full battery electric vehicles as charging infrastructure density in China and Norway erodes the hybrid value proposition for daily-use segments.
For Market Incumbents: Shield installed base advantage through captive powertrain component production and backward integration into battery cell manufacturing. Accelerate 800V electrical architecture adoption to compress cost gaps with mass-market competitors. Defend against Chinese battery-dominant challengers by locking in long-term lithium offtake agreements before mineral supply tightens further.
For New Entrants and Emerging Players: California Air Resources Board zero-emission vehicle certification fast-track offers regulatory pathway into the United States market. Target last-mile delivery fleet operators in Germany and Japan with subscription-based electrification services bundling vehicle and energy costs. Penetrate India's economy segment through PLI scheme partnerships for localized cell manufacturing.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated conglomerates with captive motor design and transmission engineering capabilities. Long-term viability hinges on mineral supply agreement portfolios spanning Chile, Australia, and Indonesia. Watch for inflection when EPA Corporate Average Fuel Economy compliance deadlines force accelerated fleet procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium and cobalt access under cost-plus indexing against LME volatility. |
| Platform Standardization | Enables component sharing across hybrid, plug-in, and full electric variants compressing development cycles. |
| Software-Defined Vehicle Investment | Integrates powertrain control algorithms with over-the-air calibration updates for EPA compliance. |
| Geographic Manufacturing Footprint | Positions production within India's PLI scheme zones to capture localized cell cost advantages. |
| Charging Infrastructure Partnership | Blurs hybrid-electric boundary by enabling plug-in variants to satisfy daily commute range envelopes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA certification databases, MIIT production filings, and IHS Markit vehicle registration data. OEM platform engineers, Tier 1 supplier procurement leads, and fleet operations directors provided qualitative input on powertrain sourcing decisions. Bottom-up unit economics triangulate against top-down regulatory mandate analysis across the United States, China, Germany, Japan, and India.
Segmentation dimensions modeled include propulsion architecture, vehicle class, battery pack capacity tier, OEM vertical integration level, and regional regulatory cluster. CAGRs derive from installed base growth trajectories and replacement cycle dynamics throughout the forecast period. Forecast inputs incorporate EPA Corporate Average Fuel Economy compliance deadlines and EU Green Deal internal combustion phase-out timelines.
Decision-makers should treat outputs as directional under assumptions of continued lithium-ion cost reduction and stable mineral supply agreements; material deviation would warrant model refresh. Revision becomes warranted when battery mineral supply concentration crosses geopolitical disruption thresholds or full battery electric vehicle pricing parity accelerates beyond modeled trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Middle East and Africa Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Crossover Vehicle Market