
 UK Automotive Camera Market | 2026-2036
UK Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Camera Market Analytics
Software-defined subscription services for over-the-air camera calibration and ADAS feature activation is recalibrating what vehicle manufacturers monetize per unit. Continental AG leverages its embedded software stack to sustain recurring revenue from camera-based safety modules. Robert Bosch GmbH anchors its UK position through localized R&D facilities focused on computer vision algorithms. Valeo competes through specialized thermal imaging expertise for premium passenger vehicle lines.
UK automotive cameras integrate CMOS image sensors, signal processing chipsets, and sealed lens assemblies engineered to IP6K9K ingress protection standards for sustained operation under vibration, thermal shock, and chemical exposure. The primary commercial purpose spans collision avoidance, lane-keeping assistance, and automated parking across passenger and commercial vehicle platforms. Rearview camera systems occupy mature volume positions with thin margins, while surround-view configurations capture expanding value pools in electric vehicle architectures. Night vision technology leads differentiation in premium segments despite constrained adoption breadth. Fleet management applications represent the fastest-growing demand channel as logistics operators mandate multi-camera visibility for insurance compliance and driver behavior monitoring.
The UK's Vehicle Certification Agency enforces UN ECE R79 and R158 standards for camera-based driver assistance and rear visibility systems, directly shaping OEM product roadmaps and homologation timelines. The General Safety Regulation mandates intelligent speed assistance and advanced emergency braking with camera input, compelling Tier-1 suppliers to redesign sensor fusion architectures. DVSA commercial vehicle inspection protocols now incorporate camera functionality checks during annual MOT-equivalent testing for heavy goods vehicles. Stakeholders must monitor how the UK adapts post-EU type-approval frameworks to determine whether divergence or alignment with UNECE regulations accelerates or fragments supplier certification burdens.
Market Dynamics
The General Safety Regulation's intelligent speed assistance mandate is forcing Tier-1 suppliers to redesign sensor fusion architectures around front-facing cameras, compressing homologation timelines and redrawing competitive positioning among embedded software providers.
Growth Catalysts
- UN ECE R158 rear visibility mandate:The UK's Vehicle Certification Agency enforces this standard for all new passenger vehicles, compelling OEMs to integrate camera-based monitoring systems as baseline equipment.
- West Midlands manufacturing cluster concentration:Tier-1 suppliers co-locate R&D and production facilities near Jaguar Land Rover and Aston Martin assembly plants, reducing logistics friction for just-in-time camera module delivery.
- Commercial fleet insurance compliance:Logistics operators mandate multi-camera visibility systems for driver behavior monitoring, creating pull-through demand for aftermarket installation networks.
Market Restraints
- CMOS image sensor supply concentration:Foundry capacity for automotive-grade sensors concentrates in East Asian manufacturing hubs, exposing UK assemblers to geopolitical shipping disruptions and extended lead times.
- Homologation cost escalation:Post-EU type-approval uncertainty forces suppliers to maintain parallel certification tracks for UNECE alignment and potential UK divergence, doubling regulatory compliance overhead.
- Silicon carbide substrate volatility:Signal processing chipsets depend on advanced semiconductor materials subject to energy-intensive production constraints and input price instability.
Strategic Opportunities
- Software-defined camera calibration:Over-the-air subscription services for ADAS feature activation enable recurring revenue streams beyond hardware shipment, displacing one-time module sales.
- Thermal imaging convergence:Night vision technology integration with standard visible-spectrum cameras creates premium differentiation for luxury passenger vehicle lines.
- DVSA commercial vehicle inspection expansion:Annual functionality checks for heavy goods vehicles institutionalize replacement cycles and standardize minimum performance thresholds across fleet operators.
Industry Challenges
- Computer vision algorithm talent scarcity:The UK competes with German and US technology clusters for embedded software engineers capable of optimizing real-time object detection under automotive thermal and vibration constraints.
- IP6K9K sealing certification timelines:Validating lens assemblies against ingress protection standards for chemical exposure and pressure washing extends product development cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Camera Market |
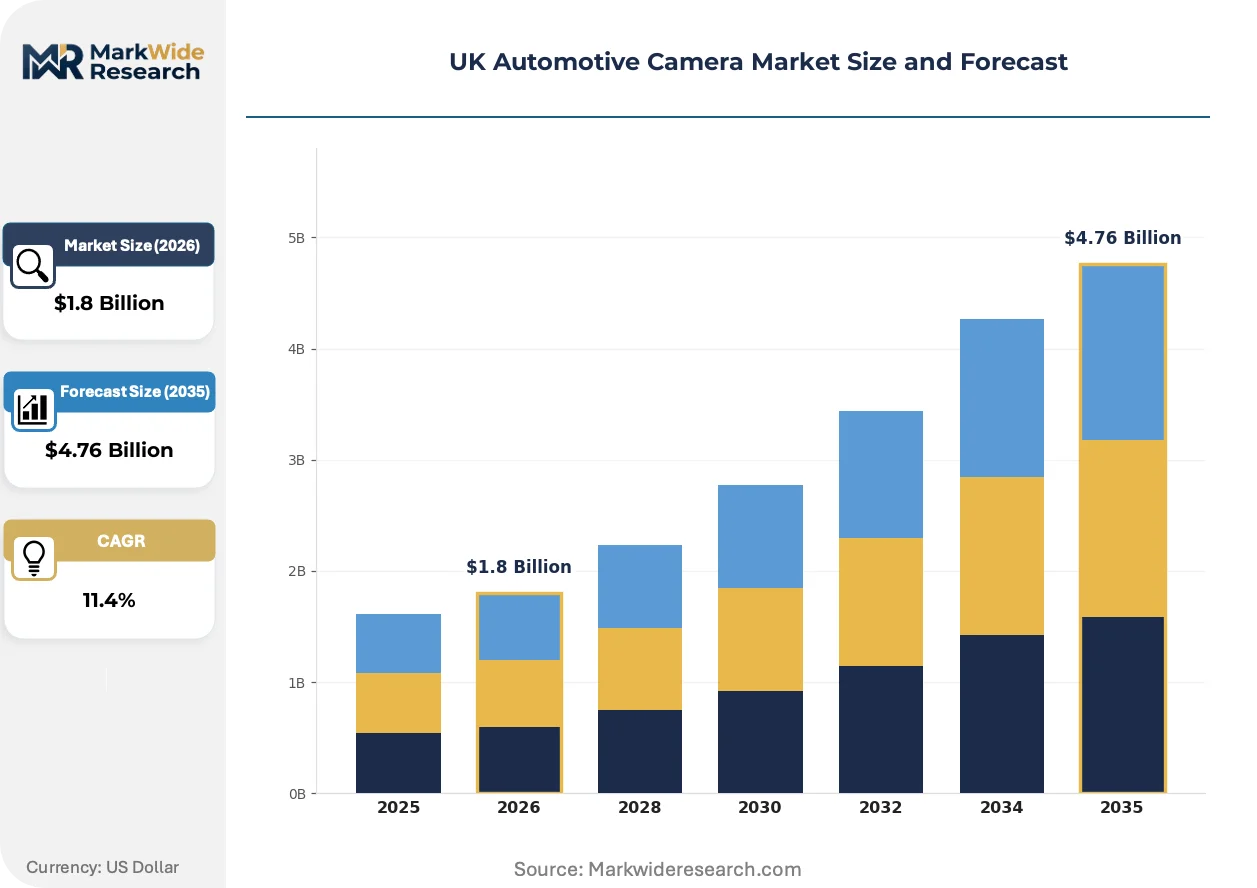
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Camera, Dashcam, Surround-View System, Night Vision Camera Technology: Digital, Analog, Thermal, LiDAR Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Fleet Management End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Valeo, Denso Corporation, ZF Friedrichshafen AG, Aptiv, Autoliv Inc., AISIN Seiki Group, AEI Boston, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Camera Market Evolving Landscape
Camera module architecture is bifurcating between cost-optimized rearview commodity units and compute-intensive surround-view systems that anchor electric vehicle platform differentiation.
8-megapixel CMOS image sensors are electrifying high-resolution front-facing applications for highway pilot and traffic sign recognition. Premium OEMs adopt these sensors for intelligent speed assistance compliance. The technology is compressing margins on 2-megapixel legacy configurations while expanding addressable content per vehicle.
The General Safety Regulation mandates advanced emergency braking with camera input across all new UK vehicle registrations. This compels Tier-1 suppliers to pre-integrate radar fusion before 2026 enforcement dates. Passenger vehicle platforms face the steepest redesign requirements, with commercial van segments trailing by eighteen to twenty-four months.
Fleet procurement now favors bundled hardware-software contracts with predictive maintenance clauses over discrete component purchasing. Large logistics operators negotiate direct with calibration service providers, disintermediating traditional aftermarket distributors. This pattern concentrates in long-haul trucking fleets operating under DVSA operator license compliance frameworks.
UK Automotive Camera Market Segmentation
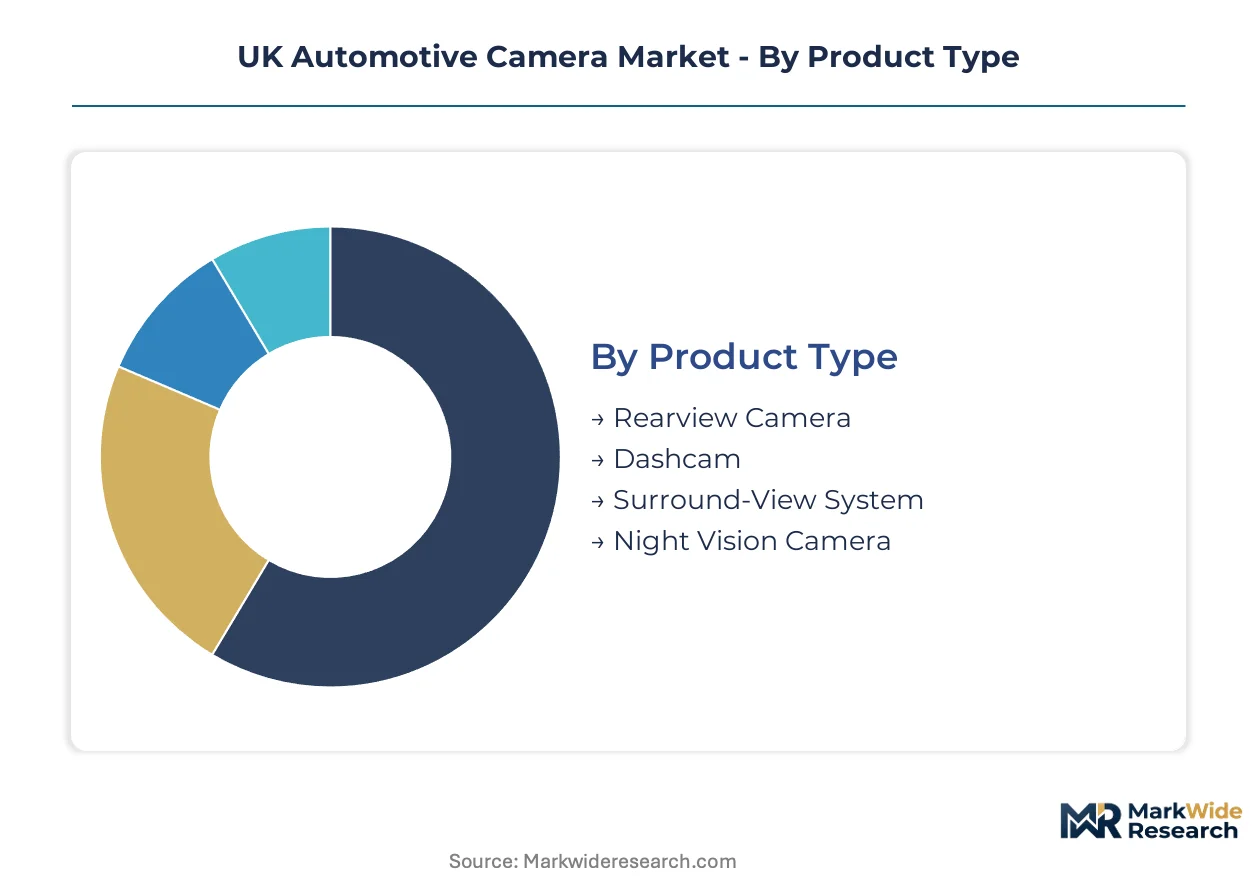
Camera module specifications diverge sharply between regulatory-mandated baseline systems and compute-intensive premium configurations. Understanding these technology-application intersections reveals where Tier-1 suppliers concentrate R&D investment versus where margin compression threatens hardware commoditization.
Product Type:
Resolution and field-of-view specifications define competitive positioning across camera categories.
- Rearview Camera:Single-lens CMOS units delivering 130-degree horizontal coverage dominate volume production for UN ECE R158 compliance. West Midlands OEM assembly lines source these as standardized modules with minimal customization, compressing supplier margins toward assembly-line economics.
- Surround-View System:Four-camera fusion architectures generate stitched 360-degree environmental mapping for automated parking and low-speed maneuvering. Electric vehicle platforms in premium segments drive specification escalation toward 3-megapixel minimums per lens unit.
- Dashcam:Forward-facing recording devices with looped storage and G-force incident tagging serve insurance documentation requirements for commercial fleet operators.
- Night Vision Camera:Thermal imaging cores operating in far-infrared spectrum extend pedestrian detection range beyond headlamp illumination for luxury passenger vehicle lines.
Mature deployment sits with Rearview Camera. Newer deployment is concentrated in Surround-View System.
Technology:
Signal processing architectures separate legacy automotive electronics from next-generation sensor fusion platforms.
- Digital:CMOS image sensors with integrated analog-to-digital conversion enable direct ISP handshake for real-time object detection pipelines. Jaguar Land Rover and Aston Martin specification sheets mandate digital interfaces for all new platform introductions.
- Thermal:Uncooled microbolometer arrays detect 8-14 micron wavelength emissions for pedestrian and animal classification independent of visible illumination. Premium SUV and executive sedan segments absorb the 4-6x cost premium over visible-spectrum alternatives.
- Analog:CVBS signal transmission persists in entry-level rearview applications where display integration costs dominate module selection criteria.
- LiDAR:Solid-state scanning units with camera fusion capability anchor Level 3 automated highway pilot development programs.
Volume concentration rests with Digital. Capability expansion is accelerating fastest in Thermal.
Application:
Vehicle platform electrification and operational duty cycles reshape camera count and specification requirements.
- Commercial Vehicles:Multi-camera configurations spanning cab interior, forward road, and blind-spot monitoring satisfy DVSA operator license compliance and fleet insurance underwriting requirements. Long-haul trucking operators mandate minimum six-camera installations for driver behavior analytics.
- Electric Vehicles:Surround-view and interior monitoring systems support automated valet parking and cabin occupancy detection. Battery packaging constraints drive camera module miniaturization toward 25mm lens height maximums.
- Passenger Vehicles:Front-facing intelligent speed assistance cameras achieve regulatory compliance with 1.2-megapixel resolution thresholds.
- Fleet Management:Telematics-integrated camera systems with cloud connectivity enable real-time driver coaching and incident reconstruction for logistics operators.
Regulatory pressure concentrates in Passenger Vehicles. Operational complexity is expanding most quickly in Commercial Vehicles.
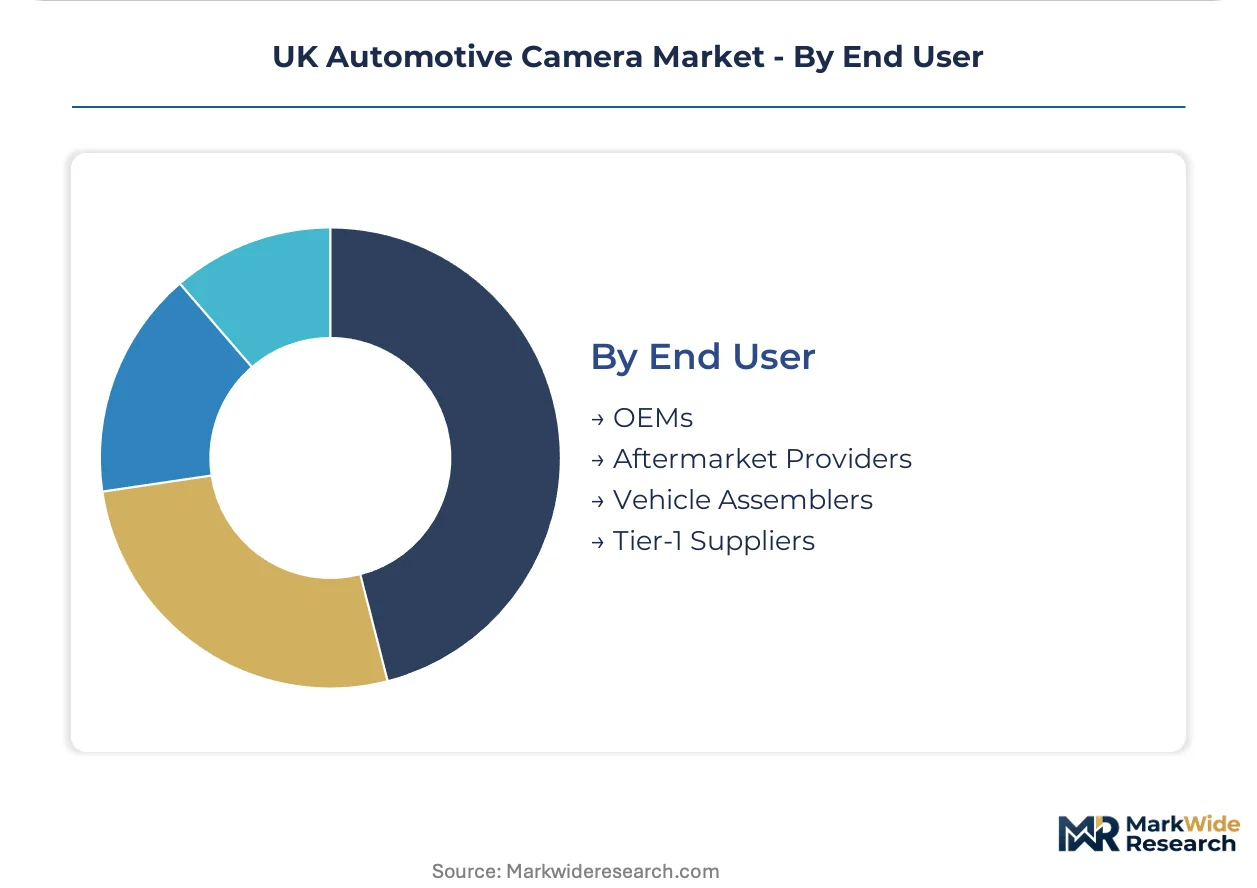
End User:
Procurement authority and integration depth determine contract structures and margin retention.
- OEMs:Vehicle manufacturers specify camera modules at platform design stage, locking in five-to-seven year supply agreements with embedded software maintenance clauses. General Safety Regulation mandates force front-facing camera inclusion across all volume model lines.
- Tier-1 Suppliers:Continental AG, Robert Bosch GmbH, and Valeo integrate camera hardware with radar fusion and domain controller electronics, capturing system-level value pools beyond discrete component supply.
- Aftermarket Providers:Installation networks serving commercial fleet retrofit demand compete on calibration service capability and DVSA inspection compliance documentation.
- Vehicle Assemblers:Contract manufacturers without full design authority execute build-to-print camera module integration under OEM engineering direction.
Design control sits with OEMs. Margin expansion is shifting toward Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK automotive camera production concentrates in the West Midlands manufacturing corridor, while consumption distributes across fleet operator networks concentrated near major logistics hubs. Domestic assembly lines supply Jaguar Land Rover and Aston Martin platforms, with component sourcing extending to East Asian foundries for CMOS image sensors. The country's regulatory alignment with UN ECE standards shapes homologation pathways for both OEM and aftermarket channels.
England
Commercial fleet operators in the Midlands and Northern England drive multi-camera retrofit demand for DVSA operator license compliance. The General Safety Regulation mandates intelligent speed assistance across all new vehicle registrations, compelling Tier-1 suppliers to accelerate front-facing camera integration. Birmingham and Coventry anchor embedded software development clusters serving Jaguar Land Rover's platform roadmaps.
Scotland
Specialist computer vision engineering talent concentrates around Edinburgh and Glasgow university research partnerships. Transport Scotland's freight decarbonization programs incentivize camera-based driver behavior monitoring in heavy goods vehicle fleets. Aberdeen's energy sector logistics operators pilot thermal imaging integration for harsh-weather fleet operations.
Wales
Commercial vehicle assembly plants in South Wales source camera modules through just-in-time supply chains linked to West Midlands Tier-1 facilities. Welsh Government advanced manufacturing grants support sensor fusion testing infrastructure for automated parking systems. The A55 corridor hosts aftermarket installation networks serving cross-border Irish Sea freight operators.
Northern Ireland
All-island logistics networks create cross-border camera standardization pressure between UK UN ECE alignment and potential EU divergence. Belfast's automotive electronics heritage supports niche calibration service providers for commercial fleet insurance compliance. Port infrastructure around Larne drives demand for surround-view systems in heavy goods vehicle maneuvering.
UK Automotive Camera Market Competitive Landscape
Top-tier vendors anchor system-level integration, while specialized component suppliers compete on module miniaturization and thermal management. The UK market exhibits moderate consolidation among Tier-1 suppliers capable of sensor fusion architecture design, with fragmentation persisting in aftermarket calibration services and fleet retrofit installation networks. Two strategic archetypes dominate: embedded software stack providers monetizing over-the-air feature activation, and thermal imaging specialists capturing premium passenger vehicle differentiation. Competitive moves center on co-location of R&D facilities near West Midlands OEM assembly plants and software-defined service portfolio expansion.
Within the Tier-1 systems integration tier, Continental AG, Robert Bosch GmbH, and Valeo exemplify contrasting strategic positioning. Continental AG represents the embedded software monetization archetype through recurring revenue models for camera calibration services. Robert Bosch GmbH anchors localized engineering presence with UK-based computer vision algorithm development. Valeo occupies the thermal imaging specialization position, serving premium OEM lines with far-infrared sensor integration. These three entities collectively illustrate how hardware shipment economics yield to software-defined value capture in next-generation ADAS deployment.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Valeo |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Aptiv |
| Autoliv Inc. |
| AISIN Seiki Group |
| AEI Boston |
| Others |
Value Network & Pricing Analysis
CMOS image sensor foundry pricing indices in Taiwan and South Korea cascade through UK automotive camera supply chains, stratifying module costs across premium surround-view systems, standard front-facing ADAS units, and economy-grade rearview commodity configurations.
Pricing Analysis
Margin tightening in rearview camera modules reflects West Midlands OEM procurement consolidation around standardized UN ECE R158 compliance units. Three-tier pricing structure across premium, standard, and economy levels separates 8-megapixel intelligent speed assistance configurations from 2-megapixel legacy rearview and thermal imaging night vision tiers. Cost-down pressure on economy-grade modules accelerates because Tier-1 suppliers compete for volume platform slots with minimal customization. Commercial fleet operators exhibit highest price sensitivity, while premium passenger vehicle OEMs absorb thermal imaging premiums for differentiation.
Supply Chain Analysis
Regional distribution centers in the West Midlands operate hub-and-spoke patterns radiating to Jaguar Land Rover and Aston Martin assembly plants, with secondary nodes serving Welsh commercial vehicle facilities. Geographic supply concentration centers on Taiwan and South Korea for CMOS image sensors, Germany for signal processing chipsets, and Japan for sealed lens assemblies. Raw material dependencies include silicon carbide substrates, automotive-grade optical glass, and IP6K9K-rated sealing compounds. Single-source vulnerability in East Asian foundry capacity exposes UK assemblers to geopolitical shipping disruptions. Distribution runs through just-in-time Tier-1 supplier networks with OEM direct contracts dominating procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
General Safety Regulation homologation cost escalation positions this market as a consolidation play, forcing sub-scale calibration service providers and aftermarket distributors into acquisition or exit.
For Market Incumbents: Extend software-defined service portfolios to capture recurring revenue from over-the-air camera calibration subscriptions, displacing one-time hardware margins. Anchor localized R&D presence in Birmingham and Coventry computer vision clusters to defend against German and US technology cluster talent poaching. Prioritize backward integration into embedded software stacks to reduce dependency on external algorithm licensing.
For New Entrants and Emerging Players: Capture aftermarket fleet retrofit demand concentrated in Northern England and Scottish logistics corridors, where DVSA operator license compliance mandates institutionalize replacement cycles. Target commercial vehicle dashcam and driver behavior monitoring segments with bundled hardware-software contracts featuring predictive maintenance clauses. Pursue direct procurement relationships with long-haul trucking operators, disintermediating traditional aftermarket distributor networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized thermal imaging module developers with far-infrared sensor integration capabilities in the West Midlands corridor. Long-term viability hinges on software-defined revenue mix and embedded algorithm IP ownership rather than pure hardware shipment economics. Monitor UK Vehicle Certification Agency post-EU type-approval divergence signals as inflection indicator for regulatory compliance overhead expansion or contraction.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Over-the-air calibration subscriptions transform Continental AG's recurring revenue model. |
| Backward Integration into CMOS Design | In-house sensor specification reduces exposure to Taiwan foundry capacity constraints. |
| Geographic Manufacturing Footprint | West Midlands co-location secures just-in-time delivery to Jaguar Land Rover platforms. |
| Platform Standardization | Unified sensor fusion architectures accelerate General Safety Regulation homologation timelines. |
| Charging Infrastructure Partnership | Electric vehicle camera miniaturization aligns with battery packaging space constraints. |
Research Methodology
Independent corroboration across Tier-1 supplier procurement executives, OEM platform engineers, aftermarket distributors, and DVSA compliance officers underwrites the qualitative findings. Primary interviews with embedded software development leads and thermal imaging R&D directors combined with secondary validation from UN ECE regulatory filings, Vehicle Certification Agency type-approval databases, and automotive production registration data. Bottom-up module shipment estimates and top-down ADAS content-per-vehicle analysis triangulate market sizing.
Comparable-period anchoring to historical intelligent speed assistance mandate adoption curves shaped the forecast window construction. Segmentation modeling spans resolution tier, vehicle propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster concentration. CAGRs derive from installed base growth rates and replacement cycle analysis. Forecast inputs include CMOS sensor foundry capacity expansion announcements and General Safety Regulation enforcement phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UK-EU regulatory divergence and East Asian semiconductor supply disruptions. Outputs reflect documented assumptions around homologation timeline adherence and fleet operator procurement pattern stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market