
 Automotive HMI Market | 2026-2036
Automotive HMI Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive HMI Market Intelligence
The architectural shift from distributed electronic control units (ECUs) to centralized domain controllers is reconfiguring the entire automotive HMI development stack. Visteon Corporation specializes in digital instrument clusters and large-format display technologies optimized for this new architecture. Continental AG leverages its deep systems integration expertise to deliver complete, pre-validated cockpit solutions to global automakers. Robert Bosch GmbH competes by supplying a broad portfolio of underlying hardware, software, and critical semiconductor components.
Automotive Human-Machine Interface (HMI) refers to the integrated systems and components through which drivers and passengers interact with a vehicle's core functions. These systems merge input devices, including capacitive touchscreens with haptic feedback, with output components like central information displays to manage navigation and entertainment. Across product types, large-format touchscreen displays and fully reconfigurable instrument clusters command significant OEM investment. Concurrently, gesture control and advanced voice recognition represent the fastest-growing, premium-feature segments.
Driver distraction and safety standards, enforced by the US NHTSA and through UNECE regulations in Europe and Japan, directly shape fundamental HMI design principles. In China, MIIT guidelines for data security and connectivity influence HMI software architecture and over-the-air update capabilities. Suppliers must therefore balance the consumer demand for feature-rich user experiences with increasingly stringent functional safety and cybersecurity mandates.
Market Dynamics
The automotive industry's architectural pivot from distributed ECUs to centralized domain controllers is the central force shaping the HMI market. This shift compels a fundamental reconfiguration of the software stack and hardware supply chain, favoring integrated, updatable cockpit systems.
Growth Catalysts
- Consumer Electronics Convergence:Demand for smartphone-like user experiences, characterized by fluid graphics and intuitive interfaces, pressures OEMs to adopt advanced HMI technologies, particularly in the competitive electric vehicle segment concentrated in China.
- Advanced Driver-Assistance Systems (ADAS):The integration of ADAS features requires more sophisticated HMI solutions to clearly and safely communicate system status and alerts to the driver, driving investment in multi-modal interfaces like AR-HUDs and haptic feedback.
- Safety Mandates:European regulations promoting Driver Monitoring Systems (DMS) create demand for HMI platforms capable of integrating camera and sensor data to detect driver drowsiness or distraction, linking safety compliance directly to HMI functionality.
Market Restraints
- Semiconductor Dependencies:The reliance on a concentrated pool of suppliers for high-performance System-on-Chip (SoC) processors and automotive-grade display panels creates supply chain vulnerabilities and pricing pressures for HMI hardware manufacturers.
- Software Complexity and Cost:Developing and validating safety-critical HMI software that complies with standards like ISO 26262 (ASIL) is resource-intensive, extending development timelines and increasing non-recurring engineering costs for suppliers.
- System Integration Challenges:The technical difficulty of integrating disparate software components, including hypervisors, multiple operating systems like Android and QNX, and proprietary OEM applications onto a single domain controller acts as a significant barrier.
Strategic Opportunities
- In-Cabin Monetization:The shift to software-defined vehicles unlocks opportunities for recurring revenue through subscription-based features, in-vehicle app stores, and services delivered via over-the-air (OTA) updates to the HMI system.
- Augmented Reality HUDs:AR-based Head-Up Displays that overlay navigation and ADAS information directly onto the driver's view of the road represent a significant growth area for premium vehicles, offering enhanced safety and user experience.
- Commercial Vehicle Telematics:Upgrading the traditionally spartan HMI in commercial trucks and fleet vehicles with integrated telematics, navigation, and diagnostics offers a substantial, underpenetrated market for ruggedized and function-specific display solutions.
Industry Challenges
- Cybersecurity Threat Management:Ensuring the security of connected HMI systems against remote attacks is a persistent operational challenge, requiring continuous monitoring, vulnerability patching, and compliance with UNECE R155 regulations throughout the vehicle's lifespan.
- Talent Scarcity:A shortage of software engineers with dual expertise in automotive-grade embedded systems and modern consumer-facing UX/UI design creates a critical talent bottleneck for both OEMs and Tier-1 suppliers.
- User Experience vs. Distraction:Balancing the consumer appetite for feature-rich, interactive displays with the regulatory imperative to minimize driver distraction, as guided by NHTSA principles, remains a core design conflict for HMI developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive HMI Market |
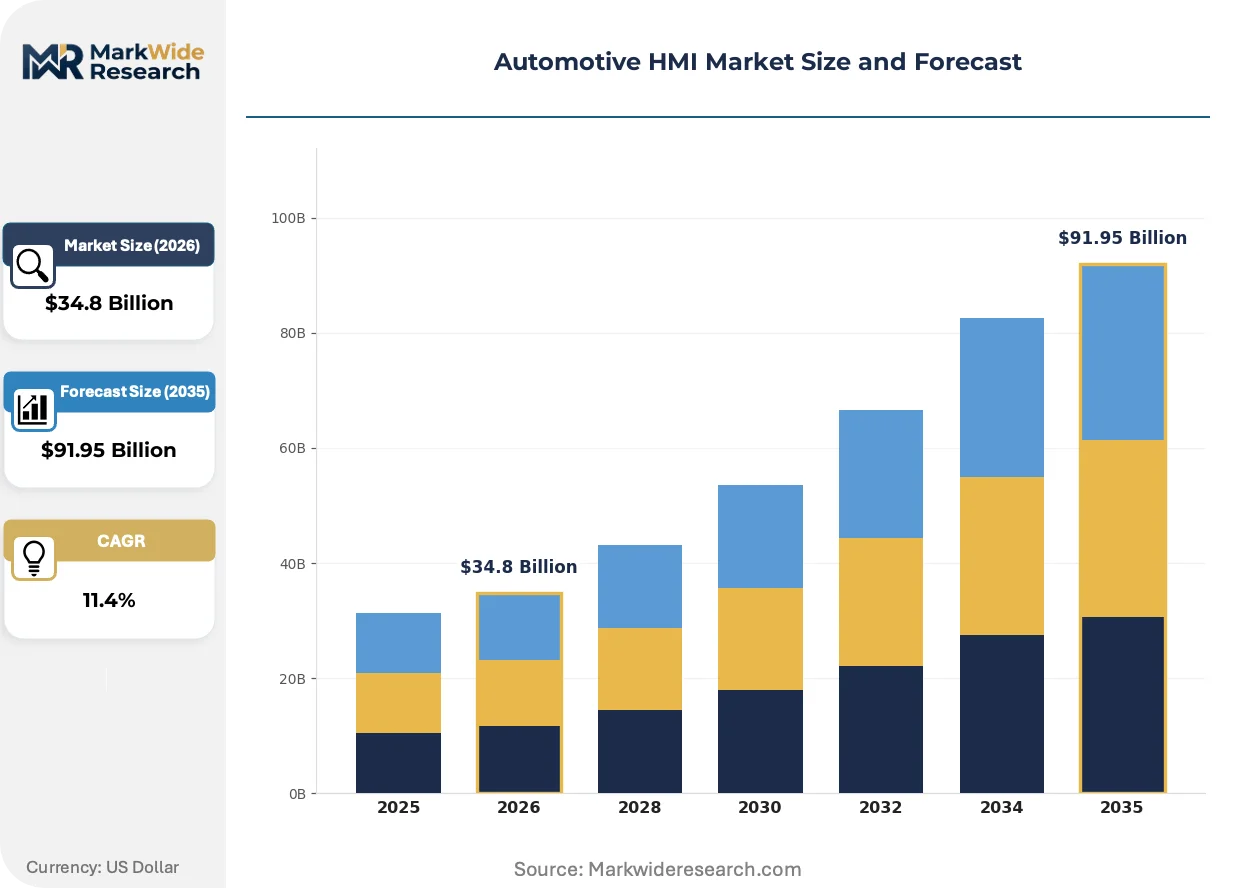
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $91.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Displays, Voice Recognition, Gesture Control, Heads-Up Display, Instrument Cluster, Central Information Display Technology: Capacitive, Resistive, Optical, Infrared, Ultrasonic, Haptic Feedback Application: Driver Assistance, Navigation, Entertainment, Climate Control, Vehicle Monitoring, Communication End User: OEMs, Tier-1 Suppliers, Aftermarket Installers, Vehicle Assemblers, Fleet Operators, Rental Services |
| Companies Covered | Visteon Corporation, Aptiv, Continental AG, Alpine Electronics Inc., Panasonic Holdings Corporation, Robert Bosch GmbH, Harman International, Valeo, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive HMI Market Strategic Shifts & Innovations
The convergence of consumer electronics user experience expectations with automotive-grade safety requirements is driving innovation across the HMI development stack. This dynamic forces suppliers to master both sophisticated software integration and safety-critical hardware design to remain competitive.
System-on-Chip (SoC) based domain controllers serve to consolidate processing for multiple in-vehicle functions, including the instrument cluster, infotainment, and ADAS visualization. Automotive OEMs in premium and electric vehicle segments are rapidly adopting this centralized architecture to reduce hardware complexity and cost. This technological consolidation is collapsing the previously distinct hardware and software design silos, forcing HMI development into a more integrated, system-level discipline.
New regulations from the United Nations, specifically UNECE R155 for cybersecurity and R156 for software updates, are directly influencing HMI architecture. These mandates require automakers to implement certified management systems for cyber threats and ensure secure over-the-air (OTA) update capabilities. The HMI software and its underlying operating system are most affected, as suppliers must now deliver solutions that are not only feature-rich but also secure, auditable, and updatable for the vehicle's entire lifecycle.
Automaker procurement patterns are evolving from sourcing individual components toward acquiring fully integrated digital cockpit systems from a single Tier-1 supplier. This shift away from a multi-vendor model for the display, cluster, and head unit favors large system integrators who can manage the immense software complexity. This behavior is most visible among new EV manufacturers and established OEMs in China aiming to accelerate development and de-risk system integration.
Automotive HMI Market Segmentation
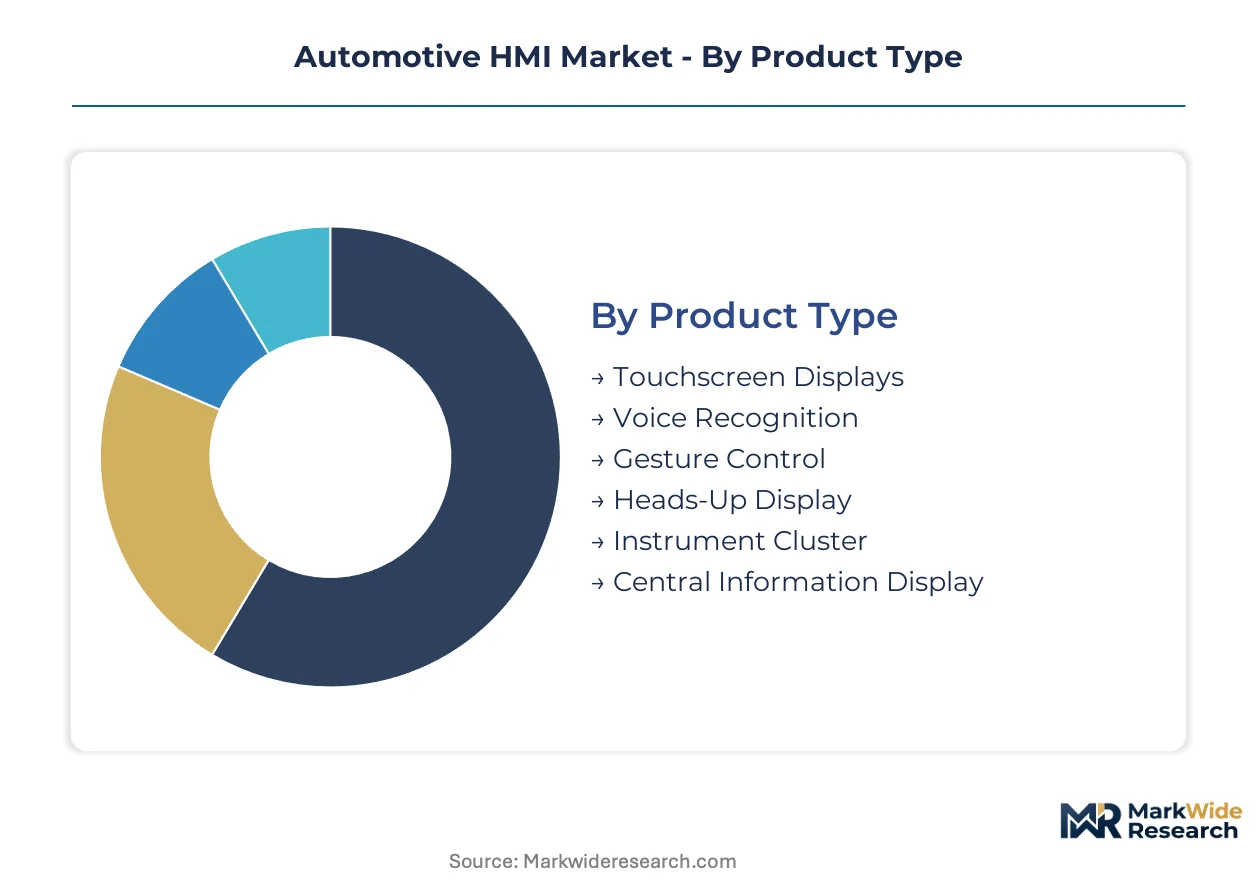
The Automotive HMI market is categorized across several dimensions, each revealing distinct commercial dynamics and technological requirements for suppliers. Understanding these segments is crucial for identifying areas of concentrated investment and emerging opportunities within the vehicle ecosystem.
Product Type:
The Automotive HMI market's product lifecycle varies significantly, with some interfaces experiencing rapid innovation cycles while others maintain longer design stability.
- Touchscreen Displays:These interactive input/output devices utilize capacitive technology for multi-touch gestures and often incorporate haptic feedback. Demand concentrates in electric vehicle manufacturers in China, driven by consumer electronics convergence.
- Instrument Cluster:This digital display provides critical driving information, often reconfigurable and integrated with ADAS data. OEM investment is substantial as these systems consolidate into centralized domain controllers.
- Voice Recognition:This system allows drivers to control vehicle functions and access information using spoken commands.
- Gesture Control:Utilizing sensors to interpret hand movements for interface interaction, this feature represents a premium offering.
- Heads-Up Display:Projecting information onto the windshield, HUDs reduce driver distraction by keeping essential data in view.
- Central Information Display:This large-format screen manages infotainment, navigation, and vehicle settings.
Instrument Clusters anchor the volume base while Gesture Control gains share at the steepest rate.
Technology:
Technology segmentation reveals distinct cost tiers, influencing adoption rates across different vehicle segments.
- Capacitive:This widely adopted touch technology senses electrical changes from finger contact, enabling multi-touch responsiveness. Demand is prevalent across all vehicle segments, forming the backbone for modern HMI.
- Haptic Feedback:Integrating tactile sensations into touch interfaces, this technology provides physical confirmation for user inputs. Premium vehicle manufacturers adopt haptic feedback to differentiate cockpit solutions.
- Resistive:Comprising multiple layers that register pressure, resistive touchscreens offer durability in rugged applications.
- Optical:Employing infrared sensors to detect touch, optical technology supports larger display sizes and design flexibility.
- Infrared:This technology uses infrared light beams to detect touch, suitable for larger, bezel-less displays.
- Ultrasonic:Utilizing sound waves to create tactile sensations, ultrasonic technology enables advanced haptic effects.
Capacitive technology forms the foundational layer, with Haptic Feedback expanding most quickly.
Application:
HMI applications are tailored to specific user priorities, ranging from critical safety functions to convenience features.
- Driver Assistance:HMI systems for driver assistance communicate ADAS status, warnings, and system interventions. Investment is driven by safety mandates and semi-autonomous driving complexity.
- Navigation:These applications provide turn-by-turn directions, traffic information, and points of interest, integrated with displays. Consumer demand for seamless, real-time navigation fuels continuous development.
- Entertainment:HMI for entertainment manages audio, video, and streaming services for vehicle occupants.
- Climate Control:This application integrates HMI elements to adjust cabin temperature and air distribution.
- Vehicle Monitoring:HMI for vehicle monitoring displays critical operational data such as tire pressure and diagnostic alerts.
- Communication:This application facilitates hands-free calling, messaging, and connectivity services for convenience and safety.
Navigation remains a core HMI function, while Driver Assistance applications are climbing the fastest.
End User:
The end-user landscape illustrates distinct supply chain dynamics, with direct procurement dominating initial vehicle integration.
- OEMs:Original Equipment Manufacturers directly integrate HMI systems into new vehicles, driving demand for complete cockpit solutions. Their procurement patterns shift towards single-source Tier-1 suppliers.
- Tier-1 Suppliers:These companies develop and supply integrated HMI modules and systems directly to OEMs, undertaking significant R&D and integration. Continental AG and Visteon exemplify this segment.
- Aftermarket Installers:These entities provide HMI upgrades and replacements for vehicles post-sale, focusing on infotainment.
- Vehicle Assemblers:Companies focused on vehicle assembly integrate HMI components sourced from various suppliers.
- Fleet Operators:Businesses managing commercial vehicle fleets require robust HMI systems for telematics, navigation, and diagnostics.
- Rental Services:Rental companies equip their vehicles with user-friendly HMI features for navigation.
OEMs represent the largest end-user segment, with Fleet Operators showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences the Automotive HMI market across key geographies. Electric vehicle manufacturers in China drive substantial demand for advanced HMI solutions, pushing innovation in user experience. This focus on integrated, software-defined cockpits reshapes investment priorities globally.
China
Chinese EV manufacturers demand cutting-edge HMI systems, emphasizing digital cockpits and advanced connectivity. MIIT guidelines for data security and connectivity shape HMI software architecture and over-the-air update capabilities. In the Yangtze River Delta, major EV players and tech firms collaborate on next-generation HMI development.
Germany
German premium automotive OEMs require sophisticated HMI solutions to support advanced driver-assistance systems and luxurious cabin experiences. UNECE regulations, particularly R155 for cybersecurity, mandate robust HMI system security and lifecycle management. Automotive clusters in Bavaria, including Munich, concentrate HMI R&D and component supply for global markets.
United States
American consumers seek smartphone-like fluidity and intuitive interfaces within their vehicles, driving demand for large-format displays. NHTSA safety standards directly influence fundamental HMI design principles to minimize driver distraction. Silicon Valley tech hubs and Detroit-area automotive suppliers collaborate on HMI software and user experience innovations.
Japan
Japanese automakers focus on highly reliable and integrated HMI systems, prioritizing advanced navigation and driver information. METI initiatives and JIS standards promote quality and functional safety in HMI component manufacturing. The Kanto region, including Tokyo, serves as a hub for HMI technology development and supply chain integration.
South Korea
South Korean automotive brands rapidly integrate advanced display technologies and voice recognition into their HMI offerings. KCC regulations guide the development of connected HMI systems, ensuring robust communication standards. The Seoul Capital Area hosts major automotive R&D centers pushing boundaries in HMI design and functionality.
Automotive HMI Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the Automotive HMI sector. The market structure shifts towards integrated solutions, favoring large Tier-1 suppliers capable of delivering complete digital cockpits. Strategic partnerships between hardware providers and software developers emerge as a dominant competitive move. Significant R&D investment focuses on software complexity and functional safety compliance.
Among the system integrators, Continental AG exemplifies a company leveraging deep systems integration expertise to deliver complete, pre-validated cockpit solutions directly to global automakers. Visteon Corporation occupies a position specializing in digital instrument clusters and large-format display technologies, optimized for the new centralized domain controller architecture. Robert Bosch GmbH anchors the underlying supply chain by providing a broad portfolio of essential hardware, software, and critical semiconductor components. These established players represent distinct archetypes within the evolving HMI ecosystem, each adapting their offerings to meet the demand for integrated, software-defined vehicle cockpits. Their strategic focus on comprehensive solutions or foundational components shapes the competitive dynamics.
| Leading Market Players |
|---|
| Visteon Corporation |
| Aptiv |
| Continental AG |
| Alpine Electronics Inc. |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| Harman International |
| Valeo |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Concentrated supply of high-performance System-on-Chip (SoC) processors from a few key manufacturers dictates margin pools for Tier-1 HMI system integrators. This upstream concentration creates both pricing power for component suppliers and integration challenges for vehicle manufacturers.
Pricing Analysis
Long-term contract-based offtake agreements with named indexation for semiconductor components define the HMI market's pricing model. Price differentiation stems from software complexity and functional safety certification (ISO 26262 ASIL levels). Cost compression intensifies due to OEM demands for integrated, cost-effective cockpit solutions. New electric vehicle manufacturers are less price-sensitive for advanced features, while established OEMs are more sensitive to non-recurring engineering costs.
Supply Chain Analysis
Single-source vulnerability for advanced semiconductor components represents a significant supply chain risk. Geographic supply concentrates heavily in Taiwan, South Korea, and China for high-performance SoCs and automotive-grade display panels. The market relies on these regions for critical raw materials and component dependencies like specialized display glass and processing units. Distribution functions through direct supply from Tier-1 integrators to Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
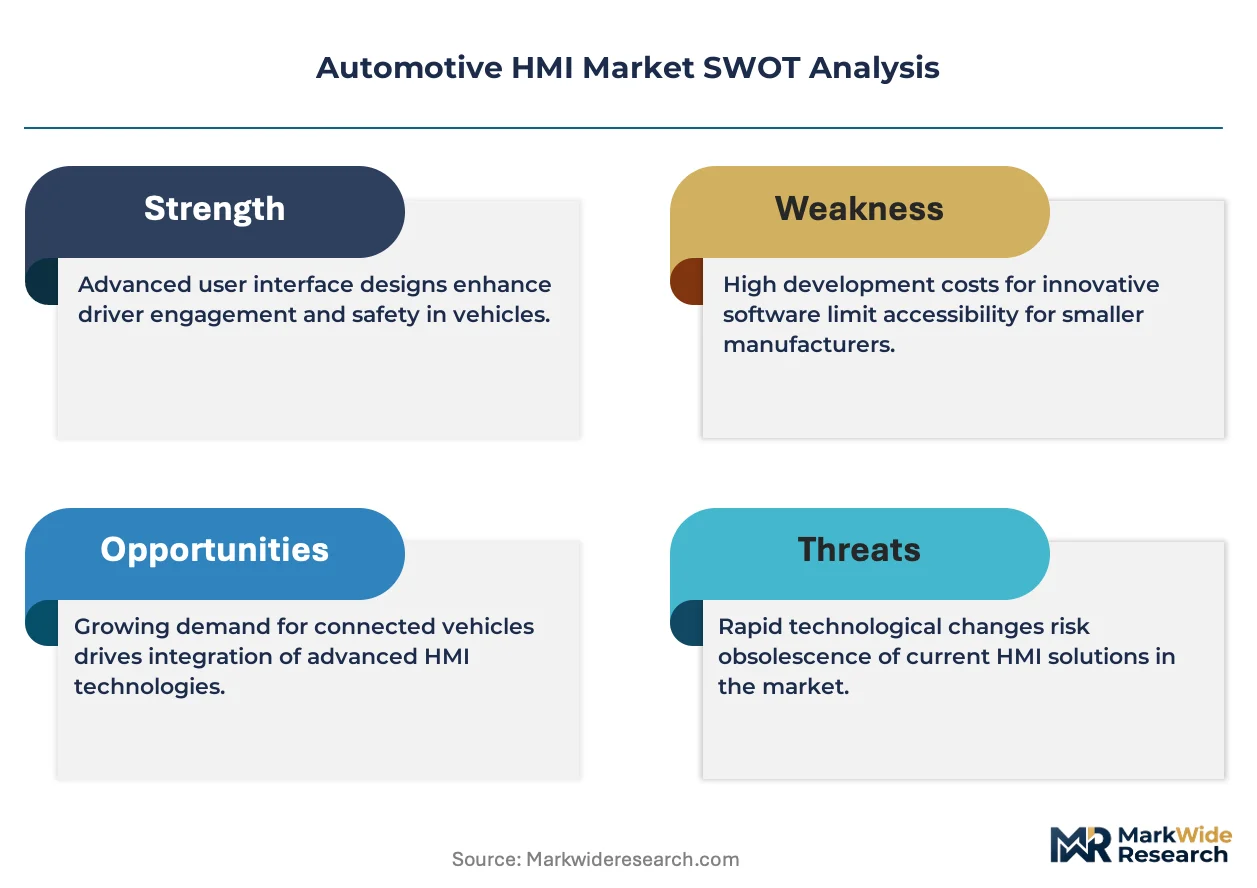
The Automotive HMI market is in a cyclical recovery driven by renewed automotive investment in software-defined vehicle architectures. This shift accelerates demand for advanced digital cockpits and integrated HMI solutions.
For Market Incumbents: Harden software integration capabilities and invest in robust cybersecurity compliance frameworks. This defends against emerging software-centric vehicle manufacturers and stringent UNECE R155 regulations. Vertical integration into critical software stacks and strategic partnerships for UX/UI design talent are essential levers. Leverage existing OEM relationships to offer complete, pre-validated cockpit solutions.
For New Entrants and Emerging Players: Pursue niche applications in commercial vehicle telematics or specialized augmented reality Head-Up Display solutions. The underpenetrated fleet operator segment in North America offers significant white-space opportunity. Offer highly customizable, ruggedized HMI systems with integrated diagnostics as a specific go-to-market angle. Focus on specific functional needs rather than broad infotainment systems.
For Investors and Strategic Acquirers: Capital is best deployed toward software-defined vehicle platform providers or specialized HMI UX/UI design firms. Market viability remains strong over the next decade due to ongoing vehicle electrification and digitalization trends. The rate of OEM adoption of standardized software platforms serves as a key inflection indicator to watch. Seek companies with strong intellectual property in secure software architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Consolidates in-house expertise for future HMI platforms and enhances system flexibility. |
| Cybersecurity Certification Program | Ensures compliance with UNECE R155 and builds customer trust in connected HMI systems. |
| UX/UI Design Studio Acquisition | Enhances user experience capabilities for next-generation interfaces demanded by consumers. |
| Advanced Display Technology Partnership | Secures access to cutting-edge large-format and augmented reality Head-Up Display panels. |
| Commercial Vehicle HMI Platform Launch | Taps into an underserved market segment with specific functional and telematics needs. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through public data. Primary research involved discussions with OEM platform engineers, Tier-1 procurement leads, HMI software architects, and automotive UX designers. Secondary sources included vehicle production databases, IHS Markit registration data, SEC 10-K filings, and regulatory body publications from NHTSA and UNECE. Bottom-up and top-down triangulation verified market sizing and growth projections.
Vehicle electrification rates, ADAS penetration, and software-defined vehicle adoption were key forecast inputs considered for this study. A robust analytical framework modeled market dynamics across the analysis window, segmenting by product type, technology, application, end-user, and vehicle class. Compound annual growth rates were derived from historical trends and projected technological advancements in HMI components and software integration.
Macroeconomic conditions sit as an overlay; deviation in global vehicle production or consumer spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and supply chain resilience. Geopolitical events and semiconductor supply disruptions pose specific risk factors for forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market