
 Africa and Middle East Automotive Camera Market | 2026-2036
Africa and Middle East Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Automotive Camera Market Outlook
AI-powered image signal processing is rewriting the automotive camera value chain across Africa and the Middle East, compressing development cycles from hardware-centric to software-defined architectures. Robert Bosch GmbH leverages its Tier-1 integration depth to dominate ADAS camera supply for European OEMs assembling vehicles in Morocco and South Africa. Continental AG anchors regional production through its manufacturing footprint in Tunisia, sustaining cost competitiveness for surround-view modules. Valeo SA specializes in thermal imaging solutions, positioning its Night Vision product line for premium SUV demand in the UAE and Saudi Arabia.
An automotive camera is a vehicle-mounted vision sensor that captures optical images through lens-and-sensor assemblies, typically employing CMOS imagers with resolution thresholds from 1.2 to 8 megapixels, to enable driver assistance, parking guidance, and autonomous navigation functions. The technology serves as the perceptual backbone for lane-keeping, collision avoidance, and pedestrian detection systems that insurance underwriters increasingly mandate for fleet coverage. Rearview cameras lead unit shipments across the product type dimension, though 360-degree camera systems command superior margin pools as luxury automakers bundle them into standard equipment packages. CMOS technology displaces legacy CCD architectures across the technology dimension, driven by lower power draw and superior low-light performance that suits Middle Eastern desert operating conditions. Fleet operators represent the fastest-growing end user category, as logistics companies in Egypt and Nigeria deploy camera systems to satisfy international supply chain audit requirements and reduce accident-related downtime costs.
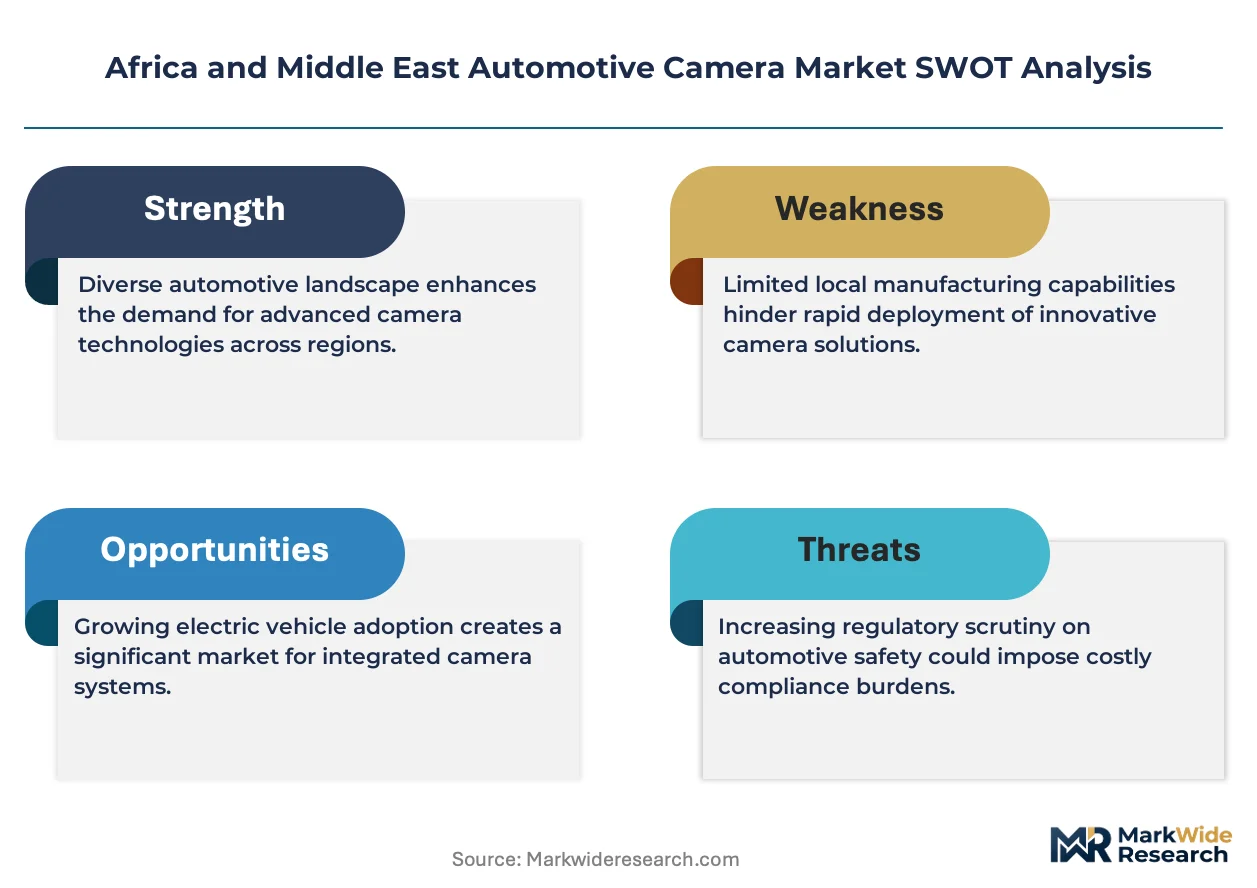
Saudi Arabia's SASO and the UAE's ESMA enforce divergent homologation timelines for camera-based safety systems, creating compliance complexity for suppliers serving both markets. Egypt's GOEIC import inspection protocols add certification layers that extend lead times for aftermarket camera distributors. South Africa's NRCS applies SANS automotive standards that align partially with UNECE regulations but retain local testing mandates. Stakeholders must monitor regulatory harmonization negotiations between Gulf and North African frameworks, as misaligned certification requirements threaten to fragment procurement scale and inflate per-unit compliance expenditure.
Market Dynamics
AI-powered image signal processing is compressing development cycles across the Africa and Middle East automotive camera market, shifting value capture from hardware suppliers to software-defined architecture providers. Fleet operators in Saudi Arabia and the UAE now mandate camera installations to satisfy insurance underwriters and reduce liability exposure, creating concentrated procurement pull along the Gulf Cooperation Council corridor.
Growth Catalysts
- SASO technical regulations:Saudi Arabia's vehicle safety mandates accelerate OEM compliance timelines for ADAS camera integration.
- Fleet insurance requirements:Logistics operators across Egypt and Nigeria deploy camera systems to satisfy international supply chain audit standards.
- Smart city infrastructure:Premium vehicle penetration in Dubai and Abu Dhabi generates concentrated demand for surround-view modules.
Market Restraints
- CMOS sensor supply concentration:Dependence on East Asian semiconductor foundries exposes regional assemblers to input volatility and extended lead times.
- Divergent homologation frameworks:Misaligned certification timelines between Saudi SASO and UAE ESMA fragment procurement scale and inflate per-unit compliance expenditure.
- Desert thermal degradation:Extreme operating temperatures in Gulf states accelerate lens coating deterioration and sensor drift, compressing replacement cycles.
Strategic Opportunities
- Underpenetrated East African corridors:Ethiopia and Kenya present white space for aftermarket camera distributors as commercial vehicle fleets modernize.
- Thermal imaging convergence:Night vision integration with pedestrian detection algorithms addresses premium SUV demand in Saudi Arabia's low-light desert driving conditions.
- Digital retail channels:E-commerce platforms bypass traditional aftermarket distributor networks in South Africa, capturing margin from direct-to-installer sales.
Industry Challenges
- Embedded vision engineering scarcity:Shortage of firmware developers skilled in edge AI optimization for CMOS architectures constrains local R&D expansion.
- UNECE R79/R157 alignment gaps:South Africa's NRCS retains local testing mandates that extend certification timelines for lane-keeping and automated steering camera systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Automotive Camera Market |
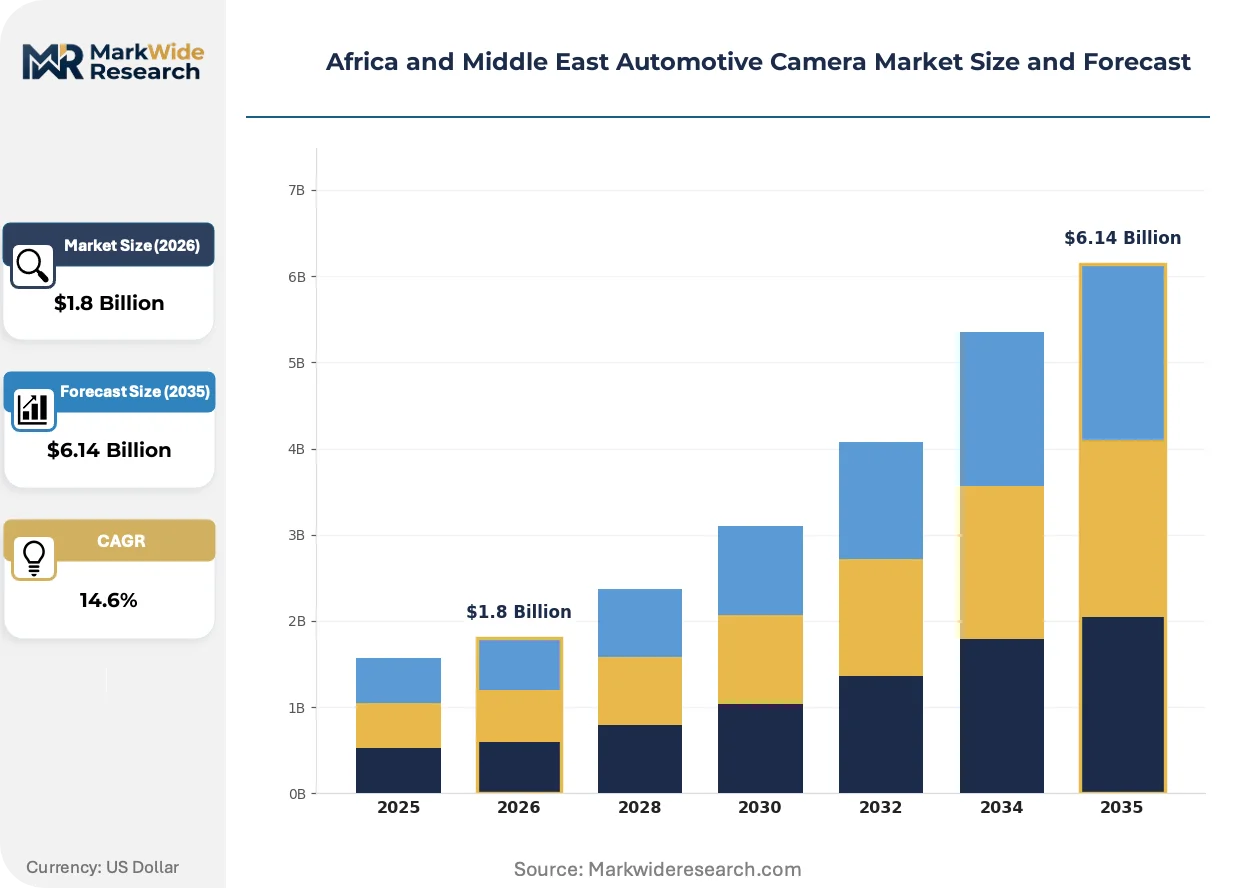
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Camera, Surround View Camera, Front Camera, 360-Degree Camera End User: OEMs, Aftermarket Suppliers, Dealerships, Fleet Operators Technology: CCD, CMOS, Infrared, Thermal Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, ADAS |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Panasonic Corporation, Magna International Inc, Valeo SA, Autoliv Inc, ZF Friedrichshafen AG, Gentex Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Automotive Camera Market Strategic Shifts
Software-defined architectures are rewriting competitive positioning across the Africa and Middle East automotive camera value chain. Three concurrent developments are compressing traditional hardware margins while opening new service revenue pools for integrated system providers.
Neural network-based image signal processing is rendering obsolete fixed-function ISP pipelines in ADAS camera modules. Tier-1 suppliers serving Moroccan and South African assembly plants now deploy programmable vision processors that enable over-the-air algorithm updates. This shift transfers value from discrete component vendors to firmware-integrated platform providers.
SASO's accelerated homologation timeline for camera-based safety systems diverges from UAE ESMA implementation schedules. Suppliers serving both markets must maintain dual certification tracks, fragmenting engineering resources and extending product validation cycles. Fleet operators in the Gulf Cooperation Council corridor face procurement delays as manufacturers reconcile conflicting technical documentation requirements.
Fleet procurement teams now bundle camera hardware with telematics analytics and driver behavior scoring. Logistics companies in Egypt and Nigeria negotiate outcome-based contracts that tie equipment payments to accident reduction metrics. This unbundles traditional equipment sales from service revenues, compressing upfront hardware margins while extending customer lifetime value for integrated platform vendors.
Africa and Middle East Automotive Camera Market Segmentation
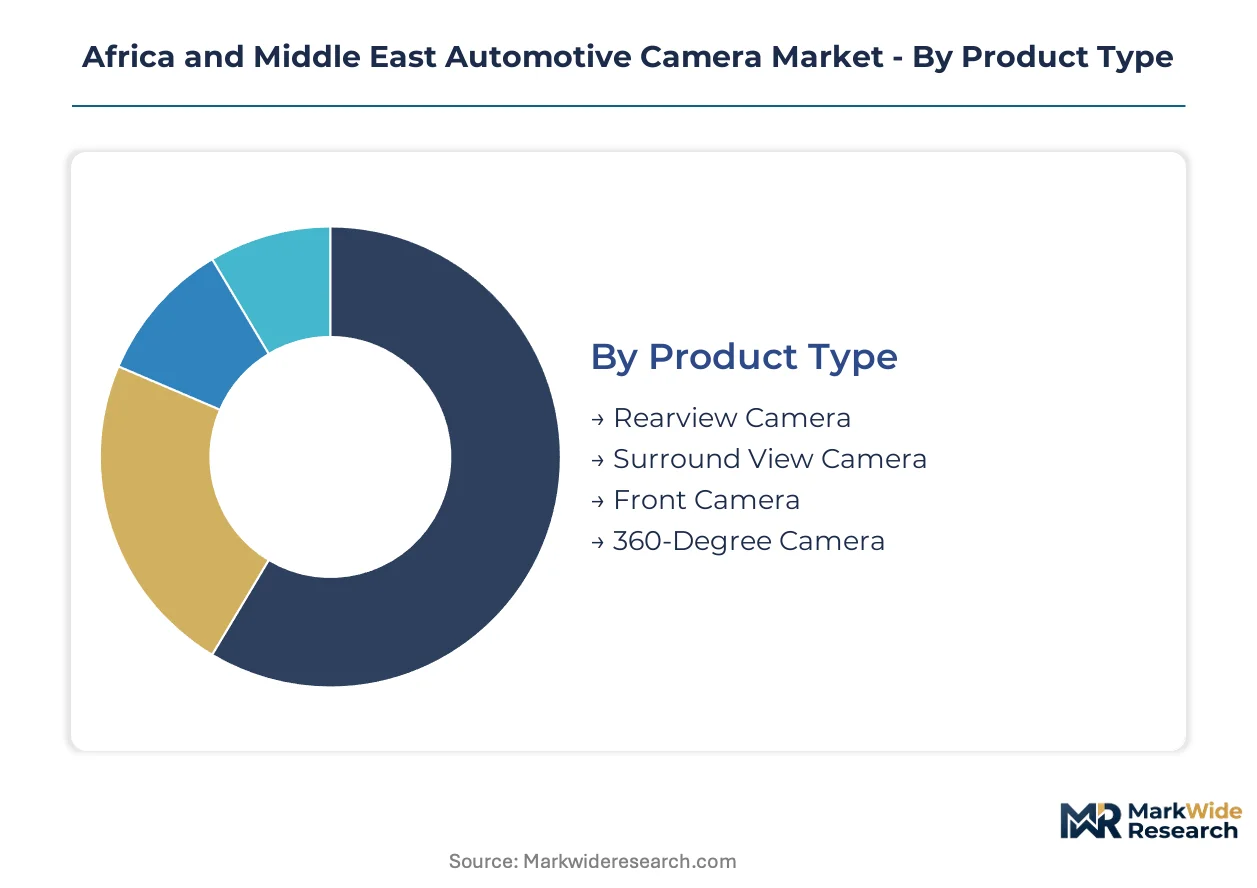
Camera module specifications diverge sharply across African and Middle Eastern operating environments, where desert thermal stress and fleet insurance mandates create distinct procurement priorities. Segmentation clarity enables suppliers to align sensor architectures with replacement cycles and compliance requirements.
Product Type:
Rearview cameras turn over fastest due to universal regulatory mandates, while 360-degree systems exhibit extended replacement cycles tied to luxury vehicle ownership periods.
- Rearview Camera:Single-lens modules with 1.2-2 megapixel resolution dominate unit economics. Fleet operators in Egypt and Nigeria deploy these for insurance compliance, accepting shorter replacement intervals to minimize liability exposure.
- 360-Degree Camera:Multi-sensor fusion architectures integrate four to six discrete imagers with stitched image processing. Premium SUV demand in Dubai and Abu Dhabi concentrates procurement pull, with surround-view modules bundling into standard equipment packages.
- Surround View Camera:Parking assistance systems with bird's-eye rendering capability serve mid-tier vehicle segments.
- Front Camera:Lane-keeping and collision avoidance sensors with extended focal lengths support ADAS functionality.
Rearview cameras anchor the volume base while 360-degree cameras gain share at the steepest rate.
End User:
Procurement authority concentrates differently across cost tiers, with fleet operators extracting volume discounts unavailable to fragmented retail channels.
- Fleet Operators:Logistics companies in Saudi Arabia and the UAE negotiate outcome-based contracts tying equipment payments to accident reduction metrics. International supply chain audit requirements drive centralized procurement at scale.
- OEMs:Vehicle manufacturers integrate camera modules during assembly, with SASO compliance timelines accelerating ADAS adoption for Saudi-bound production.
- Aftermarket Suppliers:Independent distributors serve replacement demand and vehicle retrofitting across North African corridors.
- Dealerships:Authorized service networks capture premium installation revenue for warranty-backed camera systems.
OEMs anchor the volume base while fleet operators expand most quickly.
Technology:
Sensor architecture selection tracks margin stratification, with specialized thermal imagers commanding price multiples over commodity CMOS designs.
- CMOS:Complementary metal-oxide-semiconductor imagers displace legacy architectures through lower power draw and superior low-light sensitivity. Desert operating conditions in Gulf states favor CMOS durability against thermal degradation.
- Thermal:Infrared focal plane arrays detect pedestrian heat signatures without visible light. Night vision integration addresses premium SUV demand in Saudi Arabia's low-light desert driving corridors.
- CCD:Charge-coupled device sensors retain niche applications where image uniformity outweighs power constraints.
- Infrared:Near-infrared enhanced imagers extend detection range for parking assistance in dust-laden environments.
CMOS anchors the volume base while thermal imaging climbs the fastest.
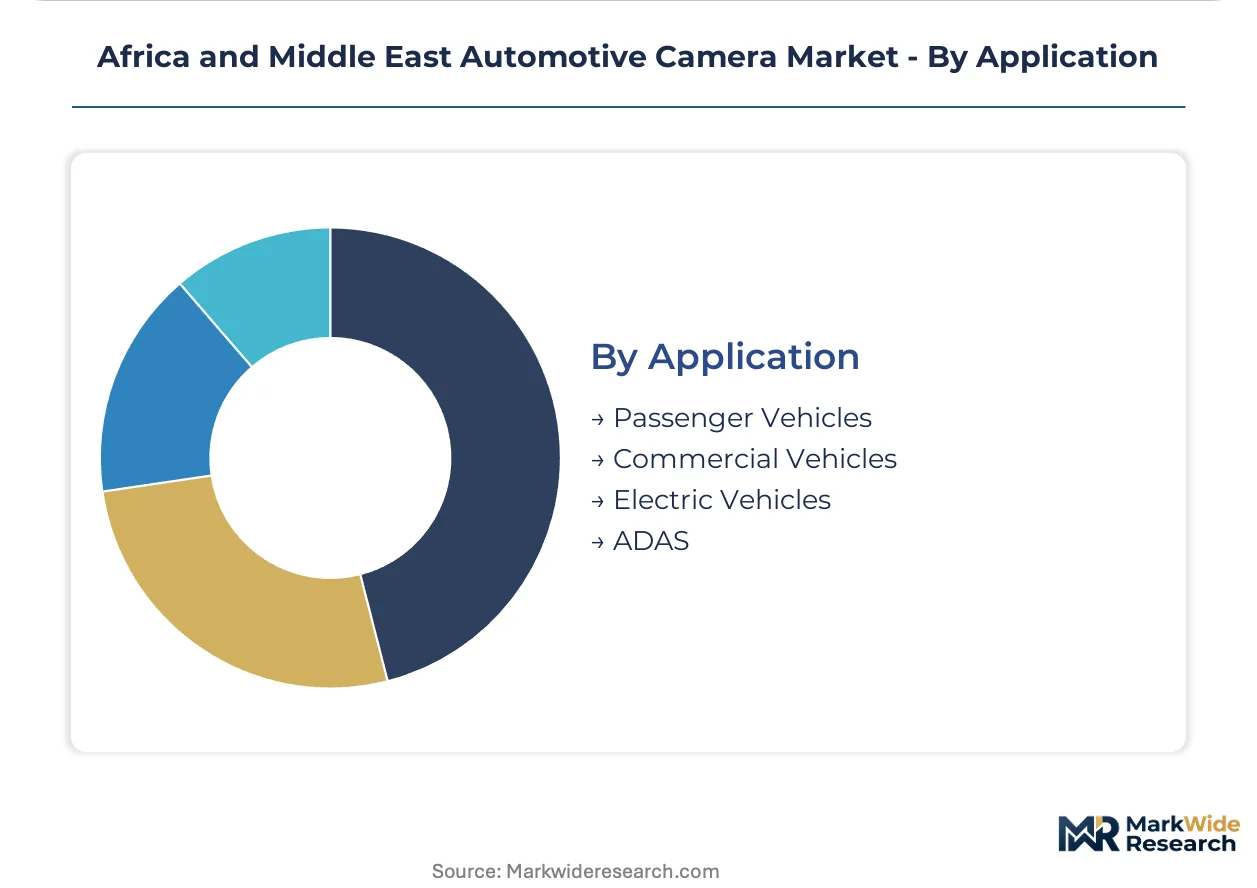
Application:
Vehicle electrification timelines and ADAS regulatory mandates create divergent growth trajectories across mobility categories.
- ADAS:Advanced driver assistance systems integrate multi-camera arrays for lane-keeping, adaptive cruise control, and automated emergency braking. SASO technical regulations accelerate OEM compliance timelines across Saudi Arabia.
- Commercial Vehicles:Heavy-duty trucks and buses deploy camera systems for blind-spot monitoring and driver fatigue detection. Fleet modernization in Ethiopia and Kenya presents white space for aftermarket distributors.
- Passenger Vehicles:Private automobile segments drive surround-view and parking camera penetration.
- Electric Vehicles:Battery-electric platforms integrate cameras for autonomous navigation and energy-efficient driver assistance.
Passenger vehicles anchor the volume base while ADAS gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan assembly plants export camera-equipped vehicles to European Union markets, while South African component manufacturers supply sub-Saharan aftermarket channels. This trade-flow configuration concentrates procurement authority in coastal manufacturing zones while inland logistics corridors drive replacement demand.
Saudi Arabia
Fleet operators in Riyadh and Jeddah mandate camera installations for insurance compliance, with heavy-duty trucks leading procurement volume. SASO technical regulations accelerate OEM compliance timelines for ADAS camera integration across all new vehicle categories. The Eastern Province industrial corridor hosts assembly plants supplying Gulf Cooperation Council markets with camera-equipped commercial vehicles.
United Arab Emirates
Premium SUV demand in Dubai and Abu Dhabi concentrates surround-view camera procurement into luxury vehicle packages. ESMA homologation requirements for camera-based safety systems diverge from Saudi timelines, fragmenting supplier certification efforts. Jebel Ali's logistics hub serves as the regional distribution node for aftermarket camera modules entering African markets.
South Africa
OEM assembly plants in Gauteng and Eastern Cape integrate camera modules for export to European and sub-Saharan markets. NRCS applies SANS automotive standards that align partially with UNECE regulations but retain local testing mandates for lane-keeping systems. Cape Town's aftermarket distribution networks supply replacement cameras to mining and logistics fleets across Southern Africa.
Egypt
Commercial vehicle fleets in Cairo and Alexandria deploy camera systems to satisfy international supply chain audit requirements. GOEIC import inspection protocols add certification layers that extend lead times for aftermarket camera distributors. The Suez Canal Economic Zone attracts logistics operators modernizing fleets with camera-based driver monitoring equipment.
Nigeria
Logistics companies in Lagos and Kano negotiate outcome-based contracts tying camera equipment payments to accident reduction metrics. The country's national automotive standards regulator maintains import documentation requirements that complicate aftermarket distributor supply chains. Port Harcourt's oil sector fleet operators drive demand for ruggedized camera systems in dust-laden operating conditions.
Africa and Middle East Automotive Camera Market Competitive Environment
On the supply side, the industry is consolidating around Tier-1 system integrators with manufacturing footprints in North Africa. Three strategic archetypes dominate: European-headquartered multinationals with Moroccan assembly integration, Japanese electronics conglomerates supplying CMOS sensor modules, and specialized thermal imaging developers targeting premium Gulf markets. Capacity expansion in Tunisian production facilities and strategic partnerships with local fleet operators constitute the dominant competitive moves.
Among European-headquartered Tier-1 suppliers, Robert Bosch GmbH, Continental AG, and Valeo SA exemplify the integrated system provider archetype. These entities anchor regional supply relationships through established manufacturing presences in Morocco and Tunisia. Their positioning reflects the shift from discrete component supply toward firmware-integrated platform provision across African and Middle Eastern automotive corridors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Panasonic Corporation |
| Magna International Inc |
| Valeo SA |
| Autoliv Inc |
| ZF Friedrichshafen AG |
| Gentex Corporation |
| Others |
Value Chain & Pricing Dynamics
East Asian CMOS foundry concentration in Taiwan and South Korea feeds margin compression downstream, where Tier-1 integrators in Morocco and Tunisia capture firmware value while discrete component vendors absorb sensor cost volatility. Fleet procurement teams in the Gulf Cooperation Council corridor exploit this asymmetry through outcome-based contracts that unbundle hardware from service revenues.
Pricing Analysis
Resolution-tier pricing gaps separate 1.2-megapixel rearview modules from 8-megapixel ADAS arrays and emerging thermal fusion architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with SASO-compliant systems commanding premiums over baseline aftermarket units. Pricing pressure stems from CMOS sensor supply bottlenecks that extend lead times for regional assemblers. Fleet operators in Egypt and Nigeria exhibit highest price sensitivity, while premium SUV buyers in Dubai absorb thermal imaging premiums without volume negotiation.
Supply Chain Analysis
Silicon wafer and lens glass feedstocks draw from Taiwan, South Korea, and Japan before reaching North African module assembly plants. CMOS sensors, polycarbonate housings, and ISP chipsets constitute critical input dependencies. Single-source vulnerability concentrates in East Asian semiconductor foundries exposed to geopolitical logistics chokepoints. Distribution runs through Jebel Ali's logistics hub for Gulf markets and Cape Town's aftermarket networks for sub-Saharan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa and Middle East automotive camera market sits in early-cycle expansion, with SASO regulatory mandates forcing ADAS penetration faster than replacement-cycle economics alone would justify.
For Market Incumbents: Harden firmware-integrated platform positioning against discrete component commoditization by deepening captive ISP development in Tunisian manufacturing facilities. Accelerate dual-track certification investments for SASO and ESMA convergence scenarios, as regulatory misalignment threatens to fragment procurement scale and dilute margin pools from integrated system sales. For New Entrants and Emerging Players: Pursue aftermarket thermal imaging distribution in Saudi Arabia's premium SUV segment, where Night Vision bundling remains underpenetrated relative to surround-view saturation in Dubai. Target white-space fleet modernization in Ethiopia and Kenya through direct-to-installer digital channels that bypass entrenched North African distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Tier-1 suppliers holding Moroccan assembly integration but lacking software-defined architecture capabilities. Five-to-ten-year viability hinges on firmware monetization transitions rather than hardware shipment volumes. Monitor ESMA-SASO harmonization negotiations as the signal for procurement consolidation and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Investment | Enables over-the-air algorithm updates that transfer value from hardware to firmware providers. |
| Dual Certification Track Maintenance | SASO and ESMA compliance investments hedge against regulatory fragmentation in Gulf markets. |
| Direct-to-Installer Digital Channel Launch | Bypasses traditional aftermarket distributors in South Africa to capture margin from installer relationships. |
| Thermal Imaging Product Line Extension | Addresses premium SUV demand in Saudi Arabia's low-light desert driving corridors. |
| Tunisian Manufacturing Footprint Expansion | Sustains cost competitiveness for surround-view modules serving European OEM assembly plants. |
Study Parameters
The analysis maps CMOS sensor architectures, thermal imaging modules, and software-defined vision processors, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operations managers. Primary interview insights triangulate against vehicle production databases, customs import records, SASO technical documentation, and UNECE regulatory filings. Bottom-up unit shipment estimates reconcile with top-down market value assessments across segmentation dimensions.
Fixed assumptions include sustained SASO enforcement timelines and current East Asian semiconductor supply configurations, while variable parameters incorporate regulatory harmonization scenarios and fleet electrification penetration rates. The projection horizon spans product type, technology generation, end-user category, and regional production cluster dimensions. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion, with content-per-vehicle trajectories and replacement cycle compression as automotive-specific calibration inputs.
Sensitivities concentrate around CMOS foundry capacity allocation shifts and Gulf regulatory harmonization outcomes. Forecasts reflect documented assumptions regarding SASO implementation adherence and fleet insurance mandate expansion. Material shifts in East Asian semiconductor export restrictions or ESMA-SASO timeline convergence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market