
 Global Automotive Holographic Display Market | 2026-2036
Global Automotive Holographic Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Holographic Display Market Analysis
Asian semiconductor foundry capacity is shifting toward automotive-grade photonics substrates as holographic display orders multiply. Samsung Electronics leverages its vertical LCD and OLED supply chain to dominate integrated cockpit module production. Continental AG anchors European demand through its embedded software and optical sensor platforms for instrument clusters. Texas Instruments sustains technology leadership in digital light processing chipsets that power laser projection head-up displays across multiple OEM programs.
Automotive holographic displays project three-dimensional imagery into the driver's sightline without requiring wearable optics, typically operating at luminance levels exceeding 15,000 cd/m² for daylight readability. These systems merge spatial light modulation with real-time vehicle telemetry to reduce cognitive load during navigation and hazard alerting. Head-up displays occupy the largest revenue pool among product types due to safety mandates and OEM bundling with advanced driver assistance packages. Laser projection technology leads growth within the technology dimension because its infinite depth of field eliminates focal plane adjustment. Luxury brands within the end-user segment command premium positioning as they absorb first-generation costs before economies of scale reach mass-market OEMs.
FDA guidance on visual ergonomics for automotive displays intersects with NHTSA distraction-reduction rules to establish minimum field-of-view and refresh-rate thresholds for holographic systems sold in the United States. ECE Regulation 125 in Europe governs installation and performance of driver information displays, while Japan's METI promotes domestic holographic component production through automotive technology roadmaps. Stakeholders must monitor divergence between regional photometric standards and the pace at which tier-1 suppliers can qualify multi-territory optical platforms without fragmenting their engineering resources.
Market Dynamics
OEM procurement of holographic head-up displays is accelerating as augmented reality interfaces migrate from concept vehicles into premium production lines, while the EU Green Deal and NHTSA distracted-driving penalties force suppliers toward certification-grade optical systems.
Growth Catalysts
- NHTSA Distraction-Reduction Rules:Stricter penalties for driver inattention are compelling automakers to integrate holographic head-up displays that project navigation and hazard alerts directly into the sightline without requiring gaze diversion.
- Laser Projection Technology:Its infinite depth of field eliminates focal plane adjustment latency, enabling real-time augmentation of road geometry that static HUDs cannot match.
- Germany-Japan-US Cluster Concentration:Overlapping automotive electronics clusters and tier-1 supplier headquarters in these three countries create dense innovation ecosystems where holographic component qualification cycles compress.
Market Restraints
- Automotive-Grade Photonics Substrate Costs:Semiconductor foundry capacity reallocation toward automotive photonics is tightening supply of indium phosphide and gallium nitride wafers, inflating bill-of-materials for spatial light modulators.
- Multi-Territory Optical Platform Fragmentation:Divergence between FDA visual ergonomics guidance, ECE Regulation 125 photometric standards, and Japan's METI roadmaps forces tier-1 suppliers to engineer region-specific variants rather than unified global modules.
- Daylight Readability Thresholds:Sustained luminance above 15,000 cd/m² for sunlit conditions demands thermal management systems that add mass and complexity to instrument cluster integration.
Strategic Opportunities
- Mass-Market OEM Absorption:Luxury brands currently absorb first-generation holographic display costs, creating a pricing ladder for tier-2 manufacturers to adopt scaled-down laser projection units as volumes amortize development.
- EU Green Deal Certification Incentives:Carbon footprint disclosure requirements for automotive electronics are favoring suppliers with vertically integrated European photonics manufacturing over import-dependent competitors.
- Real-Time Telemetry Convergence:Merging spatial light modulation with vehicle-to-everything (V2X) communication protocols opens augmented reality hazard alerting that transcends conventional sensor fusion architectures.
Industry Challenges
- Optical Engineer Talent Scarcity:The intersection of wave optics, automotive thermal management, and real-time rendering requires specialists rarely cultivated in standard photonics or automotive engineering programs.
- ISO 26262 Functional Safety Certification:Holographic displays classified as safety-critical driver information systems must achieve ASIL-B or higher ratings, extending validation timelines by 18-24 months.
- Legacy Instrument Cluster Integration:Mechanical gauge architectures in existing vehicle platforms resist seamless retrofit of holographic projection modules without dashboard redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Holographic Display Market |
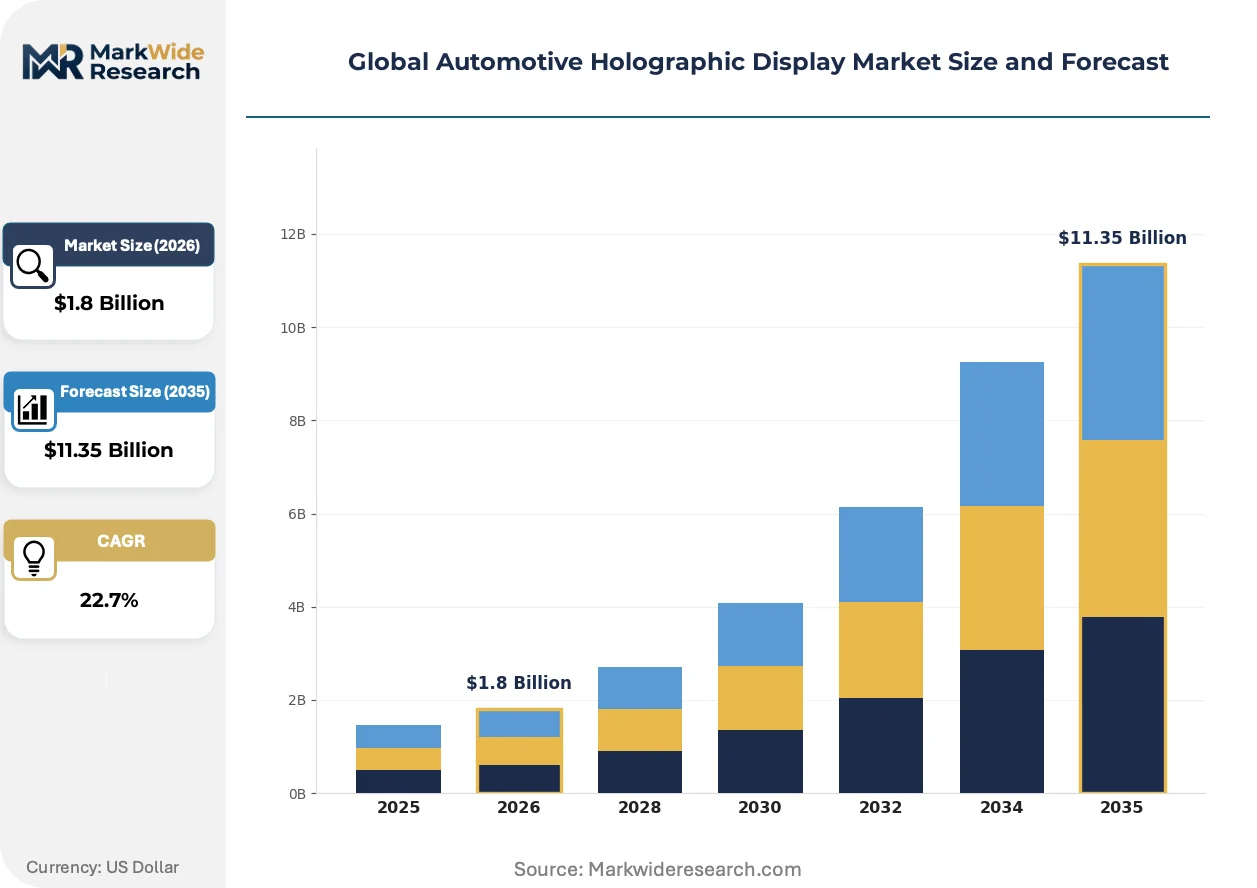
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Displays, Instrument Clusters, Rear-Seat Entertainment, Augmented Reality Displays Technology: Laser Projection, Digital Light Processing, LCD, OLED End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Luxury Brands Integration Level: Standalone Systems, Integrated Systems, Modular Solutions, Custom Solutions |
| Companies Covered | Samsung Electronics Co., Ltd., CY Vision, Texas Instruments Inc., Himax Technologies, Inc., Continental AG, NXP Semiconductors N.V., Renesas Electronics Corporation, Hyundai Mobis Co., Ltd., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Holographic Display Market Emerging Trajectories
Spatial light modulation hardware is merging with augmented reality software stacks to compress the latency between sensor detection and visual overlay, fundamentally altering how drivers process critical information.
Laser projection head-up displays are rewriting the competitive landscape for instrument cluster suppliers by eliminating the focal plane limitations that constrain conventional LCD and DLP-based systems. Luxury OEMs are adopting these modules at twice the pace of mass-market brands, compressing the technology cost curve and forcing tier-1 suppliers to choose between premium positioning and volume scale.
ECE Regulation 125 in Europe governs installation geometry and luminance uniformity for driver information displays, creating a compliance moat that favors established optical houses with existing homologation laboratories. The regulation's field-of-view minimums are accelerating windshield-integrated waveguide development while disqualifying aftermarket projection units from type approval.
Automotive electronics procurement is consolidating around integrated cockpit module contracts that bundle holographic displays with instrument clusters and infotainment controllers. German and Japanese OEMs are leading this consolidation, pressuring suppliers to absorb integration risk and warranty liability that previously sat with discrete component vendors.
Global Automotive Holographic Display Market Segmentation
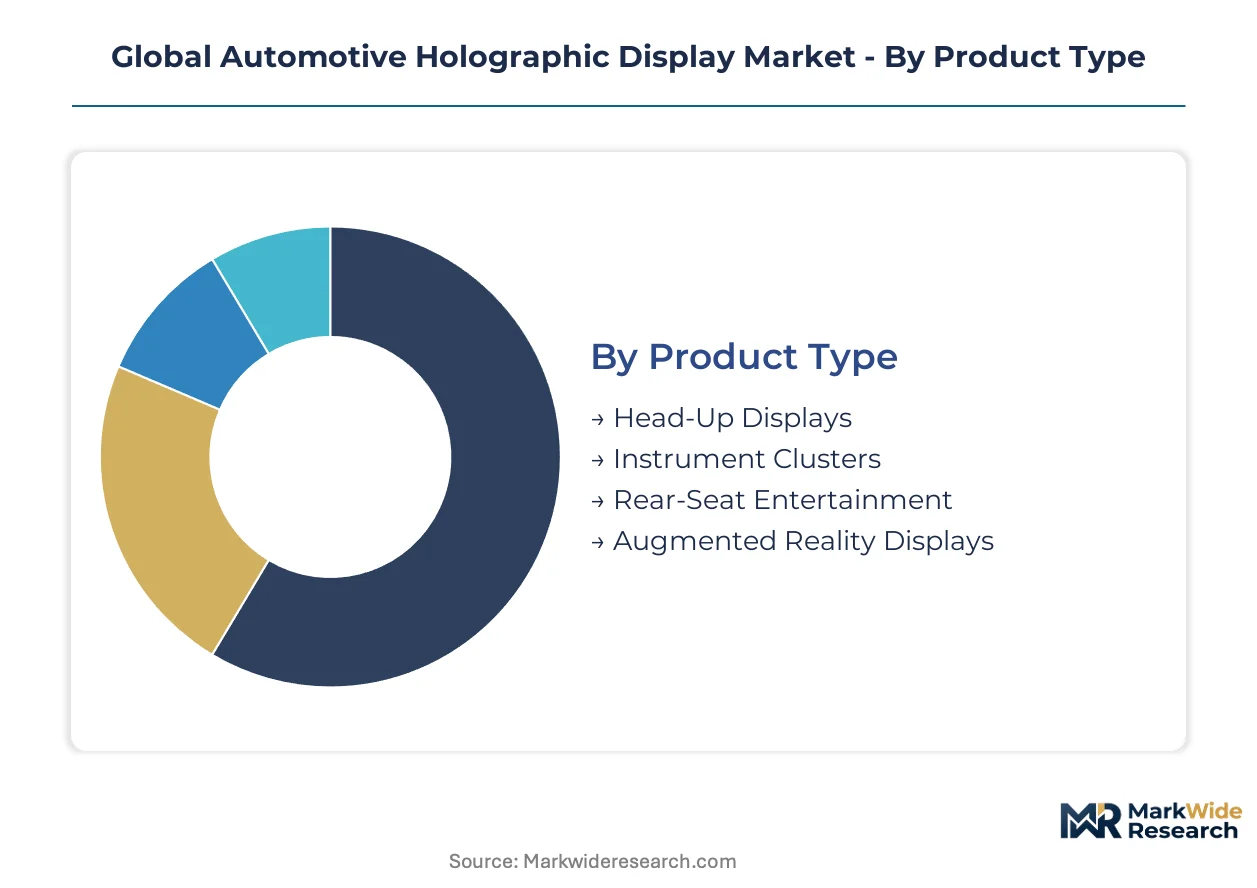
Segmentation in automotive holographic displays reveals how technical specifications, procurement hierarchies, and integration architectures fragment into distinct commercial battlegrounds. Each dimension carries divergent margin profiles, certification requirements, and supplier qualification barriers that reshape competitive positioning across the value chain.
Product Type:
Customization intensity varies sharply across this category, from standardized windshield projection modules to bespoke augmented reality architectures requiring vehicle-specific optical calibration.
- Head-Up Displays:Windshield-projected systems operating above 15,000 cd/m² luminance dominate procurement volumes from German and Japanese OEMs bundling these with advanced driver assistance packages. NHTSA distraction-reduction rules are accelerating replacement of conventional HUDs with holographic variants that eliminate gaze diversion.
- Augmented Reality Displays:Spatial light modulation merges real-time telemetry with three-dimensional road geometry overlays, commanding premium positioning from luxury brands absorbing first-generation costs before economies of scale reach mass-market OEMs. These systems require infinite depth-of-field laser projection to eliminate focal plane adjustment latency during navigation augmentation.
- Instrument Clusters:Dashboard-integrated holographic modules replace mechanical gauges with volumetric imagery.
- Rear-Seat Entertainment:Passenger-facing projection systems prioritize cabin immersion over safety-critical specifications.
Leading the category by volume: Head-Up Displays. Expanding most quickly: Augmented Reality Displays.
Technology:
Cost tier stratification separates mature flat-panel technologies from emerging photonics architectures demanding specialized semiconductor foundry capacity.
- Laser Projection:Infinite depth-of-field elimination of focal plane adjustment enables real-time road geometry augmentation that static systems cannot match. Texas Instruments and Continental AG anchor supply through digital light processing chipsets and embedded optical sensor platforms respectively.
- Digital Light Processing:Micro-mirror array modulation achieves high refresh rates required for safety-critical driver information displays under FDA visual ergonomics guidance. This technology sustains technology leadership across multiple OEM programs through proven automotive qualification pathways.
- LCD:Mature liquid crystal modulation serves cost-constrained instrument cluster applications.
- OLED:Organic electroluminescent layers enable thin-form-factor rear-seat entertainment modules.
Highest volume shipments: Digital Light Processing. Steepest expansion trajectory: Laser Projection.
End User:
Customer type determines pricing power, with direct OEM relationships commanding specification authority over aftermarket retrofit channels.
- OEMs:German, Japanese, and US automakers drive procurement acceleration as augmented reality interfaces migrate from concept vehicles into premium production lines, consolidating integrated cockpit module contracts that bundle holographic displays with instrument clusters and infotainment controllers.
- Luxury Brands:Premium vehicle lines absorb first-generation holographic display costs, creating a pricing ladder for tier-2 manufacturers to adopt scaled-down laser projection units as volumes amortize development across the analysis window.
- Tier-1 Suppliers:Continental AG and similar entities absorb integration risk and warranty liability previously sitting with discrete component vendors.
- Aftermarket Providers:ECE Regulation 125 field-of-view minimums disqualify non-homologated projection units from type approval in Europe.
Dominant procurement volume: OEMs. Gaining share fastest: Luxury Brands.
Integration Level:
Supply concentration favors modular architectures that fragment engineering resources across region-specific optical platform variants.
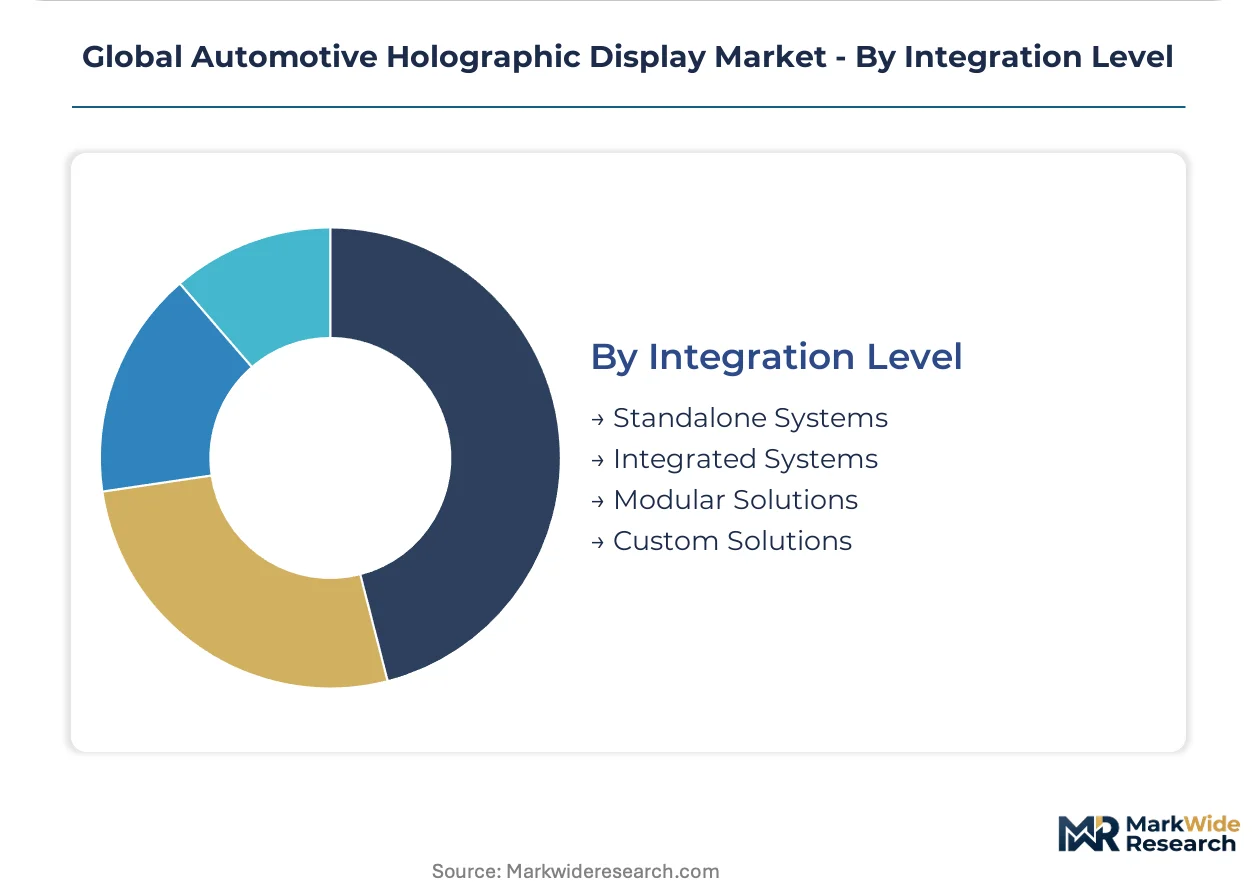
- Integrated Systems:Bundled cockpit modules combining holographic displays with instrument clusters and infotainment controllers concentrate procurement from German and Japanese OEMs pressuring suppliers toward unified subsystem responsibility. These contracts demand ISO 26262 ASIL-B functional safety certification extending validation timelines substantially.
- Modular Solutions:Standardized projection units adaptable across multiple vehicle platforms enable tier-1 suppliers to amortize qualification costs across OEM programs without fragmenting engineering resources on custom architectures.
- Standalone Systems:Discrete holographic modules retrofit into existing dashboard architectures.
- Custom Solutions:Vehicle-specific optical calibration for luxury brand flagship programs.
Procurement concentrates in: Integrated Systems. Climbing the fastest: Modular Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide and gallium nitride substrate fabrication concentrates in East Asian foundries, while optical system integration gravitates toward German and Japanese automotive electronics clusters. The report identifies five countries where holographic display procurement, regulation, and manufacturing overlap.
United States
NHTSA distraction-reduction penalties and FDA visual ergonomics guidance are accelerating OEM adoption of certification-grade head-up displays. Detroit-based automakers bundle holographic modules with advanced driver assistance packages. Texas anchors digital light processing chipset design through established semiconductor houses.
Germany
ECE Regulation 125 field-of-view minimums and EU Green Deal carbon disclosure requirements favor domestic photonics manufacturing over import-dependent competitors. Stuttgart and Munich host tier-1 supplier headquarters where integrated cockpit module contracts consolidate. Continental AG anchors European optical sensor platform development.
Japan
METI automotive technology roadmaps promote domestic holographic component production through targeted industrial policy. Nagoya and Tokyo automotive electronics clusters compress qualification cycles for spatial light modulators. Toyota and Honda procurement patterns favor local supply chain integration.
South Korea
Samsung Electronics leverages vertical LCD and OLED supply chain dominance to capture integrated cockpit module contracts. Seoul Capital Area foundries are reallocating capacity toward automotive-grade photonics substrates. Hyundai Mobis procurement is accelerating holographic head-up display integration into Genesis and Kia premium lines.
China
MIIT standards for intelligent vehicle displays and dual carbon goals are reshaping procurement toward energy-efficient optical systems. Yangtze River Delta electronics clusters host emerging spatial light modulation fabricators. Domestic OEMs are absorbing scaled-down laser projection units as volumes amortize development costs.
Global Automotive Holographic Display Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue augmented reality software integration and specialized photonics architectures. The vendor base stratifies across three tiers: integrated cockpit module suppliers, discrete holographic component vendors, and aftermarket retrofit providers. Two strategic archetypes dominate—vertically integrated electronics conglomerates and optical specialists with embedded software capabilities. Competitive moves concentrate on strategic partnerships for V2X protocol integration and capacity expansion for automotive-grade photonics substrates.
Among Asian electronics conglomerates, Samsung Electronics Co., Ltd. exemplifies vertical integration from semiconductor substrates through finished cockpit modules. Texas Instruments Inc. and Continental AG represent divergent archetypes—the former anchoring digital light processing chipset supply, the latter absorbing integration risk through embedded software and optical sensor platforms. These three entities illustrate how technology leadership and subsystem responsibility define positioning.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| CY Vision |
| Texas Instruments Inc. |
| Himax Technologies, Inc. |
| Continental AG |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Hyundai Mobis Co., Ltd. |
| Infineon Technologies AG |
| Others |
Supply Flow & Price Mechanics
NHTSA distraction-reduction penalties are compelling German and Japanese OEMs to bundle holographic head-up displays with advanced driver assistance packages, forcing tier-1 suppliers to absorb warranty liability and service commitments that inflate upfront module costs while compressing margins on standalone component sales.
Pricing Analysis
Warranty and service bundling separates integrated cockpit module contracts from discrete component transactions, with tier-1 suppliers like Continental AG absorbing multi-year warranty liability that aftermarket providers cannot match. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 ASIL certification grade and thermal management capability, with luxury OEMs showing least price sensitivity while mass-market procurement teams drive cost compression in scaled-down laser projection variants. Pricing pressure stems from automotive-grade photonics substrate shortages, particularly indium phosphide wafer allocation constraints at East Asian foundries.
Supply Chain Analysis
Dual-sourcing requirements mandated by German and US OEMs are fragmenting engineering resources across region-specific optical platform variants rather than enabling unified global modules. Semiconductor fabrication concentrates in South Korea, Taiwan, and Japan, while optical system integration gravitates toward German and Japanese automotive electronics clusters. Spatial light modulator production draws from indium phosphide, gallium nitride, and specialized photonics substrates vulnerable to foundry capacity reallocation. Single-source vulnerability in East Asian wafer supply creates chokepoint exposure. Distribution runs through tier-1 supplier headquarters in Stuttgart, Nagoya, and Detroit before OEM final assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
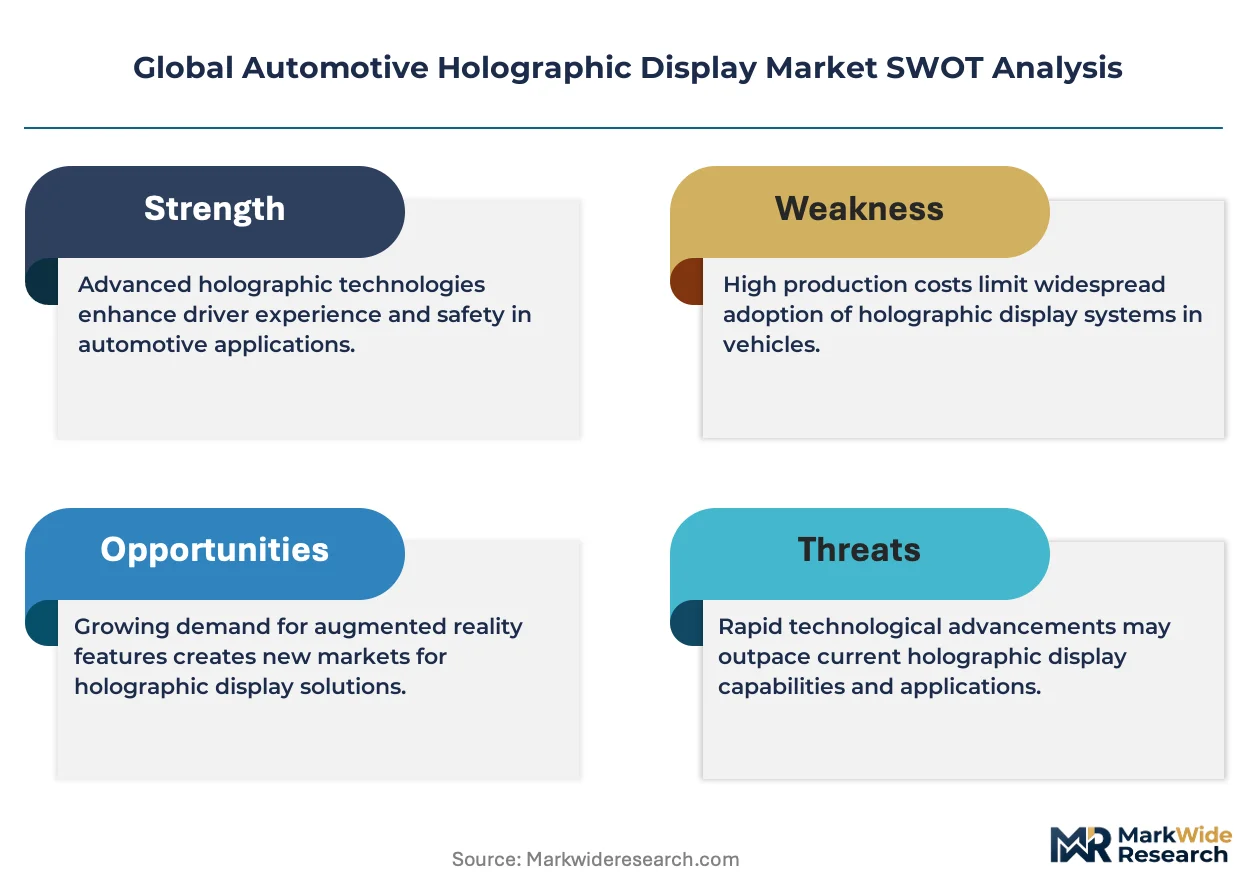
The automotive holographic display market is becoming a vertical-integration race, with control over automotive-grade photonics substrate supply and embedded software stacks determining who captures integrated cockpit module contracts.
For Market Incumbents: Anticipate margin compression from Samsung Electronics' vertical LCD and OLED supply chain dominance by securing captive indium phosphide wafer allocation through foundry partnership structures or backward integration into substrate fabrication. Accelerate ISO 26262 ASIL-B certification pipelines to defend against emerging optical specialists with embedded software capabilities. Prioritize real-time telemetry convergence with V2X protocols as a differentiation lever against commoditized projection hardware. For New Entrants and Emerging Players: EU Green Deal carbon disclosure requirements in Germany open a window for European-based photonics fabricators to capture procurement from automakers seeking supply chain transparency. Target aftermarket retrofit channels disqualified by ECE Regulation 125 field-of-view minimums with homologation-compliant waveguide modules for premium vehicle customization. Pursue white-space in Chinese domestic OEM procurement of scaled-down laser projection units as volumes amortize development costs across mass-market vehicle lines. For Investors and Strategic Acquirers: The window for entry favors optical specialists with embedded software capabilities and existing homologation laboratory infrastructure. Long-term viability hinges on qualification for integrated cockpit module contracts that bundle holographic displays with instrument cluster responsibility. Monitor tier-1 supplier consolidation patterns as the inflection signal for which component vendors will absorb versus exit integration risk.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Photonics Substrate Capacity Expansion | East Asian foundry reallocation toward indium phosphide wafer production secures supply for spatial light modulator fabrication. |
| ISO 26262 ASIL-B Certification Investment | Functional safety validation extends market access to safety-critical driver information display procurement from German OEMs. |
| V2X Protocol Integration Partnership | Real-time telemetry convergence enables augmented reality hazard alerting beyond conventional sensor fusion architectures. |
| EU Green Deal Supply Chain Repositioning | Carbon footprint disclosure compliance favors vertically integrated European photonics manufacturing over import-dependent competitors. |
| Laser Projection Technology Licensing | Infinite depth-of-field elimination of focal plane adjustment latency accelerates adoption in premium vehicle lines. |
Methodological Framework
Multi-period observation of OEM procurement patterns, tier-1 supplier qualification timelines, and photonics substrate allocation trends anchored the trend analysis, supplemented by interviews with automotive platform engineers, tier-1 supplier procurement directors, optical system integration specialists, and semiconductor foundry planning officers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of publicly traded component vendors, and ECE Regulation 125 homologation records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Input-output matrices modeled volume and value across the projection horizon through segmentation by product type, technology architecture, end-user tier, and integration level, with vehicle class and regional production cluster as automotive-specific dimensions. CAGRs derived from curve-fitting historical adoption patterns against regulatory mandate implementation schedules. Forecast inputs incorporated NHTSA rulemaking timelines, EU Green Deal carbon disclosure phase-ins, and METI technology roadmap funding allocations.
The model assumes a particular technology adoption path; alternative pathways for laser projection versus digital light processing dominance would alter the outlook for spatial light modulator substrate demand. Deviation in East Asian foundry capacity allocation or ECE Regulation 125 field-of-view enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market