
 Global Green Vehicles Market | 2026-2036
Global Green Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green Vehicles Market Analysis
Market Dynamics
Aftermarket service revenue is reconfiguring competitive economics as vehicle electrification shifts profit pools from component sales to software updates, battery health management, and charging network subscriptions. Tesla leverages its proprietary Supercharger ecosystem to lock in recurring revenue streams beyond initial vehicle transactions. BYD anchors its position through in-house production of battery cells, semiconductors, and electric drivetrains, collapsing supplier margins into captive operations. Volkswagen Group competes by scaling its modular electric drive matrix across multiple brands and price tiers.
Green vehicles encompass road transport systems utilizing battery electric, hydrogen fuel cell, hybrid-electric, or biofuel powertrains with zero or near-zero tailpipe emissions, typically incorporating lithium-ion or solid-state energy storage with energy densities exceeding 250 Wh per kilogram. These systems serve industrial and commercial purposes by decarbonizing passenger mobility, freight logistics, and public transit while reducing petroleum import dependency. Electric cars command the dominant revenue share within vehicle type segmentation as battery costs decline and charging density expands. Hydrogen fuel cell technology represents the fastest-growing power source segment for heavy-duty trucking and intercity bus applications where battery weight penalties constrain payload capacity. Fleet operators within end user segmentation concentrate margin pools through volume procurement contracts and integrated telematics platforms that optimize total cost of ownership.
The EPA tailpipe emission standards in the United States, the EU Green Deal vehicle CO2 targets enforced by ECHA-aligned mechanisms, and China's dual carbon goals administered by MEE collectively mandate phased combustion engine phaseouts and establish zero-emission vehicle sales quotas. These frameworks shape demand by conditioning market access on compliance certification, redirecting capital toward battery and hydrogen supply chains, and penalizing non-compliant manufacturers with carbon credit deficits. Stakeholders must monitor regulatory calibration timelines and battery raw material sourcing requirements to anticipate capacity allocation decisions and avoid stranded asset exposure in transitional powertrain technologies.
Market Dynamics
Battery chemistry convergence is compressing cost curves and redrawing competitive boundaries as solid-state and sodium-ion architectures displace incumbent lithium-ion dominance in commercial vehicle applications.
Growth Catalysts
- EPA tailpipe emission standards:The phased combustion engine phaseout mandates in the United States are redirecting fleet procurement toward zero-emission powertrains and conditioning market access on compliance certification.
- Fleet operator procurement concentration:Logistics and ride-hailing services are accelerating volume contracts for electric and hydrogen-powered commercial units, consolidating margin pools through integrated telematics platforms.
- Dual carbon goals:China's MEE-administered targets are establishing zero-emission vehicle sales quotas that penalize non-compliant manufacturers with carbon credit deficits.
Market Restraints
- Lithium supply concentration:Extraction and processing capacity concentrates in South American brine deposits and Australian hard-rock operations, exposing cell manufacturers to geopolitical disruption and price volatility.
- Hydrogen infrastructure gap:Heavy-duty fuel cell deployment faces structural barriers from limited refueling station density and high delivered hydrogen costs in North American corridors.
- Battery weight penalties:Energy density limitations constrain payload capacity in long-haul trucking applications where freight economics prioritize ton-mile efficiency.
Strategic Opportunities
- EU Green Deal vehicle CO2 targets:ECHA-aligned enforcement mechanisms are creating regulatory tailwinds for battery and hydrogen supply chain investment across German manufacturing clusters.
- Aftermarket service revenue:Software updates and battery health management are emerging as recurring revenue streams that reconfigure profit pools beyond initial vehicle transactions.
- India's PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting capacity allocation decisions toward South Asian supply chain nodes.
Industry Challenges
- Battery engineering talent scarcity:Electrochemist and thermal management specialist recruitment lags behind capacity expansion timelines in cell manufacturing facilities.
- Charging network certification complexity:Interoperability standards across CCS, NACS, and GB/T protocols create compliance friction for multi-jurisdictional fleet deployments.
- Semiconductor integration bottlenecks:Power electronics and battery management system sourcing requires reconfiguration of legacy automotive supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green Vehicles Market |
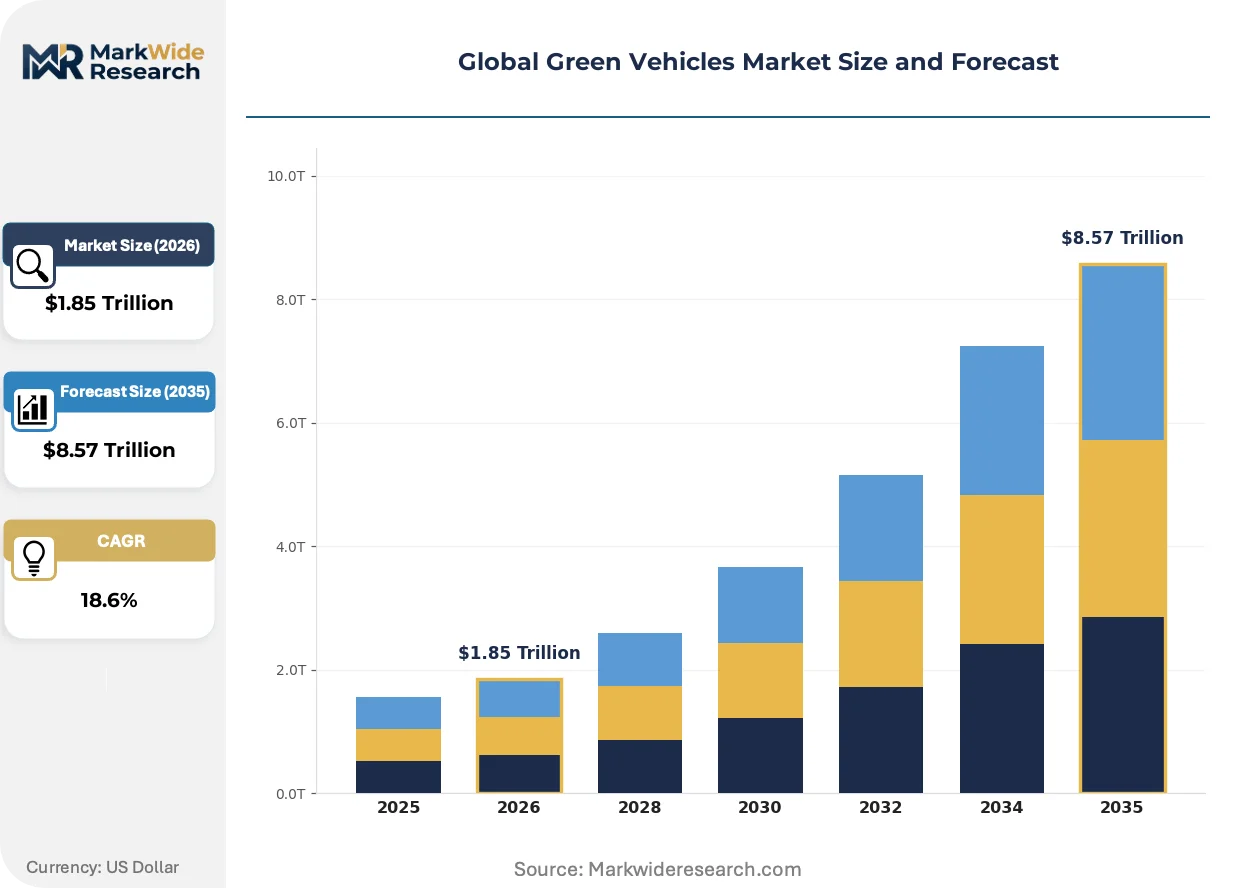
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $8.57 Trillion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Cars, Hybrid Cars, Plug-in Hybrids, Fuel Cell Vehicles Power Source: Battery Electric, Hydrogen, Biofuels, Solar Energy End User: Individual Consumers, Fleet Operators, Government Agencies, Public Transportation Technology: Battery Technology, Charging Infrastructure, Fuel Cell Technology, Renewable Energy Integration |
| Companies Covered | BYD, Tesla, Volkswagen Group, Hyundai Motor Company, General Motors, Geely Auto Group, BMW, Ford Motor Company, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green Vehicles Market Emerging Trajectories
Digital twin architectures and predictive maintenance platforms are virtualizing vehicle lifecycle management, while regulatory calibration timelines accelerate powertrain transition decisions across manufacturing bases.
Solid-state battery technology is virtualizing energy storage architecture by replacing liquid electrolytes with ceramic or polymer conductors that eliminate thermal runaway risks. Commercial fleet operators in German logistics corridors are piloting these systems for 2025-2026 deployment. The technology is virtualizing range anxiety by enabling 800+ kilometer thresholds on single charges while compressing pack volume by thirty percent.
The EU Green Deal vehicle CO2 targets enforced through ECHA-aligned mechanisms are mandating manufacturer-specific emission reduction trajectories through 2035. OEMs face carbon credit deficit penalties that redirect R&D capital from internal combustion refinement toward electric drivetrain scaling. Heavy-duty segments in the Rhine-Ruhr industrial cluster are responding with hydrogen fuel cell corridor investments.
Fleet procurement contracts are consolidating around total cost of ownership metrics that unbundle vehicle acquisition from energy and maintenance service subscriptions. Third-party fleet management platforms are displacing direct OEM relationships in North American last-mile delivery segments. California-based logistics operators are pioneering battery-as-a-service arrangements that transfer residual value risk to infrastructure providers.
Global Green Vehicles Market Segmentation
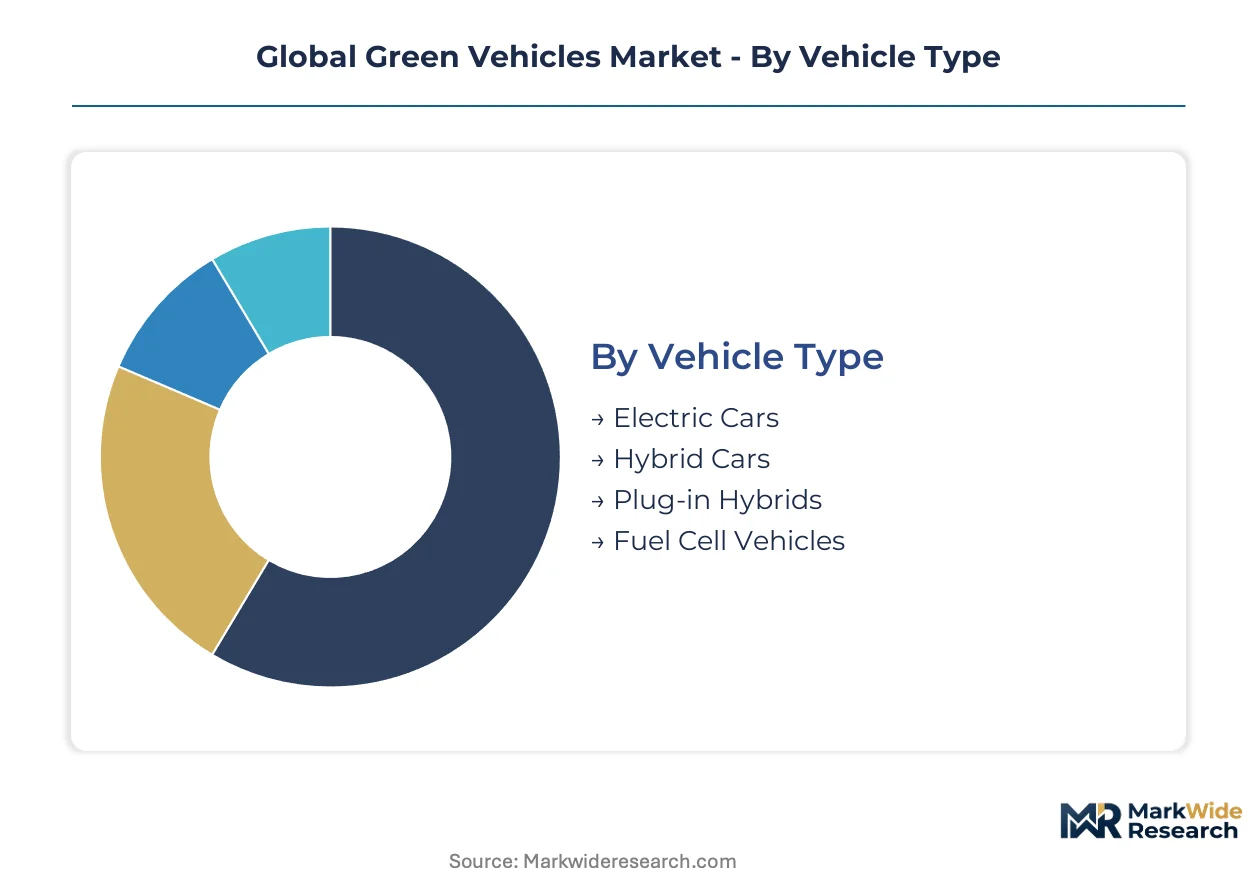
Segmentation in green vehicles reveals how powertrain diversity, procurement scale, and infrastructure maturity create distinct competitive arenas. Fleet operators and individual consumers diverge sharply on total cost of ownership calculations, while hydrogen and battery architectures split along range and payload requirements.
Vehicle Type:
Passenger mobility and freight logistics demand fundamentally different chassis configurations, energy densities, and duty cycles across the use-case spectrum.
- Electric Cars:Pure battery architectures dominate urban passenger segments with lithium-ion packs exceeding 250 Wh/kg. Individual consumers in Germany and China concentrate procurement where charging density supports daily commuting patterns without range anxiety.
- Hybrid Cars:Parallel powertrains combine internal combustion with electric assist for transitional markets lacking charging infrastructure. Fleet operators in India and Southeast Asian corridors favor these units for route flexibility without refueling dependency.
- Plug-in Hybrids:Extended-range batteries enable 50-80 kilometer electric-only operation before combustion engagement. Government agencies in the United States specify PHEVs for field service fleets requiring occasional long-distance deployment.
- Fuel Cell Vehicles:Hydrogen proton-exchange membrane stacks generate electricity onboard with water vapor as sole emission. Heavy-duty applications in the Rhine-Ruhr industrial cluster and California freight corridors adopt these for 800+ kilometer ranges without battery weight penalties.
Established volume favors electric cars; emerging adoption favors fuel cell vehicles.
Power Source:
Energy chemistry and feedstock origin determine supply chain resilience, refueling infrastructure requirements, and regulatory compliance pathways across cost tiers.
- Battery Electric:Solid-state and sodium-ion architectures are displacing incumbent lithium-ion dominance in commercial applications. Chinese cell manufacturers anchor global supply through integrated mining-to-pack operations.
- Hydrogen:Green hydrogen from electrolysis and blue hydrogen from steam methane reforming with carbon capture serve distinct price-sensitive and carbon-intensive segments. German manufacturing clusters and South Korean industrial zones concentrate electrolyzer capacity expansion.
- Biofuels:Cellulosic ethanol and renewable diesel drop into existing internal combustion infrastructure without engine modification. Brazilian sugarcane ethanol programs and Indonesian palm oil biodiesel mandates create regional supply anchors.
- Solar Energy:Photovoltaic-integrated body panels and auxiliary charging systems extend range in high-insolation geographies. Australian mining logistics and Middle Eastern last-mile delivery pilots test solar augmentation for auxiliary power loads.
Cost compression favors battery electric; infrastructure gap constraints favor biofuels in transitional corridors.
End User:
Procurement scale and ownership duration separate fragmented consumer demand from consolidated fleet purchasing power across customer type.
- Individual Consumers:Retail purchasers prioritize purchase price, charging access, and brand equity in private mobility decisions. Urban households in Shanghai, Los Angeles, and London concentrate where apartment dwellers access public charging networks.
- Fleet Operators:Logistics and ride-hailing services negotiate volume contracts with telematics-integrated total cost of ownership guarantees. California-based last-mile delivery platforms pioneer battery-as-a-service arrangements transferring residual value risk.
- Government Agencies:Municipal and federal procurement mandates specify domestic content ratios and zero-emission operational requirements. EPA fleet electrification targets and EU public procurement directives condition contract awards on compliance certification.
- Public Transportation:Bus rapid transit and rail operators require 18-hour daily duty cycles with sub-30-minute refueling windows. Shenzhen's all-electric bus fleet and Hamburg's fuel cell bus corridors demonstrate divergent technology pathways.
Margin consolidation favors fleet operators; policy tailwinds favor government agencies.
Technology:
Intellectual property concentration and capital intensity separate component suppliers from integrated system architects across maturity stages.
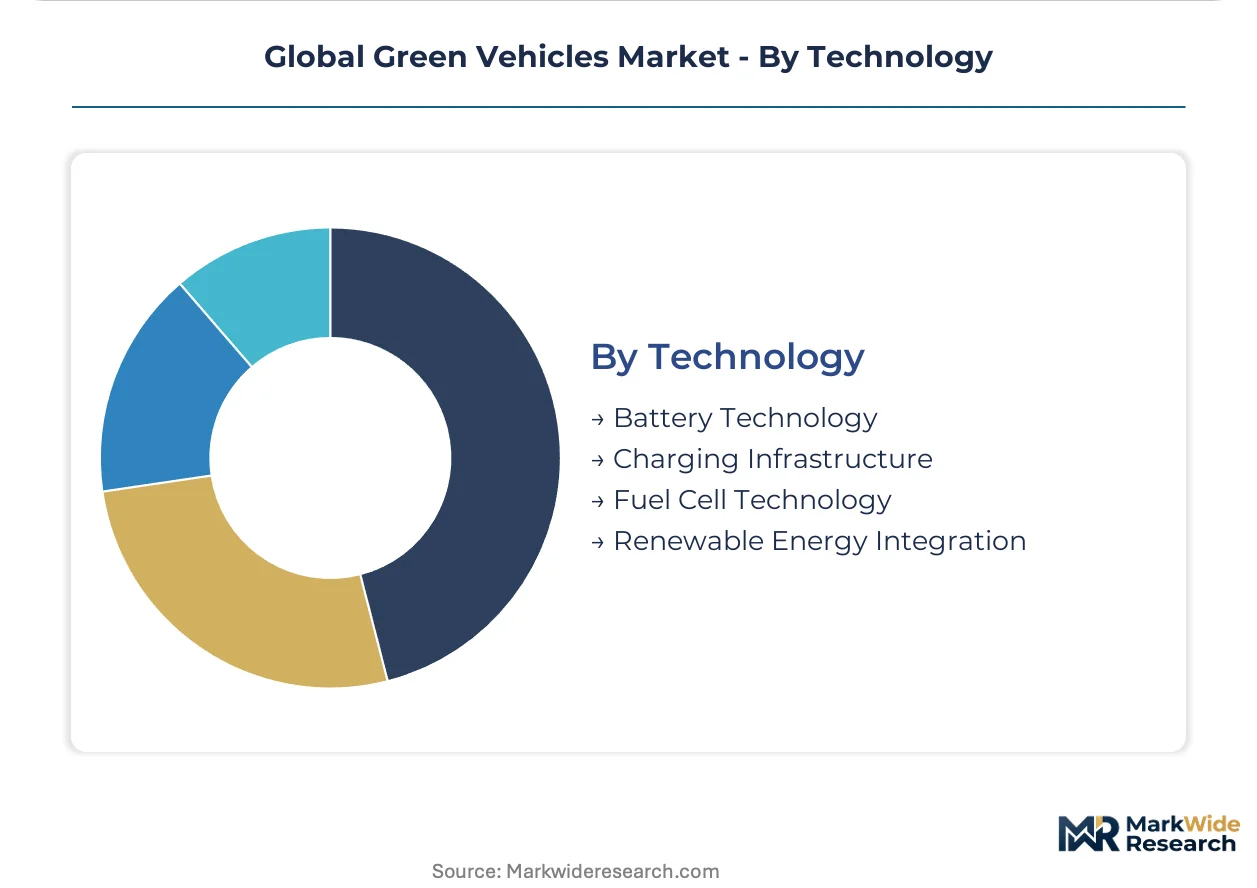
- Battery Technology:Cell chemistry, thermal management, and battery management systems determine energy density, cycle life, and safety profiles. Solid-state pilot lines in German automotive clusters and Chinese sodium-ion commercialization compress next-generation timelines.
- Charging Infrastructure:CCS, NACS, and GB/T protocol fragmentation creates interoperability friction for multi-jurisdictional deployments. Tesla's Supercharger network and China's State Grid dominate proprietary versus public infrastructure models.
- Fuel Cell Technology:Platinum catalyst loading, membrane durability, and hydrogen storage pressure define system economics. South Korean and Japanese suppliers anchor stack manufacturing while German industrial gas players control hydrogen distribution.
- Renewable Energy Integration:Vehicle-to-grid bidirectional charging and solar-vehicle-to-home systems monetize stationary battery capacity. Danish wind power corridors and Australian solar-rich regions pilot grid-stabilization revenue streams.
Supply concentration favors battery technology; standardization gaps challenge charging infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement in India and Southeast Asia favors hybrid architectures, while affluent consumer bases in Germany and coastal China absorb premium battery electric price points with minimal elasticity.
United States
Fleet electrification mandates from EPA tailpipe standards redirect commercial procurement toward zero-emission powertrains. The Inflation Reduction Act conditions tax credit eligibility on domestic battery content ratios. California's Central Valley logistics corridors host pilot deployments of heavy-duty fuel cell trucks serving agricultural freight routes.
Germany
Rhine-Ruhr industrial clusters concentrate hydrogen fuel cell corridor investments for heavy-duty applications. ECHA-aligned EU Green Deal enforcement mechanisms penalize carbon credit deficits. Bavarian automotive engineering centers pilot solid-state battery manufacturing lines targeting 2025 commercial deployment.
China
Integrated mining-to-pack operations anchor global lithium-ion cell supply through state-coordinated capacity expansion. MEE-administered dual carbon goals establish manufacturer-specific zero-emission sales quotas. Shenzhen's municipal bus fleet operates as the world's largest all-electric public transit deployment.
India
Hybrid powertrains dominate transitional procurement where charging infrastructure remains sparse. PLI scheme production-linked incentives attract advanced chemistry cell manufacturing toward Tamil Nadu and Gujarat. Delhi-NCR ride-hailing fleets negotiate volume contracts for compressed natural gas hybrid conversions.
South Korea
Industrial gas and electrolyzer capacity expansion concentrates in southeastern manufacturing zones. METI-coordinated hydrogen economy roadmaps coordinate fuel cell stack production with refueling infrastructure. Ulsan automotive clusters integrate captive semiconductor and battery management system production.
Global Green Vehicles Market Vendor Landscape
Capability concentration sits with integrated battery chemistry specialists; scale advantage sits with diversified automotive conglomerates. The market structures around three tiers: captive vertical integration, modular platform scaling, and ecosystem lock-in through charging infrastructure. Dominant competitive moves include backward integration into raw material refining and strategic partnerships for solid-state pilot production.
Within the captive integration tier, BYD exemplifies full-stack control from mineral processing through vehicle assembly. Tesla occupies a position defined by proprietary charging network density and software monetization architectures. Volkswagen Group represents modular platform economics scaled across multiple brand portfolios and price tiers.
| Leading Market Players |
|---|
| BYD |
| Tesla |
| Volkswagen Group |
| Hyundai Motor Company |
| General Motors |
| Geely Auto Group |
| BMW |
| Ford Motor Company |
| Toyota Motor Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium supply concentration in South American brine deposits and Australian hard-rock operations determines both tier spreads between premium solid-state and economy sodium-ion configurations and the geographic shape of cathode precursor supply chains. This raw material chokepoint compresses margins for cell manufacturers lacking captive offtake agreements while amplifying pricing power for integrated mining-to-pack operators.
Pricing Analysis
Aftermarket service revenue from battery health management and charging network subscriptions drives lifetime value beyond initial vehicle transactions. Three-tier pricing structure across premium, standard, and economy levels separates solid-state flagship models from lithium-ion mass-market units and sodium-ion entry segments. Cost compression in the economy tier is intensifying because Chinese sodium-ion commercialization collapses cell costs below incumbent lithium-ion benchmarks. Fleet operators exhibit lowest price sensitivity due to total cost of ownership guarantees, while individual consumers in price-sensitive corridors demonstrate highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with Chinese integrated cell producers, South Korean chemical specialists, and Japanese precision equipment suppliers. Geographic supply concentration centers on China, South Korea, and Germany for cell assembly, cathode materials, and power electronics respectively. Raw material dependencies draw from Chilean lithium, Indonesian nickel, and DRC cobalt. Single-source vulnerability in semiconductor-grade silicon anode supply creates structural exposure. Distribution runs through captive OEM channels, third-party fleet management platforms, and public charging network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global green vehicles market rewards electrochemist talent and solid-state pilot line capacity that incumbent automotive conglomerates cannot replicate internally. Battery engineering scarcity constrains expansion timelines across manufacturing bases.
For Market Incumbents: Pre-empt sodium-ion commoditization by securing captive lithium offtake from Australian hard-rock operations and accelerating solid-state pilot production in German automotive clusters. Defend against Chinese integrated producers through backward integration into cathode precursor refining. Certification investment in ECHA-aligned EU Green Deal compliance creates margin protection from carbon credit deficit penalties. For New Entrants and Emerging Players: Heavy-duty fuel cell corridors in the Rhine-Ruhr industrial cluster and California Central Valley represent the most penetrable entry points where battery weight penalties constrain incumbent solutions. India's PLI scheme production-linked incentives for advanced chemistry cell manufacturing offer subsidized capacity allocation for sodium-ion commercialization. Battery-as-a-service arrangements transferring residual value risk provide the go-to-market angle for fleet operator procurement. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors electrochemist-heavy specialists with solid-state intellectual property over diversified automotive conglomerates. Long-term viability across the next decade hinges on cathode chemistry control and thermal management system sourcing. Acquisition target archetype: mid-cap cell manufacturers with pilot line capacity and OEM qualification relationships. The signal to watch is EPA tailpipe standard calibration timelines accelerating zero-emission procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Supply Agreement | Locks in 800+ kilometer range capability for German luxury OEM platforms. |
| Charging Infrastructure Partnership | Tesla's Supercharger network access conditions fleet procurement decisions. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat capacity captures India's PLI scheme incentives. |
| Platform Standardization | Volkswagen's MEB architecture spreads R&D across multiple brand portfolios. |
| Software-Defined Vehicle Investment | Over-the-air updates monetize recurring revenue beyond initial transactions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator telematics directors, and aftermarket service heads. Secondary validation drew from vehicle production databases, EPA tailpipe standard filings, EU ECHA enforcement mechanism disclosures, and IEA hydrogen economy roadmaps. Bottom-up cell manufacturing capacity estimates triangulated against top-down fleet procurement contract values.
Calibration against historical adoption curves and regulatory phaseout timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, battery chemistry tier, OEM integration level, and regional production cluster. CAGRs were derived from capacity expansion schedules correlated with fleet operator procurement concentration. Industry-specific forecast inputs incorporate solid-state pilot line commissioning timelines and hydrogen refueling station density buildouts.
Practitioners should monitor EPA tailpipe standard stringency revisions, lithium carbonate spot price volatility, and solid-state manufacturing yield rates for early signals of forecast deviation. Quarterly review of fleet operator procurement contract announcements and battery cell capacity utilization reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market