
 Traffic Sign Recognition System Market | 2026-2036
Traffic Sign Recognition System Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Sign Recognition System Market Intelligence
Software-defined feature subscriptions for over-the-air recognition updates is rebalancing how suppliers monetize traffic sign recognition capabilities. Continental AG leverages its integrated ADAS portfolio to bundle recognition modules with broader sensor fusion packages. Mobileye anchors its position through proprietary computer vision silicon that reduces latency in classification tasks. Robert Bosch GmbH competes across both passenger and commercial vehicle tiers with scalable camera-to-ECU architectures.
A traffic sign recognition system comprises camera sensors, image processing algorithms, and classification engines that detect, interpret, and communicate road sign information to vehicle control systems or drivers in real time. These systems operate at frame rates exceeding 30 fps with detection ranges typically spanning 50-250 meters depending on sensor configuration and ambient lighting conditions, serving primarily to reduce speed-limit violations and prevent intersection collisions. Deep learning architectures now dominate development pipelines because convolutional neural networks deliver superior accuracy in degraded weather conditions compared with legacy template-matching approaches. Advanced Driver Assistance Systems applications capture the largest current revenue pool, while Smart Transportation deployments for municipal traffic management represent the fastest-expanding segment as cities retrofit existing infrastructure with connected roadside units.
The National Highway Traffic Safety Administration in the United States mandates specific performance benchmarks for camera-based driver assistance under its NCAP evaluation protocols, directly influencing OEM sourcing decisions for North American vehicle programs. The European Union's AI Act and UNECE WP.29 regulations impose conformity assessment requirements on machine-learning components within safety-critical automotive systems, creating compliance barriers for non-certified suppliers. Euro NCAP's evolving test protocols for vulnerable road user protection further tighten the performance threshold for sign recognition accuracy in complex urban scenarios. Stakeholders must monitor how regulatory divergence between U.S. NCAP, EU type-approval frameworks, and China's GB standards reshapes product development roadmaps and regional go-to-market sequencing.
Market Dynamics
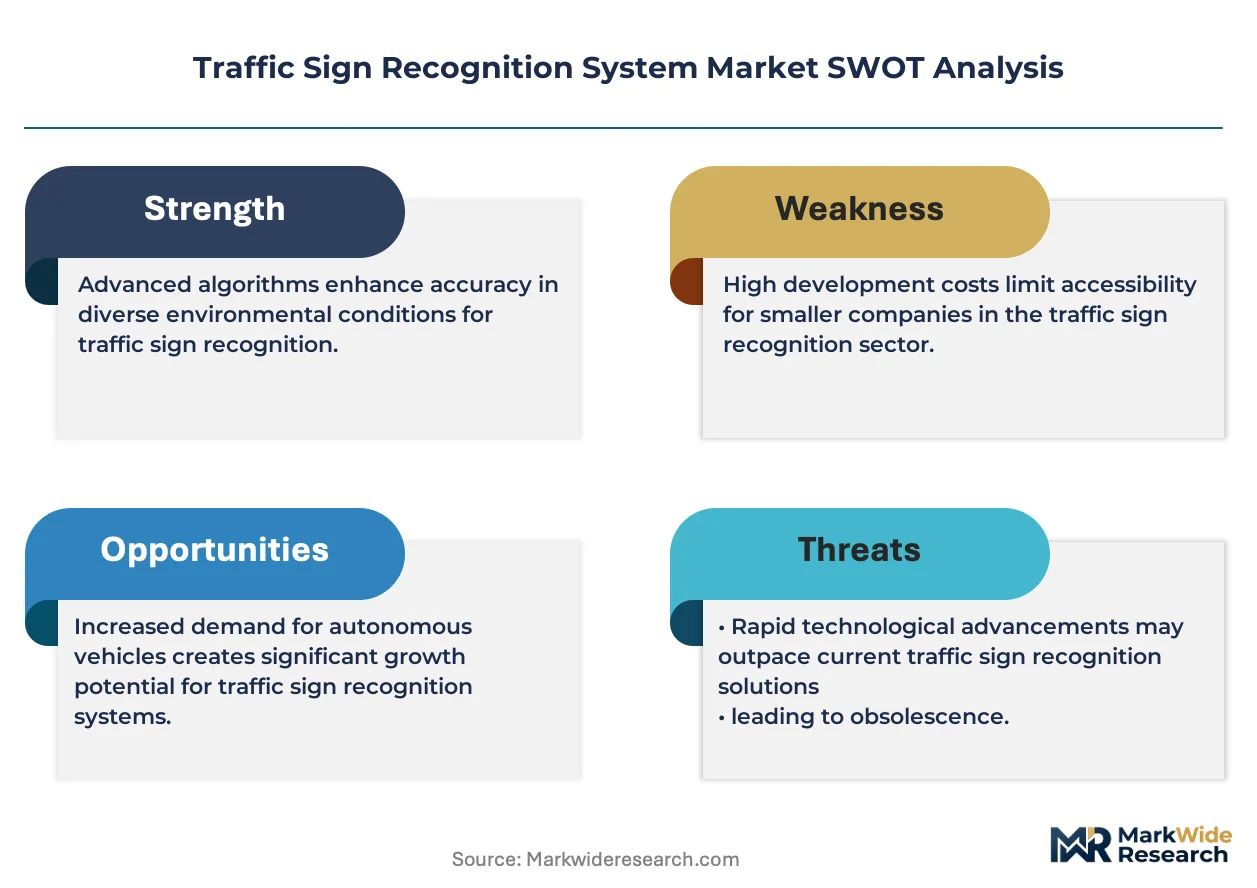
The EU AI Act and UNECE WP.29 regulations are compressing development timelines for machine-learning safety systems, forcing suppliers to restructure conformity assessment workflows before 2025 type-approval deadlines.
Growth Catalysts
- Regulatory Mandate Convergence:Euro NCAP's 2026 protocols will penalize vehicles lacking traffic sign recognition, compelling OEMs to standardize camera-based systems across all trim levels.
- Sensor Fusion Integration:Lidar-to-camera data pipelines are reducing false-positive rates in degraded visibility, accelerating ADAS platform adoption in premium vehicle segments.
- Municipal Infrastructure Modernization:German cities are deploying connected roadside units that broadcast digital sign data, creating dual-validation architectures for autonomous vehicle testing.
Market Restraints
- Semiconductor Supply Concentration:Advanced image signal processors for automotive vision systems source from a concentrated East Asian foundry base, exposing procurement to geopolitical disruption.
- Algorithm Validation Costs:Edge-case testing for snow-covered and backlit signs requires proprietary datasets that smaller suppliers cannot afford to curate.
- Regulatory Fragmentation:Divergent GB standards in China versus UNECE frameworks force dual certification tracks, inflating engineering overhead for multinational suppliers.
Strategic Opportunities
- Commercial Vehicle Retrofit Demand:European fleet operators face 2027 safety mandates for heavy trucks, opening aftermarket channels for camera-to-ECU upgrade kits.
- V2X Convergence:Integration of cellular vehicle-to-everything protocols with onboard vision systems enables predictive sign alerting before physical detection range.
- Software Subscription Models:Over-the-air recognition map updates allow recurring revenue streams detached from hardware replacement cycles.
Industry Challenges
- Functional Safety Certification Bottleneck:ISO 26262 ASIL-D qualification for neural network components demands specialized verification engineers scarce in European labor markets.
- Legacy Fleet Integration Complexity:CAN bus architectures in pre-2020 vehicles lack bandwidth for real-time image processing, limiting addressable retrofit volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Sign Recognition System Market |
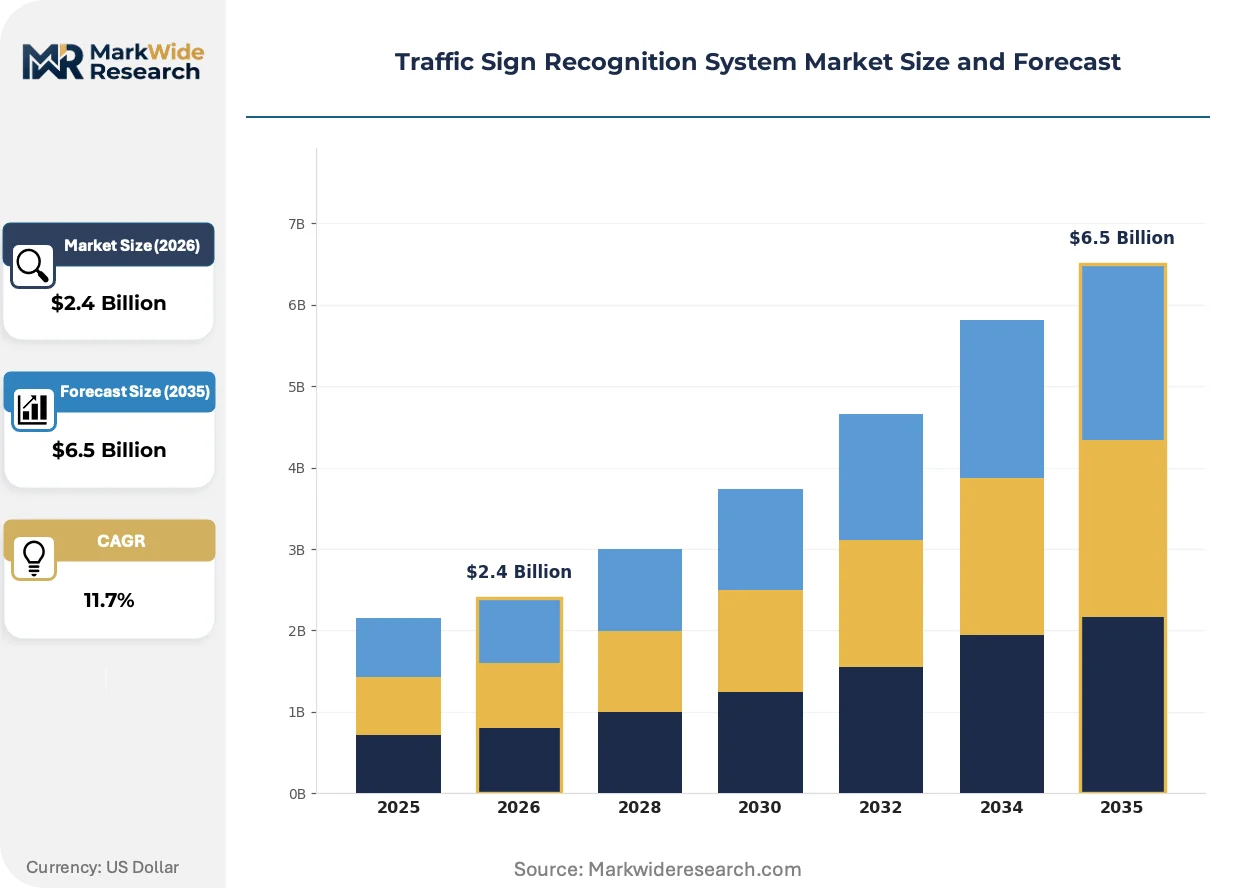
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Computer Vision, Deep Learning, Image Processing Application: Autonomous Vehicles, Advanced Driver Assistance Systems, Fleet Management, Smart Transportation End User: Automotive Manufacturers, Transportation Authorities, Logistics Companies, Insurance Providers Installation: On-Premises, Cloud-Based, Integrated Systems, Standalone Solutions |
| Companies Covered | DENSO CORPORATION, Magna International Inc., Robert Bosch GmbH, Aptiv, Ford Motor Company, Continental AG, ZF Friedrichshafen AG, Valeo, Mobileye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Sign Recognition System Market Strategic Shifts & Innovations
Deep learning architectures are compressing the competitive gap between tier-one suppliers and specialized computer vision firms, reshaping how recognition capabilities integrate into broader sensor fusion stacks.
Transformer-based neural networks are consolidating market position for edge-case classification in adverse weather. Tier-one suppliers embed these architectures directly into camera modules to reduce ECU processing load. This consolidation is eliminating standalone software licensing as a viable business model for mid-tier algorithm developers.
The EU AI Act's conformity assessment requirements for machine-learning safety systems are forcing suppliers to document training data provenance and model drift monitoring. Automotive OEMs now require algorithmic transparency reports before platform integration. European type-approval bodies are responding with accelerated certification pathways for suppliers demonstrating continuous learning governance.
Fleet procurement departments are unbundling recognition software from bundled ADAS packages to negotiate direct contracts with specialized vision providers. Commercial vehicle operators in Germany and France lead this disintermediation, seeking performance-based pricing tied to speed-limit compliance metrics. This pattern is compressing margins for full-stack suppliers dependent on integrated system sales.
Traffic Sign Recognition System Market Segmentation
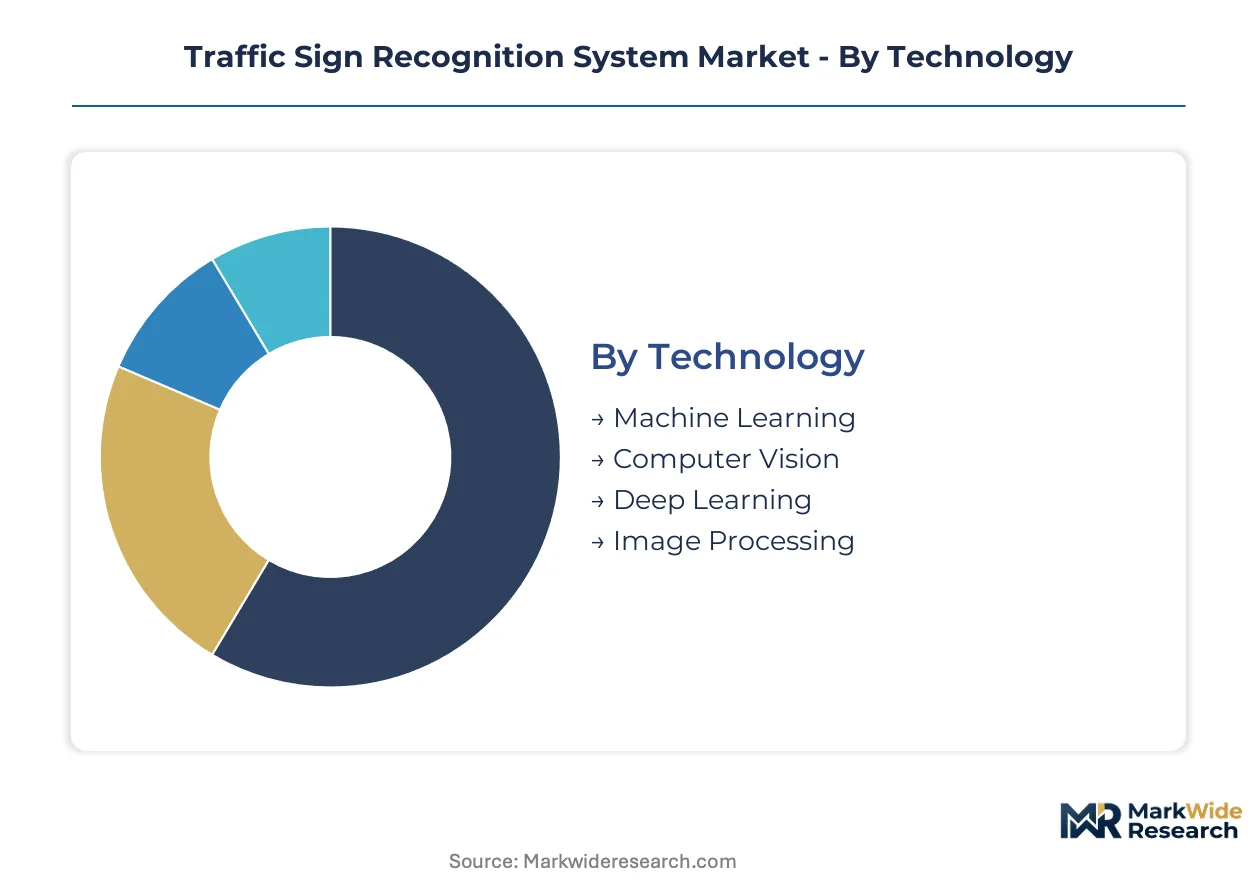
Technology choices determine processing latency and weather resilience, while application focus shapes whether suppliers pursue OEM integration or infrastructure deployment. End-user procurement patterns differ sharply between volume automotive contracts and municipal smart city tenders.
Technology:
Buyers differentiate primarily by computational constraints at the edge versus training data requirements for accuracy optimization.
- Deep Learning:Convolutional and transformer-based neural networks process multi-layer feature extraction for degraded visibility scenarios. Automotive OEMs in Germany specify these architectures for Euro NCAP compliance testing under adverse weather protocols.
- Computer Vision:Traditional algorithmic approaches using edge detection and geometric analysis operate with lower silicon overhead. Fleet operators in France deploy these for retrofitted commercial vehicles where processing budgets remain constrained.
- Machine Learning:Supervised classification models trained on curated sign datasets balance accuracy against interpretability requirements. Insurance providers favor these for liability documentation where decision explainability matters.
- Image Processing:Preprocessing pipelines for noise reduction, lens distortion correction, and dynamic range optimization prepare raw sensor feeds. Camera module suppliers bundle these as firmware layers to differentiate hardware offerings.
Deep Learning leads volumes today; Image Processing is gaining share fastest through embedded module integration.
Application:
Cost tiers separate mass-market passenger vehicle deployments from premium autonomous platforms and municipal infrastructure retrofits.
- Advanced Driver Assistance Systems:Camera-to-ECU architectures delivering speed-limit alerts and intersection warnings dominate current procurement. German OEMs standardize these across trim levels to meet evolving Euro NCAP assessment protocols.
- Smart Transportation:Connected roadside units broadcasting digital sign data to approaching vehicles represent infrastructure-side deployment. Municipal authorities in Stuttgart and Munich pilot these for autonomous vehicle validation corridors.
- Autonomous Vehicles:Redundant perception stacks requiring sub-50-millisecond classification latency for safety-critical decisions. Robotaxi developers in California and Arizona specify these for SAE Level 4 operational design domains.
- Fleet Management:Aftermarket telematics integration capturing sign data for driver coaching and compliance documentation. Logistics operators across the Benelux region deploy these to reduce speed violation penalties.
Advanced Driver Assistance Systems anchors revenue today; Smart Transportation climbs fastest on municipal modernization budgets.
End User:
Volume concentration versus margin structure distinguishes high-unit automotive contracts from specialized infrastructure and insurance analytics segments.
- Automotive Manufacturers:Tier-one suppliers integrate recognition modules into consolidated ADAS platform sourcing. Procurement teams at Volkswagen Group and BMW specify fused camera-radar architectures for next-generation vehicle programs.
- Transportation Authorities:Public sector tenders for highway monitoring and urban traffic management infrastructure. Germany's KBA coordinates type-approval testing protocols that shape supplier development priorities.
- Logistics Companies:Commercial vehicle operators seeking driver assistance retrofits for regulatory compliance. French fleet operators negotiate performance-based contracts tied to speed-limit adherence metrics.
- Insurance Providers:Telematics data aggregation for risk scoring and claims verification. Underwriters in the United Kingdom analyze sign compliance patterns to refine usage-based premium models.
Automotive Manufacturers dominate unit volumes; Insurance Providers are expanding most quickly on data monetization strategies.
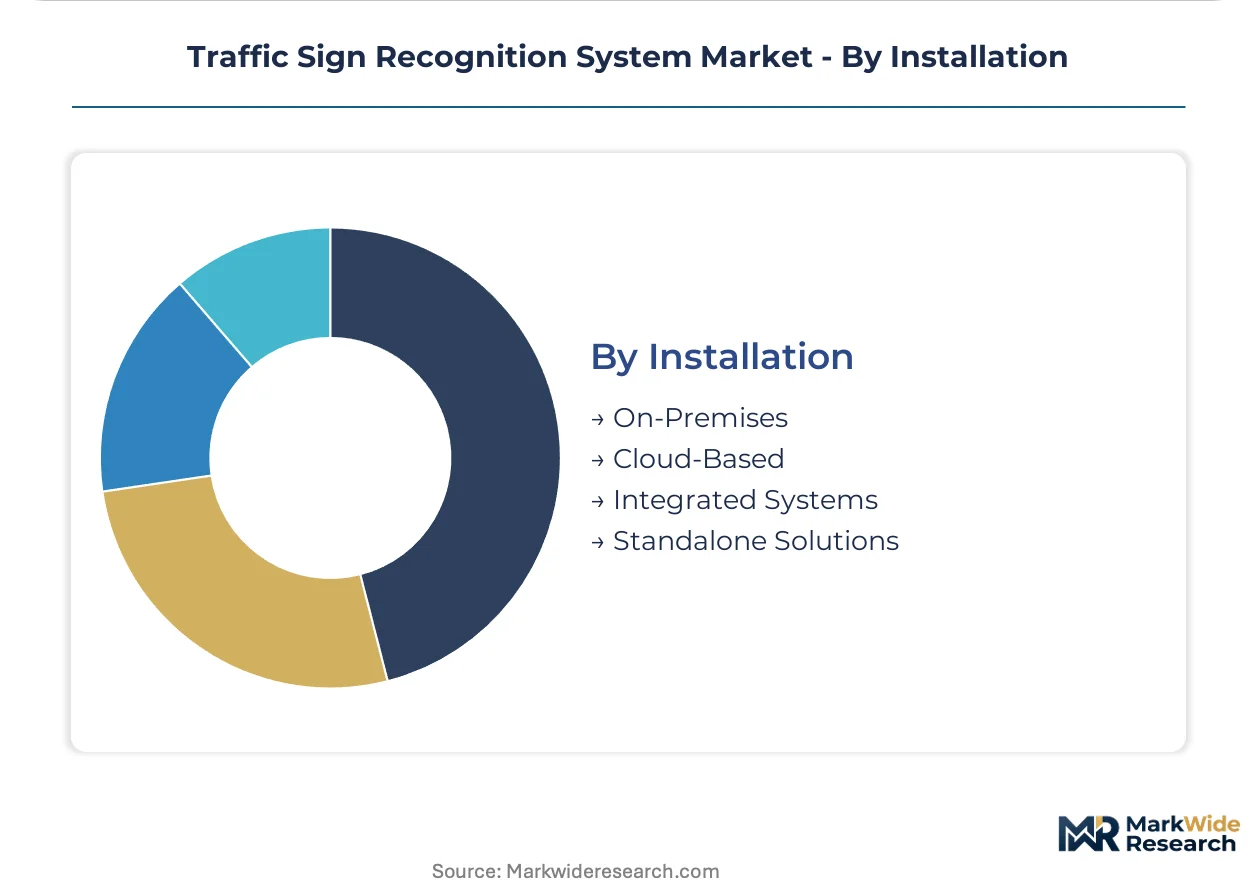
Installation:
Customer technical sophistication and legacy system constraints determine whether buyers accept cloud dependency or demand edge autonomy.
- Integrated Systems:Camera modules with embedded processing fused into vehicle domain controller architectures. Silicon Valley autonomous vehicle developers specify these to minimize wiring harness complexity.
- Standalone Solutions:Self-contained hardware-software packages for retrofit installation in existing vehicle fleets. German commercial vehicle workshops stock these for mandatory safety equipment upgrades.
- On-Premises:Local server deployments for transportation authority traffic control centers processing municipal camera networks. Bavarian state operators maintain these for data sovereignty compliance.
- Cloud-Based:Centralized model training and map update distribution with edge inference only at vehicle level. Connected car platforms leverage these for over-the-air recognition capability refreshes.
Integrated Systems leads deployment scale; Cloud-Based is accelerating fastest on software subscription revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping supplier location decisions as the EU AI Act's conformity costs diverge from U.S. NCAP's performance-based approach. Tier-one suppliers now optimize R&D footprints across jurisdictions to manage certification overhead.
Germany
KBA type-approval protocols and Euro NCAP 2026 mandates are accelerating OEM procurement timelines. The EU AI Act's machine-learning documentation requirements force suppliers to maintain algorithmic transparency repositories. Stuttgart and Munich anchor autonomous vehicle validation corridors where connected roadside units enable dual-validation architectures.
United States
NHTSA NCAP evaluation protocols directly influence camera-based driver assistance sourcing for North American vehicle programs. The absence of federal AI system mandates creates lower compliance barriers than European frameworks. California and Arizona robotaxi developers specify redundant perception stacks for SAE Level 4 operational domains.
China
GB standards divergence from UNECE frameworks forces dual certification tracks for multinational suppliers. The country's national automotive regulator maintains distinct testing protocols for vision-based safety systems. Yangtze River Delta manufacturing clusters concentrate domestic camera module production for local OEM integration.
France
ANSM oversight of software-as-medical-device classifications is spilling into automotive AI governance discussions. Fleet operators in the Paris region negotiate performance-based contracts tied to speed-limit compliance metrics. Commercial vehicle retrofit demand concentrates in Lyon and Marseille logistics corridors.
Japan
METI industrial policy supports domestic semiconductor supply chains for automotive image signal processors. JIS standards for vehicle safety systems maintain compatibility with UNECE frameworks while preserving national testing autonomy. Nagoya's automotive engineering cluster hosts Tier-one supplier R&D facilities for Asian market platforms.
Traffic Sign Recognition System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-stack ADAS integrators commanding automotive OEM contracts while modular software vendors serve fleet retrofit channels. The vendor base concentrates around tier-one automotive suppliers with existing sensor fusion portfolios, supplemented by specialized computer vision firms. Three archetypes dominate: integrated platform providers bundling recognition with broader ADAS stacks; standalone vision specialists licensing algorithm modules; and silicon-anchored players embedding processing into camera hardware. M&A activity targets machine-learning engineering teams, while geographic expansion follows OEM platform localization requirements.
Among German-based automotive suppliers, Robert Bosch GmbH and Continental AG exemplify integrated platform strategies spanning passenger and commercial vehicle tiers. Mobileye anchors the silicon-anchored archetype through proprietary computer vision hardware. These three represent divergent competitive positioning around bundled versus modular, hardware-centric versus software-centric value capture models.
| Leading Market Players |
|---|
| DENSO CORPORATION |
| Magna International Inc. |
| Robert Bosch GmbH |
| Aptiv |
| Ford Motor Company |
| Continental AG |
| ZF Friedrichshafen AG |
| Valeo |
| Mobileye |
| Others |
Cost & Logistics Intelligence
Advanced image signal processor procurement from Taiwan and South Korea feeds through tier-one automotive suppliers into three-tier pricing structures across premium, standard, and economy levels, with EU AI Act compliance costs compressing margins at the mid-market tier while premium ADAS bundles maintain pricing power through sensor fusion integration.
Pricing Analysis
Distributor margin stacking at the aftermarket retrofit tier compresses final pricing by 15-20 points before fleet operator negotiation. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified neural network modules from legacy computer vision architectures and basic image processing firmware. Pricing pressure stems from semiconductor foundry concentration in East Asia and the EU AI Act's conformity assessment overhead. Fleet operators in France exhibit highest price sensitivity due to performance-based contract structures, while German OEM procurement teams prioritize certification tier over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing for automotive-grade image signal processors and South Korean memory foundries for neural network inference storage. Camera module assembly draws from Chinese lens manufacturing, German automotive-grade connector suppliers, and Japanese image sensor fabrication. Tariff exposure runs through U.S.-China technology trade restrictions on advanced semiconductors. Distribution runs through tier-one ADAS integrators who bundle recognition modules with broader sensor fusion packages, bypassing standalone software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Euro NCAP 2026 mandates shift procurement toward ASIL-D certified systems that command premium positioning over legacy computer vision alternatives.
For Market Incumbents: Lock in algorithmic transparency repositories to satisfy EU AI Act training data provenance requirements before type-approval deadlines compress. Defend against modular software vendors disintermediating ADAS bundles by embedding transformer architectures directly into camera hardware, reducing ECU processing load and eliminating standalone licensing opportunities. Prioritize ISO 26262 ASIL-D qualification investments to capture German OEM platform standardization across all trim levels. For New Entrants and Emerging Players: The 40-point spread between premium autonomous vehicle perception stacks and economy fleet retrofit kits opens white-space at the commercial vehicle aftermarket tier. Target standalone camera-to-ECU upgrade kits for European heavy truck operators facing 2027 safety mandates, where CAN bus bandwidth constraints in pre-2020 vehicles limit incumbent full-stack solutions. Pursue direct contracting with French and Benelux logistics operators seeking performance-based pricing tied to speed-limit compliance metrics. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety certification bottlenecks and proprietary dataset curation costs strand mid-tier algorithm developers without tier-one automotive relationships. Five-to-ten year viability favors silicon-anchored players with captive computer vision hardware or integrated platform providers with consolidated ADAS sourcing relationships. Watch for accelerated certification pathways from European type-approval bodies as the signal indicating which suppliers have achieved continuous learning governance compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Repository Investment | EU AI Act compliance enables type-approval pathway access for German OEM platform integration. |
| Transformer Architecture Camera Module Embedding | Edge-case classification capability in adverse weather displaces standalone software licensing models. |
| Commercial Vehicle Aftermarket Channel Development | 2027 European fleet safety mandates open retrofit volume inaccessible to integrated platform bundling. |
| V2X Protocol Integration Partnership | Cellular vehicle-to-everything convergence enables predictive sign alerting before physical detection range. |
| Continuous Learning Governance Certification | Accelerated European type-approval pathways differentiate qualified suppliers in procurement evaluations. |
Research Approach
Coverage spans Germany, the United States, China, France, and Japan, with primary inputs from each combining structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, fleet operator safety managers, and transportation authority technology officers alongside secondary validation through UNECE WP.29 regulatory filings, NHTSA NCAP evaluation protocols, Euro NCAP test documentation, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the projection horizon. Segmentation dimensions modeled include technology architecture, application tier, end-user procurement pattern, and installation topology, with vehicle class and regional regulatory cluster as automotive-specific cross-cuts. CAGRs derive from fitted growth curves anchored to observable adoption inflection points in German OEM integration timelines and municipal infrastructure deployment schedules. Industry-specific inputs capture semiconductor foundry capacity allocation trends and Euro NCAP protocol evolution trajectories.
Caveats apply where foundry capacity reallocation, geopolitical trade restriction expansion, or regulatory divergence between UNECE and GB standard frameworks could materially shift the outlook. Forecasts reflect assumptions about algorithm validation cost trajectories and functional safety engineering labor market elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market