
 UAE Automotive Sensors Market | 2026-2036
UAE Automotive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Automotive Sensors Market Analytics
Authorized dealer networks across the UAE are reshaping how automotive sensors reach end users, with tier-one distributors now controlling inventory allocation for advanced driver-assistance components. Robert Bosch GmbH leverages its Dubai logistics hub to dominate aftermarket sensor availability for European vehicle platforms. Continental AG anchors its Gulf presence through direct OEM supply contracts with domestic vehicle assemblers. Infineon Technologies AG differentiates via semiconductor sensor specialization targeting emission control modules for regional heat conditions.
Automotive sensors are electromechanical transducers that convert physical variables—pressure, temperature, proximity, or speed—into electrical signals for vehicle electronic control units, typically operating across temperature ranges from minus forty to one hundred fifty degrees Celsius and communicating via CAN or LIN bus protocols. Their primary purpose is to enable real-time monitoring and feedback control for safety, powertrain efficiency, and emissions compliance in modern vehicles. Pressure sensors lead product type demand due to their ubiquity in engine management and tire pressure monitoring systems, while MEMS technology captures expanding share through miniaturization advantages in optical and ultrasonic applications. Safety systems application segments command premium positioning as collision avoidance mandates intensify, whereas emission control sensors face margin compression from commoditization despite regulatory volume requirements.
MOHAP and the Emirates Authority for Standardization and Metrology enforce vehicle safety and environmental compliance frameworks that directly determine sensor specification thresholds for models sold or assembled domestically. The UAE's alignment with UN ECE regulations through GCC standardization protocols further elevates product certification requirements for imported sensor modules. Stakeholders must monitor evolving autonomous vehicle testing permits issued by Dubai's Roads and Transport Authority, as these pilot programs will establish precedent for next-generation sensor procurement specifications before broader regulatory codification.
Market Dynamics
Collision avoidance mandates from the Emirates Authority for Standardization and Metrology are compressing sensor procurement cycles as domestic assemblers race to comply with upgraded vehicle safety protocols before enforcement deadlines.
Growth Catalysts
- ADAS mandate acceleration:The Emirates Authority for Standardization and Metrology's updated vehicle safety protocols now require advanced driver-assistance components on all new passenger vehicle assemblies, forcing immediate procurement of radar and camera modules.
- Smart mobility infrastructure:Dubai's Roads and Transport Authority has committed to autonomous vehicle testing corridors that demand V2X sensor networks, creating dedicated procurement channels for lidar and ultrasonic arrays.
- Fleet operator prioritization:Commercial vehicle operators in Abu Dhabi and Dubai are specifying collision avoidance packages as standard equipment to reduce insurance premiums and liability exposure.
Market Restraints
- Semiconductor supply concentration:Advanced MEMS and CMOS sensor dies originate from concentrated East Asian foundry capacity, exposing UAE distributors to allocation rationing during demand spikes.
- Extreme temperature specification costs:Sensors rated for sustained operation above 85°C ambient require specialized packaging and thermal compensation circuits that inflate bill-of-materials costs versus standard automotive grades.
- UN ECE certification friction:GCC alignment with UN ECE regulations imposes extended homologation timelines for imported sensor modules, delaying revenue recognition for distributors.
Strategic Opportunities
- Autonomous testing precedent:Dubai's Roads and Transport Authority pilot programs will establish procurement specifications for next-generation lidar and radar arrays before broader regulatory codification across the Emirates.
- Aftermarket channel expansion:Authorized dealer networks are capturing sensor replacement demand from aging European vehicle fleets, creating margin-rich installation and calibration service revenue.
- Emission control sensor refresh:MOHAP enforcement of tightened environmental compliance frameworks is forcing replacement cycles for oxygen and NOx sensors in legacy commercial vehicle populations.
Industry Challenges
- Calibration technician scarcity:ADAS sensor installation requires precise optical and radar alignment capabilities that exceed traditional automotive electrician training, constraining service throughput at dealer networks.
- Integration complexity with legacy CAN architectures:Newer LIN-flexible sensor modules face compatibility friction when retrofitting into older European vehicle platforms dominant in the UAE used-car fleet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Automotive Sensors Market |
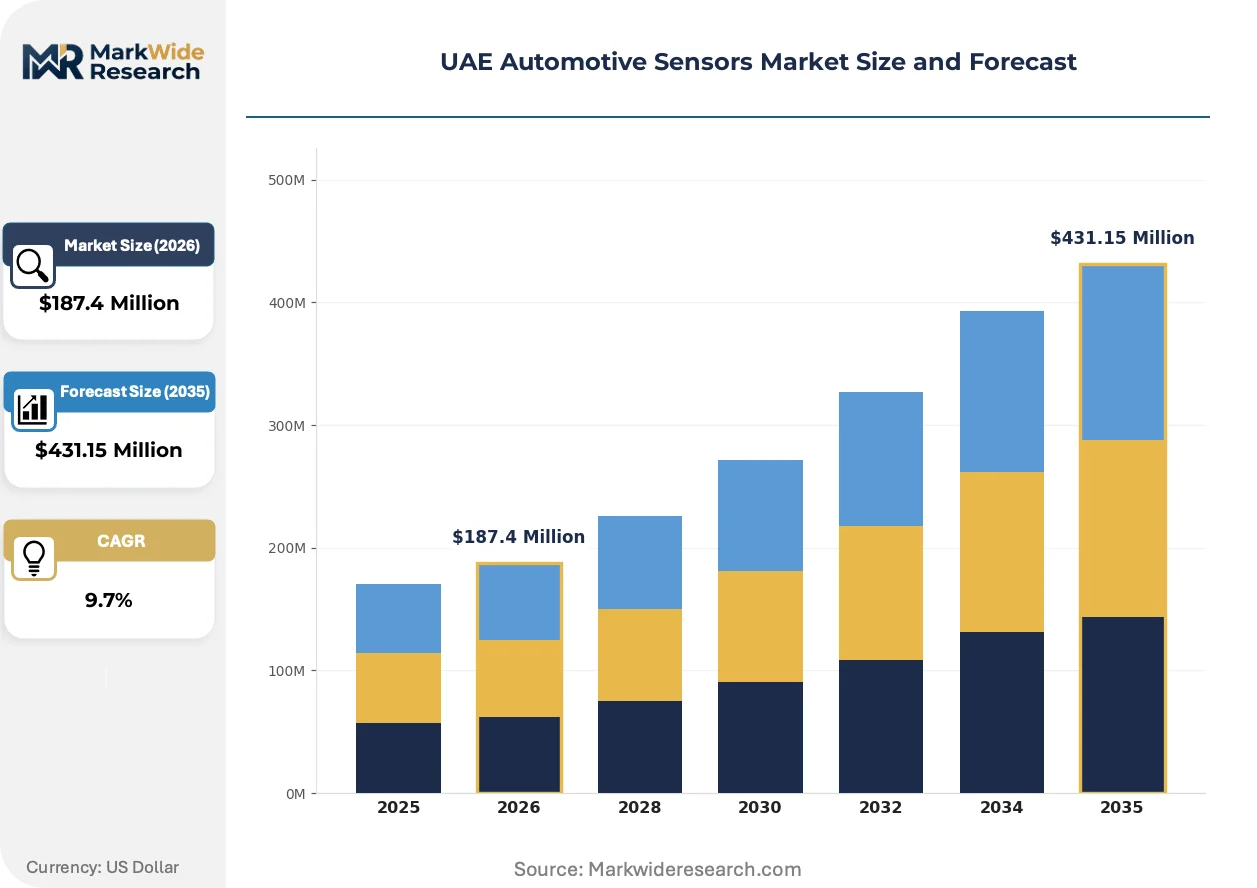
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Proximity Sensors, Speed Sensors Technology: Optical Sensors, MEMS Sensors, Ultrasonic Sensors, Radar Sensors End User: OEMs, Aftermarket Providers, Fleet Management, Vehicle Assemblers Application: Safety Systems, Engine Control, Emission Control, Collision Avoidance |
| Companies Covered | Robert Bosch GmbH, Continental AG, Infineon Technologies AG, Denso Corporation, BorgWarner Inc., NXP Semiconductors, Valeo, Autoliv Inc., STMicroelectronics NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Automotive Sensors Market Evolving Landscape
Solid-state sensing architectures and software-defined perception systems are compressing hardware refresh cycles while elevating the strategic importance of embedded algorithm development capabilities among UAE distributors.
Silicon photonics-based lidar modules are replacing mechanical scanning assemblies in premium vehicle platforms. Domestic fleet operators specifying Level 2+ automation packages are demanding solid-state reliability for desert operating conditions. This transition is rendering obsolete the maintenance-intensive motor-and-mirror designs that previously dominated aftermarket replacement demand.
MOHAP enforcement protocols for vehicle emissions compliance are tightening specification thresholds for oxygen, NOx, and particulate matter sensors. Domestic assemblers must now source components certified to updated environmental frameworks ahead of import permit renewals. Aftermarket distributors are responding by pre-staging certified inventory in Dubai logistics hubs to avoid customs clearance delays.
Fleet procurement committees are consolidating sensor vendor relationships around tier-one distributors offering integrated installation and calibration services. Authorized dealer networks are displacing independent garages for ADAS component replacement as liability concerns mount. This concentration is most visible in Dubai's commercial vehicle segment, where operators prioritize single-source accountability over price competition.
UAE Automotive Sensors Market Segmentation
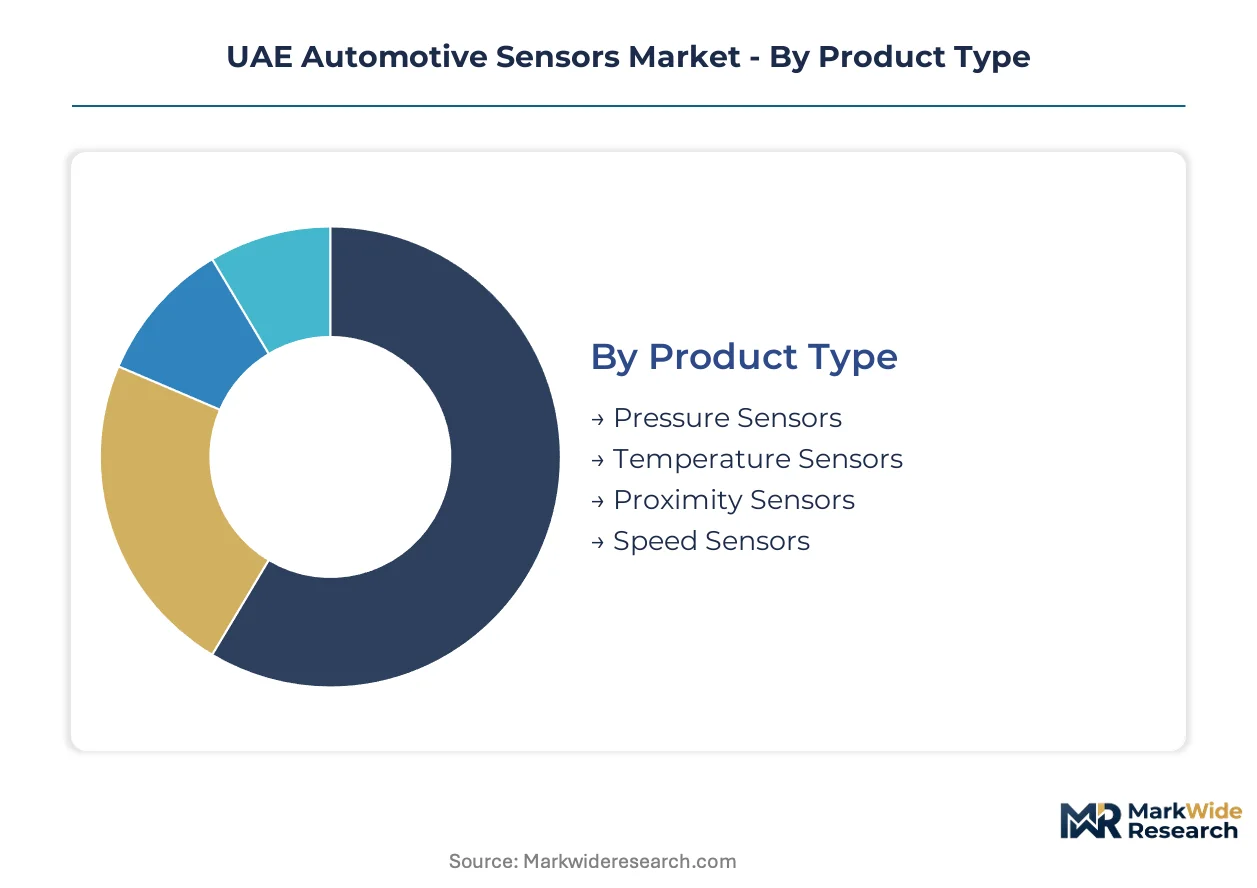
Sensor specification requirements diverge sharply across deployment contexts in the Emirates. Procurement patterns for Dubai's luxury passenger fleet bear little resemblance to Abu Dhabi commercial vehicle mandates. Understanding these dimensional splits enables targeted positioning against divergent technical and commercial priorities.
Product Type:
Cost tier differentiation separates commodity-grade replacements from precision-engineered assemblies commanding substantial specification premiums.
- Pressure Sensors:Piezoresistive and capacitive transducers monitor manifold absolute pressure, fuel rail pressure, and tire inflation states. Demand concentrates in Dubai's premium vehicle service centers where TPMS calibration errors trigger warranty claims. MOHAP emission enforcement is accelerating replacement cycles for barometric pressure sensors in legacy commercial fleets.
- Temperature Sensors:Thermistor-based and RTD architectures span coolant, intake air, and exhaust gas monitoring applications. Abu Dhabi's heavy-duty transport operators specify extended-range variants rated beyond standard automotive grades for desert operating conditions. Thermal compensation circuits inflate unit costs versus temperate-climate equivalents.
- Proximity Sensors:Inductive and capacitive detection modules enable parking assistance and gesture control interfaces.
- Speed Sensors:Hall-effect and magnetoresistive devices transmit wheel speed data to ABS and traction control modules.
Pressure sensors command the established base. The steepest expansion runs through temperature sensors as thermal management complexity rises in electrified powertrains.
Technology:
Application context determines whether optical precision, mechanical miniaturization, or RF penetration characteristics dominate procurement specifications.
- Optical Sensors:CMOS and CCD imaging arrays capture lane markings, traffic signage, and obstacle boundaries for vision-based ADAS. Dubai's Roads and Transport Authority autonomous testing corridors are specifying multi-spectral cameras capable of penetrating sand-haze conditions. Image sensor procurement is consolidating around distributors offering integrated calibration tooling.
- MEMS Sensors:Micro-electromechanical accelerometers and gyroscopes enable inertial measurement for stability control and navigation dead-reckoning. Fleet operators in Sharjah and Ras Al Khaimah are specifying MEMS-based tire pressure monitors for their vibration tolerance on unpaved access routes. Miniaturization advantages are displacing conventional electromechanical alternatives in space-constrained installations.
- Ultrasonic Sensors:Piezoelectric transducer arrays generate proximity maps for low-speed parking maneuvers.
- Radar Sensors:77GHz and 24GHz FMCW modules enable long-range object detection and adaptive cruise control functionality.
Optical sensors anchor current ADAS deployment volumes. MEMS architectures are climbing the fastest as unit economics improve and integration density requirements intensify.
End User:
Customer type segmentation reveals divergent procurement rhythms, specification authority, and service attachment expectations.
- OEMs:Original equipment manufacturers specify sensor modules during vehicle platform development cycles with multi-year supply agreements. European luxury marques dominate Dubai's new vehicle registrations, sourcing radar and camera assemblies through tier-one integrators with direct Bosch and Continental relationships.
- Aftermarket Providers:Independent distributors and service chains address replacement demand from aging fleet populations. Authorized dealer networks are capturing ADAS sensor replacement volume as liability concerns displace independent garages for calibration-critical installations.
- Fleet Management:Commercial vehicle operators in Abu Dhabi's logistics and construction sectors consolidate procurement across multi-vehicle specifications.
- Vehicle Assemblers:Domestic assembly operations in Dubai Industrial City and KIZAD source sensor modules for regional production of commercial and passenger vehicles.
OEMs retain specification authority for new vehicle content. Aftermarket providers are gaining share fastest as the installed base of ADAS-equipped vehicles ages into replacement cycles.
Application:
Functional purpose determines regulatory exposure, performance certification requirements, and margin structure across deployment scenarios.
- Safety Systems:Airbag deployment sensors, seatbelt pretensioner triggers, and rollover detection modules operate under zero-failure reliability mandates. Emirates Authority for Standardization and Metrology protocols require documented traceability for safety-critical components, favoring authorized distributor channels over gray-market alternatives.
- Engine Control:MAP sensors, oxygen sensors, and knock detectors optimize combustion efficiency across varying fuel quality conditions. MOHAP emission enforcement is forcing refresh cycles for legacy oxygen and NOx sensors in commercial vehicle populations operating on lower-grade fuel stocks.
- Emission Control:Particulate matter and selective catalytic reduction monitoring sensors face margin compression from commoditization despite regulatory volume requirements.
- Collision Avoidance:Fusion architectures combining radar, lidar, and camera inputs enable automatic emergency braking and pedestrian detection.
Engine control sensors represent the volume anchor. Collision avoidance applications are expanding most quickly as fleet operators prioritize insurance premium reductions and liability mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Dubai and Abu Dhabi corridors while procurement costs escalate in Sharjah and Northern Emirates due to logistics friction and technician scarcity. This asymmetry shapes distributor network investments and inventory pre-positioning strategies across the Emirates.
Dubai
Premium vehicle service centers and smart mobility infrastructure investments drive sensor procurement volumes. Dubai's Roads and Transport Authority autonomous vehicle testing corridors demand multi-spectral cameras and V2X sensor networks. Dubai Industrial City hosts domestic assembly operations sourcing radar and camera modules for regional production.
Abu Dhabi
Commercial vehicle fleet operators prioritize collision avoidance packages to reduce insurance premiums and liability exposure. MOHAP emission enforcement protocols tighten specification thresholds for oxygen and NOx sensors in legacy commercial fleets. Khalifa Industrial Zone anchors heavy-duty transport operator procurement consolidation.
Sharjah
MEMS-based tire pressure monitors gain specification for vibration tolerance on unpaved access routes serving construction and logistics sectors. Emirates Authority for Standardization and Metrology vehicle safety protocols accelerate sensor integration mandates for regional fleet operators. Sharjah's industrial zones concentrate aftermarket distribution hubs serving Northern Emirates access routes.
Northern Emirates
Temperature sensor demand concentrates in extended-range variants rated beyond standard automotive grades for desert operating conditions. MOHAP environmental compliance frameworks force replacement cycles for legacy emission control sensors. Ras Al Khaimah's logistics corridors link to Dubai distribution hubs with extended procurement cycles.
UAE Automotive Sensors Market Competitive Landscape
Full-line system integrators and semiconductor specialists split the market into distinct capability tiers with limited overlap in customer access. Authorized dealer networks now control inventory allocation for advanced driver-assistance components, compressing independent distributor margins. Tier-one distributors with direct OEM relationships and specialized semiconductor fabricators represent the dominant archetypes. Competitive dynamics center on strategic partnerships with domestic assemblers and geographic expansion through Dubai logistics hub positioning.
Within the full-line system integrator tier, Robert Bosch GmbH and Continental AG exemplify archetypes leveraging direct OEM supply relationships and aftermarket channel dominance. Bosch leverages its Dubai logistics hub to anchor aftermarket sensor availability for European vehicle platforms. Continental AG occupies a position through direct OEM supply contracts with domestic vehicle assemblers. Infineon Technologies AG represents the semiconductor specialist archetype, differentiating via sensor specialization targeting emission control modules for regional heat conditions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Infineon Technologies AG |
| Denso Corporation |
| BorgWarner Inc. |
| NXP Semiconductors |
| Valeo |
| Autoliv Inc. |
| STMicroelectronics NV |
| Others |
Value Network & Pricing Analysis
Undercapacity in East Asian MEMS foundry capacity is driving allocation rationing that simultaneously inflates spot-market premiums and compresses margins for UAE distributors holding standard-grade inventory. This utilization squeeze forces domestic assemblers toward configured-to-order procurement with extended lead-time commitments, reshaping how tier-one distributors position thermal-compensated sensor variants against commodity alternatives.
Pricing Analysis
The customization-premium spread separates standard-grade pressure sensors from desert-rated variants with extended thermal compensation circuits. Pricing stratifies across premium, standard, and economy tiers based on certification grade alignment with Emirates Authority for Standardization and Metrology protocols and volume scale commitments from fleet operators. Cost compression in the emission control sensor tier is intensifying because MOHAP enforcement has commoditized oxygen and NOx module specifications. Fleet management committees exhibit highest price sensitivity due to multi-vehicle procurement consolidation, while Dubai's premium vehicle service centers prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control regimes restricting advanced CMOS and MEMS fabrication equipment to Chinese foundries are constraining alternative supply development for automotive-grade sensor dies. The UAE market draws from Taiwan, South Korea, and Japan for MEMS accelerometers, radar chipsets, and CMOS imaging arrays respectively. Raw material dependencies center on silicon wafers, rare-earth magnets for Hall-effect devices, and specialized ceramic substrates for high-temperature thermistors. Single-source vulnerability concentrates in 77GHz radar module supply where two East Asian fabricators dominate global capacity. Distribution runs through Dubai's Jebel Ali logistics hub with tier-one distributors controlling inventory allocation for ADAS components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE automotive sensors market builds defensive moats through regulatory entrenchment, as Emirates Authority for Standardization and Metrology certification requirements create switching costs that lock domestic assemblers into approved supplier relationships.
For Market Incumbents: Pre-empt emerging solid-state lidar specialists by securing exclusive distribution rights for silicon photonics-based perception modules before Dubai's Roads and Transport Authority codifies autonomous vehicle procurement specifications. Accelerate backward integration into thermal compensation circuit design to defend margin position against commodity pressure from standard-grade Asian imports. Channel control through authorized dealer networks remains the priority lever for ADAS replacement volume capture. For New Entrants and Emerging Players: Mid-market commercial vehicle fleets in Sharjah and Ras Al Khaimah represent the most penetrable entry point given incumbent underinvestment in vibration-tolerant MEMS tire pressure monitoring for unpaved access routes. Aftermarket calibration service bundling offers a differentiated go-to-market angle against parts-only distributors, particularly for collision avoidance sensor installations requiring optical alignment capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one distributors with integrated installation and calibration service contracts tied to fleet management procurement committees. Long-term viability across the analysis window favors acquisition targets possessing direct OEM supply relationships with domestic vehicle assemblers in Dubai Industrial City and KIZAD. The signal to watch is Dubai's Roads and Transport Authority autonomous testing permit expansion, which would force accelerated procurement specification updates across the Emirates.| Strategic Initiative | Industry Significance |
|---|---|
| Desert-Rated Sensor Certification Investment | MOHAP thermal specification thresholds favor pre-certified inventory positioning in Dubai logistics hubs. |
| ADAS Calibration Service Expansion | Authorized dealer networks capture replacement volume as liability concerns displace independent garages. |
| Solid-State Lidar Distribution Partnership | Dubai's Roads and Transport Authority pilot programs establish precedent before broader regulatory codification. |
| Fleet Management Consolidation Targeting | Abu Dhabi commercial operators prioritize single-source accountability for collision avoidance package procurement. |
| Emission Control Sensor Pre-Staging | MOHAP enforcement timelines create inventory velocity advantages for certified oxygen and NOx module distributors. |
Research Methodology
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations managers, and dealership service heads provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, Emirates Authority for Standardization and Metrology protocol filings, and customs import records. Bottom-up sensor unit demand estimates triangulated against top-down vehicle production forecasts across the analysis window.
Scenario-bracketing anchored the forecast framework with low-base-high demand trajectories reflecting divergent ADAS mandate enforcement timelines and autonomous vehicle testing corridor expansion rates. Segmentation dimensions spanned product type, technology architecture, end-user category, and application function with vehicle class and propulsion architecture as automotive-specific overlays. CAGRs derived from unit-volume buildups multiplied by average selling price trajectories, with thermal specification premium erosion and MEMS cost curves as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in fleet operator capital expenditure cycles or Dubai property development sentiment would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and foundry capacity expansion. Material shifts in Emirates Authority for Standardization and Metrology vehicle safety protocol adoption schedules or East Asian semiconductor export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Boat Wiring Harness Market