
 Motorcycle Stability Control Market | 2026-2036
Motorcycle Stability Control Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Stability Control Market Analytics
A shortage of embedded software engineers with functional safety expertise is unwinding production timelines across the motorcycle stability control supply chain. Bosch leverages its proprietary MEMS sensor fabrication to dominate inertial measurement unit supply for two-wheeler applications. Continental sustains competitive positioning through deep integration with European OEM brake system architectures. Brembo anchors its presence in the premium segment via specialized cornering ABS calibration for high-displacement sport motorcycles.
Motorcycle stability control encompasses electronic systems that modulate braking force, throttle response, and chassis dynamics to prevent loss of traction or lateral instability, typically integrating six-axis inertial measurement units sampling at 100 Hz or higher with hydraulic brake actuators capable of sub-100-millisecond intervention cycles. The primary commercial purpose centers on reducing fatal single-vehicle crashes while enabling manufacturers to differentiate premium product tiers through advanced safety credentials. Anti-lock Braking System technology occupies the largest installed base due to regulatory mandates across major markets, though Electronic Stability Control represents the fastest-expanding margin pool as OEMs bundle cornering functionality into flagship touring and sport platforms. Integrated Systems command premium positioning by consolidating braking, traction, and throttle control into unified ECU architectures that reduce wiring complexity and calibration overhead for motorcycle manufacturers.
NHTSA's Federal Motor Vehicle Safety Standards for motorcycle braking performance, combined with the European Union's Euro 5 emission and safety framework administered by the European Commission, shape product certification requirements and OEM sourcing decisions across developed markets. India's Ministry of Road Transport and Highways mandates ABS for all two-wheelers above 125cc, creating compliance-driven demand that localizes supply chain investments. Japan's Ministry of Land, Infrastructure, Transport and Tourism maintains voluntary but influential safety ratings that steer domestic OEM technology roadmaps. Stakeholders must monitor divergence between emerging market mandate timelines and premium segment voluntary adoption curves to calibrate R&D allocation and regional manufacturing commitments.
Market Dynamics
Embedded software engineering scarcity is compressing production timelines across the motorcycle stability control supply chain, forcing OEMs to recalibrate R&D allocation toward in-house functional safety capability building.
Growth Catalysts
- Euro 5 Safety Framework:The European Commission's integrated emission and safety mandates require advanced braking modulation on new motorcycles, compelling OEMs to source six-axis inertial measurement units and cornering ABS modules.
- India's ABS Mandate:The Ministry of Road Transport and Highways requires anti-lock braking on all two-wheelers above 125cc, generating compliance-driven procurement from domestic manufacturers and Tier 1 suppliers.
- Cornering Functionality Bundling:Premium touring and sport motorcycle segments are integrating electronic stability control as standard equipment, differentiating flagship product tiers through unified ECU architectures.
Market Restraints
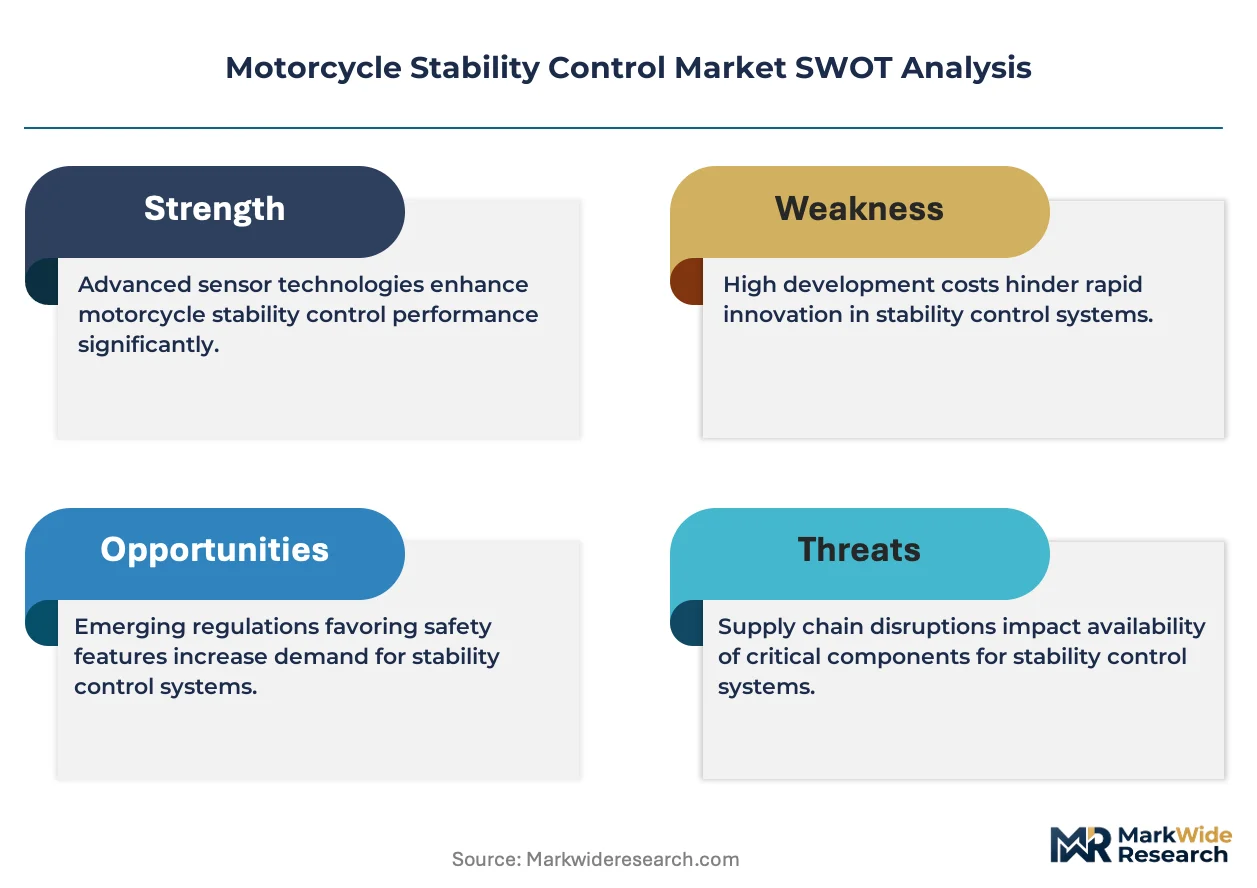
- MEMS Sensor Supply Concentration:Proprietary fabrication capabilities for high-frequency inertial sensors concentrate among a limited supplier base, creating single-source vulnerability for two-wheeler IMU procurement.
- Functional Safety Certification Costs:ISO 26262 ASIL-D compliance for motorcycle stability software requires extensive validation cycles, elevating non-recurring engineering costs for mid-volume OEM programs.
- Hydraulic Actuator Input Volatility:Specialized solenoid valves and high-pressure pump components face price pressure from automotive brake system demand, squeezing margin on sub-100-millisecond intervention hardware.
Strategic Opportunities
- Mid-Displacement Segment Penetration:Electronic stability control remains optional on 250-400cc commuter motorcycles in Southeast Asian markets, presenting white space for cost-optimized IMU and ECU integration.
- Throttle-by-Wire Convergence:Integration of ride-by-wire systems with stability control algorithms enables predictive traction management, opening bundled platform opportunities for integrated system suppliers.
- Brazil's Regulatory Trajectory:ANVISA and national transport authorities are evaluating mandatory ABS timelines for two-wheelers, creating early-mover positioning for certification-ready suppliers.
Industry Challenges
- Embedded Functional Safety Talent Gap:Shortages of engineers with ISO 26262 expertise and motorcycle-specific chassis dynamics knowledge are extending calibration timelines by 6-12 months.
- Legacy Brake Architecture Integration:Retrofitting cornering ABS into existing hydraulic brake platforms without full system redesign requires complex sensor fusion algorithms and extensive track validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Stability Control Market |
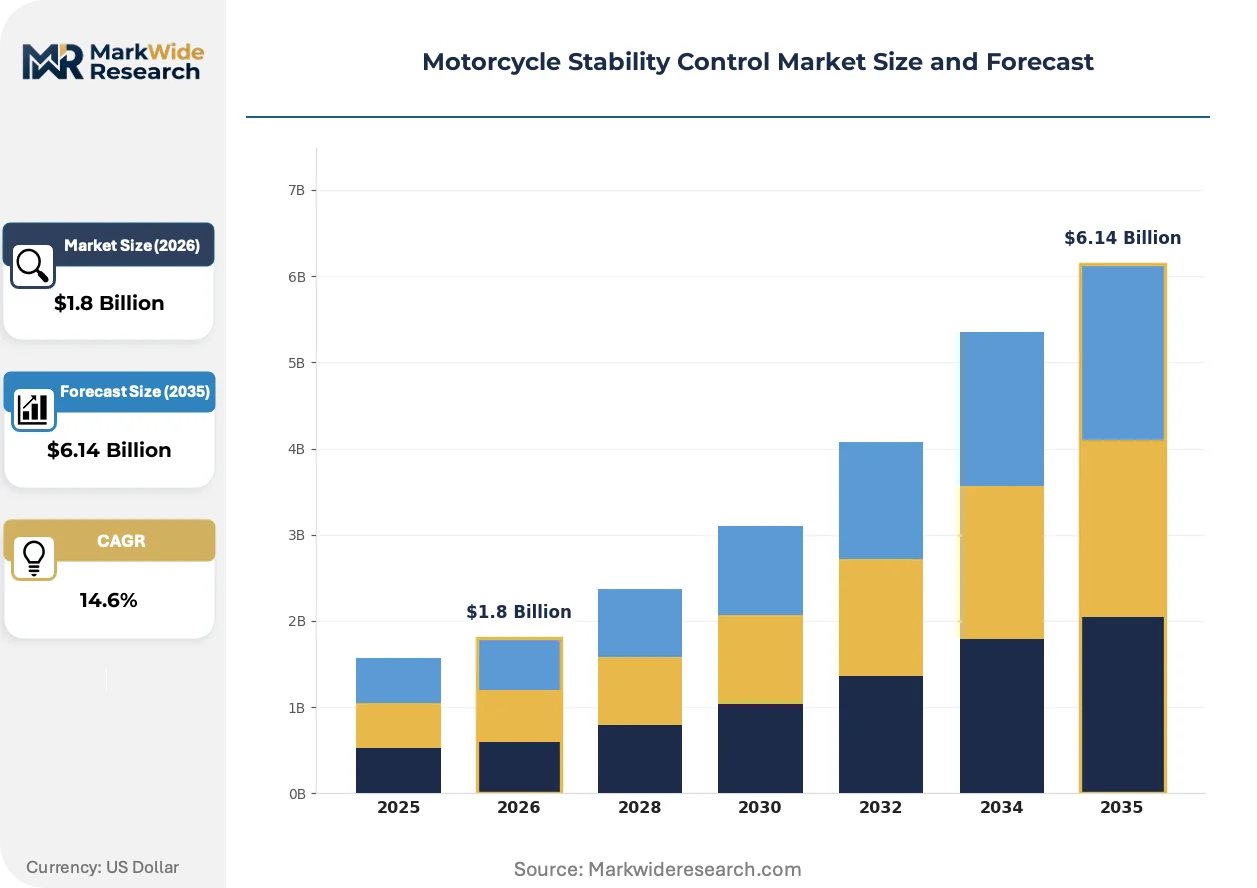
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Anti-lock Braking System, Traction Control System, Electronic Stability Control, Ride-by-Wire End User: Motorcycle Manufacturers, Aftermarket Providers, OEMs, Custom Builders Application: Touring Motorcycles, Sport Motorcycles, Cruiser Motorcycles, Off-road Motorcycles Product Type: Standalone Systems, Integrated Systems, Advanced Driver Assistance Systems, Others |
| Companies Covered | Bosch, Continental, Brembo, BMW Motorrad, Honda, Ducati, Yamaha, ZF Friedrichshafen, KTM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Stability Control Market Evolving Landscape
Algorithmic prediction is replacing reactive intervention in motorcycle stability architectures, with machine learning-based traction models enabling anticipatory throttle and brake modulation before loss-of-control events.
AI-driven predictive stability algorithms are displacing threshold-based intervention logic in premium motorcycle platforms. BMW Motorrad and Ducati are deploying neural network models trained on racetrack telemetry to anticipate rear-wheel slip 50-100 milliseconds before traditional IMU detection. This capability is compressing the competitive window for suppliers lacking machine learning integration roadmaps.
Japan's Ministry of Land, Infrastructure, Transport and Tourism has elevated electronic stability control weighting in its voluntary safety rating scheme, effective for 2025 model year certifications. Domestic OEMs Honda and Yamaha are accelerating cornering ABS standardization across sport-touring lines to secure top-tier ratings. The policy is forcing European and Indian exporters to match Japanese-spec stability functionality for premium segment access.
Fleet procurement by motorcycle rental and ride-hailing operators is reshaping stability system specification priorities. Southeast Asian mobility platforms Grab and Gojek are mandating ABS and optional traction control for contractor vehicle eligibility, shifting aftermarket upgrade demand toward certified retrofit kits. This channel now accounts for substantial volume in Indonesia and Vietnam where personal ownership dominates retail but fleet standardization drives safety feature diffusion.
Motorcycle Stability Control Market Segmentation
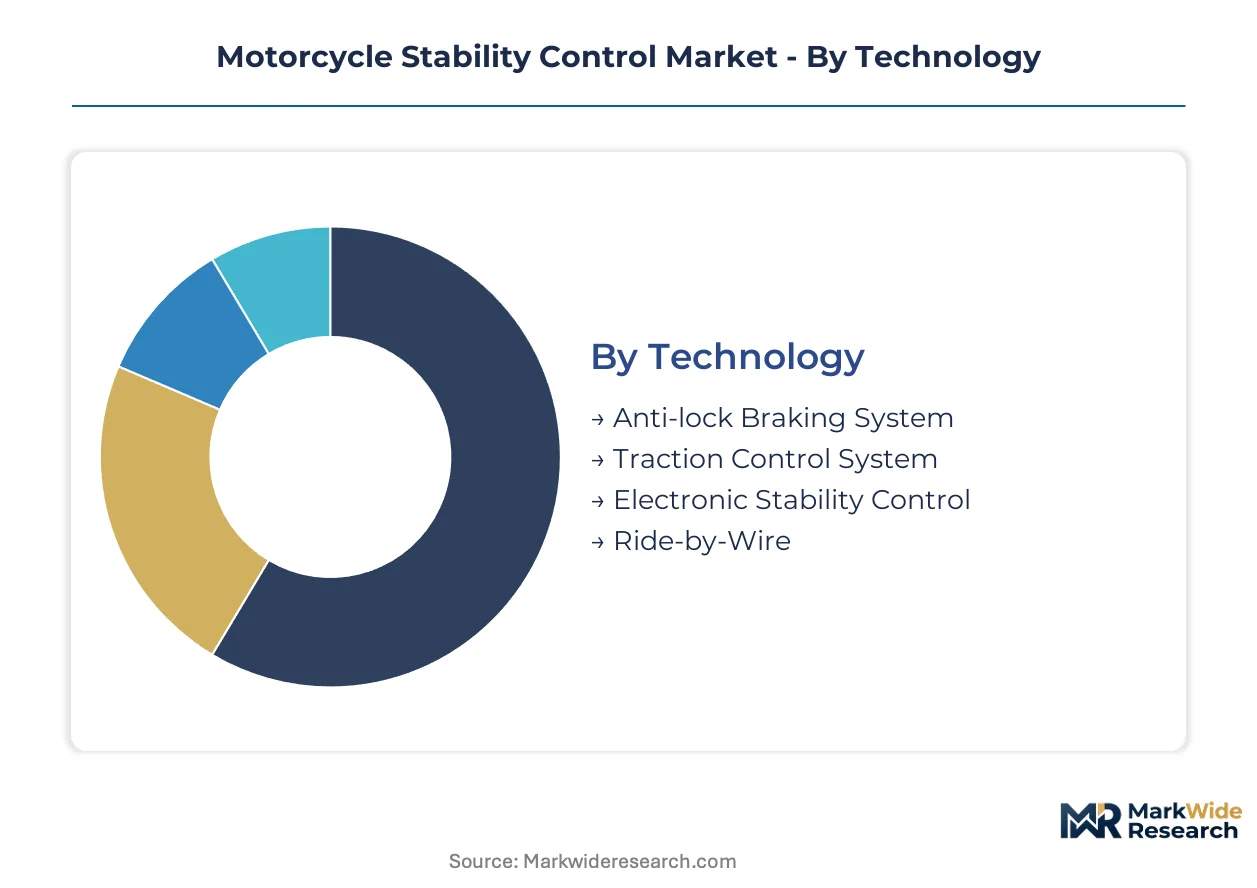
Motorcycle stability control segments align sharply with channel economics. Technology tiers map to OEM procurement cycles, while application segments concentrate in distinct geographic markets with divergent safety mandates and displacement preferences.
Technology:
Anti-lock Braking System modules flow through high-volume OEM channels serving India's 125cc-plus mandate, while Electronic Stability Control concentrates in premium manufacturer direct procurement for European and Japanese sport-touring platforms.
- Anti-lock Braking System:Hydraulic modulation units sampling wheel speed at 100 Hz or higher, integrated with solenoid valve blocks for sub-100-millisecond pressure release. Demand concentrates in India and Southeast Asia where the Ministry of Road Transport mandates fitment on displacement segments above 125cc, compressing supplier margins through compliance-driven volume procurement.
- Electronic Stability Control:Unified ECU architectures combining six-axis inertial measurement with predictive chassis dynamics algorithms. European premium OEMs and Japan's Honda and Yamaha are standardizing this across sport-touring lines to secure top-tier ratings from the Ministry of Land, Infrastructure, Transport and Tourism.
- Traction Control System:Wheel slip mitigation through ignition retard and fuel cut strategies, predominantly specified for high-torque sport motorcycles.
- Ride-by-Wire:Electronic throttle actuation enabling predictive torque management, emerging as a bundled platform enabler for integrated stability architectures.
Anti-lock Braking System dominates installed base through regulatory mandate penetration. Electronic Stability Control is where expansion concentrates as OEMs differentiate premium tiers through unified control architectures.
End User:
Cost tiers separate this category. Motorcycle Manufacturers absorb non-recurring engineering for ASIL-D certification, while Aftermarket Providers compete on retrofit kit affordability without full system redesign.
- Motorcycle Manufacturers:Direct procurement of calibrated IMU-ECU-actuator packages with integrated functional safety validation. Germany's KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism certification requirements drive specification rigidity.
- OEMs:Tier 1 brake system suppliers integrating stability modules into hydraulic architectures, with Continental and Bosch commanding position through proprietary sensor fabrication and deep brake platform integration.
- Aftermarket Providers:Certified retrofit kits for fleet operators and owner upgrades, channeling through Southeast Asian mobility platforms mandating ABS eligibility for contractor vehicles.
- Custom Builders:Low-volume specialist applications requiring bespoke calibration, constrained by ISO 26262 validation cost thresholds.
Motorcycle Manufacturers capture volume concentration. Aftermarket Providers represent the channel gaining share fastest as fleet standardization reshapes specification priorities in Indonesia and Vietnam.
Application:
Volume clusters in commuter displacement bands, while margin concentrates where cornering functionality commands premium positioning.
- Touring Motorcycles:Flagship displacement platforms integrating full stability suites including cornering ABS and adaptive cruise control. European and Japanese OEMs bundle these as standard equipment to justify premium pricing tiers.
- Sport Motorcycles:High-revving platforms demanding millisecond-level intervention precision, with Ducati and BMW Motorrad deploying neural network traction models trained on racetrack telemetry.
- Cruiser Motorcycles:Low-center-of-gravity platforms prioritizing straight-line braking stability over lean-angle modulation, predominantly specified for North American markets.
- Off-road Motorcycles:Specialized calibration profiles allowing deliberate wheel slip for terrain traversal, requiring switchable intervention thresholds.
Touring Motorcycles anchor revenue concentration through bundled system specification. Sport Motorcycles show the steepest expansion trajectory as predictive algorithms displace threshold-based intervention logic.
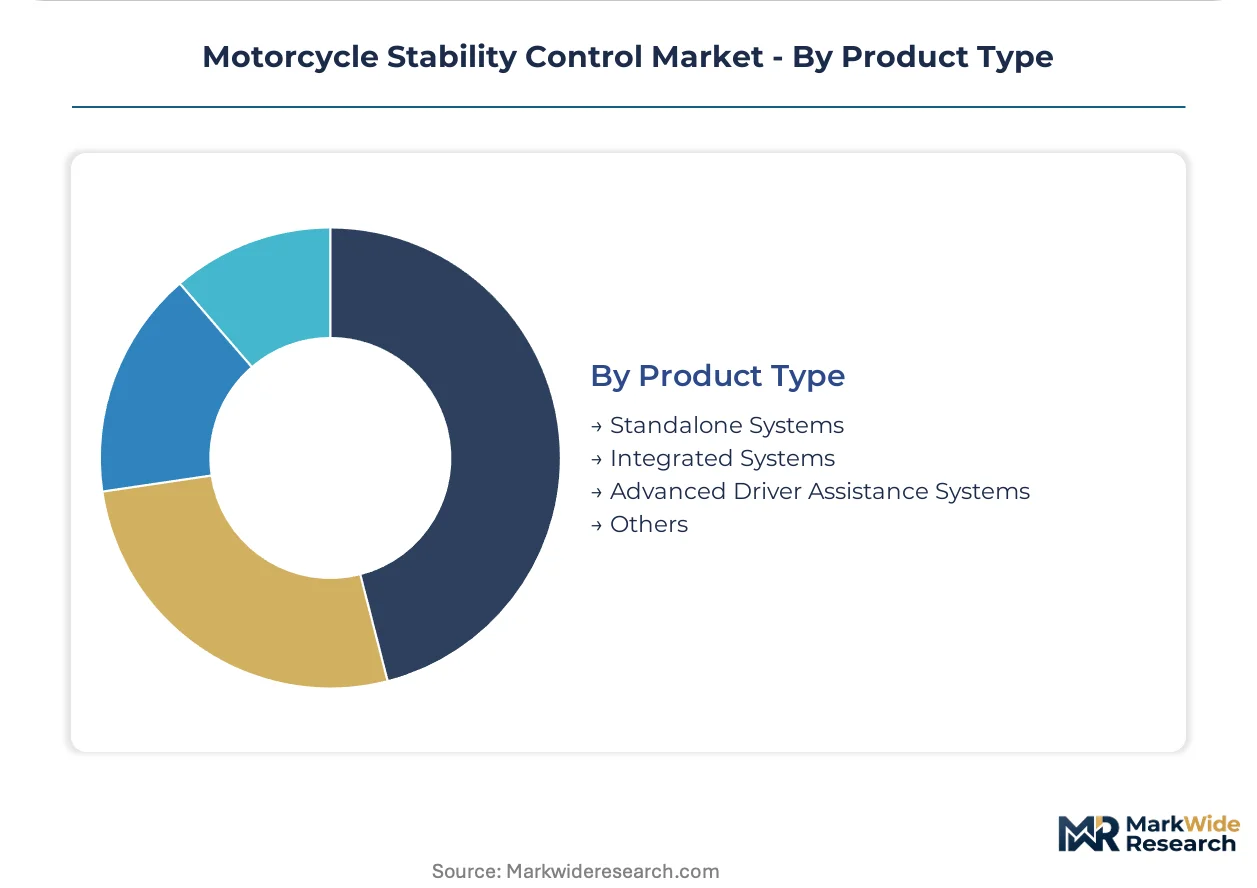
Product Type:
Supply concentration favors integrated architectures, while standalone modules persist where legacy brake platforms resist full redesign.
- Integrated Systems:Consolidated ECU architectures reducing wiring complexity and calibration overhead, specified by premium OEMs seeking manufacturing simplification.
- Standalone Systems:Discrete ABS or traction control modules retrofitting legacy hydraulic platforms, channeling through aftermarket and mid-displacement OEM procurement.
- Advanced Driver Assistance Systems:Emerging radar-camera fusion for adaptive cruise and collision mitigation, nascent in motorcycle applications.
- Others:Specialized calibration tools and diagnostic interfaces supporting dealer network service operations.
Integrated Systems command margin concentration through unified procurement. Standalone Systems persist where retrofit economics outweigh platform redesign investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ministry of Road Transport and Highways anchors the dominant geography through mandatory ABS regulations that reshape procurement patterns across the two-wheeler supply chain. Compliance-driven demand from domestic manufacturers concentrates investments in Tamil Nadu and Karnataka. Regional variation in safety mandates and displacement preferences fragments specification requirements across major production clusters.
Germany
KBA certification requirements for electronic stability systems drive OEM specification rigidity among premium motorcycle manufacturers. The European Commission's Euro 5 safety framework mandates advanced braking modulation that compels sourcing of six-axis inertial measurement units. Manufacturing concentration in Bavaria and Baden-Württemberg hosts advanced R&D facilities where Bosch and Continental maintain brake system integration centers.
Japan
Honda and Yamaha accelerate cornering ABS standardization across sport-touring lines to secure top-tier ratings from the Ministry of Land, Infrastructure, Transport and Tourism. The 2025 model year certification scheme elevates electronic stability control weighting in voluntary safety assessments. Industrial clusters in the Kanto region around Tokyo and the Chubu region around Nagoya concentrate domestic OEM technology roadmaps and supplier partnerships.
India
Domestic manufacturers Bajaj Auto and TVS Motor generate compliance-driven procurement from the Ministry of Road Transport's ABS mandate on two-wheelers above 125cc. Tamil Nadu's Chennai-Bengaluru industrial corridor localizes supply chain investments for IMU and hydraulic actuator production. Karnataka's Bengaluru tech hub attracts embedded software engineering talent for functional safety certification programs.
United States
NHTSA's Federal Motor Vehicle Safety Standards for motorcycle braking performance shape product certification requirements for imported premium models. Harley-Davidson and Indian Motorcycle specification priorities concentrate on cruiser platforms prioritizing straight-line stability over lean-angle modulation. Midwest manufacturing clusters in Wisconsin and Minnesota anchor domestic assembly with limited stability system integration compared to European and Japanese premium tiers.
Brazil
ANVISA and national transport authorities evaluate mandatory ABS timelines that create early-mover positioning opportunities for certification-ready suppliers. São Paulo state's industrial belt concentrates motorcycle assembly from multinational OEMs serving Latin American export markets. Local manufacturers anticipate regulatory alignment with European and Indian safety frameworks to maintain access to developed market supply chains.
Motorcycle Stability Control Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around suppliers commanding proprietary sensor fabrication and deep brake platform integration. The upper tier captures premium procurement through unified ECU architectures that reduce wiring complexity for motorcycle manufacturers. Three strategic archetypes define positioning: integrated system suppliers with captive MEMS capabilities, brake-focused specialists leveraging hydraulic actuator expertise, and OEM-captive technology divisions serving affiliated marques. Competitive moves concentrate on backward integration into inertial sensor production and strategic partnerships for machine learning algorithm development.
Among German-based integrated suppliers, Bosch and Continental exemplify the dominant archetype combining proprietary fabrication with brake system integration, while Brembo anchors the brake-specialist tier through cornering ABS calibration expertise for high-displacement sport motorcycles.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Brembo |
| BMW Motorrad |
| Honda |
| Ducati |
| Yamaha |
| ZF Friedrichshafen |
| KTM |
| Others |
Value Network & Pricing Analysis
Six-month calibration timelines for ISO 26262 ASIL-D certification compress supplier margins while amplifying pricing power for Bosch and Continental's captive MEMS fabrication. This lead-time rigidity forces mid-volume OEMs toward bundled procurement contracts that trade unit cost transparency for guaranteed volume allocation.
Pricing Analysis
Geographic price spreads of 30-40% separate German KBA-certified integrated systems from Indian Ministry of Road Transport compliance-grade ABS modules. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with Electronic Stability Control commanding substantial premiums over standalone ABS. Pricing pressure stems from hydraulic actuator input cost volatility as automotive brake demand competes for solenoid valve supply. Fleet procurement by Grab and Gojek contractors shows highest price sensitivity, while European touring motorcycle OEMs absorb premium positioning with minimal negotiation.
Supply Chain Analysis
Strategic stockpiling of six-axis inertial measurement units dominates supplier inventory strategy given MEMS foundry capacity constraints and 12-16 week wafer fabrication cycles. Manufacturing concentrates in Germany, Japan, and India where Bosch, Continental, and domestic Tier 1s maintain captive sensor production. The supply chain draws from specialized silicon wafers, rare-earth magnet components for solenoid actuators, and high-pressure hydraulic pump castings. Single-source vulnerability for proprietary IMU fabrication creates structural risk. Distribution runs through OEM direct procurement for integrated systems and certified retrofit kit channels for aftermarket fleet standardization in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-displacement segments where 250-400cc commuter motorcycles in Southeast Asia lack standard stability integration, creating niches for cost-optimized IMU-ECU suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into MEMS sensor fabrication and exclusive brake platform partnerships with European OEMs. Threat from machine learning-based predictive stability algorithms displacing threshold-based intervention logic demands accelerated R&D allocation toward neural network traction models. Certification investment in Brazil's ANVISA pre-mandate window anchors long-term Latin American supply relationships. For New Entrants and Emerging Players: Anchor in aftermarket retrofit certification for Indonesia and Vietnam fleet operators where Grab and Gojek contractor eligibility mandates create immediate volume. Mid-displacement 250-400cc platforms in Thailand and Malaysia represent the most penetrable segment given optional stability specification. Go-to-market through mobility platform procurement committees bypasses traditional OEM channel barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because safety mandate expansion across Brazil, Southeast Asia, and potential NHTSA rulemaking creates installed base growth with limited demand elasticity. Acquisition targets should display ISO 26262 functional safety capability and existing cornering ABS calibration expertise. Signal to watch is divergence between India's ABS mandate compliance saturation and Electronic Stability Control penetration in premium displacement segments.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensor Fabrication Expansion | Captive IMU production insulates Bosch and Continental from foundry allocation constraints. |
| Machine Learning Algorithm Partnership | Neural network traction models trained on racetrack telemetry differentiate BMW Motorrad and Ducati platforms. |
| Brazil Regulatory Pre-Certification | ANVISA-ready ABS modules position suppliers for mandatory mandate implementation. |
| Throttle-by-Wire Integration | Ride-by-wire convergence with stability control enables predictive torque management bundles. |
| Fleet Retrofit Certification | Grab and Gojek contractor eligibility requirements channel aftermarket volume through certified kit providers. |
Research Methodology
Cross-validation between primary interviews with motorcycle OEM platform engineers, Tier 1 brake system procurement leads, and embedded software functional safety specialists anchors the qualitative findings. Secondary validation draws from KBA type-approval databases, Ministry of Road Transport and Highways regulatory filings, vehicle production statistics from IHS Markit, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up triangulation across displacement segment volumes and top-down manufacturer revenue attribution reconcile market sizing estimates.
Sensitivity analysis across the projection horizon tests volume assumptions against regulatory mandate delay scenarios and MEMS supply disruption cases. Segmentation dimensions modeled include technology tier, application displacement class, end-user procurement channel, and regional regulatory cluster. CAGRs derive from segment-level volume trajectories weighted by average selling price evolution. Forecast inputs incorporate Euro 5 safety framework implementation pace, India's ABS mandate enforcement rigor, and Japan's Ministry of Land, Infrastructure, Transport and Tourism rating scheme weighting adjustments.
Material uncertainties — regulatory mandate timeline slippage, MEMS foundry capacity allocation shifts, and machine learning algorithm validation failures — sit outside the modeled envelope. Forecasts reflect assumptions about compliance-driven procurement elasticity and premium segment voluntary adoption curves. Revision becomes warranted when Brazil's ANVISA mandate timeline or NHTSA rulemaking activity crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Stolen Vehicle Recovery (SVR) Tracking Service Market