
 Video Event Data Recorder Market | 2026-2036
Video Event Data Recorder Market Size, Share, and Industry Trends Forecast 2026-2036
Video Event Data Recorder Market Outlook
Aftermarket service revenue is reconfiguring profit pools across the Video Event Data Recorder landscape. Lytx Inc. leverages its driver risk management platform to sustain recurring subscription income. Samsara Inc. anchors its position through integrated fleet telematics and video analytics. Geotab Inc. dominates the open-platform ecosystem by enabling third-party application development.
A Video Event Data Recorder captures, stores, and transmits audiovisual footage alongside vehicle telemetry through onboard sensors, GPS modules, and solid-state storage rated for extreme temperature and vibration conditions; its primary purpose is to reconstruct incidents, exonerate drivers, and enable predictive safety interventions. Fixed cameras lead product type deployment in transit buses and rail systems, while mobile cameras represent the fastest-growing category as law enforcement agencies replace legacy dashcam infrastructure. AI analytics technology commands the highest margin pool by converting raw footage into automated incident classification and driver coaching workflows.
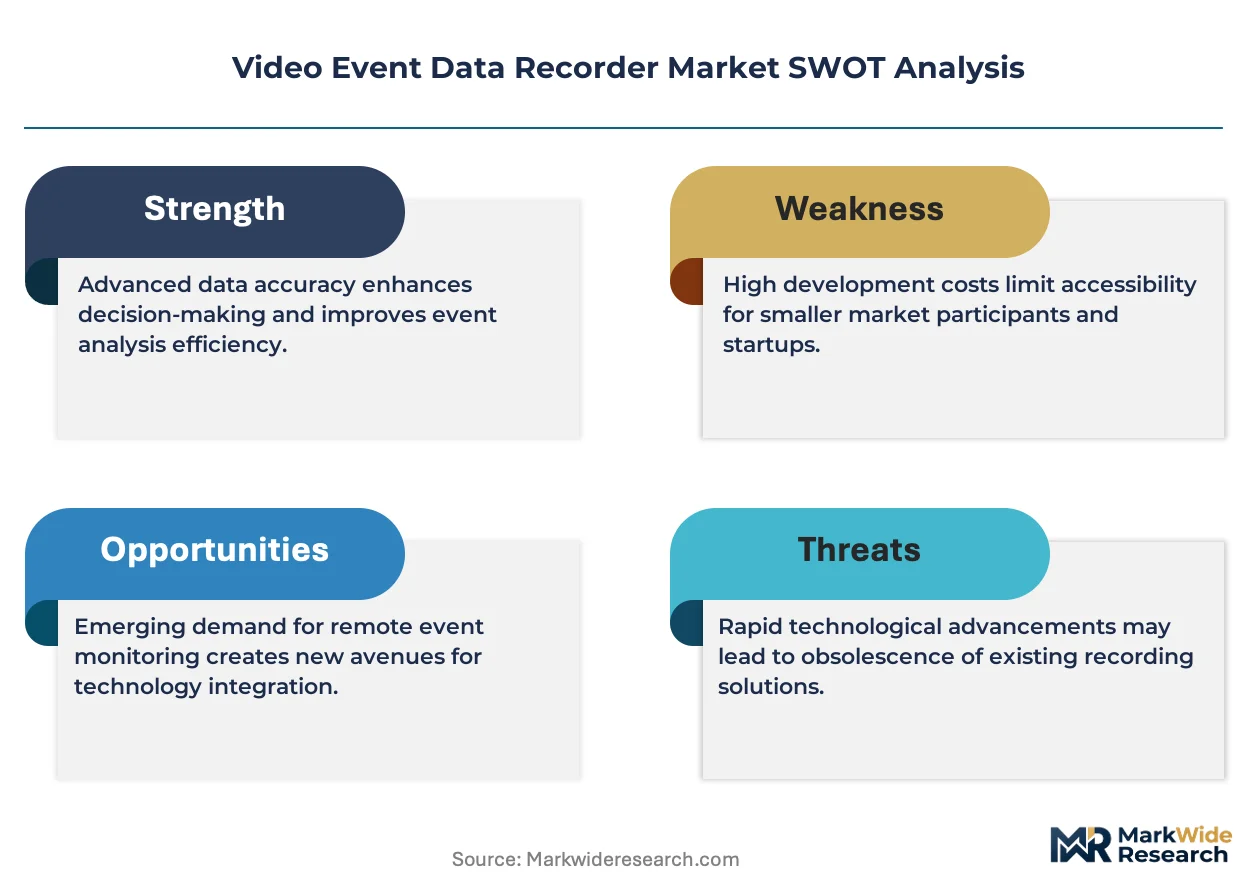
The National Highway Traffic Safety Administration and Federal Motor Carrier Safety Administration mandate event recording capabilities for commercial vehicles, while the EU AI Act imposes algorithmic transparency requirements on automated video analysis systems. These frameworks compel manufacturers to certify data integrity, consent protocols, and cross-border transfer mechanisms before market entry. Stakeholders must monitor evolving liability standards that shift accountability between device makers, fleet operators, and insurance underwriters as real-time intervention capabilities mature.
Market Dynamics
Fleet operators are consolidating vendor relationships around integrated platforms that combine video capture with real-time AI inference and cloud-native fleet management tools, compressing procurement cycles and raising switching costs for incumbent hardware-only suppliers.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated video analysis systems are compelling fleet operators to upgrade legacy recording hardware with certified AI-enabled devices.
- Commercial trucking liability exposure:Insurance underwriters in the United States are demanding continuous video documentation to reduce claims disputes and accelerate settlement timelines.
- Solid-state storage durability:Industrial-grade NAND flash rated for extreme temperature and vibration conditions is eliminating mechanical failure modes that plagued hard-disk-based systems.
Market Restraints
- Semiconductor supply concentration:Advanced image signal processors and AI accelerators depend on foundry capacity concentrated in Taiwan and South Korea, creating procurement vulnerability.
- GDPR consent architecture:Cross-border data transfer mechanisms and driver notification protocols impose engineering overhead that slows product iteration cycles.
- Cellular connectivity cost volatility:Fleet-wide 4G/5G data plans for continuous video upload represent a recurring operational burden that scales linearly with vehicle count.
Strategic Opportunities
- Rail and transit authority modernization:Fixed-camera deployments in urban mass transit systems present underpenetrated demand as agencies replace analog CCTV infrastructure.
- Predictive maintenance convergence:Integration of video event data with telematics and vibration sensors enables unified fleet health monitoring platforms.
- Law enforcement body-wear expansion:Mobile camera adoption by municipal police departments is accelerating as agencies seek synchronized vehicle and officer-mounted recording systems.
Industry Challenges
- Edge AI firmware certification:Validating neural network performance across temperature, vibration, and electromagnetic interference conditions extends product qualification timelines.
- Multi-vehicle synchronization:Timestamp alignment and footage correlation across distributed camera networks in transit fleets demands specialized systems integration expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Event Data Recorder Market |
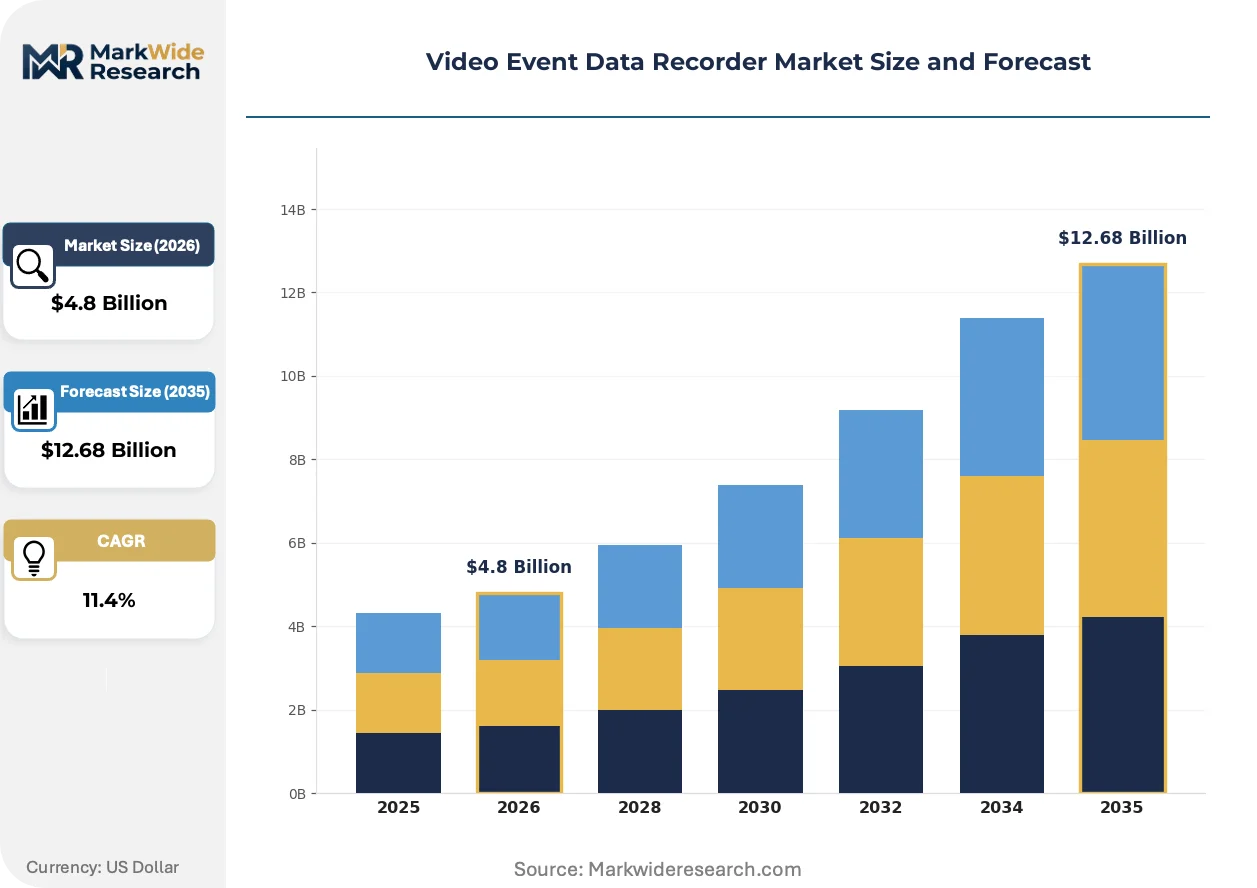
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, Mobile Cameras, Hybrid Systems, Software Solutions End User: Transportation Companies, Fleet Management Firms, Emergency Services, Insurance Providers Technology: Video Streaming, Cloud Storage, AI Analytics, Sensor Integration Application: Road Safety, Accident Investigation, Data Analysis, Real-Time Monitoring |
| Companies Covered | Lytx Inc., Samsara Inc., Verizon Connect Inc., Geotab Inc., Digital Ally Inc., WatchGuard Video, Hikvision, Motorola Solutions, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Event Data Recorder Market Strategic Shifts
Video event data recorder architecture is bifurcating between purpose-built edge inference devices and software-defined platforms that abstract hardware dependencies through containerized analytics pipelines.
On-device neural processing units with dedicated tensor cores are collapsing the latency between incident capture and automated classification, enabling real-time driver coaching without cloud round-trips. Transit operators in Germany are deploying these systems to detect pedestrian proximity violations at bus depots. The compression of inference latency is eliminating the competitive moat of centralized cloud analytics providers.
The EU AI Act's risk-based classification system for biometric identification and emotion recognition is forcing manufacturers to rearchitect feature sets for European deployment. Systems capable of driver fatigue detection must now expose algorithmic decision logic for audit. Commercial vehicle OEMs are responding by partitioning AI capabilities into region-locked firmware modules.
Fleet procurement committees are consolidating video, telematics, and dispatch systems under single-platform contracts that bundle hardware, connectivity, and analytics subscriptions. Channel partners who previously sold discrete dashcam hardware are repositioning as managed service providers. This behavioral shift is most pronounced among mid-sized logistics operators in the United States seeking to reduce vendor management overhead.
Video Event Data Recorder Market Segmentation
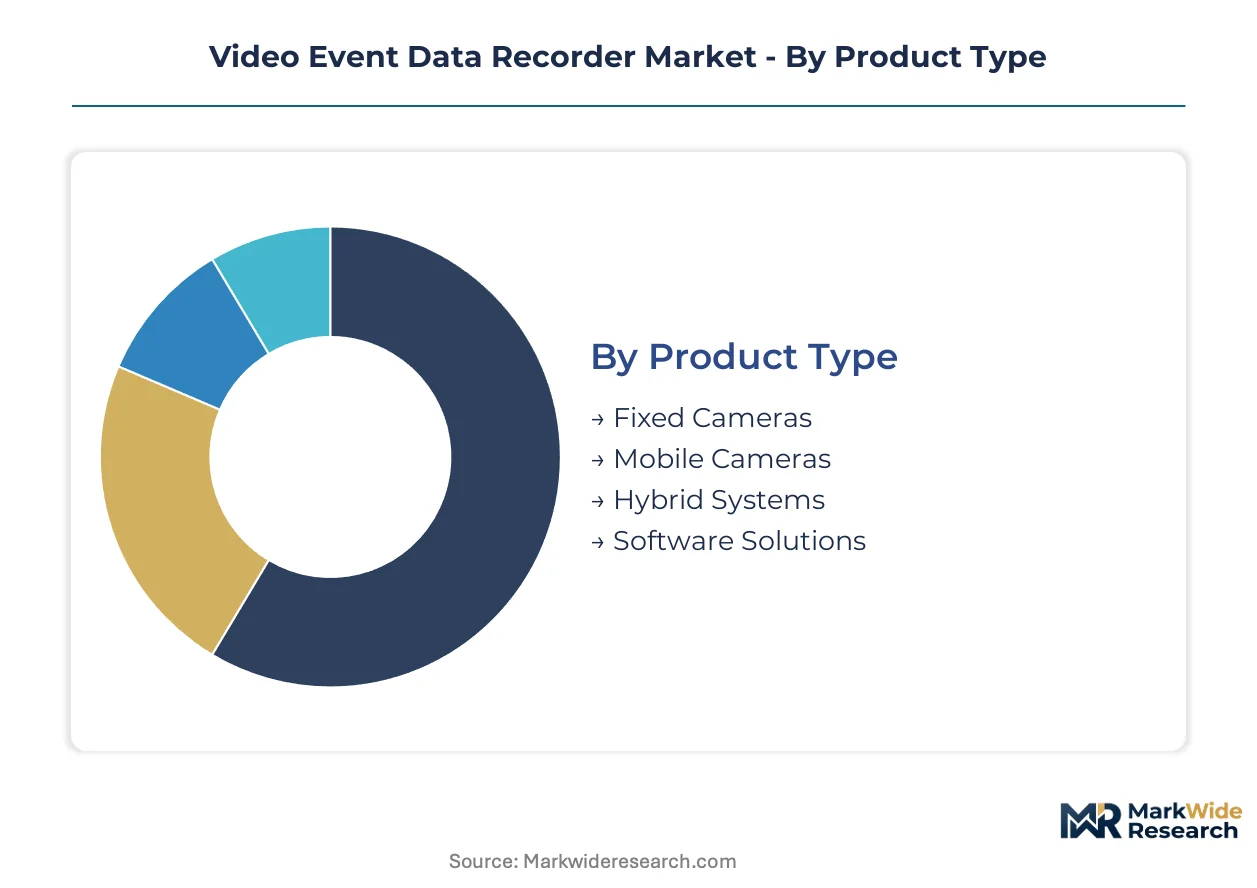
Video event data recorder procurement cycles vary dramatically by segment, with hardware refresh timelines stretching seven to ten years while software subscriptions turn over annually. Understanding these velocity differentials helps vendors align R&D investment with revenue predictability.
Product Type:
Replacement cycles diverge sharply across hardware categories, with solid-state components extending useful life while software-defined systems demand continuous versioning.
- Fixed Cameras:Permanently mounted units in transit buses and rail depots utilize hardened enclosures rated for vibration and temperature extremes. Transit authorities in Germany and the United States concentrate demand as agencies modernize analog CCTV infrastructure under EU AI Act and NHTSA guidelines.
- Mobile Cameras:Portable recording devices for law enforcement vehicles and temporary fleet deployments. Police departments in California, Texas, and Florida are expanding synchronized vehicle-officer recording systems, though procurement volatility follows municipal budget cycles.
- Hybrid Systems:Dual-mode architectures combining fixed mounting with detachable components for flexible deployment scenarios.
- Software Solutions:Containerized analytics pipelines and firmware modules that abstract hardware dependencies.
Fixed cameras dominate installed base across transit infrastructure. Mobile cameras represent where expansion concentrates most steeply.
End User:
Customer concentration patterns reflect liability exposure gradients, with commercial trucking operators facing the steepest insurance pressure while public agencies navigate procurement complexity.
- Fleet Management Firms:Integrated platform operators consolidating video, telematics, and dispatch under single-vendor contracts. Mid-sized logistics operators in the United States are compressing vendor relationships to reduce management overhead.
- Transportation Companies:Commercial trucking and passenger transit operators mandated by FMCSA and EU regulations to maintain continuous recording capabilities. Cross-border data transfer protocols under GDPR impose engineering overhead on European operations.
- Emergency Services:Fire departments and ambulance operators requiring ruggedized recording for incident documentation.
- Insurance Providers:Underwriters demanding video documentation to accelerate claims resolution and reduce dispute volume.
Fleet management firms command the highest contract values. Insurance providers are gaining purchasing influence fastest.
Technology:
Margin structures invert across the technology stack, with hardware commoditizing while inference and storage layers capture expanding value share.
- AI Analytics:On-device neural processing with dedicated tensor cores enabling real-time incident classification without cloud round-trips. German transit operators deploy these systems for pedestrian proximity detection at bus depots.
- Cloud Storage:Fleet-wide data lakes with automated retention policies and chain-of-custody documentation. Cellular connectivity costs scale linearly with vehicle count, creating operational burden for large deployments.
- Video Streaming:Low-latency transmission protocols for live fleet monitoring and emergency response coordination.
- Sensor Integration:Unified telemetry combining video, GPS, accelerometer, and CAN bus data streams.
Cloud storage anchors recurring revenue models. AI analytics is climbing the fastest as a differentiation layer.
Application:
Use case maturity correlates with regulatory enforcement intensity, with accident reconstruction standardized while predictive interventions remain emergent.
- Road Safety:Real-time driver coaching and violation detection workflows. EU AI Act algorithmic transparency requirements force manufacturers to expose decision logic for European deployments.
- Accident Investigation:Post-collision reconstruction combining video telemetry with sensor fusion. FMCSA mandates govern evidence admissibility standards in the United States.
- Data Analysis:Pattern recognition across aggregated fleet footage for risk profiling and premium calculation.
- Real-Time Monitoring:Live operational visibility for dispatch coordination and emergency response.
Accident investigation dominates contractual specifications. Road safety applications are gaining share fastest as predictive capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Fleet operators in the United States prioritize insurance liability reduction through continuous recording, while European deployments emphasize GDPR-compliant consent architectures and algorithmic transparency under the EU AI Act.
United States
Commercial trucking fleets and municipal police departments drive procurement volume. The FMCSA mandates event recording capabilities for commercial vehicles, accelerating hardware refresh cycles. California, Texas, and Florida lead state-level adoption as law enforcement agencies deploy synchronized vehicle-officer recording systems.
Germany
Transit authorities modernize analog CCTV infrastructure in urban bus and rail depots. The EU AI Act imposes strict algorithmic transparency requirements on driver fatigue detection systems. Bavaria and North Rhine-Westphalia concentrate manufacturing and systems integration expertise for European-market devices.
China
Domestic fleet operators integrate video event data with telematics platforms for logistics optimization. MIIT standards govern vehicle data security and cross-border transfer restrictions. The Yangtze River Delta and Pearl River Delta host component manufacturing clusters for solid-state storage and image signal processors.
United Kingdom
Insurance underwriters demand video documentation to accelerate claims resolution and reduce dispute volume. GDPR consent protocols and driver notification requirements shape product design specifications. The Midlands and Southeast England concentrate fleet management firm headquarters and systems integrators.
Japan
Commercial vehicle OEMs embed event recorders as standard equipment to meet METI safety guidelines. JIS standards specify durability ratings for extreme temperature and vibration conditions. The Kanto region around Tokyo anchors domestic manufacturing and R&D for automotive-grade NAND flash components.
Video Event Data Recorder Market Competitive Environment
Capability concentration sits with integrated platform providers; scale advantage sits with specialized hardware fabricators. The market structure bifurcates between subscription-based fleet software operators and component-focused device manufacturers. Three archetypes dominate: cloud-native platform operators, open-ecosystem enablers, and purpose-built hardware specialists. Consolidation pressures favor M&A activity around AI analytics capabilities, while geographic expansion targets European compliance-certified product lines.
Within the integrated platform tier, Lytx Inc. and Samsara Inc. exemplify the shift toward recurring subscription revenue models. Geotab Inc. occupies a distinctive position as an open-platform ecosystem anchor. These three companies represent the strategic pivot away from discrete hardware sales toward bundled hardware-connectivity-analytics contracts that compress procurement cycles and elevate switching costs for fleet operators.
| Leading Market Players |
|---|
| Lytx Inc. |
| Samsara Inc. |
| Verizon Connect Inc. |
| Geotab Inc. |
| Digital Ally Inc. |
| WatchGuard Video |
| Hikvision |
| Motorola Solutions |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwan's advanced foundry nodes is tightening procurement timelines for AI accelerators and image signal processors, compressing supplier bargaining power while elevating hardware premiums for fleet operators seeking certified edge inference devices.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one fleet operators and integrated platform providers, locking in three-to-five-year subscription bundles that combine hardware, connectivity, and analytics. Three-tier pricing structure across premium, standard, and economy levels separates FMCSA-certified systems with full AI telemetry from basic event recording hardware. Price differentiation hinges on GDPR compliance architecture and EU AI Act certification grade. Cost compression in entry-tier hardware is intensifying because Chinese component suppliers are expanding NAND flash fabrication capacity. Mid-sized logistics operators in the United States exhibit highest price sensitivity, while German transit authorities prioritize algorithmic transparency over unit cost.
Supply Chain Analysis
Upstream feedstock for solid-state storage controllers draws from Taiwan, South Korea, and Japan, where advanced NAND fabrication and image signal processor design concentrates. Key component dependencies include industrial-grade NAND flash, neural processing units with tensor cores, and hardened GPS modules rated for vibration extremes. Single-source vulnerability around TSMC's 7nm and 5nm capacity creates procurement risk for on-device AI accelerators. Distribution runs through direct OEM partnerships for commercial vehicle manufacturers and specialized fleet management integrators serving municipal transit authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified firmware engineers capable of validating neural network performance across electromagnetic interference and temperature extremes remain scarce relative to platform deployment timelines, creating a bottleneck that favors incumbents with established qualification workflows.
For Market Incumbents: Harden EU AI Act compliance capabilities by partitioning AI features into region-locked firmware modules that expose algorithmic decision logic for audit. Expand backward integration into solid-state storage controller design to reduce exposure to Taiwan foundry concentration. Channel control through exclusive partnerships with commercial vehicle OEMs defends against cloud-native entrants seeking to displace hardware-centric relationships. For New Entrants and Emerging Players: Build out white-label analytics pipelines for mid-sized fleet operators in the United States seeking to consolidate vendor relationships under single-platform contracts. Rail and transit authority modernization in Germany presents the most penetrable geography, as agencies replace analog CCTV infrastructure with AI-enabled fixed-camera systems. A managed service provider positioning that bundles installation, connectivity, and cloud storage subscriptions bypasses incumbent hardware lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward integrated platform operators with demonstrated recurring revenue traction and EU AI Act certification pathways already validated. Long-term viability across the projection horizon rests on AI analytics differentiation rather than hardware fabrication scale. The signal to monitor is FMCSA mandate expansion to smaller commercial vehicle classes, which would accelerate hardware refresh cycles and elevate platform switching costs.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Algorithmic transparency requirements in Germany and France mandate audit-ready firmware architectures. |
| Backward Integration into NAND Controllers | Captive supply of industrial-grade storage components reduces Taiwan foundry dependency for edge devices. |
| Platform Integration with Fleet Telematics | Unified video-telemetry-dispatch contracts compress procurement cycles for mid-sized US logistics operators. |
| Strategic Partnership with Transit Authorities | Fixed-camera deployments in German urban depots replace aging CCTV under EU modernization grants. |
| Acquisition of Edge AI Specialist Firm | On-device neural processing talent accelerates real-time incident classification without cloud latency. |
Study Parameters
Desk research of FMCSA regulatory filings, EU AI Act implementation guidance, and commercial vehicle OEM technical specifications preceded structured interviews with fleet management procurement directors, transit authority operations chiefs, and insurance underwriting risk officers. Primary fieldwork with systems integrators in Germany and the United States validated hardware refresh timelines and subscription pricing trajectories. Secondary sources included NHTSA safety databases, GDPR enforcement case records, and NAND flash supply chain disclosures. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, and technology segments.
Assumptions around EU AI Act enforcement intensity and FMCSA mandate expansion were held fixed at baseline levels, while cellular connectivity cost trajectories and Taiwan foundry utilization were varied across sensitivity bands. The analytical framework modeled volume and value outputs across hardware category, deployment scale, and regional regulatory cluster. CAGRs were derived from regression analysis of historical procurement cycles and projected replacement rates. Forecast inputs incorporated fleet operator consolidation patterns and AI analytics adoption curves by vehicle class.
Stress conditions across semiconductor supply availability, GDPR consent enforcement, and commercial trucking liability exposure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology substitution rates. Cross-checking against NHTSA crash investigation database trends and EU transport agency procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Brake Override System Market