
 Automotive Brake Actuation Systems Market | 2026-2036
Automotive Brake Actuation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Actuation Systems Market Analysis
Software-defined brake calibration is restructuring how automotive suppliers monetize actuation platforms. Robert Bosch GmbH leverages embedded diagnostic subscriptions to extend recurring revenue beyond hardware sales. ZF Friedrichshafen AG anchors its position through R&D intensity in integrated brake-by-wire architectures. Continental AG competes across the full stack from hydraulic valves to autonomous-ready electro-hydraulic modules.
Automotive brake actuation systems translate driver or autonomous inputs into hydraulic, pneumatic, or electric force at wheel-end calipers, operating at pressures typically exceeding 150 bar in commercial applications to achieve deceleration rates mandated by federal stopping-distance standards. Their primary purpose is ensuring repeatable, modulated braking performance across vehicle classes while supporting advanced driver assistance functions. Electric actuation is outpacing hydraulic growth as battery-electric platforms eliminate engine-driven vacuum assist, while electro-hydraulic configurations retain dominance in heavy-duty segments where pneumatic backup remains essential. Anti-lock Braking System technology constitutes the mature revenue base, whereas regenerative braking integration represents the fastest-expanding margin pool as OEMs seek to recapture kinetic energy.
NHTSA's Federal Motor Vehicle Safety Standards govern minimum stopping performance and ABS requirements for vehicles sold in the United States, while the EPA's vehicle emissions framework indirectly shapes actuation design through weight-reduction mandates that favor compact electric architectures. The EU's General Safety Regulation mandates advanced emergency braking and intelligent speed assistance, compelling Tier-1 suppliers to redesign actuation platforms for sensor fusion compatibility. Stakeholders must decide whether to develop proprietary brake-by-wire protocols or align with emerging ISO 26262 functional safety standards that will determine supplier qualification for next-generation autonomous platforms.
Market Dynamics
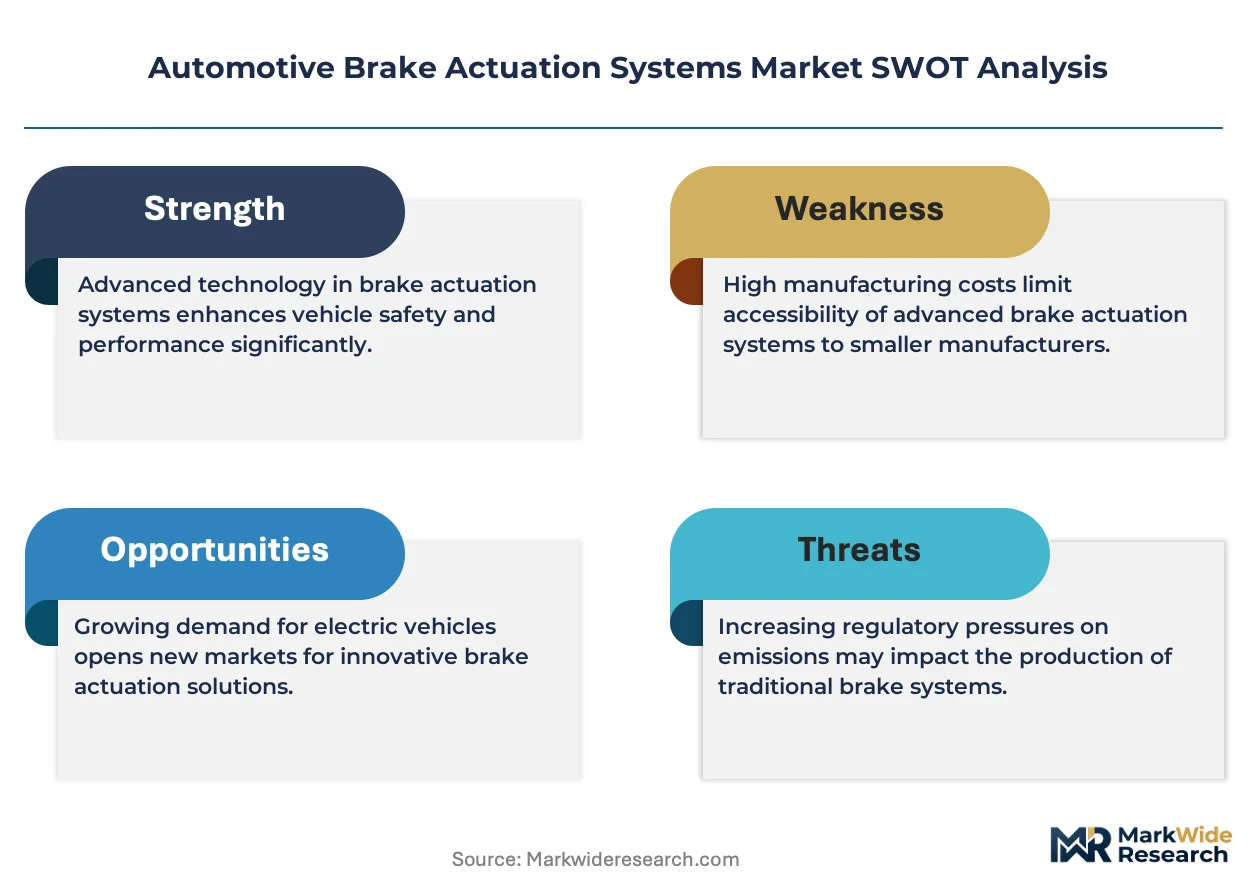
Brake-by-wire architectures are compressing the traditional hydraulic supply chain, forcing Tier-1 suppliers to recalibrate around silicon content and embedded software validation cycles rather than casting and machining economies.
Growth Catalysts
- EU General Safety Regulation:Mandates for advanced emergency braking and intelligent speed assistance compel OEMs to procure sensor-fusion-ready actuation modules, expanding addressable content per vehicle.
- Battery-electric platforms:Elimination of engine-driven vacuum assist creates captive demand for electric brake boosters and integrated electro-hydraulic control units across passenger and commercial segments.
- Stuttgart-Wolfsburg corridor:Concentrated German OEM engineering centers accelerate validation cycles for integrated brake-by-wire systems, compressing supplier qualification timelines.
Market Restraints
- Rare earth magnet pricing:Neodymium and dysprosium volatility in electric motor supply chains elevates input cost uncertainty for permanent-magnet-based brake actuators.
- Semiconductor foundry concentration:Taiwan and South Korea dominance in automotive-grade microcontroller supply creates single-source vulnerability for brake control modules.
- Functional safety certification:ISO 26262 ASIL-D compliance timelines extend 18-24 months, gating supplier entry and freezing incumbent advantage.
Strategic Opportunities
- India commercial vehicle fleet:Underpenetrated air brake automation and pending Bharat Stage VI Phase 2 enforcement create whitespace for pneumatic-electro hybrid actuation platforms.
- Software-defined vehicle architectures:Over-the-air brake calibration updates enable recurring revenue streams and remote diagnostic monetization beyond hardware shipment.
- Regenerative-pneumatic integration:Convergence of kinetic energy recovery with compressed air systems in heavy-duty segments opens margin expansion in long-haul trucking applications.
Industry Challenges
- Embedded systems talent scarcity:Shortage of functional safety engineers with ISO 26262 and AUTOSAR expertise constrains R&D velocity at mid-tier suppliers.
- Legacy fleet interoperability:Backward compatibility requirements for SAE J1939 and ISO 11992 protocols complicate brake-by-wire rollout in mixed-age commercial vehicle parc.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Actuation Systems Market |
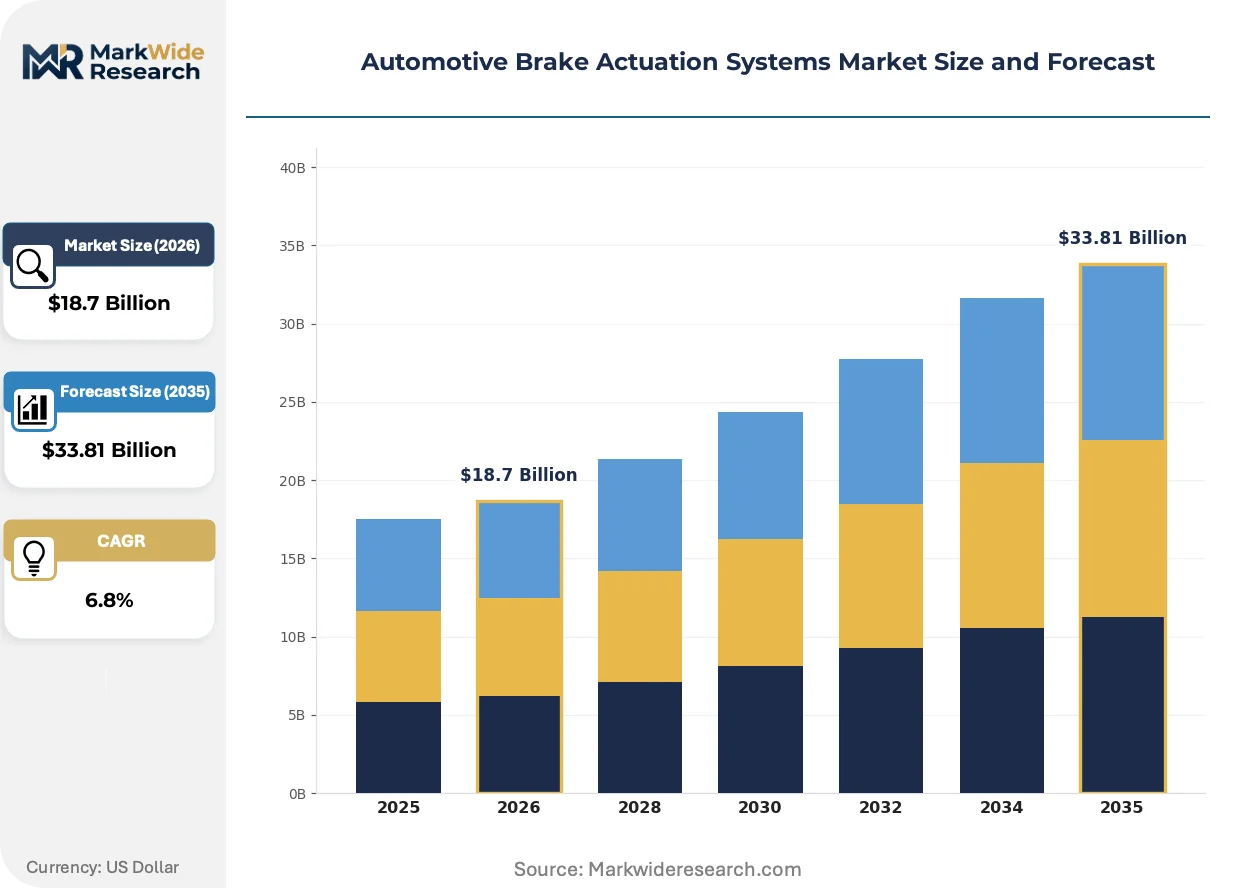
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Electric, Electro-Hydraulic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Anti-lock Braking System, Electronic Stability Control, Automatic Braking, Regenerative Braking Installation Type: New Installation, Retrofit, Modular, Integrated |
| Companies Covered | Continental AG, ZF Friedrichshafen AG, Robert Bosch GmbH, Knorr-Bremse AG, AISIN Corporation, MICO, Inc., ADVICS CO., LTD., Akebono Brake Industry Co., Ltd., Hitachi Astemo Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Actuation Systems Market Emerging Trajectories
Actuation platforms are bifurcating between fully electric architectures for passenger battery-electric vehicles and electro-pneumatic hybrids for commercial duty cycles, with software integration becoming the primary differentiation axis.
Electro-hydraulic brake boosters are electrifying vacuum-independent actuation for electric vehicles. Passenger car OEMs are adopting integrated motor-pump units at accelerating pace. This transition is electrifying the supplier base, compressing margins on legacy master cylinder and vacuum booster portfolios while expanding silicon and firmware addressable markets.
NHTSA Federal Motor Vehicle Safety Standard 135 governs stopping distance and antilock performance for light vehicles, with proposed updates incorporating automatic emergency braking test protocols. The rulemaking is forcing recalibration of hydraulic control unit response times and sensor latency budgets. Heavy-duty segments face parallel pressure from pending NHTSA heavy vehicle AEB mandates, accelerating electro-pneumatic retrofit demand.
Fleet operators are consolidating brake system procurement around total cost of ownership metrics rather than upfront component pricing. Large commercial vehicle lessors now specify predictive maintenance clauses and guaranteed uptime service agreements, displacing transactional parts purchasing. This behavioral shift is most pronounced in North American long-haul trucking, where telematics-enabled brake wear monitoring supports outcome-based supplier contracts.
Automotive Brake Actuation Systems Market Segmentation
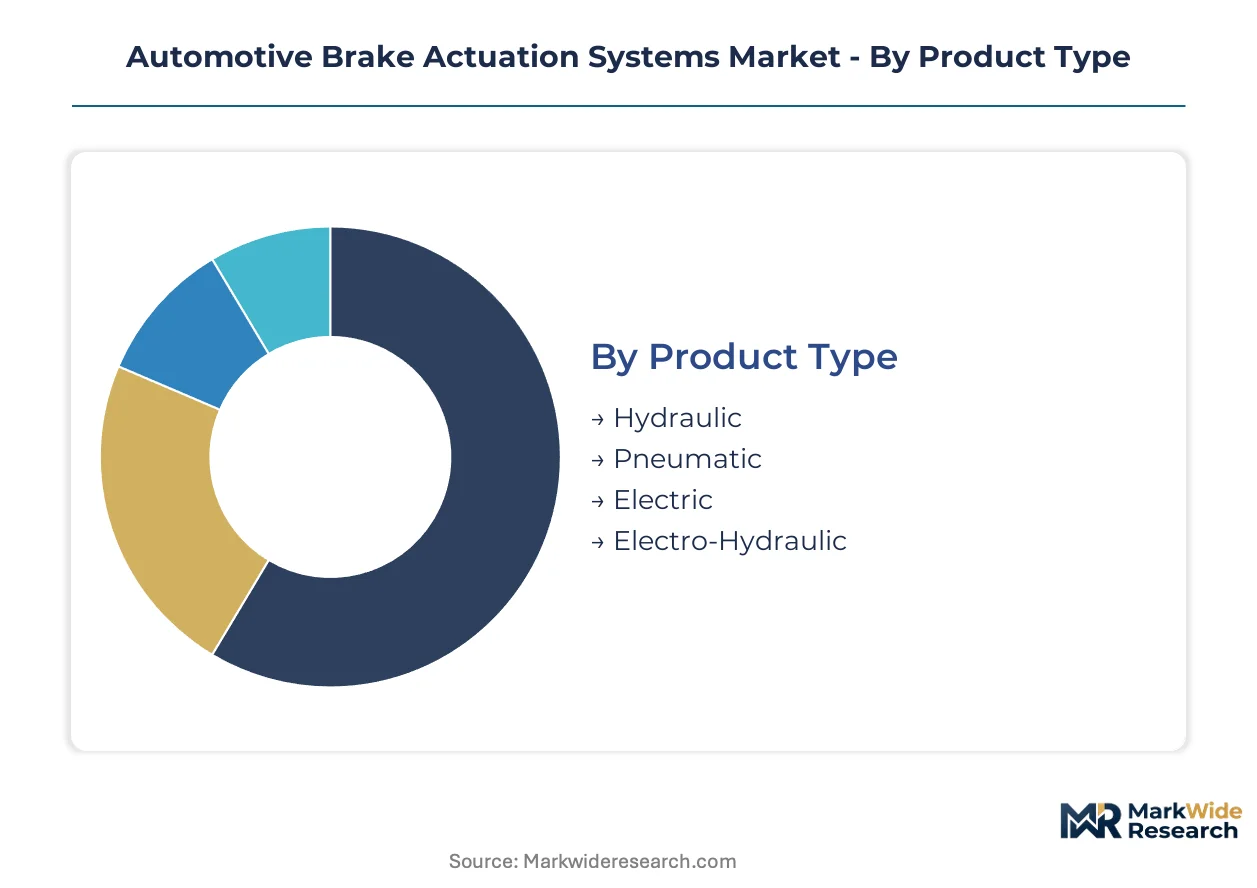
Brake actuation systems fragment across four critical dimensions: propulsion mechanism, supply chain position, control intelligence, and deployment architecture. Each dimension reveals distinct margin profiles and supplier qualification barriers that determine competitive positioning.
Product Type:
Volume production concentrates in mature hydraulic architectures, while premium value migrates toward electric and electro-hybrid configurations.
- Hydraulic:Conventional fluid-based systems utilizing master cylinders and vacuum boosters dominate legacy passenger and light commercial fleets. Demand concentrates in North American and Southeast Asian OEM supply chains where cost sensitivity preserves incumbent technology. NHTSA Federal Motor Vehicle Safety Standard 135 stopping-distance requirements lock in proven hydraulic architectures for high-volume nameplates.
- Electric:Motor-driven actuation eliminates vacuum dependency, enabling integration with battery-electric platforms. Stuttgart engineering centers validate these systems for German OEM premium nameplates where regenerative blending complexity justifies higher system cost. The technology is displacing vacuum boosters fastest in European battery-electric vehicle launches.
- Pneumatic:Compressed-air systems serve heavy-duty commercial applications requiring sustained braking energy. Long-haul trucking fleets across the US Interstate corridor specify pneumatic actuation for trailer compatibility and maintenance standardization.
- Electro-Hydraulic:Hybrid architectures combine electric motor control with hydraulic force multiplication. Commercial vehicle OEMs adopt these for autonomous-ready platforms requiring precise modulation independent of driver pedal input.
Mature deployment sits with Hydraulic systems. Newer deployment is concentrated in Electric configurations.
End User:
Customer type determines contract structure, with OEMs demanding system integration liability and aftermarket providers seeking plug-compatible replacement modules.
- OEMs:Original equipment manufacturers specify complete actuation platforms with embedded software and sensor fusion interfaces. German and Japanese passenger car OEMs now mandate brake-by-wire compatibility for next-generation vehicle architectures.
- Aftermarket Providers:Independent distributors and service chains procure replacement calipers, boosters, and control modules. North American commercial vehicle aftermarket channels show fastest expansion for remanufactured electro-pneumatic units.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source pre-validated actuation subsystems. Indian commercial vehicle assemblers represent the steepest expansion trajectory for air brake automation.
- Tier-1 Suppliers:Integrated module producers supply complete brake control systems to multiple OEMs. Bosch and Continental anchor this segment through captive manufacturing in Germany's automotive corridor.
Contract concentration favors OEMs. Margin expansion concentrates in Tier-1 supplier direct relationships.
Technology:
Functional safety certification tiers separate commodity anti-lock modules from autonomous-ready automatic braking platforms.
- Anti-lock Braking System:Wheel-speed-modulated pressure control prevents lockup during emergency stops. This mature technology constitutes the revenue base for hydraulic valve and pump suppliers serving mass-market nameplates.
- Electronic Stability Control:Yaw-rate and lateral-acceleration-based intervention corrects vehicle trajectory. ESC module demand climbs fastest in Indian and Brazilian passenger vehicle regulatory compliance cycles.
- Automatic Braking:Sensor-fused autonomous emergency braking executes stops without driver intervention. EU General Safety Regulation mandates are accelerating OEM procurement of these platforms.
- Regenerative Braking:Kinetic energy recovery through electric motor reversal maximizes battery-electric range. This technology captures the fastest margin expansion as OEMs prioritize efficiency certification.
Regulatory mandates drive Automatic Braking adoption. Efficiency optimization concentrates Regenerative Braking deployment in premium battery-electric nameplates.
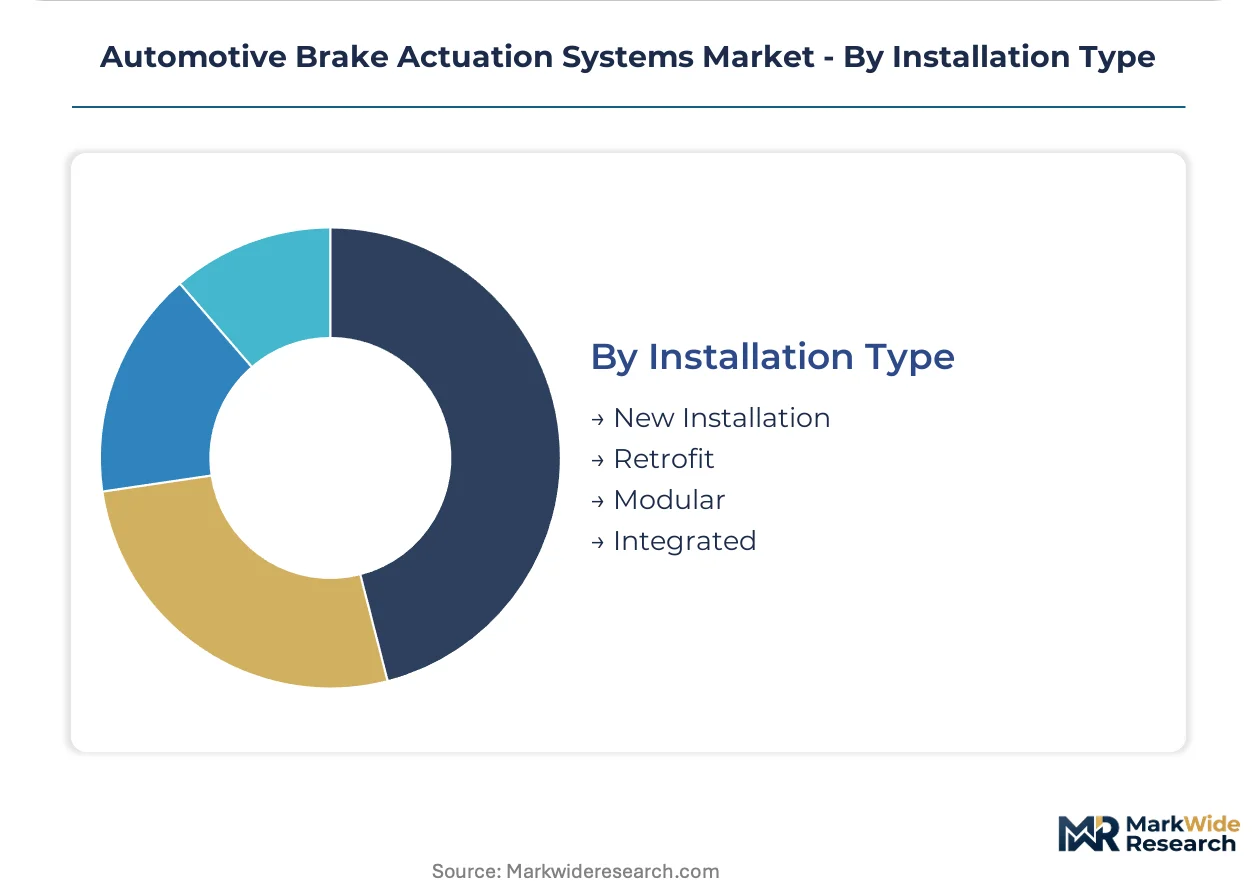
Installation Type:
Integration depth determines supplier engineering responsibility, with modular architectures enabling tier-1 subsystem specialization.
- New Installation:Factory-original actuation systems specified at vehicle program launch. German OEM engineering centers concentrate validation resources here for brake-by-wire integration.
- Retrofit:Aftermarket replacement of legacy systems with updated architectures. US commercial vehicle fleets drive demand for electro-pneumatic retrofits pending NHTSA heavy vehicle automatic emergency braking mandates.
- Modular:Self-contained actuation subsystems integrating controller, actuator, and power electronics in standardized packages. Tier-1 suppliers favor this architecture for multi-OEM supply efficiency.
- Integrated:Vehicle-architecture-embedded actuation with domain controller consolidation. Premium battery-electric platforms specify these for software-defined vehicle compatibility.
Volume production favors Modular packaging. Technology leadership concentrates in Integrated architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of automotive brake actuation systems concentrates in Germany's manufacturing corridor, while consumption spreads across regulatory-driven markets in North America, Europe, and Asia-Pacific. Supply chains span multiple continents with component sourcing and final assembly often separated by thousands of kilometers.
Germany
Stuttgart and Wolfsburg engineering centers validate integrated brake-by-wire systems for premium OEM nameplates. ECE R131 mandates for advanced emergency braking accelerate procurement of sensor-fusion-ready modules. The Baden-Württemberg cluster hosts captive manufacturing by Robert Bosch GmbH and ZF Friedrichshafen AG.
United States
NHTSA Federal Motor Vehicle Safety Standard 135 governs stopping-distance requirements for light vehicles, locking in hydraulic architectures for high-volume nameplates. Pending heavy vehicle automatic emergency braking mandates drive electro-pneumatic retrofit demand. Michigan-based engineering centers concentrate validation resources for brake control unit response times.
China
Battery-electric platform proliferation eliminates engine-driven vacuum assist, creating captive demand for electric brake boosters. MIIT vehicle emissions frameworks indirectly shape actuation design through weight-reduction mandates. Yangtze River Delta manufacturing bases supply both domestic OEMs and export markets.
Japan
METI industrial policy supports autonomous-ready brake-by-wire development through targeted R&D subsidies. JIS standards govern component interoperability for domestic vehicle platforms. Kanto region engineering centers specialize in electronic stability control module production for Asian export markets.
India
Commercial vehicle fleet expansion drives underpenetrated air brake automation demand. Bharat Stage VI Phase 2 enforcement creates whitespace for pneumatic-electro hybrid actuation platforms. Maharashtra and Gujarat assembly operations source pre-validated subsystems from Tier-1 suppliers.
Automotive Brake Actuation Systems Market Vendor Landscape
Top-tier vendors anchor integrated system supply, while mid-tier specialists compete on modular component cost. The vendor base spans German engineering-intensive conglomerates, Japanese precision manufacturers, and emerging Asian fabricators. Two strategic archetypes dominate: silicon-forward brake-by-wire platform developers and legacy hydraulic specialists defending machining economies. Competitive moves center on functional safety certification acceleration and embedded software talent acquisition.
Within the German engineering-intensive tier, Continental AG, ZF Friedrichshafen AG, and Robert Bosch GmbH exemplify the integrated module producer archetype. These Stuttgart-based and Friedrichshafen-headquartered entities occupy positions spanning hydraulic valves to autonomous-ready electro-hydraulic architectures. Their geographic concentration in the automotive corridor reflects proximity to OEM engineering centers and compressed supplier qualification timelines.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Knorr-Bremse AG |
| AISIN Corporation |
| MICO, Inc. |
| ADVICS CO., LTD. |
| Akebono Brake Industry Co., Ltd. |
| Hitachi Astemo Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive integration into permanent-magnet motor production anchors supplier pricing power against rare earth volatility, while outsourced semiconductor sourcing exposes brake control module margins to foundry concentration risk in Taiwan and South Korea. Tier-1 suppliers with in-house magnet processing command premium positioning for electric brake boosters.
Pricing Analysis
Cost-down pressure on hydraulic valve suppliers accelerates because OEMs consolidate procurement around brake-by-wire platforms with embedded software content. Three-tier pricing structure across premium ASIL-D certified, standard ISO 26262 compliant, and economy non-certified levels separates qualification tiers. Pricing pressure stems from semiconductor input cost pass-through constraints. Aftermarket remanufacturers exhibit highest price sensitivity; German OEM direct Tier-1 relationships show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for automotive-grade microcontrollers feeding brake control modules. Neodymium and dysprosium for electric motor actuators draw from Chinese processing dominance; hydraulic castings rest on German and Mexican machining capacity. Tariff exposure on rare earth derivatives threatens margin stability. Distribution runs through Stuttgart-Wolfsburg corridor engineering centers to global OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 26262 ASIL-D certification capacity constraints prop pricing premiums for qualified suppliers, creating supply-constrained vendor selection dynamics across the analysis window.
For Market Incumbents: Acquire embedded software validation capabilities to defend against silicon-forward entrants displacing hydraulic machining economies. Deepen backward integration into rare earth magnet processing to neutralize input cost volatility. Accelerate AUTOSAR talent acquisition before functional safety engineer scarcity freezes R&D velocity. For New Entrants and Emerging Players: Capture Indian commercial vehicle air brake automation whitespace before Bharat Stage VI Phase 2 enforcement consolidates incumbent positions. Target Maharashtra and Gujarat assembly operations with pre-validated pneumatic-electro hybrid subsystems. Lead with outcome-based service contracts displacing transactional parts purchasing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by German engineering-intensive conglomerates seeking brake-by-wire platform completeness. Five-to-ten year viability favors suppliers with ASIL-D certification and captive magnet processing. Watch NHTSA heavy vehicle AEB mandate timing as fleet retrofit demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Reduces OEM qualification timelines for sensor-fusion-ready actuation modules. |
| Rare Earth Magnet Supply Agreement | Secures neodymium pricing stability for electric brake booster motor production. |
| Software-Defined Vehicle Investment | Enables over-the-air brake calibration recurring revenue beyond hardware shipment. |
| Geographic Manufacturing Footprint Expansion | Positions assembly capacity near Yangtze River Delta battery-electric platforms. |
| Functional Safety Certification Acceleration | Compresses ISO 26262 ASIL-D timelines to unlock autonomous-ready supplier qualification. |
Methodological Framework
Multi-period observation of vehicle platform electrification rates and regulatory mandate implementation anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and functional safety certification auditors. Secondary validation drew from NHTSA rulemaking dockets, EU General Safety Regulation implementation guidance, vehicle production databases, and SEC filings of listed automotive suppliers. Bottom-up segment sizing triangulated against top-down OEM content-per-vehicle estimates.
Segment-weighting across propulsion mechanism, control intelligence tier, and regional production cluster shaped the analytical framework across the projection horizon. Modeled dimensions spanned hydraulic, electric, pneumatic, and electro-hydraulic architectures; ABS, ESC, automatic braking, and regenerative technologies; and OEM, aftermarket, and assembler end-user channels. CAGRs derived from vehicle production forecasts and technology penetration curves, with brake-by-wire adoption rates and rare earth price trajectories as key sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization and autonomous vehicle deployment delays. Forecasts reflect documented assumptions on regulatory enforcement timing and OEM platform consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Middle East and Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Safety Restraint Systems Market
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
Automatic High Beam Control Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market